
 Thermal Pallet Covers Market | 2026-2036
Thermal Pallet Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Pallet Covers Market Outlook
Pharmaceutical shippers is collapsing the historical dominance of food distributors as the primary buyer archetype for thermal pallet covers. Cold Chain Technologies leverages its specialized engineering focus to sustain premium positioning in validated pharmaceutical lanes. Pelican BioThermal anchors its competitive stance through deep integration with temperature-assurance protocols for cell and gene therapies. 3M Company differentiates via material science leadership in reflective barrier films that extend thermal protection duration.
Thermal pallet covers are engineered protective enclosures constructed from multi-layer reflective and insulating materials—typically aluminum-laminated substrates, non-woven polypropylene, or closed-cell foam composites—designed to moderate radiative heat transfer and convective exchange around palletized cargo. These systems function as passive thermal management devices, maintaining target temperature bands for 48–120 hours without active refrigeration, thereby reducing dependency on mechanical cooling during ground handling and last-mile distribution. Insulated foil materials dominate current procurement volumes due to their favorable mass-to-thermal-resistance ratio, while non-woven fabric segments are gaining fastest in pharmaceutical applications where breathable yet thermally stable constructions address moisture accumulation risks. Cold chain logistics remains the largest application channel, though perishable transport segments are maturing as commoditization pressures compress margin pools in produce and dairy lanes.
The EU F-Gas Regulation and REACH compliance frameworks in Europe compel manufacturers to eliminate high-global-warming-potential blowing agents from insulated core materials, reshaping formulation roadmaps across the supply base. FDA validation requirements for pharmaceutical shipping containers in the United States create parallel compliance burdens that favor suppliers with documented thermal qualification protocols. Stakeholders must monitor evolving pharmacopeial standards for temperature excursion definitions, as tighter thresholds will determine which material technologies retain commercial viability in regulated lanes.
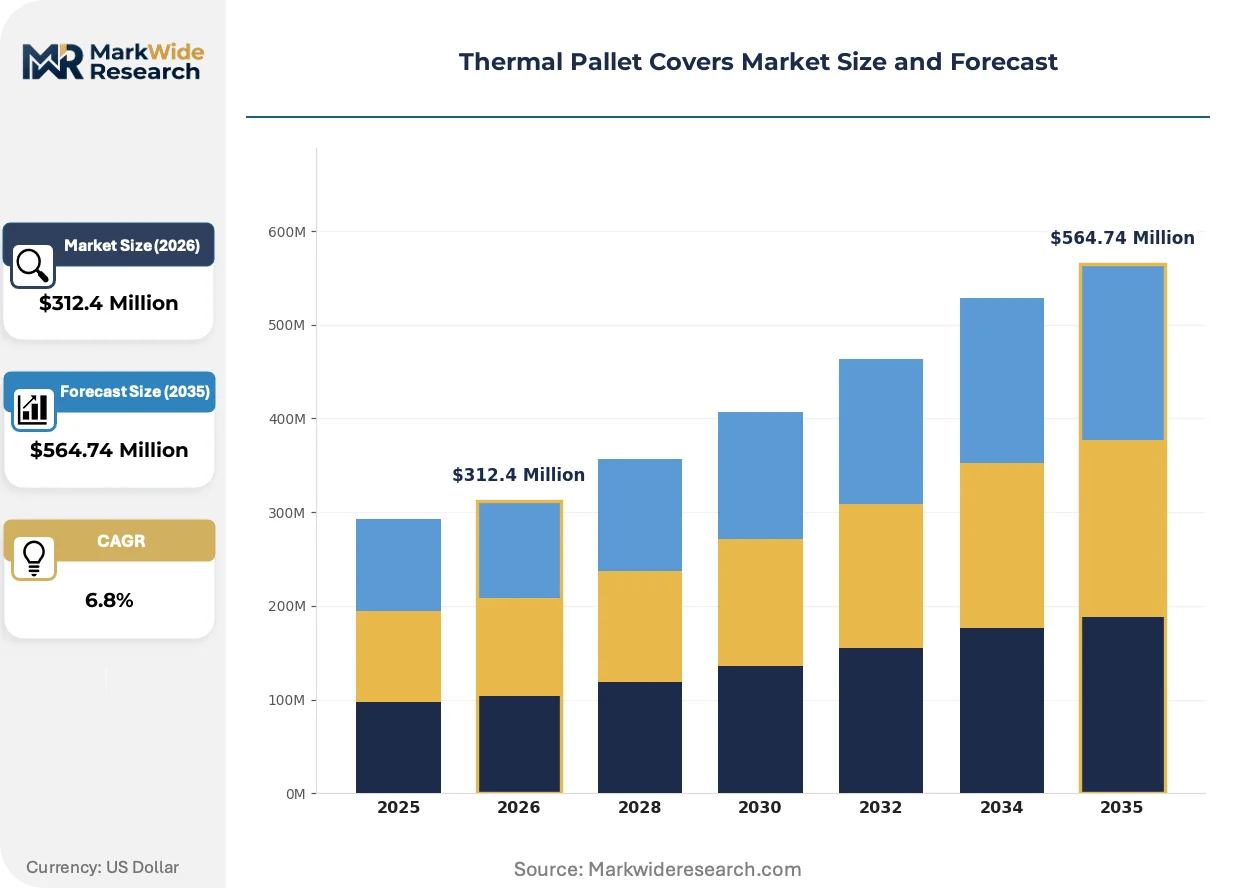
Market Dynamics
Pharmaceutical cold chains are pivoting toward passive thermal protection as biologics and cell therapies multiply temperature excursion risks. The EU F-Gas Regulation accelerates this structural migration by restricting synthetic refrigerants across European logistics networks.
Growth Catalysts
- Regulatory phase-out of HFC refrigerants:The EU F-Gas Regulation compels logistics operators to abandon mechanical cooling for intermodal handoffs, elevating thermal covers to primary protection status in pharmaceutical lanes.
- Biologics distribution expansion:Cell and gene therapy shipments require validated 2-8°C stability windows during extended ground segments, driving specification upgrades in multi-layer reflective materials.
- Centralized European distribution hubs:Germany's dense pharmaceutical export corridors concentrate procurement volumes for validated thermal systems serving Benelux and Nordic secondary distribution.
Market Restraints
- Aluminum-laminated substrate cost volatility:Primary aluminum pricing swings compress margin pools for manufacturers of reflective barrier films, forcing selective SKU rationalization.
- Core material supply concentration:Closed-cell foam composites rely on concentrated European chemical feedstock suppliers, exposing cover fabricators to REACH compliance-driven formulation disruptions.
- Passive duration limitations:Thermal covers cannot substitute active refrigeration beyond 120-hour thresholds, capping addressable market share in transoceanic pharmaceutical lanes.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO-validated cold chain expansion for generic injectables creates procurement white space for thermal cover suppliers meeting WHO prequalification standards.
- Reusable cover service models:Reverse logistics networks for rental-based thermal protection reduce per-shipment costs for mid-tier pharmaceutical distributors.
- MEA temperature assurance mandates:Gulf Cooperation Council pharmaceutical regulators are adopting EU-equivalent GDP guidelines, opening validated passive systems to Dubai and Riyadh distribution hubs.
Industry Challenges
- Thermal qualification protocol complexity:FDA 21 CFR Part 11 validation requirements for shipping container documentation extend sales cycles by 8-14 months for new supplier entrants.
- Multimodal integration friction:Thermal covers must interface with divergent air cargo ULD specifications and pharmaceutical trailer dimensions, complicating universal product architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Pallet Covers Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Woven Polypropylene, Non-Woven Fabric, Insulated Foil, Bubble Wrap Application: Cold Chain Logistics, Food Storage, Pharmaceutical Shipping, Perishable Transport Temperature Range: Low Temperature, High Temperature, Controlled Temperature, Ambient End User: Food Distributors, Healthcare Providers, Retailers, Manufacturers |
| Companies Covered | Smurfit Kappa Group, Amcor Plc, Cold Chain Technologies, Insulated Products Corporation, Thermal Packaging Solutions, Pelican BioThermal, 3M Company, Cryopak, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Pallet Covers Market Strategic Shifts
Material science advances and regulatory stringency are splitting thermal cover architectures into specialized tiers. The market is witnessing divergent evolution paths for commodity perishable protection versus validated pharmaceutical systems.
Multi-layer reflective barrier construction is bifurcating the supplier base into pharmaceutical-grade validators and commodity perishable providers. Cell therapy shippers demand 168-hour validated performance documentation, forcing material scientists to embed phase-change materials between aluminum-laminated substrates. This technical escalation compresses margin structures for undifferentiated produce-focused manufacturers while enabling premium positioning for qualified pharmaceutical specialists.
REACH compliance deadlines for blowing agent reformulation are eliminating legacy polyurethane cores from European supply chains. ECHA substance restrictions force foam suppliers to migrate toward hydrofluoroolefin alternatives or bio-based aerogel matrices. German pharmaceutical distributors now specify thermal covers with documented blowing agent pedigree, shifting procurement criteria from unit cost to compliance traceability.
Consolidated buying by third-party logistics providers concentrates contract value among fewer thermal cover vendors. Large European pharmaceutical 3PLs now mandate single-source national agreements with embedded reverse logistics obligations, displacing fragmented regional supplier relationships. This purchasing concentration is most pronounced in the Netherlands, where centralized distribution for temperature-sensitive generics creates procurement leverage exceeding neighboring markets.
Thermal Pallet Covers Market Segmentation
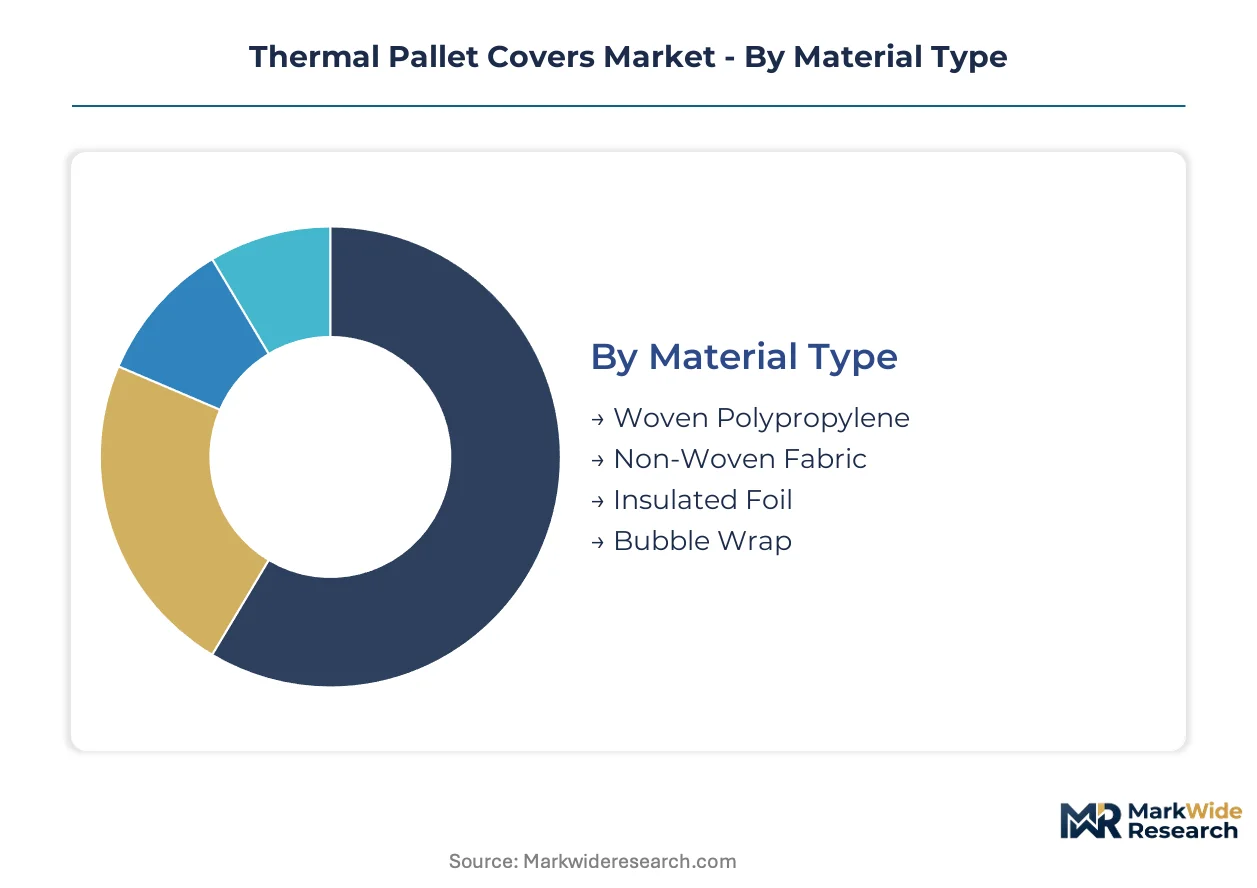
Thermal pallet cover specifications diverge sharply between validated pharmaceutical lanes and commodity perishable flows. Material composition, temperature banding, and end-use compliance requirements create distinct procurement tiers that suppliers must navigate simultaneously.
Material Type:
REACH compliance deadlines and FDA validation protocols split material sourcing into pharmaceutical-grade and industrial-grade supply chains.
- Insulated Foil:Multi-layer aluminum-laminated substrates with closed-cell foam cores deliver 48-120 hour thermal resistance. German pharmaceutical exporters specify these for validated 2-8°C cell therapy shipments under GDP guidelines.
- Non-Woven Fabric:Breathable polypropylene constructions mitigate moisture accumulation in temperature-sensitive biologics. Demand concentrates in Benelux distribution hubs where multi-modal handoffs require vapor-permeable yet thermally stable barriers.
- Woven Polypropylene:Cost-optimized for produce and dairy lanes with shorter protection windows.
- Bubble Wrap:Lightweight cushioning for ambient pharmaceutical shipments with minimal thermal risk.
Insulated foil handles the majority of throughput; non-woven fabric is expanding most quickly on share.
Application:
Customer procurement budgets stratify across temperature assurance mandates versus cost-per-unit minimization.
- Cold Chain Logistics:Third-party logistics providers contract for standardized cover fleets serving multiple pharmaceutical clients. Netherlands-based 3PLs now mandate embedded reverse logistics obligations in national agreements.
- Pharmaceutical Shipping:Cell and gene therapy distributors require 168-hour validated performance documentation with phase-change material integration. CDSCO-validated corridors in India create new procurement white space for WHO-prequalified suppliers.
- Perishable Transport:Commoditized produce lanes face margin compression from reusable rental models.
- Food Storage:Static warehouse applications with lower thermal performance thresholds.
Cold chain logistics anchors volume concentration; pharmaceutical shipping shows the steepest specification escalation.
Temperature Range:
Pharmacopeial standard revisions are narrowing excursion tolerance bands and reshaping cover design priorities.
- Controlled Temperature:2-8°C stability windows for biologics and vaccines dominate specification intensity. EMA guidance on temperature excursion definitions forces material scientists to embed redundant barrier layers.
- Low Temperature:Frozen pharmaceutical and plasma shipments require extended duration performance beyond 120-hour thresholds.
- High Temperature:Gulf Cooperation Council pharmaceutical regulators adopting EU-equivalent GDP guidelines are opening demand in Dubai and Riyadh distribution hubs.
- Ambient:Standard protection for non-critical generic drug shipments with minimal regulatory documentation.
Controlled temperature commands premium positioning; high temperature is gaining share fastest from regulatory harmonization in the Middle East.
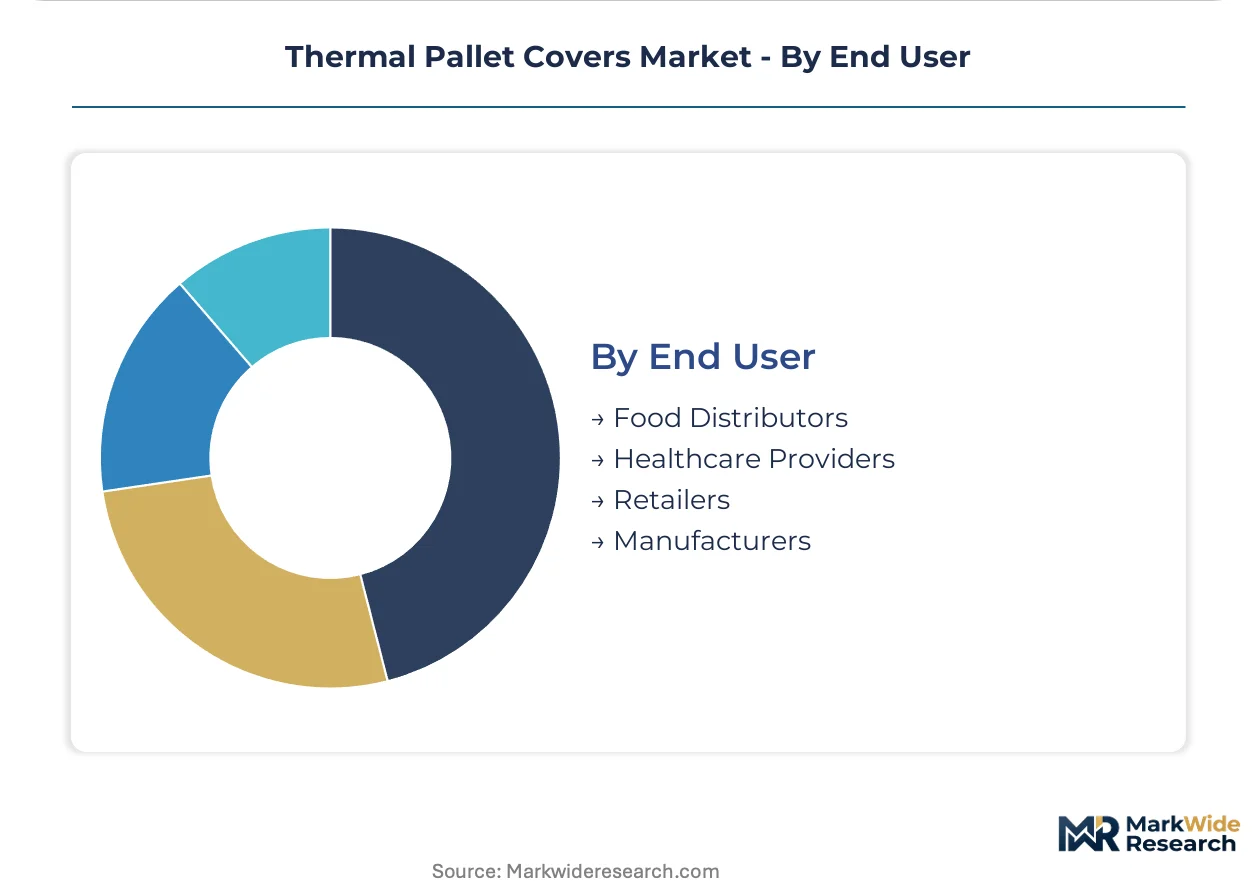
End User:
Consolidated buying power and compliance liability allocation determine supplier relationship structures.
- Healthcare Providers:Hospital systems and specialty pharmacies bear direct responsibility for therapy integrity during receipt. FDA 21 CFR Part 11 validation requirements extend their vendor qualification cycles to 8-14 months.
- Food Distributors:Historical volume leaders now facing displacement as pharmaceutical shippers scale procurement. Margin pressure from reusable cover service models compresses their supplier margins.
- Retailers:Grocery chains with private-label temperature-sensitive product lines.
- Manufacturers:Pharmaceutical and biotech firms with captive logistics operations.
Healthcare providers concentrate compliance-driven demand; food distributors retain volume scale but surrender margin to rental-based alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical shippers dominate procurement across concentrated European distribution corridors and emerging Indian export lanes. Cold Chain Technologies and Pelican BioThermal anchor premium positioning in validated temperature-assurance networks. Regional regulatory divergence shapes material specification requirements and supplier qualification protocols.
Germany
Pharmaceutical export corridors through Frankfurt and Hamburg concentrate demand for GDP-validated thermal systems serving Benelux and Nordic secondary distribution. The EU F-Gas Regulation compels logistics operators to abandon mechanical cooling for intermodal handoffs, elevating passive thermal protection to primary status. Baden-Württemberg's biologics manufacturing cluster drives specification intensity for 168-hour validated covers with phase-change material integration.
United States
FDA 21 CFR Part 11 validation requirements extend vendor qualification cycles to 8-14 months, concentrating contract value among established suppliers with documented thermal qualification protocols. Boston's cell and gene therapy corridor demands extended-duration performance documentation beyond standard 120-hour thresholds. The Pacific Northwest pharmaceutical logistics hub scales reusable cover service models to reduce per-shipment costs for mid-tier distributors.
India
CDSCO-validated cold chain expansion for generic injectables creates procurement white space for thermal cover suppliers meeting WHO prequalification standards. Maharashtra's pharmaceutical manufacturing belt concentrates export-oriented demand for 2-8°C stability assurance during extended ground segments to Mumbai air cargo terminals. The country's national pharmaceutical regulator tightens temperature excursion definitions, forcing material upgrades in multi-layer reflective barriers.
Netherlands
Centralized distribution for temperature-sensitive generics creates procurement leverage exceeding neighboring markets, with large pharmaceutical 3PLs mandating single-source national agreements. REACH compliance deadlines for blowing agent reformulation eliminate legacy polyurethane cores from supply chains serving Rotterdam and Amsterdam logistics hubs. Randstad-based distributors now specify thermal covers with documented blowing agent pedigree, shifting procurement criteria from unit cost to compliance traceability.
United Arab Emirates
Gulf Cooperation Council pharmaceutical regulators adopting EU-equivalent GDP guidelines open validated passive systems to Dubai and Riyadh distribution hubs. Dubai's pharmaceutical free zone concentrates demand for high-temperature protection systems addressing ambient extremes during ground handling. MOHAP's temperature assurance mandates accelerate specification upgrades among logistics operators serving MEA pharmaceutical import corridors.
Thermal Pallet Covers Market Competitive Environment
Player mix skews toward diversified packaging conglomerates with thermal divisions alongside specialized cold-chain engineering firms. Market structure concentrates contract value among suppliers with FDA validation protocols and REACH-compliant material roadmaps. Three archetypes dominate: pharmaceutical-grade validators with 168-hour qualification documentation, commodity perishable providers facing margin compression, and reusable service model operators building reverse logistics networks. Competitive moves center on M&A for thermal qualification capabilities and strategic partnerships with 3PLs for embedded reverse logistics obligations.
Among diversified packaging conglomerates, Smurfit Kappa Group and Amcor Plc occupy positions spanning commodity and premium tiers through portfolio breadth. Specialized cold-chain engineering firms exemplify pharmaceutical-grade positioning, with Cold Chain Technologies representing validated thermal system architects and Pelican BioThermal anchoring cell and gene therapy temperature-assurance protocols. 3M Company sits within material science leadership archetypes for reflective barrier films. These named entities illustrate competitive stratification without exhaustively mapping market presence.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Amcor Plc |
| Cold Chain Technologies |
| Insulated Products Corporation |
| Thermal Packaging Solutions |
| Pelican BioThermal |
| 3M Company |
| Cryopak |
| International Paper Company |
| Others |
Value Chain & Pricing Dynamics
Ninety-day raw material hedging cycles in aluminum-laminated substrates tie pricing power directly to REACH-compliant foam core availability across German and Dutch manufacturing clusters. Inventory positioning at Rotterdam and Hamburg logistics hubs concentrates procurement leverage among pharmaceutical 3PLs with embedded reverse logistics obligations.
Pricing Analysis
Prior-generation polyurethane-core covers trade at commodity benchmarks while REACH-compliant hydrofluoroolefin formulations command certification premiums and next-generation phase-change material systems anchor validated pharmaceutical tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA validation documentation, GDP compliance traceability, and volume scale commitments. Pricing pressure stems from aluminum spot volatility compressing reflective barrier film margins. Food distributors exhibit acute price sensitivity versus healthcare providers absorbing premium positioning for 168-hour validated performance.
Supply Chain Analysis
Strategic stockpiling of REACH-compliant blowing agents dominates inventory strategy as ECHA deadlines eliminate legacy polyurethane formulations from European supply chains. Manufacturing concentrates in Germany, the Netherlands, and the United States for pharmaceutical-grade validators, with China and India supplying woven polypropylene for commodity tiers. Raw material dependencies center on primary aluminum, closed-cell foam composites, and phase-change material substrates. Single-source vulnerability in European chemical feedstock suppliers exposes fabricators to formulation disruptions. Distribution runs through centralized pharmaceutical 3PL networks with reverse logistics obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal pallet cover procurement cycles track pharmaceutical capital expenditure waves, with biologics manufacturing expansion driving replacement demand across European and North American distribution corridors.
For Market Incumbents: Fortify qualification documentation against FDA 21 CFR Part 11 validation requirements that extend competitor sales cycles. Deepen backward integration into REACH-compliant foam core production to secure blowing agent pedigree traceability. Anchor capacity expansion in Baden-Württemberg and Randstad clusters where pharmaceutical export density concentrates contract value. For New Entrants and Emerging Players: Anchor in CDSCO-validated Indian export corridors for generic injectables where WHO prequalification standards create procurement white space. Target reusable cover service models with embedded reverse logistics obligations to displace fragmented regional suppliers. Pursue Gulf Cooperation Council GDP guideline adoption as the primary go-to-market angle for high-temperature protection systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming thermal divisions lacking pharmaceutical validation protocols. Long-term viability hinges on REACH-compliant material roadmaps and documented thermal qualification capabilities. Watch for EMA temperature excursion definition revisions as the inflection indicator forcing material technology upgrades across installed cover fleets.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA deadlines eliminate legacy polyurethane cores from European pharmaceutical supply chains. |
| Phase-Change Material Integration | Cell therapy shippers demand 168-hour validated performance documentation for gene therapy distribution. |
| Reverse Logistics Network Buildout | Reusable cover service models reduce per-shipment costs for mid-tier pharmaceutical distributors. |
| FDA Validation Protocol Investment | Documented thermal qualification capabilities concentrate contract value among established suppliers. |
| GCC GDP Guideline Alignment | MOHAP mandates open Dubai and Riyadh distribution hubs to validated passive thermal systems. |
Study Parameters
Cross-validation between primary interviews with cold chain logistics directors and secondary validation through EMA guidance documents anchors the qualitative findings. Conversations with pharmaceutical 3PL procurement managers, thermal cover manufacturing engineers, regulatory affairs specialists at CDSCO and FDA, and biologics distribution executives informed material specification trends. Secondary sources include REACH substance restriction databases, GDP guideline harmonization frameworks, customs trade data for aluminum-laminated substrates, and pharmaceutical shipping container validation protocols. Bottom-up demand modeling triangulates against top-down market sizing across material type and application segments.
Sensitivity analysis around aluminum price volatility and REACH compliance timelines shapes the forecast framework. Segmentation dimensions modeled include material composition, temperature range banding, end-user compliance liability, and regional regulatory cluster across the projection horizon. CAGRs derive from pharmaceutical biologics shipment growth trajectories and passive thermal protection substitution rates for mechanical cooling. Industry-specific inputs incorporate CDSCO cold chain expansion timelines and F-Gas Regulation phase-out schedules.
Material uncertainties — regulatory deadline accelerations, aluminum supply disruptions, pharmacopeial standard revisions — sit outside the modeled envelope. Forecasts reflect assumptions on GDP guideline adoption rates and blowing agent reformulation completion. Revision becomes warranted when EMA temperature excursion thresholds tighten beyond current 2-8°C stability windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Canada Pallets Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market