
 Pallet Bands Market | 2026-2036
Pallet Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Bands Market Analytics
Buyer concentration among North American third-party logistics providers is restructuring procurement volumes for pallet securing products. Alliance Rubber Company leverages its synthetic rubber compounding expertise to serve high-volume warehouse operators. Aero Rubber Company, Inc. anchors its position through custom extrusion capabilities for non-standard pallet configurations. Uline, Inc. controls distribution reach via its direct-to-fulfillment-center catalog model.
Pallet bands are elastic securing devices manufactured from natural rubber, synthetic elastomers, or woven polymers, typically exhibiting 50-150% elongation capacity and tensile strength ratings between 8-25 MPa depending on duty class; their primary function is to stabilize unitized loads during handling, storage, and transit without requiring mechanical fastening equipment. Heavy-duty bands and non-slip variants command premium positioning due to their performance in automated conveyor environments where load shift tolerance approaches zero. Polyester and nylon material grades are gaining share in cold-chain applications where natural rubber embrittles, while polyethylene sustains volume leadership in ambient-temperature warehouse operations.
The EPA oversees volatile organic compound emissions from rubber processing facilities, compelling Ohio and Texas manufacturing plants to deploy thermal oxidizers in extrusion lines. OSHA ergonomic guidelines for manual material handling indirectly shape band width and tension specifications to reduce repetitive strain injuries among warehouse workers. Stakeholders must monitor how California's extended producer responsibility frameworks for plastic packaging may eventually classify certain polymer band grades as regulated articles.
Market Dynamics
Automated warehouse conveyor systems are compressing tolerance for load shift, forcing pallet band specifications toward zero-slip elastomer grades that natural rubber cannot reliably deliver.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in Germany's industrial corridor are tripling band procurement volumes to secure irregular parcel loads for high-velocity sortation.
- REACH chemical compliance:Europe's rubber product regulations are accelerating synthetic elastomer adoption among compounders serving cold-chain distribution networks.
- Cold-chain infrastructure buildout:Pharmaceutical and fresh-produce handlers in North America are specifying polyester-reinforced bands where embrittlement risk disqualifies natural rubber.
Market Restraints
- Petrochemical feedstock volatility:Synthetic rubber prices track naphtha and butadiene contracts, compressing margin predictability for extrusion manufacturers.
- Ohio-Texas production concentration:Thermal oxidizer mandates from EPA regional offices have locked capacity expansion behind six-figure compliance investments.
- Mechanical fastening substitution:Stretch wrap systems with pre-tension sensors are capturing share in ambient-temperature warehouse operations where band elasticity is non-critical.
Strategic Opportunities
- India's pharmaceutical cold chain:CDSCO temperature-compliance mandates for biologics distribution are creating specification demand for nylon-core bands in Mumbai and Hyderabad logistics clusters.
- California extended producer responsibility:Pending plastic packaging frameworks may reclassify polymer bands as regulated articles, rewarding early recyclability certification.
- Direct-to-fulfillment distribution:Catalog models bypassing industrial distributors are capturing procurement authority from warehouse operators seeking SKU consolidation.
Industry Challenges
- Compounding technician scarcity:Synthetic rubber formulation expertise concentrates among aging workforces in Akron and Houston, constraining quality scaling.
- ISO 9001 certification timelines:Automated conveyor OEMs are requiring supplier quality documentation that extends onboarding to 14-18 months.
- Legacy band inventory incompatibility:Warehouse operators holding natural rubber stock face write-down pressure as synthetic grades become specification-default.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Bands Market |
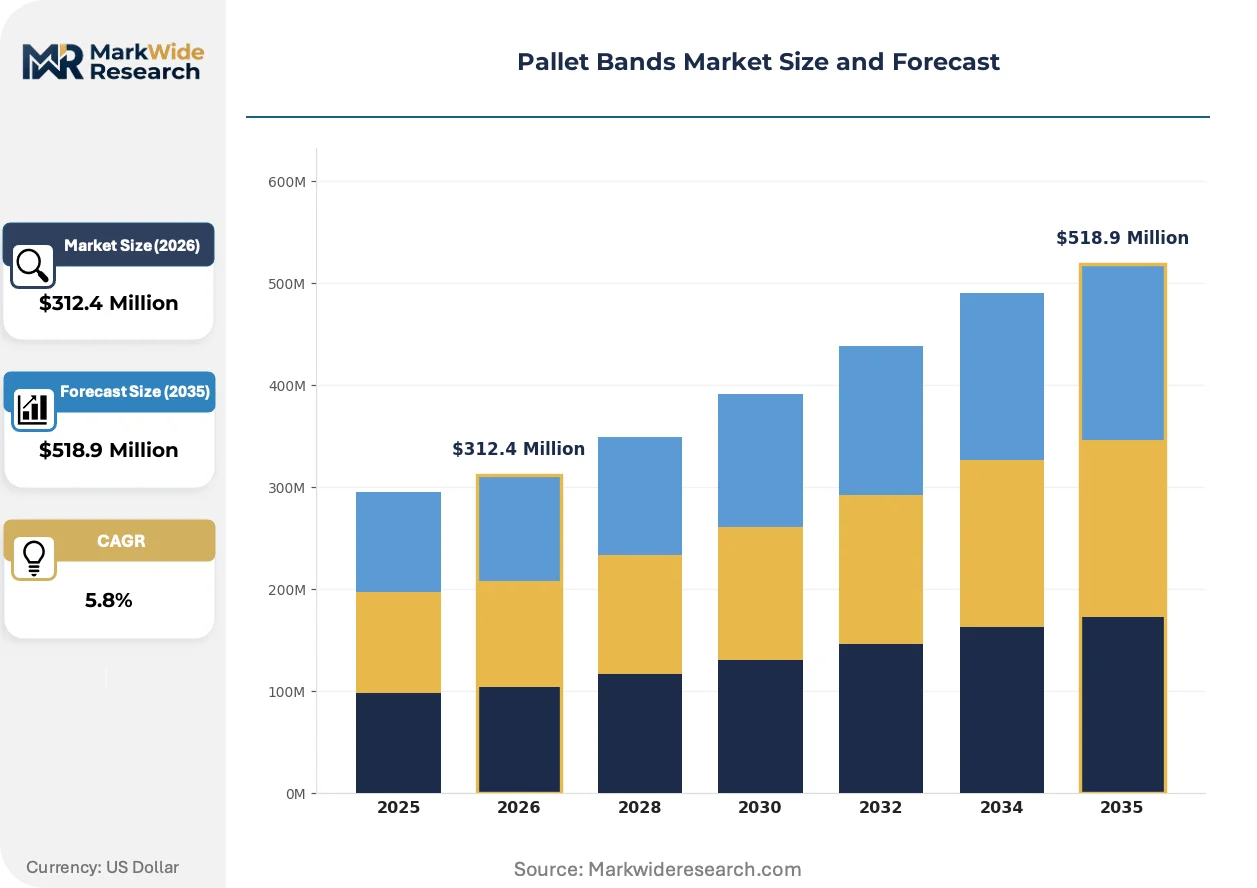
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bands, Heavy-Duty Bands, Stretch Bands, Non-Slip Bands Material: Polyethylene, Rubber, Nylon, Polyester Application: Warehouse, Transportation, Retail, Industrial End User: Logistics Companies, Manufacturing Plants, Distribution Centers, E-Commerce |
| Companies Covered | Alliance Rubber Company, Aero Rubber Company, Inc., Staples Inc., Uline, Inc., Western Rubber & Supply, Inc., Erich Nonne GmbH, Erich Utsch AG, 3M, Packit Packaging Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Bands Market Evolving Landscape
Material science advances and regulatory chemistry constraints are bifurcating the product landscape into performance-grade synthetics and commodity polyethylene, with specification authority migrating from procurement to engineering functions.
Silicone-modified synthetic elastomers are expanding into automated conveyor environments where temperature cycling between -20°C and +40°C degrades conventional compounds. Pharmaceutical distributors in Germany and the Netherlands are specifying these grades for validated cold-chain lanes. The technology is expanding into premium pricing tiers that natural rubber suppliers cannot penetrate without reformulation investment.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber articles are compelling compounders to certify raw material streams through ECHA-registered laboratories. Ohio and Texas manufacturing plants now require third-party testing documentation for every production lot destined for European export. Synthetic rubber grades with pre-certified feedstock chains are capturing specification preference from risk-averse multinational logistics operators.
Buyer consolidation among North American third-party logistics providers is compressing supplier rosters to three approved vendors per warehouse network. Engineering teams at these operators are unbundling band procurement from general MRO purchasing, creating direct specification relationships with extrusion manufacturers. This pattern is most visible in the Chicago and Dallas fulfillment corridors where facility counts exceed fifty nodes.
Pallet Bands Market Segmentation
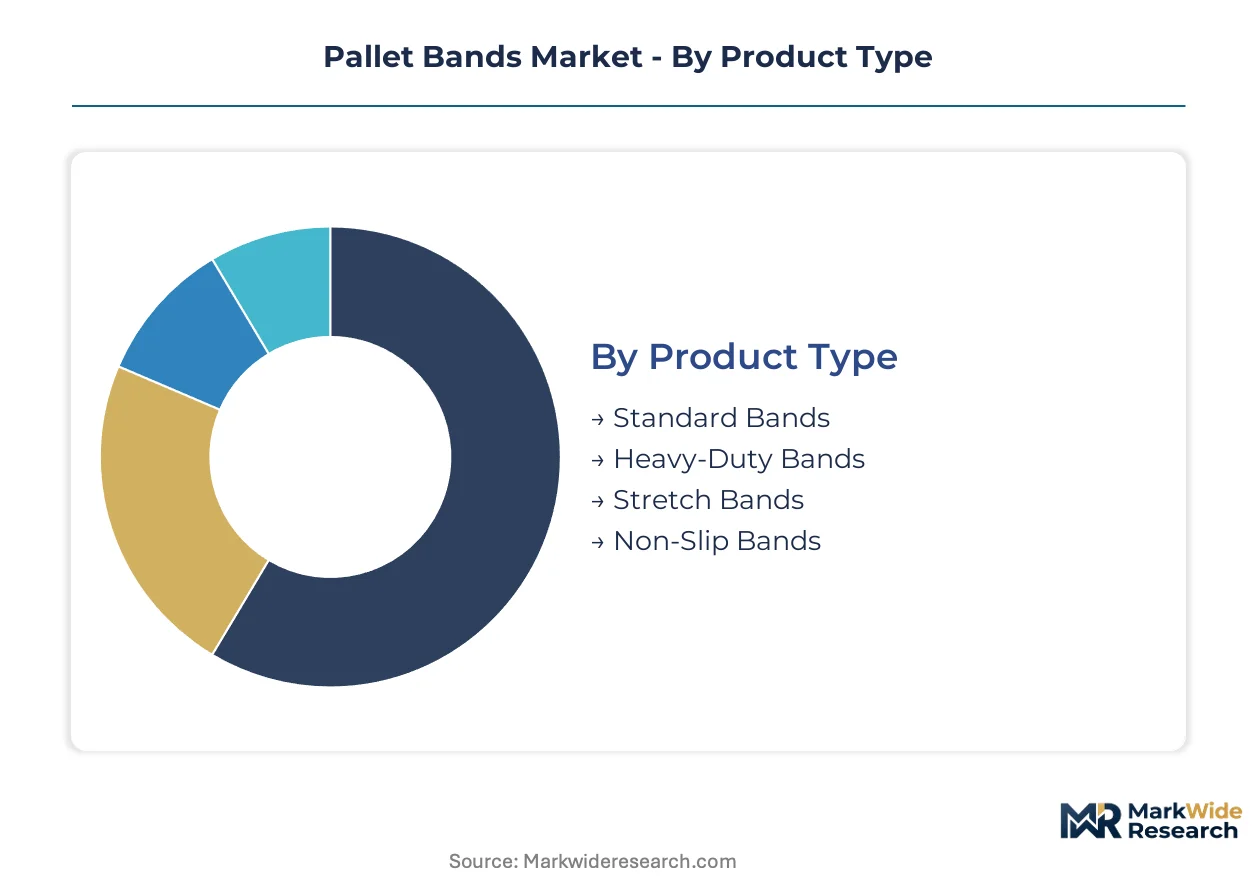
Pallet band procurement patterns diverge sharply between ambient warehouse operations and validated cold-chain environments, with specification authority migrating from procurement officers to engineering teams as load-securing tolerances tighten. Understanding these segment boundaries reveals where margin compression and premium pricing coexist within the same product category.
Product Type:
Standalone securing applications dominate high-volume warehouse procurement, while embedded system integration characterizes automated conveyor specifications where zero-slip performance is mandatory.
- Standard Bands:Polyethylene and natural rubber formulations serve ambient-temperature warehouse operations with 50-100% elongation ratings. Demand concentrates among U.S. third-party logistics providers in the Chicago and Dallas fulfillment corridors where manual handling predominates and cost-per-unit drives procurement decisions.
- Heavy-Duty Bands:Synthetic elastomer compounds deliver 100-150% elongation with tensile strength exceeding 20 MPa for irregular load geometries. German industrial logistics operators in the Rhine-Ruhr corridor specify these grades for high-velocity e-commerce sortation where mechanical fastening would damage parcel integrity.
- Stretch Bands:Woven polymer constructions with memory-recovery properties suit repetitive application cycles in retail backroom operations.
- Non-Slip Bands:Surface-modified elastomers with friction coefficients above 0.6 serve automated conveyor environments in pharmaceutical distribution.
Volume placements concentrate in Standard Bands; the faster expansion belongs to Heavy-Duty Bands.
Material:
Cost tier stratification separates commodity polyethylene from performance-grade synthetics, with cold-chain compliance requirements pushing specification decisions toward certified feedstock chains.
- Polyethylene:Virgin and recycled grades dominate ambient-temperature warehouse procurement due to price stability and extrusion efficiency. U.S. distribution centers in Ohio and Texas sustain volume leadership through direct mill relationships, though California's pending extended producer responsibility frameworks may reclassify certain grades as regulated articles.
- Rubber:Natural and synthetic elastomer formulations span duty classes from light warehouse securing to heavy industrial stabilization. REACH Annex XVII polycyclic aromatic hydrocarbon restrictions are accelerating synthetic adoption among compounders serving European pharmaceutical cold-chain networks, with ECHA-registered laboratory certification now required for every production lot.
- Nylon:High-tenacity filament constructions maintain dimensional stability across -40°C to +80°C temperature cycling for biologics distribution.
- Polyester:Reinforced core structures resist embrittlement in frozen supply chains where natural rubber fails.
Polyethylene holds the largest installed base; polyester and nylon are climbing the fastest as cold-chain infrastructure expands.
Application:
Customer type determines whether bands function as primary load securing or supplementary stabilization within multi-layer containment systems.
- Warehouse:High-frequency application and removal cycles demand durability and ergonomic width specifications to comply with OSHA guidelines for manual material handling. North American third-party logistics providers are consolidating supplier rosters to three approved vendors per network, unbundling band procurement from general MRO purchasing.
- Transportation:Vibration resistance and UV stability requirements favor synthetic elastomer grades for over-the-road freight. German automotive parts distributors specify silicone-modified compounds for validated lanes where temperature cycling between -20°C and +40°C degrades conventional materials.
- Retail:Backroom stock rotation and display replenishment drive demand for color-coded sizing systems.
- Industrial:Heavy manufacturing environments require cut-resistant formulations for metal and glass handling.
Warehouse applications command the highest procurement volumes; transportation specifications are gaining share fastest as fleet operators adopt zero-slip standards.
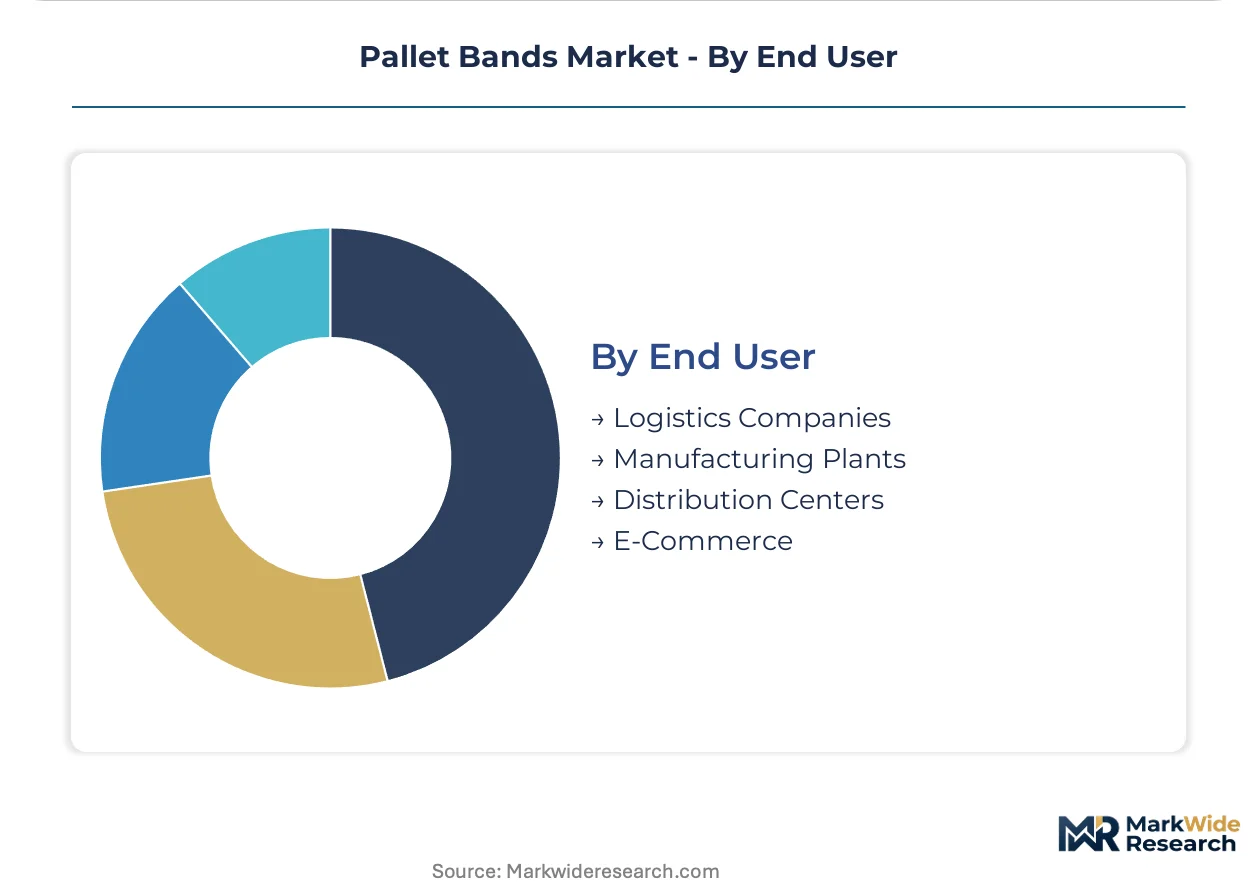
End User:
Scale and specification sophistication separate enterprise procurement functions from decentralized facility-level purchasing.
- Logistics Companies:Multi-node warehouse networks leverage consolidated procurement volumes to extract pricing concessions and enforce quality documentation standards. ISO 9001 certification timelines extending to 14-18 months are compressing supplier rosters to extrusion manufacturers with pre-established quality systems.
- Manufacturing Plants:Inbound material securing and outbound finished goods stabilization create dual demand streams with differing specification requirements. Akron and Houston compounding expertise concentrates among aging workforces, constraining quality scaling for synthetic rubber formulations.
- Distribution Centers:Direct-to-fulfillment catalog models are capturing procurement authority through SKU consolidation offerings.
- E-Commerce:Irregular parcel geometries and high-velocity sortation drive specification toward heavy-duty and non-slip grades.
Logistics companies generate the largest aggregate demand; e-commerce fulfillment centers are expanding procurement fastest as band-per-pallet ratios rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority for pallet securing products concentrates among third-party logistics operators in Germany's industrial corridor, with e-commerce fulfillment density driving specification shifts toward heavy-duty synthetic grades across multiple continents.
United States
Third-party logistics networks in the Chicago and Dallas fulfillment corridors are consolidating supplier rosters to three approved vendors per warehouse network. OSHA ergonomic guidelines for manual material handling shape band width specifications to reduce repetitive strain injuries. Ohio and Texas manufacturing plants deploy thermal oxidizers to comply with EPA regional mandates on volatile organic compound emissions from rubber processing.
Germany
Rhine-Ruhr logistics operators specify heavy-duty synthetic elastomer bands for high-velocity e-commerce sortation where mechanical fastening would damage parcel integrity. ECHA-registered laboratory certification for REACH Annex XVII polycyclic aromatic hydrocarbon restrictions applies to every production lot bound for pharmaceutical cold-chain networks. Stuttgart automotive parts distributors validate silicone-modified compounds for temperature cycling between -20°C and +40°C.
India
CDSCO temperature-compliance mandates for biologics distribution create specification demand for nylon-core bands in Mumbai and Hyderabad logistics clusters. The national pharmaceutical regulator enforces cold-chain infrastructure standards that disqualify natural rubber in frozen supply chains. Maharashtra-based fulfillment operators face procurement pressure as synthetic grades become specification-default for pharmaceutical distribution.
Netherlands
Pharmaceutical distributors in Rotterdam and Amsterdam logistics hubs specify silicone-modified synthetic elastomers for validated cold-chain lanes. REACH chemical composition rules accelerate synthetic adoption among compounders serving European distribution networks. Eindhoven Region extrusion manufacturers capture specification preference from risk-averse multinational logistics operators through pre-certified feedstock chains.
China
Yangtze River Delta warehouse operators adopt polyester-reinforced bands where embrittlement risk disqualifies natural rubber in pharmaceutical cold-chain applications. GB standards and MIIT industrial guidelines shape synthetic rubber formulation requirements for logistics equipment. Shanghai-based fulfillment centers face procurement volume expansion as irregular parcel geometries drive band-per-pallet ratios higher.
Pallet Bands Market Competitive Landscape
Ohio and Texas producers anchor one tier of synthetic rubber compounding; German specialists hold specification authority in European pharmaceutical cold-chain networks. The vendor base organizes around three strategic archetypes: synthetic elastomer compounders with REACH-certified feedstock chains, custom extrusion specialists serving non-standard pallet configurations, and direct-to-fulfillment catalog distributors capturing procurement authority through SKU consolidation. Capacity expansion and strategic partnerships dominate competitive moves as automated conveyor OEMs extend supplier quality documentation timelines.
Within the synthetic compounding tier, Alliance Rubber Company and Aero Rubber Company, Inc. exemplify divergent positioning strategies. Alliance Rubber Company occupies a position among compounders leveraging formulation expertise for high-volume warehouse operators. Aero Rubber Company, Inc. anchors the custom extrusion archetype for non-standard pallet configurations. Uline, Inc. represents the direct-to-fulfillment distribution model that bypasses industrial distributors to capture procurement authority from warehouse operators seeking SKU consolidation.
| Leading Market Players |
|---|
| Alliance Rubber Company |
| Aero Rubber Company, Inc. |
| Staples Inc. |
| Uline, Inc. |
| Western Rubber & Supply, Inc. |
| Erich Nonne GmbH |
| Erich Utsch AG |
| 3M |
| Packit Packaging Solutions |
| Others |
Value Network & Pricing Analysis
Third-party logistics provider consolidation in the Chicago and Dallas fulfillment corridors anchors pricing power with volume-scale buyers who negotiate three-vendor roster terms. This buyer concentration compresses margin predictability for extrusion manufacturers while rewarding compounders with pre-certified REACH feedstock chains.
Pricing Analysis
Volume-scale polyethylene grades trade on thin margins while synthetic elastomer premiums widen. Three-tier pricing structure across premium silicone-modified, standard synthetic, and economy polyethylene levels reflects certification grade and temperature-performance specifications. Cost compression in commodity tiers is intensifying because stretch wrap systems capture ambient-temperature share. Small warehouse operators exhibit highest price sensitivity; pharmaceutical cold-chain distributors prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Ohio and Texas synthetic rubber compounding capacity locked behind EPA thermal oxidizer mandates. Raw material streams draw from naphtha and butadiene petrochemical feedstocks, natural rubber latex imports, and ECHA-certified synthetic elastomer precursors. Tariff exposure on Asian polymer imports threatens margin stability for distributors serving West Coast fulfillment centers. Distribution runs through direct-to-fulfillment catalog models that bypass industrial MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
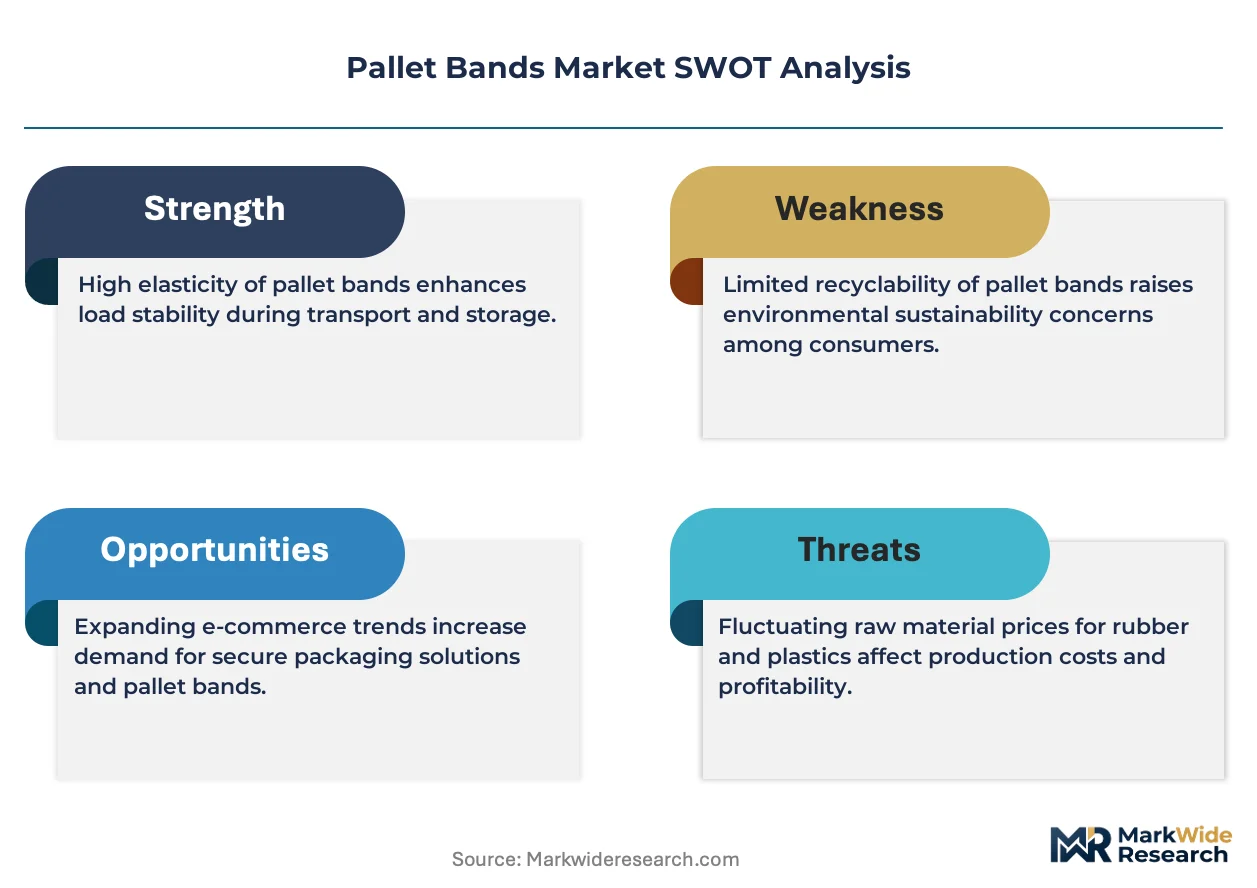
This market is consolidating around REACH-certified compounders as regulatory chemistry constraints force reformulation investments that weaker natural rubber specialists cannot fund.
For Market Incumbents: Anchor specification authority through ECHA-registered laboratory partnerships that accelerate European pharmaceutical cold-chain approvals. Secure backward integration into certified synthetic elastomer feedstocks before petrochemical volatility destabilizes margin structures. Stretch wrap substitution in ambient warehouse operations threatens volume placements; defend through heavy-duty grade differentiation for automated conveyor environments. For New Entrants and Emerging Players: Begin with India's pharmaceutical cold-chain corridor where CDSCO temperature mandates create specification demand without entrenched supplier relationships. Target nylon-core band production for Mumbai and Hyderabad logistics clusters where natural rubber disqualification opens procurement windows. Pursue direct-to-fulfillment catalog positioning that consolidates SKU authority from decentralized warehouse purchasing. For Investors and Strategic Acquirers: The window for entry favors synthetic rubber compounders with pre-certified REACH feedstock chains and established thermal oxidizer compliance. Long-term viability hinges on specification migration toward zero-slip elastomer grades that natural rubber cannot reliably deliver. Watch for California extended producer responsibility framework finalization as inflection signal for polymer band reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Feedstock Certification | ECHA-registered laboratory partnerships unlock European pharmaceutical cold-chain specifications. |
| Silicone-Modified Compound Development | Temperature cycling resistance captures premium positioning in automated conveyor environments. |
| Direct-to-Fulfillment Distribution Buildout | Catalog models bypass industrial distributors to capture procurement authority from warehouse operators. |
| Thermal Oxidizer Capacity Expansion | EPA compliance investments in Ohio and Texas lock in synthetic rubber extrusion capacity. |
| Nylon-Core Production for Cold Chain | CDSCO mandates in India create specification demand where natural rubber embrittles. |
Research Methodology
Trade databases, chemical industry association reports, and regulatory filing repositories formed the secondary backbone for demand quantification. Primary interviews with extrusion plant managers, third-party logistics procurement leads, pharmaceutical cold-chain operators, and rubber compounding technicians validated specification trends. Bottom-up shipment data triangulated against top-down consumption estimates across product type, material grade, and application segments.
Historical trendline analysis tracked specification shifts from natural rubber to synthetic elastomer grades across the projection horizon. Modeled dimensions included duty class, material chemistry, temperature performance tier, and end-use vertical. CAGRs derived from segment-level volume trajectories adjusted for REACH regulatory compliance timelines and cold-chain infrastructure buildout rates. Petrochemical feedstock contract volatility and automated conveyor OEM qualification periods informed sensitivity ranges.
Feedstock price shocks, regulatory reclassification events, and mechanical fastening substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about specification migration speed and certification timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
India Pallets Market