
 Pallet Wraps Market | 2026-2036
Pallet Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Wraps Market Outlook
Aftermarket film recovery and recycling services is reconfiguring margin pools away from virgin resin sales toward closed-loop collection programs. Berry Global leverages its North American collection infrastructure to control post-industrial scrap flows. Dow Chemical Company anchors technical innovation through metallocene polyethylene catalyst platforms that improve puncture resistance. Amcor competes via global procurement scale across multiple resin chemistries.
Pallet wraps are highly extensible polymer films, typically 12–35 microns thick, engineered to elongate 200–400% under tension and recover to form a unitizing force around palletized loads. The primary purpose is to secure goods during transit while protecting against moisture, dust, and tampering. Stretch film dominates volume due to its cost efficiency in automated and semi-automated warehouse environments. Multi-layer coextrusion technology captures expanding margin pools as converters replace monolayer structures with puncture-resistant formulations. Hybrid materials represent the fastest-evolving material category as brand owners seek to balance performance with sustainability targets.
The EPA regulates resin manufacturing emissions under the Clean Air Act, while OSHA sets workplace exposure limits for volatile compounds during film extrusion. The EU REACH framework restricts certain phthalate plasticizers in PVC-based wraps, redirecting formulation investment toward polyethylene alternatives. Stakeholders must monitor evolving extended producer responsibility schemes that will determine who bears collection infrastructure costs.
Market Dynamics
Automated stretch wrapping systems are displacing manual banding in e-commerce fulfillment centers, compressing labor costs while accelerating film consumption per pallet. This equipment shift concentrates purchasing power among large logistics operators capable of justifying capital deployment.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are redirecting converter investment toward post-consumer resin blends, expanding addressable volume for circular film formulations.
- Automotive parts distribution:Germany's industrial logistics corridor generates sustained demand for high-performance load containment films with puncture resistance specifications.
- Metallocene polyethylene catalyst platforms:Advanced polymerization technology is improving film elongation recovery and puncture resistance, enabling downgauging without performance loss.
Market Restraints
- Crude oil derivative volatility:Ethylene and propylene feedstock costs swing with naphtha and natural gas liquid pricing, compressing converter margins without pass-through mechanisms.
- Resin supply concentration:Gulf Coast petrochemical complexes dominate North American polyethylene supply, exposing film extruders to hurricane-related production interruptions.
- Mechanical recycling contamination limits:Multi-layer coextruded films face technical barriers to closed-loop reprocessing, constraining circular economy claims.
Strategic Opportunities
- Post-industrial scrap collection infrastructure:Closed-loop collection programs are capturing margin pools previously retained by virgin resin suppliers, rewarding backward-integrated converters.
- Hybrid material formulations:Bio-based and recycled content blends offer positioning against sustainability targets without full performance sacrifice.
- Extended producer responsibility schemes:Emerging frameworks in France and Italy will determine collection cost allocation, favoring early infrastructure investors.
Industry Challenges
- Coextrusion equipment specialization:Multi-layer line installation demands capital commitments exceeding monolayer retrofits, stranding smaller converters.
- REACH compliance documentation:Phthalate restrictions in PVC-based wraps require reformulation investment and supply chain requalification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Wraps Market |
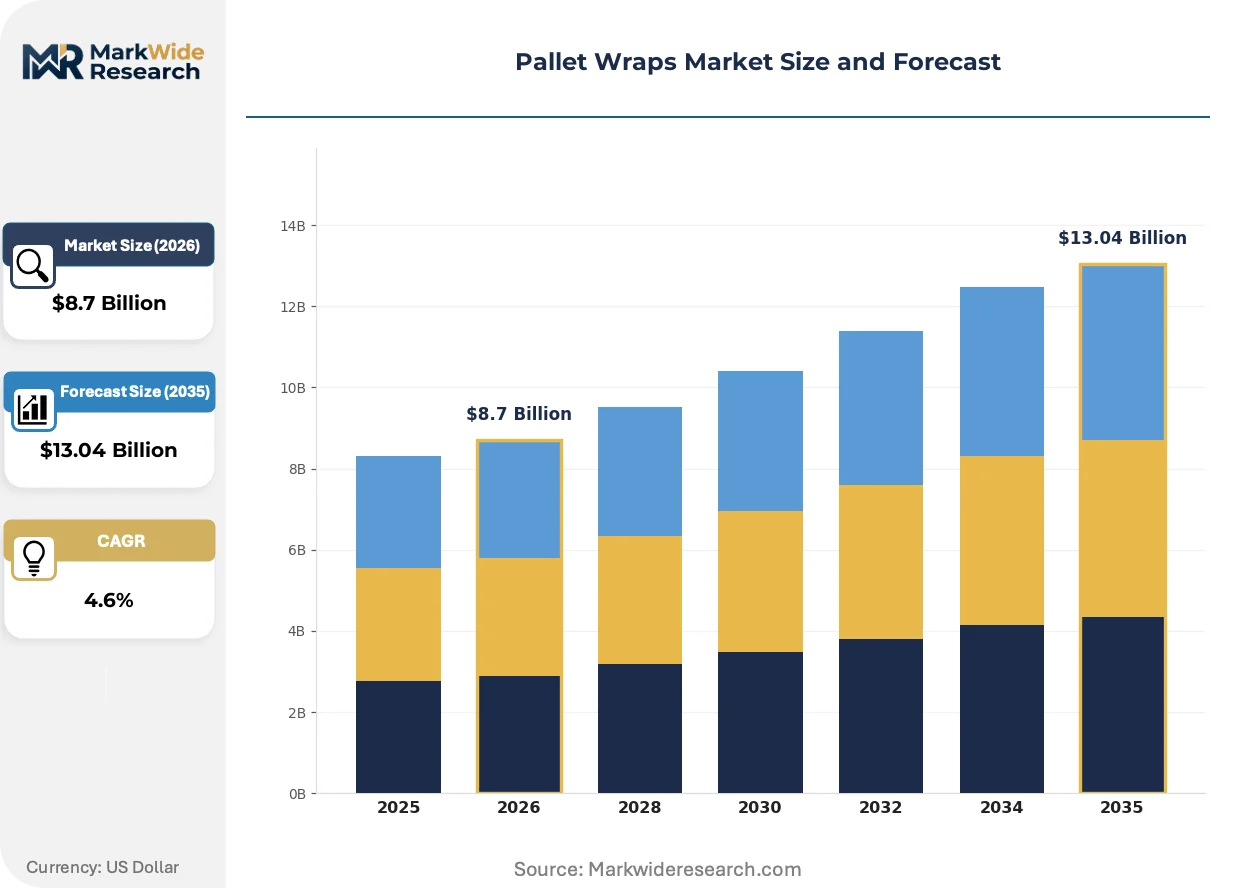
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Hood Wraps, Pallet Covers Material: Polyethylene, Polypropylene, PVC, Hybrid Materials End User: Retail, Food & Beverage, Pharmaceuticals, Electronics Packaging Type: Single Layer, Multi-layer, Decorative, Custom Printed |
| Companies Covered | AEP Industries, Paragon Films, Berry Global, Amcor, Intertape Polymer Group, Sigma Plastics Group, Coveris, Dow Chemical Company, Inteplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Wraps Market Strategic Shifts
Film converters are engineering material architectures that reconcile load containment performance with mechanical recyclability. This tension between functional specifications and circular design principles is driving equipment and formulation roadmaps.
Machine-direction oriented stretch film is digitizing warehouse automation integration through embedded RFID tags and tension-sensing feedback loops. Third-party logistics providers operating high-velocity fulfillment centers are adopting these intelligent films at accelerated replacement cycles. The technology is digitizing inventory tracking and damage attribution, compressing insurance and claims processing overhead.
REACH restrictions on phthalate plasticizers in flexible PVC applications are redirecting formulation investment toward polyethylene alternatives. Industrial converters serving food-contact and medical logistics segments face accelerated requalification timelines. Germany's automotive supply base is responding fastest, having pre-emptively shifted specifications ahead of enforcement dates.
Consolidated buying by mega-fulfillment operators is compressing supplier rosters and extending contract durations. Regional distributors serving mid-tier manufacturers are losing share to direct procurement portals operated by resin-integrated film producers. This concentration is most visible in the Netherlands and Belgium, where port-proximate warehousing clusters have centralized purchasing decisions for cross-border European distribution.
Pallet Wraps Market Segmentation
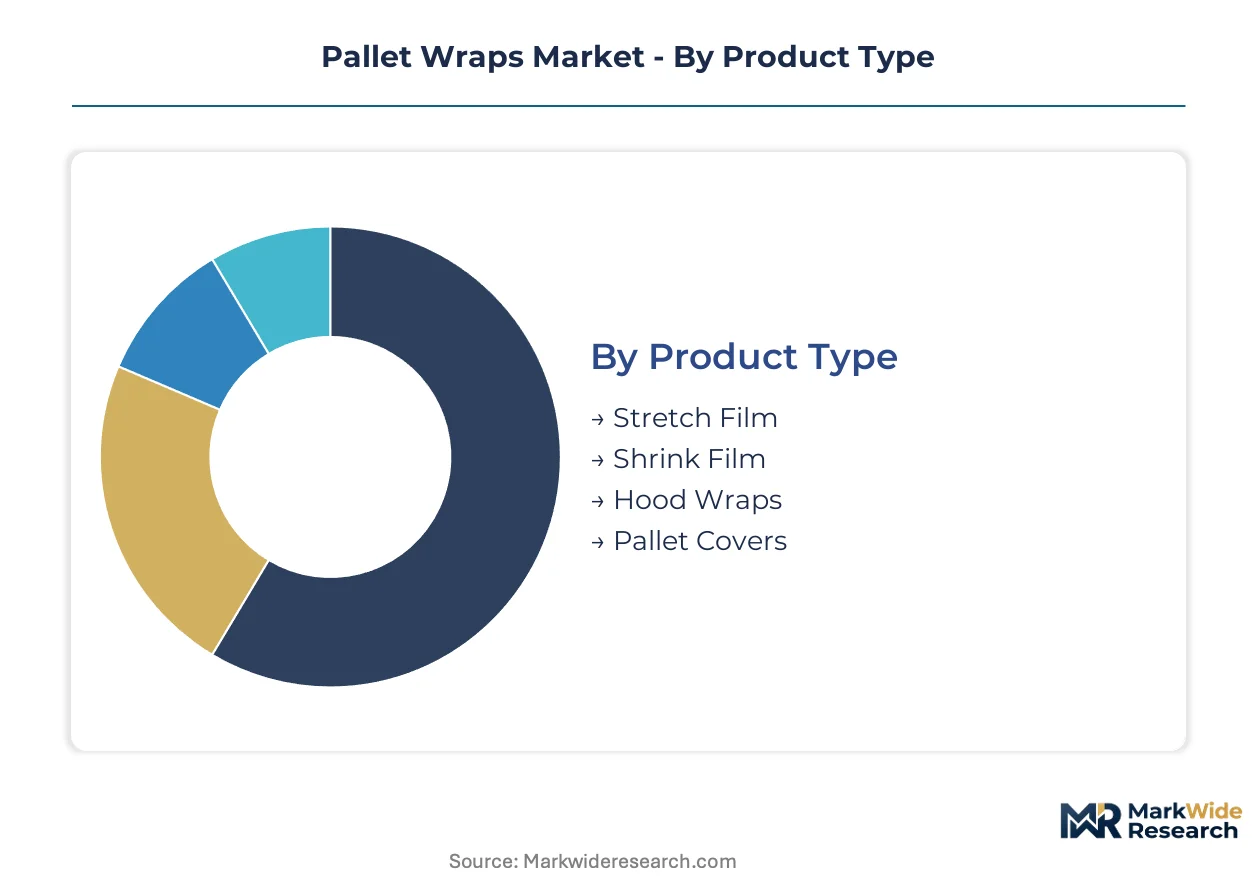
Pallet wrap segmentation reveals divergent technical requirements across load containment applications. Material architecture and layer construction determine compatibility with automated wrapping systems and circular recovery pathways.
Product Type:
Stretch film dominates warehouse automation while shrink formats serve specialized containment needs.
- Stretch Film:Linear low-density polyethylene formulations elongate 200-400% under tension to generate unitizing force around palletized loads. E-commerce fulfillment centers in Germany's Ruhr industrial corridor are standardizing on 12-23 micron cast stretch films for high-velocity automated lines, driven by labor cost compression targets.
- Shrink Film:Heat-activated biaxially oriented structures conform tightly to irregular load geometries through controlled thermal recovery. Pharmaceutical distribution hubs in Switzerland demand medical-grade shrink formats with tamper-evident sealing for temperature-sensitive biologics, constrained by batch qualification timelines.
- Hood Wraps:Pre-sized tubular films slip over palletized loads without tensioning equipment, serving intermittent-volume operations.
- Pallet Covers:Loose-fitting polyethylene sheets provide dust and moisture protection for static storage applications.
Established volume favors Stretch Film; emerging adoption favors Hood Wraps.
Material:
Resin selection balances puncture resistance against mechanical recyclability constraints.
- Polyethylene:Metallocene-catalyzed linear low-density grades deliver superior elongation recovery and dart impact resistance compared to conventional Ziegler-Natta polymers. Automotive parts distributors in Stuttgart specify high-performance polyethylene wraps for sharp-edged metal components, pressured by downgauging mandates without load failure.
- Hybrid Materials:Bio-based and post-consumer recycled content blends address EU Packaging and Packaging Waste Regulation recyclability thresholds while maintaining functional specifications. French logistics operators are piloting 30% recycled content stretch films under extended producer responsibility pre-compliance programs.
- Polypropylene:Oriented polypropylene offers higher stiffness and clarity for retail display applications.
- PVC:Phthalate-plasticized formulations face REACH restriction-driven displacement toward polyethylene alternatives.
Polyethylene retains cost-positioning dominance; Hybrid Materials are climbing the fastest on regulatory tailwinds.
End User:
Vertical applications impose distinct performance certifications and contamination sensitivity.
- Food & Beverage:FDA and EFSA compliance for direct and indirect food contact drives migration-tested resin selection and additive restrictions. Dairy distribution networks in the Netherlands require cold-temperature puncture resistance for condensation-prone refrigerated loads.
- Pharmaceuticals:EU GDP guidelines mandate tamper-evidence and chain-of-custody documentation for serialized drug shipments. Swiss cold-chain logistics providers specify anti-fog coated films for temperature-monitoring visibility.
- Retail:High-velocity fulfillment demands rapid-wrap cycle compatibility.
- Electronics:Electrostatic discharge protection requirements influence additive packages.
Food & Beverage commands the largest installed base; Pharmaceuticals shows the steepest specification escalation.
Packaging Type:
Layer architecture determines puncture resistance, optical clarity, and reprocessing feasibility.
- Multi-layer:Coextruded structures combining stiff outer layers with tacky inner surfaces optimize load containment and pallet adhesion. Belgium's port-proximate distribution clusters are adopting 5-layer cast films for cross-border automotive component flows, despite mechanical recycling contamination barriers.
- Single Layer:Monolayer blown films offer simpler reprocessing streams for closed-loop collection programs. German converters are maintaining monolayer capacity to serve post-industrial scrap recovery contracts.
- Decorative:Pigmented and surface-printed formats serve brand visibility requirements.
- Custom Printed:Logo and handling instruction integration reduces secondary labeling needs.
Multi-layer captures premium performance margins; Single Layer aligns with circular infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes pallet wraps through precision-engineered automotive logistics networks, while the United States absorbs volume through fragmented e-commerce fulfillment infrastructure. China deploys films primarily for export-oriented manufacturing consolidation, diverging from Europe's regulatory-driven circular economy focus.
Germany
Automotive parts distribution through Stuttgart and Wolfsburg generates specification-grade demand for puncture-resistant metallocene polyethylene films. The EU Packaging and Packaging Waste Regulation enforces recyclability thresholds that redirect converter investment toward post-consumer resin blends. The Ruhr industrial corridor hosts automated fulfillment centers standardizing on 12-23 micron cast stretch films for high-velocity lines.
United States
E-commerce fulfillment center expansion across Texas and Georgia accelerates automated stretch wrapping adoption, displacing manual banding with labor-cost compression targets. EPA Clean Air Act oversight regulates resin manufacturing emissions, while OSHA sets workplace exposure limits for volatile compounds during film extrusion. Gulf Coast petrochemical complexes concentrate polyethylene supply, exposing extruders to hurricane-related production interruptions.
China
Export manufacturing consolidation around Shenzhen and Dongguan drives bulk palletization demand for containerized shipping. MIIT industrial standards govern packaging material specifications for cross-border trade compliance. Yangtze River Delta logistics hubs are deploying multi-layer coextruded films for electronics export loads despite mechanical recycling contamination barriers.
France
Extended producer responsibility pre-compliance programs are piloting 30% recycled content stretch films among Paris-region logistics operators. ANSM and environmental regulators enforce packaging waste recovery targets ahead of EU mandate deadlines. The Île-de-France distribution cluster is centralizing procurement decisions for cross-border European flows through port-proximate warehousing.
Netherlands
Dairy distribution networks require cold-temperature puncture resistance for condensation-prone refrigerated loads across Rotterdam port logistics. EFSA compliance mandates migration-tested resin selection for indirect food contact applications. Dutch converters maintain monolayer capacity to serve post-industrial scrap recovery contracts with closed-loop collection infrastructure.
Pallet Wraps Market Competitive Environment
Capability concentration sits with resin-integrated multinationals; scale advantage sits with regional extrusion specialists. The vendor base stratifies into three tiers: integrated petrochemical-film producers commanding formulation IP, mid-scale converters leveraging geographic proximity to demand clusters, and commodity extruders competing on throughput economics. Dominant competitive moves include backward integration into post-industrial scrap collection infrastructure and multi-layer coextrusion line installation exceeding monolayer retrofit capital requirements.
Among North American resin-integrated producers, Dow Chemical Company and Berry Global occupy positions exemplifying the capability-tier archetype. Dow anchors technical innovation through metallocene polyethylene catalyst platforms, while Berry leverages collection infrastructure to control post-industrial scrap flows. Paragon Films and Intertape Polymer Group represent mid-scale regional specialists competing through geographic proximity to automotive and food distribution clusters. Sigma Plastics Group and Inteplast Group exemplify throughput-focused commodity extruders serving price-sensitive contract packaging segments.
| Leading Market Players |
|---|
| AEP Industries |
| Paragon Films |
| Berry Global |
| Amcor |
| Intertape Polymer Group |
| Sigma Plastics Group |
| Coveris |
| Dow Chemical Company |
| Inteplast Group |
| Others |
Value Chain & Pricing Dynamics
Gulf Coast petrochemical complexes anchor North American polyethylene supply, concentrating resin pricing power among integrated producers while exposing downstream film extruders to feedstock volatility without full pass-through mechanisms. Mega-fulfillment operators leverage consolidated procurement volumes to compress supplier rosters and extend contract durations, shifting margin capture toward logistics end-users.
Pricing Analysis
Long-term offtake contracts dominate procurement between resin-integrated film producers and large logistics operators, with spot purchasing confined to smaller converters serving intermittent-volume applications. Price differentiation rests on metallocene catalyst grade certification and post-consumer recycled content thresholds, with virgin resin formulations commanding premiums over mechanical-recyclable blends. Pricing pressure stems from crude oil derivative volatility swinging ethylene feedstock costs, while commodity extruders serving price-sensitive contract packaging segments exhibit highest buyer price sensitivity. Premium-grade automotive specification films show lowest elasticity as Stuttgart and Wolfsburg supply bases prioritize load failure avoidance over unit cost.
Supply Chain Analysis
Export-control regimes on advanced metallocene catalyst technology limit catalyst platform licensing flows from US and European patent holders to Chinese converters, constraining quality parity in Asia-Pacific production. Geographic supply concentrates in US Gulf Coast, Germany's industrial corridor, and China's Yangtze River Delta petrochemical hubs. Raw material dependencies center on ethylene and propylene feedstocks, naphtha cracking capacity, and catalyst precursor chemicals. Single-source vulnerability runs through hurricane-exposed Gulf Coast polyethylene complexes. Distribution runs through direct procurement portals operated by resin-integrated producers, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mega-fulfillment operators capable of justifying automated stretch wrapping capital deployment, fragmenting regional distributor influence and extending contract durations toward resin-integrated producers.
For Market Incumbents: Insulate margin pools through backward integration into post-industrial scrap collection infrastructure, capturing circular economy value streams previously retained by virgin resin suppliers. Expand metallocene catalyst platform capacity in Germany's Ruhr corridor to defend specification-grade automotive contracts against emerging hybrid material entrants. Prioritize REACH-compliant formulation roadmaps ahead of phthalate restriction enforcement timelines. For New Entrants and Emerging Players: Pursue white-space opportunities in French and Italian extended producer responsibility pre-compliance programs, where 30% recycled content stretch film pilots lack established converter relationships. Target Belgium and Netherlands port-proximate warehousing clusters with monolayer film offerings aligned to closed-loop collection infrastructure investment. Lead with sustainability certification bundling rather than price undercutting to bypass incumbent volume discounts. For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because post-industrial scrap collection networks and mechanical recycling contamination solutions will determine margin capture over virgin resin cycles. Acquisition targets should emphasize converters with backward-integrated collection infrastructure and multi-layer coextrusion line installation ahead of monolayer stranded capacity. Watch EU Packaging and Packaging Waste Regulation enforcement calibration as the inflection signal for recycled content premium viability.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Industrial Scrap Collection Infrastructure | Berry Global's captive control over North American scrap flows captures circular margin pools from virgin resin suppliers. |
| Metallocene Catalyst Platform Expansion | Dow Chemical's technical innovation anchor improves puncture resistance specifications for Stuttgart automotive distributors. |
| Multi-Layer Coextrusion Line Installation | Five-layer cast film adoption in Belgium's port clusters enables cross-border automotive component load containment. |
| Extended Producer Responsibility Pre-Compliance | French logistics operators piloting 30% recycled content films position ahead of EU mandate deadlines. |
| REACH-Compliant Formulation Roadmap | Phthalate-free polyethylene alternatives redirect investment from PVC-based wraps under ECHA restrictions. |
Study Parameters
A spread of perspectives from plant managers at film extrusion facilities, procurement leads at automotive and food distribution clusters, technical R&D directors at resin suppliers, and channel partners in European logistics networks converged on the working assumptions shaping demand elasticity and specification escalation. Secondary validation drew from customs and trade data tracking polyethylene resin flows, SEC 10-K filings of integrated petrochemical-film producers, Cefic plastics industry reports, and ECHA regulatory enforcement documentation. Bottom-up volume estimates triangulated against top-down resin consumption projections across the analysis window.
Demand-supply balance modeling anchored the forecast framework, with segmentation dimensions spanning product type, material architecture, end-use vertical, and packaging layer construction alongside regional production hub clustering. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trajectories incorporating downgauging trends and recycled content premium evolution. Industry-specific inputs included automated stretch wrapping equipment deployment rates in e-commerce fulfillment centers and EU regulatory compliance timeline assumptions.
Sensitivities concentrate around crude oil derivative volatility, hurricane-related Gulf Coast production interruptions, and mechanical recycling contamination breakthrough timelines. Forecasts reflect documented assumptions on resin price pass-through mechanisms and extended producer responsibility scheme adoption rates. Material shifts in EU recyclability mandate enforcement calibration or metallocene catalyst licensing regime changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
China Pallets Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Presswood Pallets Market