
 Pallet Packaging Market | 2026-2036
Pallet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Packaging Market Insights
A capital-intensity divergence between asset-heavy pooling networks and lightweight trading specialists is reorganizing competitive dynamics in pallet supply. Brambles Limited sustains the largest pooled pallet network through intensive capital deployment and tracking infrastructure. Cabka Group differentiates via in-house production of recycled plastic pallets, controlling resin-to-finished-product quality. PalletOne competes through regional manufacturing scale across the southeastern United States, leveraging proximity to food processing clusters.
Pallet packaging encompasses standardized load-bearing platforms constructed from wood, plastic, metal, or engineered fiber materials, typically measuring 48 by 40 inches in North American markets, designed for forklift entry and unitized goods transport. Wooden pallets retain dominant share in food and beverage applications due to low unit cost and repairability, though plastic pallets are displacing wood in pharmaceutical cold chains where washability and dimensional consistency prevent contamination. Composite material segments occupy narrow but high-margin niches in export logistics, where ISPM-15 heat treatment exemptions reduce customs friction.
The EPA regulates pallet manufacturing emissions under Clean Air Act wood combustion standards, while the EU F-Gas Regulation and REACH framework constrain plastic pallet resin chemistry and recycling certification requirements. FDA food contact rules and ISPM-15 phytosanitary standards jointly determine material eligibility for cross-border agricultural and pharmaceutical shipments. Stakeholders must monitor tightening extended producer responsibility laws in multiple jurisdictions, as these frameworks will increasingly mandate pallet take-back obligations and recycled content minimums.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a structural pivot toward reusable pallet pooling systems, compressing single-use wooden pallet demand while elevating capital requirements for tracking infrastructure and reverse logistics networks.
Growth Catalysts
- E-commerce fulfillment density:Fulfillment centers in Germany and the United States are driving pallet volume expansion through automated storage and retrieval systems requiring standardized platform dimensions.
- REACH compliance migration:Chemical manufacturers across the European Union are converting to plastic pallets to eliminate ISPM-15 heat treatment documentation for cross-border intra-EU shipments.
- Cold chain pharmaceutical expansion:Temperature-controlled biologics distribution is accelerating washability-certified plastic pallet adoption to prevent microbial contamination.
Market Restraints
- Resin price volatility:Virgin HDPE and PP feedstock costs fluctuate with crude oil indices, compressing margins for recycled plastic pallet producers dependent on post-industrial scrap.
- Regional hardwood supply concentration:Southern yellow pine harvesting in the southeastern United States faces competing demand from construction and furniture sectors.
- ISPM-15 enforcement inconsistency:Phytosanitary certificate recognition gaps between national plant protection organizations create customs delays for wooden pallet exporters.
Strategic Opportunities
- India manufacturing corridor penetration:The country's PLI scheme for logistics infrastructure is opening pallet pooling contracts with automotive component suppliers in Tamil Nadu and Gujarat.
- RFID-embedded pallet convergence:Integration of passive UHF tags with blockchain traceability protocols enables outcome-based rental pricing tied to trip visibility.
- Extended producer responsibility tailwinds:France's anti-waste law mandates pallet take-back obligations, creating service revenue streams for reverse logistics operators.
Industry Challenges
- Asset tracking technician scarcity:Pooling operators face recruitment gaps for IoT hardware deployment and fleet management software configuration.
- Multi-certification timeline compression:Simultaneous FDA food contact, EPA emissions, and EU F-Gas compliance requires 18-24 month product qualification cycles.
- Legacy WMS integration friction:ERP connectivity with proprietary pallet tracking platforms demands custom API development for mid-market 3PL customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Packaging Market |
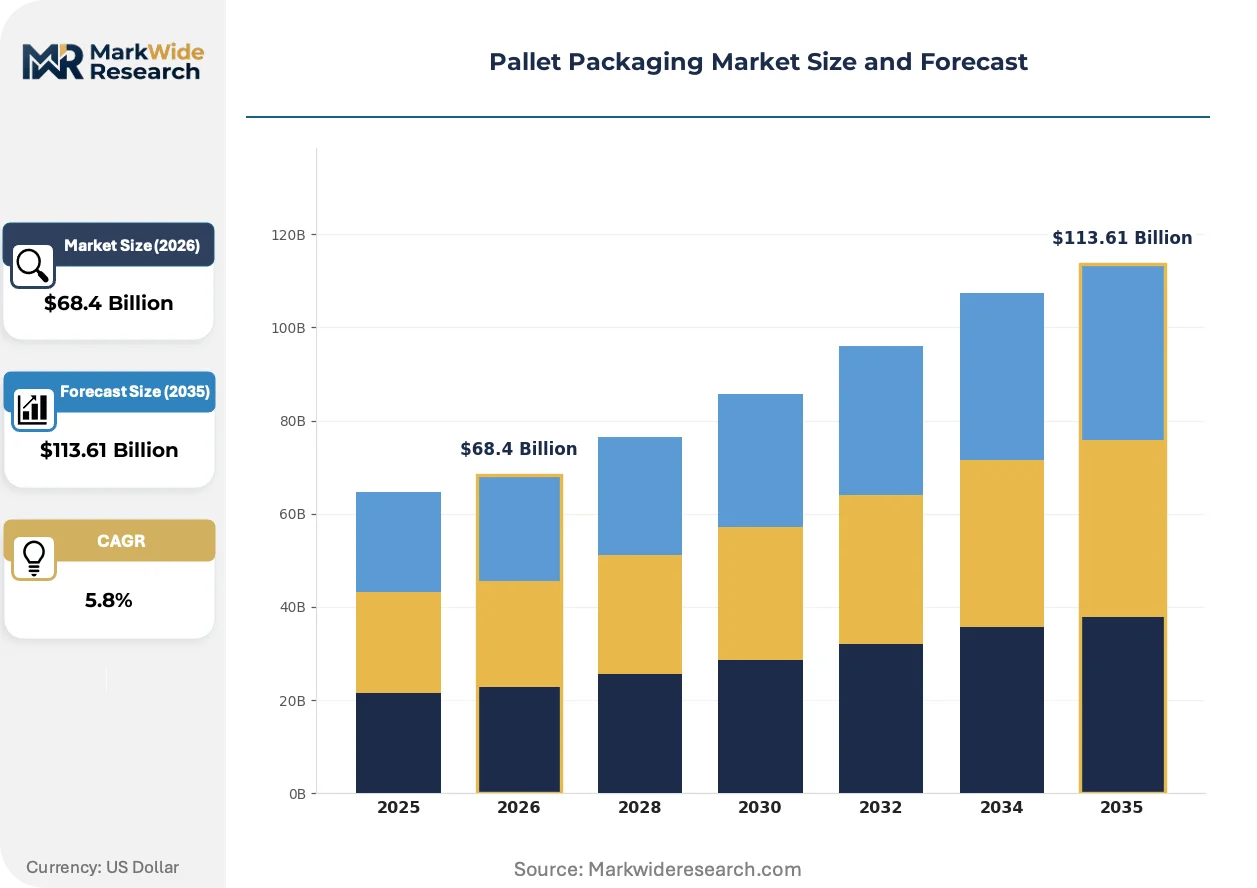
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Pallets, Plastic Pallets, Metal Pallets, Presswood Pallets, Corrugated Pallets Material: HDPE, PP, Steel, Bamboo, Composite Materials Application: Food & Beverage, Chemicals, Pharmaceuticals, Consumer Electronics, E-commerce, Agriculture End User: Manufacturers, Warehousing Providers, Logistics Operators, Retail Chains, Distributors |
| Companies Covered | Brambles Limited, PalletOne, Rehrig Pacific Company, Loscam, ORBIS Corporation, PECO Pallet, Cabka Group, Schoeller Allibert Group, Craemer Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Packaging Market Trends and Innovations
Active experimentation with embedded sensor networks and alternative resin formulations is fragmenting traditional material hierarchies while regulatory pressure compresses product lifecycles toward circularity.
RFID and GPS-enabled pallets are bifurcating the market between premium tracked assets for high-value pharmaceutical and aerospace supply chains and untagged commodity platforms for bulk agricultural distribution. Pharmaceutical 3PLs in Germany and Switzerland are deploying these systems for real-time temperature and location monitoring. The technology is bifurcating procurement patterns, with large pooling networks capturing long-term contracts while independent traders retreat to spot-market wooden pallet segments.
The EU F-Gas Regulation is constraining blowing agent chemistries in structural foam plastic pallets, forcing manufacturers toward physical foaming or solid-wall designs with higher material intensity. Producers serving cold chain applications face reformulation costs exceeding EUR 2 million per production line. German automotive suppliers are responding by consolidating purchases with vertically integrated resin compounders capable of certifying fluorinated gas-free supply chains.
Outcome-based rental contracts are displacing per-trip pricing in European food retail, with major grocers in France and the Netherlands paying only for pallets successfully completing full circulation cycles. This model transfers trip-loss risk to pooling operators while incentivizing asset recovery investment. The shift is most visible in fresh produce distribution, where seasonal volume spikes previously forced buyers into costly safety stock positions.
Pallet Packaging Market Segmentation
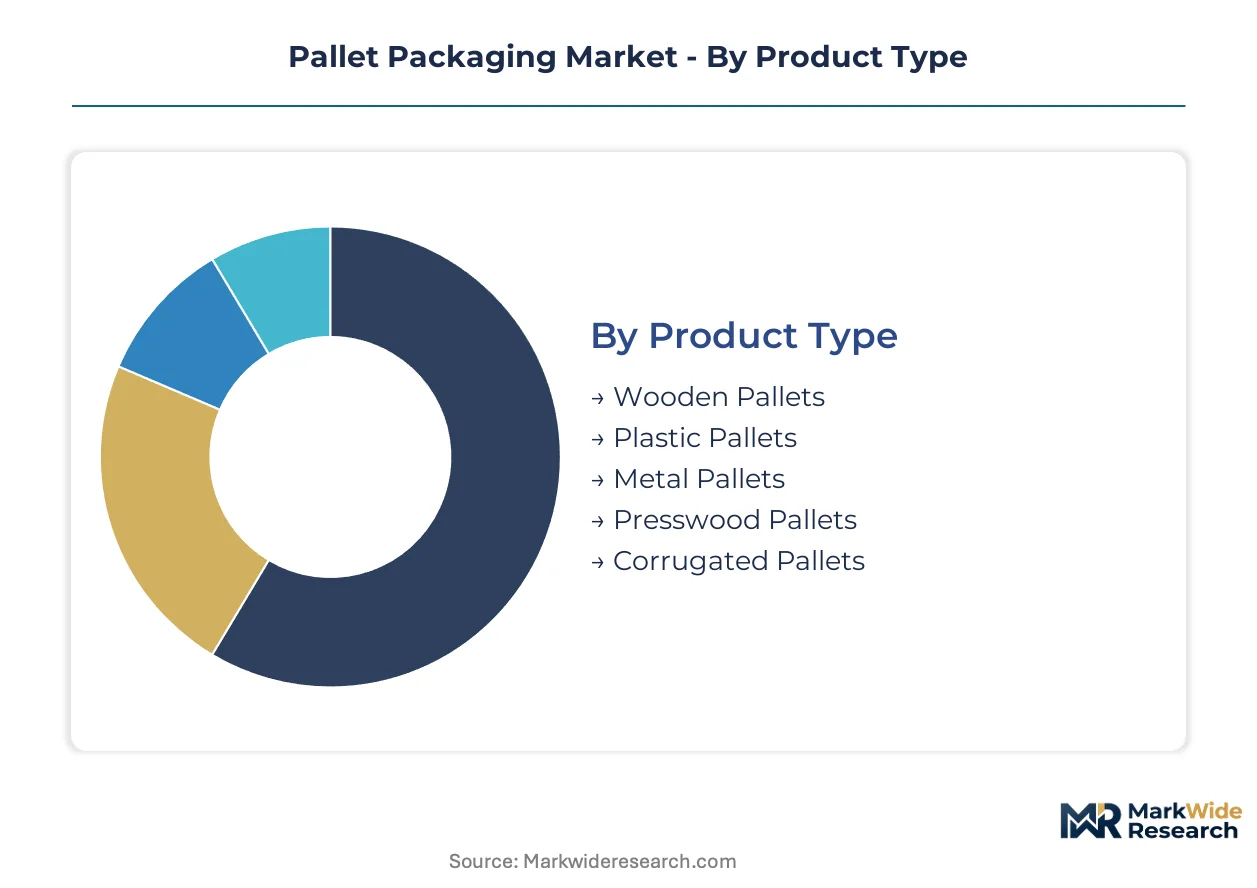
Pallet packaging segmentation reveals divergent capital requirements and regulatory exposure across material classes and end-use verticals. Procurement patterns in this market split sharply between asset-heavy pooling models and lightweight spot-market trading, with each segment carrying distinct compliance burdens and lifecycle economics.
Product Type:
Domestic circulation favors repairable formats, while export-oriented demand gravitates toward treatments and materials that clear phytosanitary barriers.
- Wooden Pallets:Southern yellow pine and oak construction dominates North American food and beverage logistics. Repairability and low unit cost sustain demand across domestic supply chains, though ISPM-15 heat treatment requirements add cost and documentation friction for cross-border shipments.
- Plastic Pallets:HDPE and PP injection-molded platforms are displacing wood in pharmaceutical cold chains across Germany and Switzerland. Washability and dimensional consistency prevent microbial contamination, while exemption from phytosanitary certification streamlines intra-European Union logistics for chemical manufacturers.
- Metal Pallets:Steel construction serves aerospace and heavy machinery sectors requiring extreme load ratings and fire resistance.
- Presswood Pallets:Engineered fiber compression molding offers ISPM-15 exemption without heat treatment, attracting export-heavy agricultural shippers.
- Corrugated Pallets:Lightweight paperboard construction addresses one-way lightweight freight in e-commerce fulfillment, though moisture sensitivity limits reuse cycles.
Wooden pallets hold the largest share; momentum sits with plastic pallets.
Material:
Resin chemistry and fiber sourcing determine regulatory compliance pathways and circularity credentials across production networks.
- HDPE:Virgin and post-industrial recycled high-density polyethylene dominates structural foam pallet production. REACH and EU F-Gas Regulation constraints on blowing agents are forcing reformulation investments exceeding two million euros per production line for cold chain suppliers.
- PP:Polypropylene offers superior chemical resistance for industrial chemical handling. Automotive component manufacturers in Tamil Nadu and Gujarat under India's PLI scheme are consolidating purchases with resin compounders capable of certifying fluorinated gas-free supply chains.
- Steel:Galvanized and stainless grades serve heavy-load and hygienic applications where pallet longevity exceeds material cost premiums.
- Bamboo:Rapid-renewable fiber sourcing appeals to sustainability-mandated procurement in European food retail.
- Composite Materials:Hybrid resin-fiber engineering occupies narrow export niches where ISPM-15 exemptions reduce customs friction.
HDPE captures the dominant volume position; PP is climbing the fastest on chemical sector conversion.
Application:
End-use verticals impose divergent performance specifications, from temperature integrity to contamination prevention.
- Food & Beverage:Washability requirements and FDA food contact rules drive material selection. Fresh produce distribution in France and the Netherlands is shifting to outcome-based rental contracts that transfer trip-loss risk to pooling operators.
- Chemicals:Spill containment and corrosion resistance prioritize plastic and sealed-construction formats. REACH compliance migration is accelerating plastic pallet adoption for cross-border intra-EU shipments.
- Pharmaceuticals:Temperature-controlled biologics distribution demands washability-certified platforms with dimensional consistency for automated storage systems.
- Consumer Electronics:ESD-sensitive components require conductive or static-dissipative pallet specifications.
- E-commerce:Fulfillment center automation in Germany and the United States requires standardized 48-by-40-inch platform dimensions for storage and retrieval system compatibility.
- Agriculture:Seasonal volume spikes and export orientation favor low-cost, ISPM-15-compliant formats for one-way international shipment.
Food and beverage maintains the largest installed base; pharmaceuticals shows the steepest expansion trajectory.
End User:
Customer scale and integration depth determine whether procurement flows through long-term pooling contracts or spot-market trading.
- Manufacturers:Automotive and chemical producers in Germany maintain high pallet circulation rates through captive pooling networks or intensive capital deployment in tracking infrastructure.
- Warehousing Providers:Third-party logistics operators face legacy WMS integration friction when connecting ERP systems to proprietary pallet tracking platforms.
- Logistics Operators:Asset-light trucking and freight forwarding specialists rely on spot-market wooden pallet sourcing for irregular lane coverage.
- Retail Chains:Major grocers in France are mandating take-back obligations under anti-waste law, creating service revenue streams for reverse logistics operators.
- Distributors:Mid-market wholesalers balance cost sensitivity against the administrative burden of multi-certification timelines for FDA, EPA, and EU compliance.
Manufacturers command the deepest pooling relationships; retail chains are driving the fastest contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pallet pooling networks in Germany command 15-20% rental premiums over spot-market wooden platforms in Poland, reflecting capital-intensity gaps and tracking infrastructure disparities across the European Union.
United States
Automated fulfillment centers in Georgia and Tennessee drive standardized 48-by-40-inch pallet volume through robotic storage and retrieval systems. EPA Clean Air Act wood combustion standards regulate domestic manufacturing emissions. PalletOne maintains southeastern manufacturing scale proximate to food processing clusters across Florida and the Carolinas.
Germany
Automotive and chemical manufacturers sustain the highest pallet circulation rates in Europe through captive pooling networks. EU F-Gas Regulation constrains structural foam blowing agents, forcing reformulation investments. Pharmaceutical 3PLs in Bavaria deploy RFID-enabled platforms for real-time temperature monitoring of biologics shipments.
China
E-commerce fulfillment density in the Yangtze River Delta and Pearl River Delta regions accelerates demand for standardized platforms compatible with automated warehouses. MIIT industrial standards govern plastic pallet structural specifications. Zhengzhou Shuli Machinery Co., Ltd. exemplifies domestic equipment fabricators serving logistics infrastructure expansion.
India
The PLI scheme for logistics infrastructure is opening pallet pooling contracts with automotive component suppliers. BIS certification requirements shape material eligibility for food contact and industrial applications. Tamil Nadu and Gujarat manufacturing corridors concentrate demand from electronics and automotive exporters seeking ISPM-15-compliant formats.
France
Major grocery retailers in Île-de-France mandate outcome-based rental contracts that transfer trip-loss risk to pooling operators. Anti-waste law obligations create reverse logistics service revenue streams. Fresh produce distribution networks in Provence-Alpes-Côte d'Azur shift from safety stock purchasing to circulation-cycle pricing models.
Pallet Packaging Market Competitive Landscape
Concentration sits with asset-heavy pooling operators deploying intensive capital in tracking infrastructure and reverse logistics networks. The vendor base spans three tiers: multinational pooling networks with proprietary fleet management systems, regional manufacturing specialists leveraging geographic proximity to end-use clusters, and spot-market traders sourcing untreated wooden platforms for irregular lane coverage. Dominant competitive moves include backward integration into resin compounding for plastic pallet producers and strategic partnerships between pooling operators and third-party logistics providers for WMS integration.
Within the multinational pooling tier, Brambles Limited and Loscam occupy positions defined by fleet scale and geographic coverage breadth. Among European-based specialists, Cabka Group exemplifies manufacturers with captive resin-to-product quality control. Rehrig Pacific Company anchors the North American regional manufacturing vector with southeastern U.S. production concentration. These three entities represent divergent strategic postures: capital-intensive network deployment, vertical manufacturing integration, and regional scale proximity.
| Leading Market Players |
|---|
| Brambles Limited |
| PalletOne |
| Rehrig Pacific Company |
| Loscam |
| ORBIS Corporation |
| PECO Pallet |
| Cabka Group |
| Schoeller Allibert Group |
| Craemer Holding GmbH |
| Others |
Pricing and Supply Chain Analysis
Plastic pallet displacement of wooden platforms in pharmaceutical cold chains simultaneously redraws supply geography toward German resin compounders and compresses price premiums for washability-certified formats. This substitution dynamic concentrates pricing power with vertically integrated producers while spot-market wooden pallet traders face margin erosion from ISPM-15 documentation costs.
Pricing Analysis
The customization-premium spread between RFID-embedded tracked assets and untagged commodity platforms spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade (FDA food contact, ISPM-15 phytosanitary) and volume scale, with large pooling networks capturing long-term contract premiums. Cost compression in economy-tier wooden segments is intensifying because southern yellow pine supply competes with construction sector demand. Small distributors exhibit highest price sensitivity, while pharmaceutical 3PLs prioritize contamination prevention over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asia-Europe container congestion and Red Sea route disruptions are elevating landed costs for HDPE resin feedstock. Supply concentrates in Germany, China, and the southeastern United States, with production drawing from virgin petroleum derivatives, post-industrial recycled scrap, and regional hardwood harvests. Single-source vulnerability sits with specialized resin compounders certifying fluorinated gas-free supply chains under EU F-Gas Regulation. Distribution runs through asset-heavy pooling networks for high-volume manufacturers and spot-market traders for irregular lane coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet packaging demand tracks the automotive and e-commerce capital expenditure cycle, with German automotive production rates and US fulfillment center buildouts serving as lead indicators. Recovery positioning favors operators with captive resin supply or established pooling network density.
For Market Incumbents: Compound network density through targeted capacity addition in Tamil Nadu and Gujarat manufacturing corridors where India's PLI scheme concentrates automotive component demand. Prioritize backward integration into resin compounding to defend margins against virgin HDPE price volatility. Certify fluorinated gas-free production lines ahead of EU F-Gas Regulation enforcement timelines to capture chemical manufacturer conversion demand.
For New Entrants and Emerging Players: Anchor in outcome-based rental contract servicing for French grocery retailers mandated by anti-waste law take-back obligations. The most penetrable white space sits with mid-market 3PLs facing legacy WMS integration friction with proprietary pooling platforms. Lead with API-first tracking infrastructure that reduces ERP connectivity deployment cycles versus incumbent proprietary systems.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional manufacturing specialists in southeastern US food processing corridors. Long-term viability across the next decade hinges on circularity infrastructure and extended producer responsibility compliance capabilities. Watch for inflection when France, Germany, and Netherlands mandate minimum recycled content thresholds that disqualify virgin-only producers from retail chain contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Blockchain Traceability Integration | Enables outcome-based rental pricing tied to trip completion visibility for pharmaceutical 3PLs. |
| Resin Compounding Backward Integration | Captures margin from HDPE feedstock volatility while certifying EU F-Gas Regulation compliance. |
| India Manufacturing Corridor Expansion | Positions pooling operators for PLI scheme automotive contracts in Tamil Nadu and Gujarat. |
| Legacy WMS API Development | Reduces integration friction for mid-market 3PLs currently excluded from proprietary tracking platforms. |
| Extended Producer Responsibility Infrastructure | Creates reverse logistics revenue streams under French anti-waste law and impending EU-wide mandates. |
Research Methodology
Desk research of trade association publications, customs and logistics infrastructure databases, and regulatory filing repositories preceded structured interviews with pooling network operations directors, resin compounding technical leads, pharmaceutical 3PL procurement managers, and food retail supply chain planners. Primary fieldwork combined with secondary validation from EPA emissions disclosures, EU ECHA substance registrations, and India BIS certification records. Bottom-up pallet volume modeling by end-use vertical and material class triangulated against top-down logistics infrastructure investment forecasts.
Variance decomposition across material substitution rates, e-commerce fulfillment center automation adoption, and regulatory compliance timeline shifts shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include material class, product type, application vertical, end-user scale tier, and regional regulatory cluster. CAGRs derived from logistic curve fitting to historical pooling network expansion patterns, with specific inputs including German automotive production indices and US southeastern food processing employment data.
Decision-makers should treat outputs as directional under assumptions of sustained EU Packaging and Packaging Waste Regulation enforcement and stable India PLI scheme logistics infrastructure allocations; material deviation would warrant model refresh. Specific risk factors include ISPM-15 enforcement inconsistency between national plant protection organizations and resin price volatility exceeding historical bands. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Corrugated Pallet Wrap Market