
 Europe Pallet Wrapping Machine Market | 2026-2036
Europe Pallet Wrapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pallet Wrapping Machine Market Insights
Equipment leasing and pay-per-wrap service contracts are narrowing the competitive field in Europe's pallet wrapping machine sector. Robopac leverages its Aetna Group parent infrastructure to sustain manufacturing scale across Italian and German plants. Signode Industrial Group anchors its position through steel and plastic strapping integration that complements wrapping workflows. TOSA Group differentiates by specializing in custom-engineered turntable and rotary arm configurations for mid-volume European manufacturers.
A pallet wrapping machine applies stretch film, shrink film, or protective covers around palletized loads using motorized turntables, rotary arms, or robotic gantries, typically achieving 150-300% pre-stretch ratios to minimize material consumption while securing goods for transport and storage. Automatic systems dominate installed base value in high-throughput food and beverage facilities where line integration demands consistent cycle speeds. Semi-automatic configurations retain structural importance in pharmaceuticals and consumer goods operations with lower volume variability and limited capex budgets. Robotic wrapping cells represent the fastest-growing technology category as warehousing verticals pursue flexible end-of-line automation that adapts to mixed pallet sizes without mechanical changeover.
The EU Machinery Directive and CE marking requirements govern equipment safety and electromagnetic compatibility across all member states, while REACH and the F-Gas Regulation constrain film chemistry and sealing technology choices available to machine builders. Germany's KBA and France's CNIL indirectly shape market access through packaging waste traceability mandates and industrial data handling standards that wrapping systems must support. Stakeholders should monitor how the EU Green Deal's evolving extended producer responsibility frameworks will alter total cost-of-ownership calculations for film-based versus reusable pallet containment systems.
Market Dynamics
Automated warehouse expansion across Europe's logistics corridor is compressing equipment replacement cycles, as fulfillment operators demand pallet wrapping systems that integrate directly with WMS platforms and robotic palletizing cells.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclate content thresholds are accelerating converter investment in high-efficiency stretch film systems capable of processing post-industrial regrind without throughput loss.
- Food and beverage distribution:Germany's cold chain expansion and France's dairy export growth are driving demand for automated turntable configurations with washdown-rated enclosures.
- Pre-stretch film technology:Motorized film carriages achieving 250-300% elongation ratios are cutting material consumption per pallet by one-third versus legacy mechanical braking systems.
Market Restraints
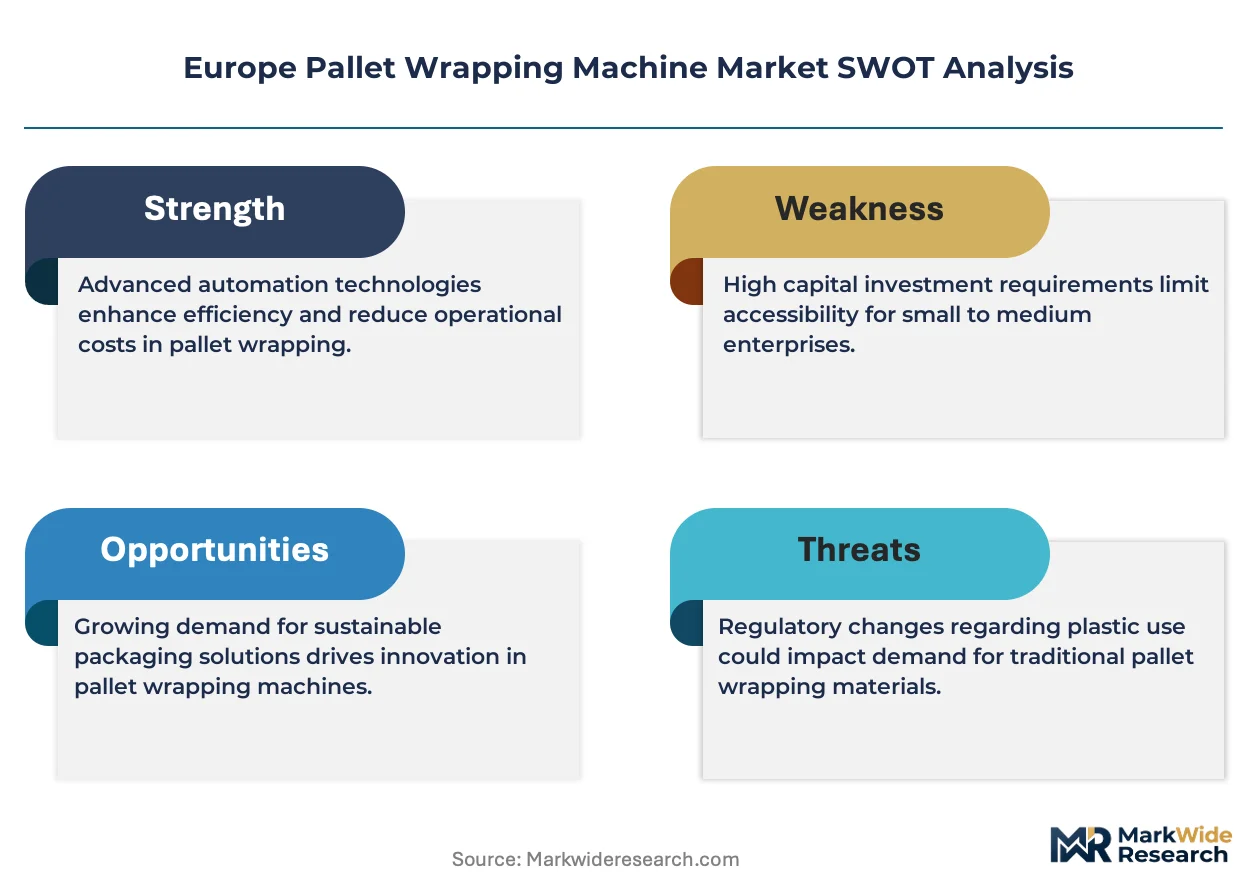
- Steel and aluminum input volatility:Rotary arm fabrication costs fluctuate with commodity pricing, compressing margin visibility for mid-volume equipment manufacturers.
- CE marking compliance timeline:Machinery Directive conformity assessment delays of 4-6 months are extending order-to-delivery intervals and straining working capital.
- Reusable pallet containment systems:Strapping and banding alternatives are capturing share in closed-loop automotive component logistics where film waste incurs extended producer responsibility surcharges.
Strategic Opportunities
- Italy's pharmaceutical corridor:Turin and Milan packaging hubs show underpenetrated demand for semi-automatic rotary arm systems with cleanroom-compatible finishes.
- Pay-per-wrap service contracts:Leasing models with bundled film supply are opening access to SME food processors previously priced out of automatic system ownership.
- EU Green Deal carbon border adjustments:Domestic equipment manufacturers gain cost advantage over Asian imports as embedded emissions reporting becomes mandatory for machinery procurement.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven pre-stretch carriage maintenance requires specialized skill sets that vocational training pipelines in Eastern Europe have not scaled to match equipment deployment.
- Legacy PLC integration:Brownfield warehouse automation projects face protocol incompatibility between 1990s-era control architectures and modern Ethernet/IP wrapping cell controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pallet Wrapping Machine Market |
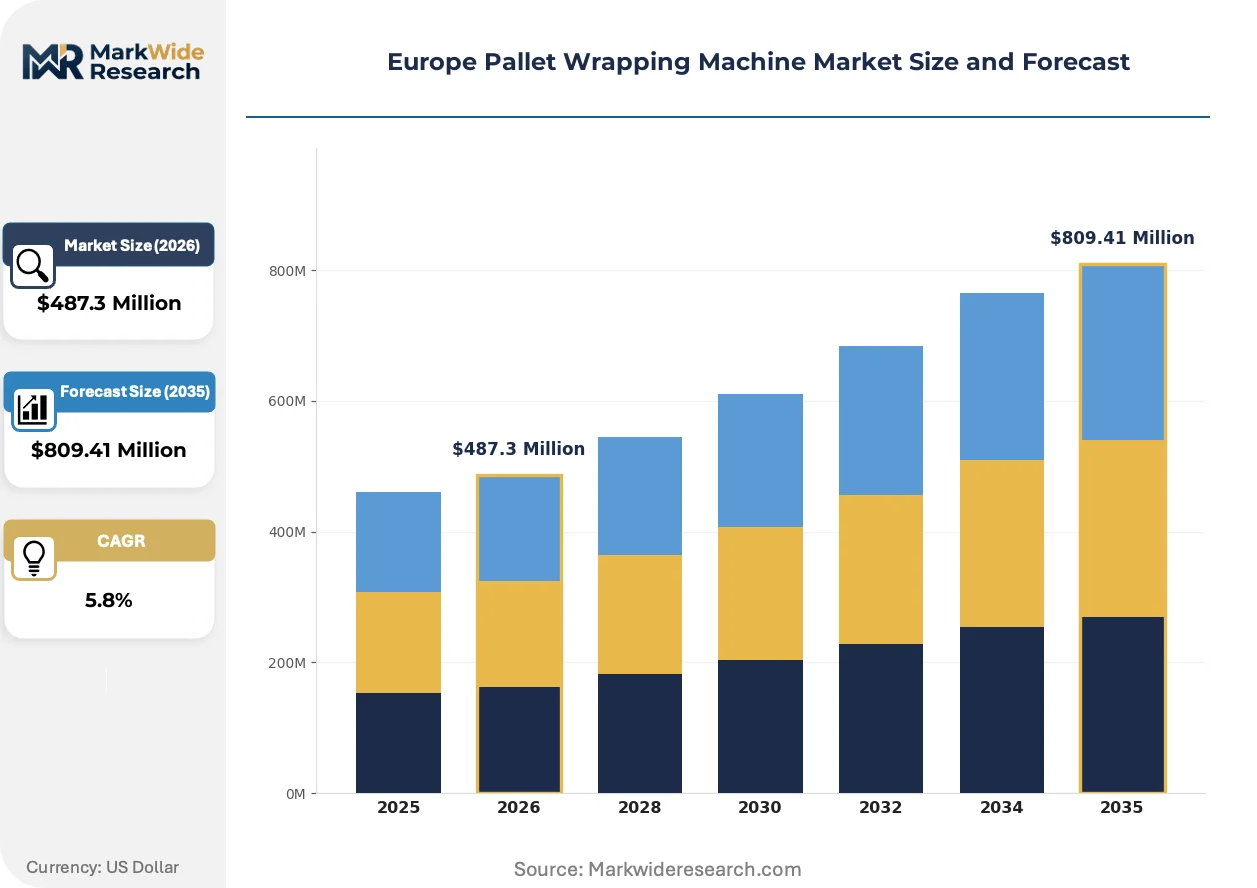
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Automatic, Semi-Automatic, Manual, Robotic End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Logistics Technology: Stretch Film, Shrink Film, Pallet Covers, Others Industry Vertical: Manufacturing, Retail, Warehousing, Export |
| Companies Covered | Robopac (Aetna Group SPA), Signode Industrial Group LLC, TOSA Group, Officina Meccanica Sestese S.p.A. (OMS Group), Muller LCS, Siat S.p.A., Strema Maschinenbau GmbH, Matco International Holding BV, Cyklop UK Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pallet Wrapping Machine Market Trends and Innovations
Machine learning-enabled film tension control and collaborative robotic loading are converging to reshape end-of-line automation economics. Three developments warrant particular attention.
Vision-guided robotic wrapping cells with adaptive gripper technology are rendering obsolete fixed-format turntable systems in e-commerce fulfillment centers. German third-party logistics operators are deploying these configurations for mixed-SKU pallet consolidation where SKU variability exceeds 500 units per shift. The technology compresses changeover downtime from 15 minutes to under 30 seconds.
REACH restrictions on phthalate plasticizers are forcing film formulation shifts that demand heated pre-stretch rollers and modified sealing jaws. Machine builders serving the French fresh produce export sector are retrofitting existing rotary arm platforms with temperature-controlled film paths to accommodate bio-based stretch materials with narrower processing windows.
Consolidated buying by pan-European grocery retailers is compressing equipment specification diversity. Procurement teams at centralized distribution centers in the Netherlands and Belgium are mandating common HMI interfaces and spare part interchangeability across multi-site footprints, forcing smaller Italian and Spanish manufacturers toward modular platform architectures or private-label supply relationships.
Europe Pallet Wrapping Machine Market Segmentation
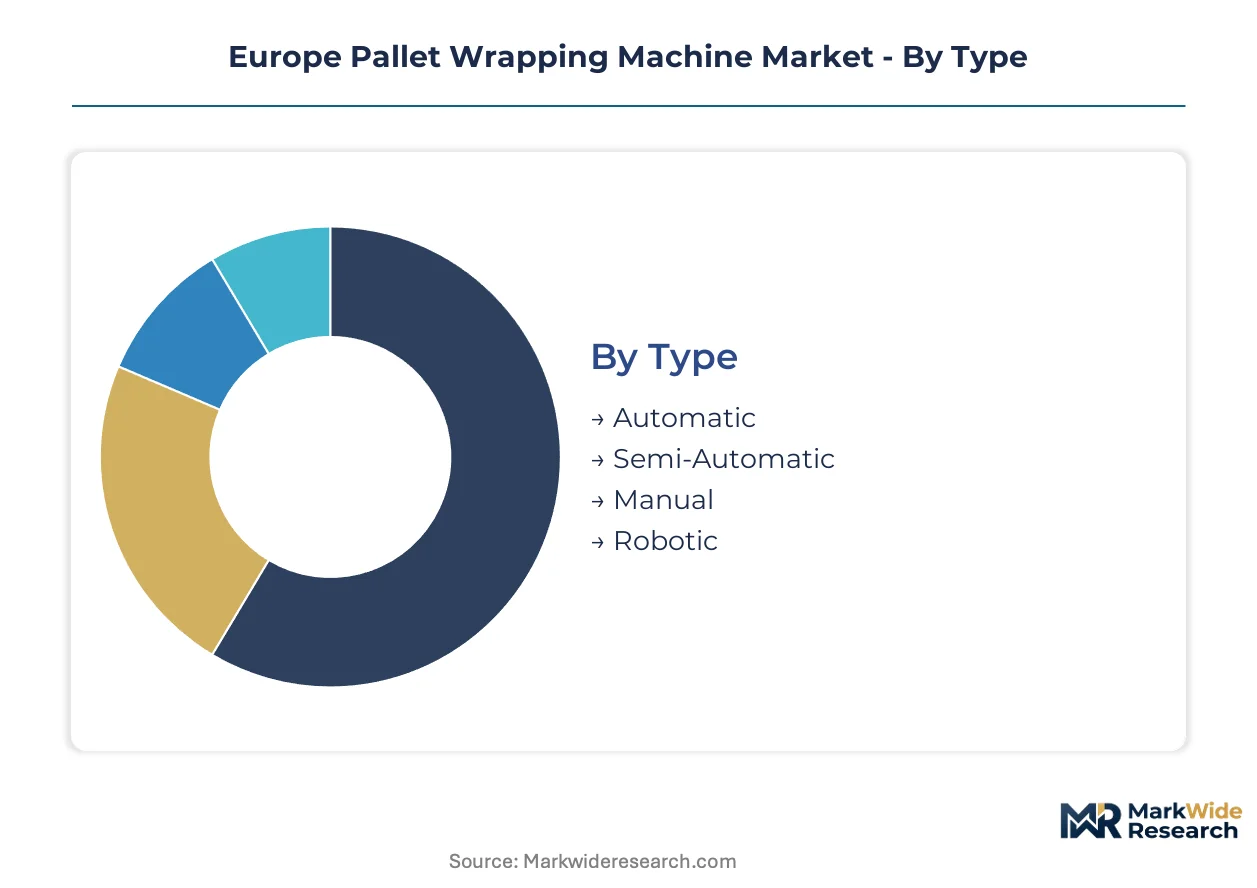
Equipment specification diversity in Europe's pallet wrapping sector reflects divergent throughput requirements and capex constraints across end-use verticals. Segment boundaries blur as semi-automatic platforms gain servo-driven capabilities and robotic cells penetrate mid-volume applications previously served by turntable systems.
Type:
Replacement cycles vary dramatically by automation tier, with high-throughput automatic systems turning over every 7-9 years while manual equipment persists for 15+ years in low-volume operations.
- Automatic:Turntable and rotary arm configurations with integrated conveyor interfaces dominate German food and beverage distribution centers where line speeds exceed 40 pallets per hour. Cold chain operators in France specify washdown-rated enclosures and stainless steel construction to meet dairy export sanitation protocols.
- Semi-Automatic:Operator-attended turntable systems with powered pre-stretch carriages serve Italian pharmaceutical packaging hubs where batch variability and validation requirements slow full automation adoption. These configurations balance labor input with film efficiency gains from 250% elongation ratios.
- Manual:Hand-held dispensers and mobile wrapping carts persist in small-scale German craft food producers and French agricultural cooperatives with seasonal volume spikes below 20 pallets daily.
- Robotic:Vision-guided gantry systems with adaptive end-effectors are penetrating Dutch e-commerce fulfillment centers where SKU diversity exceeds 500 units per shift and mechanical changeover becomes prohibitive.
Automatic systems dominate installed base value across Europe's logistics corridor. Robotic configurations are where expansion concentrates as warehousing verticals pursue flexible end-of-line automation.
End User:
Procurement sophistication varies by vertical, with pharmaceutical buyers emphasizing validation documentation and logistics operators prioritizing WMS integration speed.
- Food & Beverage:German dairy processors and French meat exporters drive demand for high-speed rotary arm systems with modified atmosphere compatibility. REACH restrictions on film plasticizers are forcing heated pre-stretch retrofits to process bio-based stretch materials.
- Pharmaceuticals:Turin and Milan packaging hubs source semi-automatic rotary arm systems with cleanroom-compatible finishes and IQ/OQ/PQ documentation packages for EU GMP compliance.
- Consumer Goods:Italian cosmetics manufacturers and Spanish household product distributors favor compact turntable configurations with quick-change film carriages for frequent SKU transitions.
- Logistics:Third-party operators in Belgium and the Netherlands specify common HMI architectures across multi-site footprints to reduce technician training burden and spare part inventory.
Food and beverage anchors equipment volume across the region. Pharmaceuticals is where margin expansion concentrates due to validation premiums and specification stickiness.
Technology:
Material chemistry constraints under REACH and the EU Packaging and Packaging Waste Regulation are reshaping equipment compatibility requirements faster than mechanical platform turnover.
- Stretch Film:Cast and blown film systems with motorized pre-stretch carriages achieving 300% elongation dominate German automotive component export operations. The EU Green Deal's extended producer responsibility frameworks are accelerating investment in high-recyclate-content film processing capability.
- Shrink Film:Heat tunnel and radiant sealing configurations serve French fresh produce export packers requiring hermetic moisture barriers for long-haul distribution to Middle Eastern markets.
- Pallet Covers:Hooding systems with gusseted polyethylene or woven PP enclosures capture share in Italian ceramic tile and building materials logistics where puncture resistance exceeds stretch film capability.
- Others:Strapping integration and banding alternatives are displacing film in closed-loop German automotive supply chains where waste minimization targets override material cost considerations.
Stretch film commands the largest installed base. Shrink film applications are expanding most quickly in temperature-sensitive export verticals.
Industry Vertical:
Facility age and automation maturity create divergent equipment specification patterns across verticals, with brownfield manufacturing sites facing legacy PLC integration constraints.
- Manufacturing:German industrial goods producers integrate wrapping cells directly with robotic palletizing systems via EtherNet/IP protocols, though 1990s-era control architectures in Eastern European plants require gateway retrofits.
- Retail:Centralized grocery distribution centers in the Netherlands mandate spare part interchangeability across pan-European footprints, forcing Italian and Spanish equipment suppliers toward modular platform standardization.
- Warehousing:Automated storage and retrieval system integration drives demand for wrapping cells with WMS handshake capability and cycle time synchronization to crane retrieval rates.
- Export:French and Italian freight forwarders specify equipment with multi-language HMI interfaces and CE marking documentation packages for rapid customs clearance in destination markets.
Manufacturing holds the deepest installed base. Warehousing is where technology refresh concentrates as automation investments compress replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators and food processors concentrate equipment procurement across Germany, France, and Italy's industrial corridors. Cold chain expansion and export compliance requirements drive specification diversity.
Germany
Dairy processors and meat exporters demand high-speed rotary arm systems with washdown-rated stainless steel enclosures. KBA packaging waste traceability mandates require machine builders to integrate data logging for extended producer responsibility reporting. The North Rhine-Westphalia logistics corridor hosts automated distribution centers where WMS-integrated wrapping cells synchronize with robotic palletizing operations.
France
Fresh produce export packers and dairy cooperatives drive demand for modified atmosphere-compatible stretch film systems. CNIL industrial data handling standards constrain HMI architecture choices for equipment serving pharmaceutical logistics. The Île-de-France freight forwarding cluster specifies multi-language interfaces and CE documentation packages for rapid customs clearance in Middle Eastern destination markets.
Italy
Pharmaceutical packaging hubs in Turin and Milan source semi-automatic rotary arm configurations with cleanroom-compatible finishes. REACH phthalate restrictions force heated pre-stretch retrofits to process bio-based stretch materials with narrow processing windows. Lombardy's cosmetics manufacturers favor compact turntable systems with quick-change film carriages for frequent SKU transitions.
Netherlands
Pan-European grocery retailers operating centralized distribution centers mandate common HMI interfaces and spare part interchangeability across multi-site footprints. EU Green Deal carbon border adjustments favor domestic equipment procurement over Asian imports as embedded emissions reporting becomes mandatory. The Randstad logistics cluster deploys vision-guided robotic wrapping cells for mixed-SKU e-commerce fulfillment.
Belgium
Third-party logistics operators specify wrapping systems with WMS handshake capability and cycle time synchronization to AS/RS crane retrieval rates. CE marking conformity assessment timelines extend order-to-delivery intervals, straining working capital for mid-volume equipment buyers. The Antwerp-Brussels industrial corridor concentrates pharmaceutical and consumer goods distribution automation investments.
Europe Pallet Wrapping Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Europe's pallet wrapping machine sector. Equipment leasing platforms and film-supply bundling arrangements concentrate procurement relationships among integrated service providers. Three archetypes dominate: Italian-German manufacturing conglomerates with captive distribution networks, mid-scale specialists in custom-engineered configurations, and steel/plastic strapping integrators offering complementary containment workflows. Competitive dynamics center on pay-per-wrap service contract expansion and modular platform standardization for pan-European spare part interoperability.
Among Italian manufacturing groups, Robopac (Aetna Group SPA) and OMS Group exemplify vertically integrated infrastructure spanning domestic and German production assets. Signode Industrial Group LLC represents the strapping-integration archetype, occupying a position where steel and plastic banding workflows complement film-based containment. TOSA Group anchors the custom-engineering tier, specializing in turntable and rotary arm configurations for mid-volume European manufacturers with specification-intensive requirements. These three entities collectively illustrate how geographic manufacturing footprint and service-model innovation shape competitive positioning.
| Leading Market Players |
|---|
| Robopac (Aetna Group SPA) |
| Signode Industrial Group LLC |
| TOSA Group |
| Officina Meccanica Sestese S.p.A. (OMS Group) |
| Muller LCS |
| Siat S.p.A. |
| Strema Maschinenbau GmbH |
| Matco International Holding BV |
| Cyklop UK Limited |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Italian and German component fabrication plants is compressing margin visibility for mid-volume equipment builders, forcing selective price discipline on rotary arm configurations while stretching payment terms for steel-intensive assemblies.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate procurement between equipment builders and German automotive logistics operators. Pricing stratifies across premium servo-driven systems with 300% pre-stretch capability, standard electromechanical turntable configurations, and economy-tier manual equipment for seasonal agricultural users. Cost compression in mid-automation tiers is intensifying because pan-European grocery retailers mandate spare part interchangeability across multi-site footprints. SME food processors in Southern Europe exhibit highest price sensitivity, while pharmaceutical packaging hubs in Northern Italy prioritize validation documentation over unit economics.
Supply Chain Analysis
Tariff exposure between Chinese servo motor suppliers and European machine builders dominates supply chain risk planning for automated wrapping cell manufacturers. Component sourcing concentrates in Germany for precision gearboxes, Italy for stainless steel fabrication, and China for servo drives and HMI panels. Raw material dependencies span cold-rolled steel for rotary arm structures, engineered polymers for film carriages, and copper windings for pre-stretch motors. Distribution runs through captive service networks of Aetna Group and Signode Industrial Group, supplemented by independent distributors serving Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pan-European logistics operators as consolidated procurement teams at centralized distribution centers capture volume leverage over fragmented equipment suppliers.
For Market Incumbents: Build switching-cost moats through pay-per-wrap service contracts with bundled film supply and predictive maintenance telemetry. Robotic wrapping cells with WMS integration capability represent the priority R&D vector. Defensive consolidation should target aftermarket service networks in the Netherlands and Belgium to preempt independent distributor encroachment. For New Entrants and Emerging Players: Semi-automatic rotary arm systems for Italian pharmaceutical packaging hubs with cleanroom-compatible finishes represent the most penetrable entry point. Leasing platforms with film-supply bundling open access to SME food processors previously priced out of automatic system ownership. Go-to-market execution should anchor on CE marking compliance acceleration to compress order-to-delivery intervals versus incumbent timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic wrapping cell manufacturing as vision-guided gantry systems displace fixed-format turntable platforms. Long-term viability favors equipment builders with captive film formulation partnerships and modular platform architectures supporting pan-European spare part interchangeability. Monitor German KBA packaging waste traceability mandate implementation as an inflection signal for data-logging capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Pay-per-Wrap Service Contract Expansion | Leasing models with bundled film supply capture SME food processors in Italy and Spain. |
| Robotic Wrapping Cell Development | Vision-guided gantry systems address Dutch e-commerce fulfillment SKU diversity exceeding 500 units per shift. |
| CE Marking Compliance Acceleration | Conformity assessment timeline compression differentiates against 4-6 month incumbent delivery intervals. |
| Modular Platform Standardization | Spare part interchangeability satisfies Netherlands grocery retailer centralized procurement mandates. |
| Heated Pre-Stretch Retrofit Capability | Temperature-controlled film paths accommodate REACH-compliant bio-based stretch materials for French produce exporters. |
Research Methodology
Desk research of EU regulatory filings, machinery trade association datasets, and customs import records preceded structured interviews with plant engineers at German food and beverage distribution centers, procurement leads at French dairy cooperatives, aftermarket service heads at Italian equipment manufacturers, and maintenance directors at Dutch third-party logistics operators. Primary intelligence combined with secondary validation from ECHA REACH substance registrations, KBA packaging waste traceability guidelines, and CE marking conformity assessment databases. Bottom-up equipment shipment analysis and top-down end-use demand estimation were triangulated against operating metrics disclosed in industrial automation sector filings.
Assumptions regarding EU Packaging and Packaging Waste Regulation enforcement timelines, steel input price volatility bands, and automation adoption rates in Eastern European warehousing were held fixed across baseline scenarios while varying robotic cell penetration speed and pay-per-wrap contract uptake in sensitivity analyses. Segmentation modeling spanned automation tier, end-use vertical, film technology type, and country-level regulatory cluster. CAGRs were derived from installed base turnover analysis and replacement cycle compression observed across Germany's logistics corridor. Forecast inputs included warehouse automation capex intentions from pan-European grocery retailers and pharmaceutical packaging hub expansion plans in Turin and Milan.
Macroeconomic conditions sit as an overlay; deviation in Eurozone industrial production indices, steel commodity pricing, or Eastern European labor cost inflation would shift the trajectory for mid-volume equipment demand. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Corrugated Pallet Wrap Market