
 Italy Plastic Bottles Market | 2026-2036
Italy Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Plastic Bottles Market Insights
Buyer concentration among Italian beverage bottlers is hardening as multinational drink brands reduce their approved supplier lists to secure volume discounts and quality consistency. Alpla Group leverages its integrated preform-to-bottle manufacturing footprint across Northern Italy to capture these consolidated accounts. Berry Global Inc. sustains competitive tension through specialized barrier technologies for sensitive beverages. Bormioli Pharma SpA anchors the pharmaceutical end-use segment with certification-heavy production that smaller converters cannot replicate.
Italy plastic bottles are hollow container structures extrusion- or injection-blow-molded from thermoplastic resins, typically engineered with wall thickness between 0.25 mm and 1.5 mm and thread finishes standardized to DIN or GPI neck specifications for cap compatibility. PET dominates volume production due to its clarity, barrier performance, and compatibility with existing Italian recycling infrastructure collected through CONAI-managed schemes. HDPE bottles for household and personal care applications carry thicker walls and chemical resistance that command margin premiums over commodity PET water bottles. The refillable packaging type retains structural importance in Italian mineral water culture, where returnable formats still circulate through dedicated retail channels.
CONAI's packaging fee modulation, the EU Single-Use Plastics Directive as transposed into Italian law through Legislative Decree 196/2021, and BIS-equivalent UNI standards for food contact materials collectively reshape material selection and design obligations for domestic producers. These frameworks penalize virgin plastic use while creating compliance moats around converters with certified recycling streams and testing documentation. Stakeholders must monitor how Italy's upcoming implementation of revised EU Packaging and Packaging Waste Regulation alters minimum recycled content thresholds and reuse targets before committing to capacity expansion or material platform shifts.
Market Dynamics
CONAI's packaging fee modulation and the EU Single-Use Plastics Directive transposition through Legislative Decree 196/2021 are restructuring material economics across Italian converter operations, forcing rapid rPET integration while compressing margins on virgin resin-dependent production lines.
Growth Catalysts
- Extended Producer Responsibility:CONAI's fee modulation incentivizes converters to source certified recycled feedstock, creating first-mover advantages for facilities with verified recycling streams.
- Beverage Industry Consolidation:Multinational drink brands are shrinking approved supplier lists, rewarding Northern Italian converters with integrated preform-to-bottle capabilities and scale economies.
- Barrier Technology Advancement:Oxygen-scavenging and multilayer co-injection systems are unlocking premium applications in sensitive beverages and functional drinks.
Market Restraints
- rPET Supply Bottleneck:Food-grade recycled pellet availability remains constrained by Italy's collection infrastructure gaps and contamination rates in post-consumer bales.
- Energy Cost Volatility:Natural gas and electricity price swings disproportionately impact blow-molding operations in Lombardy and Emilia-Romagna manufacturing clusters.
- Substitute Material Pressure:Glass returnable formats retain cultural preference in Italian mineral water channels, limiting PET penetration in high-margin premium segments.
Strategic Opportunities
- Pharmaceutical Certification Gap:UNI standards for food contact materials and pharma-grade compliance create defensible moats for converters investing in cleanroom blow-molding capacity.
- Cosmetic Brand Proximity:Milan and Bologna headquarters clusters enable just-in-time supply relationships with beauty and personal care brands seeking localized packaging partners.
- Refillable Infrastructure Modernization:Returnable bottle washing and tracking systems present retrofit opportunities as retailers expand deposit-return schemes.
Industry Challenges
- Technical Workforce Scarcity:Blow-molding process engineers and rPET quality technicians are in short supply across Northern Italy's industrial districts.
- Compliance Documentation Burden:CONAI recycling certification and BIS-equivalent UNI testing protocols extend product approval timelines for new material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Plastic Bottles Market |
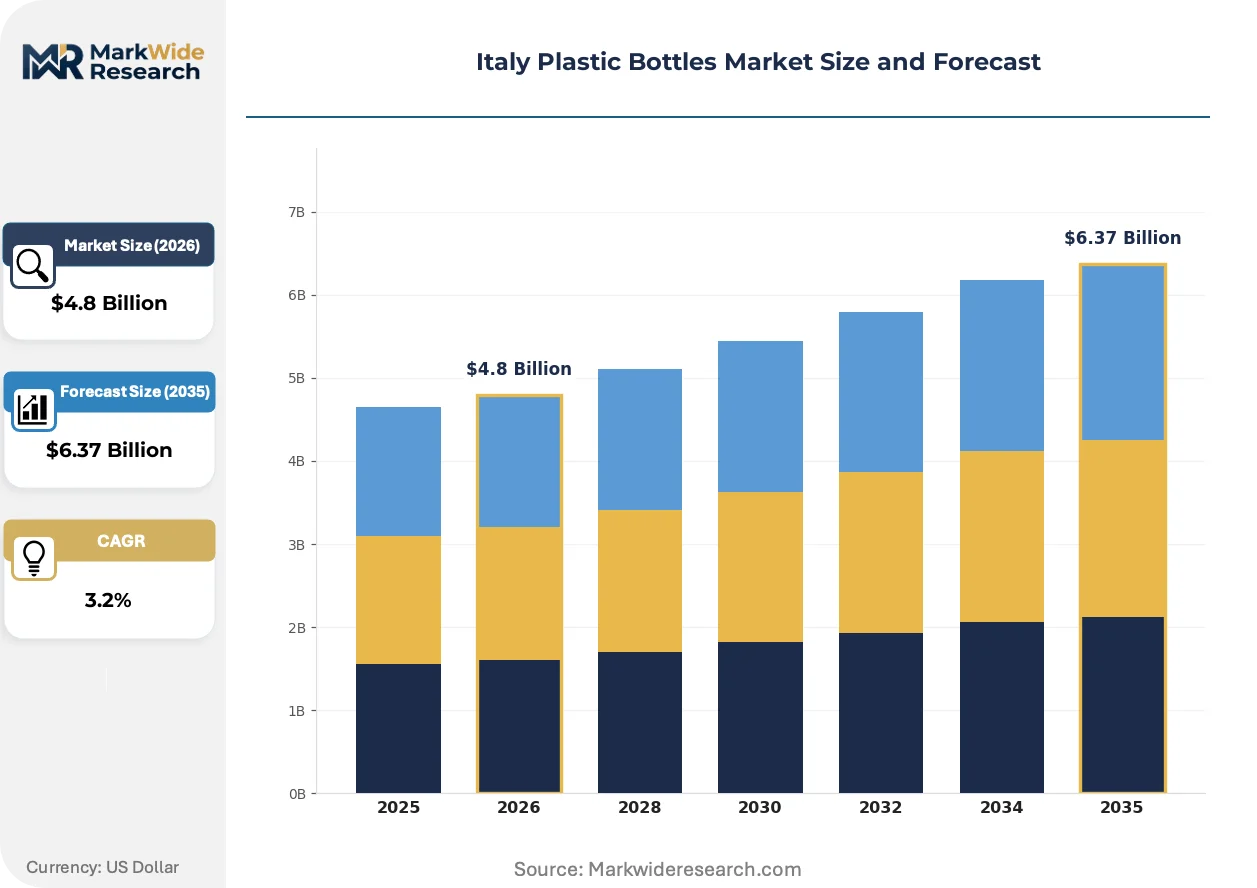
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Beverage Industry, Personal Care, Household Products, Pharmaceutical Packaging Type: Single-Serve, Bulk, Refillable, Disposable Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Alpla Group, Berry Global Inc., Gerresheimer AG, Bormioli Pharma SpA, Berlin Packaging Italy SpA, Valgroup Italia SRL, Daunia Plast SpA, Verve SpA, Plastopiave SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Plastic Bottles Market Trends and Innovations
Digital manufacturing controls and regulatory compliance automation are converging to reshape Italian converter competitiveness, with proximity to brand headquarters becoming a technical differentiator rather than purely a logistics advantage.
All-electric blow-molding machinery with integrated vision inspection is automating defect detection and process adjustment in real time. Premium beverage bottlers in Emilia-Romagna are retrofitting lines with these systems to minimize human intervention in clean-zone environments. This automation is compressing the quality variance between shifts and reducing giveaway rates on high-speed production.
Legislative Decree 196/2021's transposition of the EU Single-Use Plastics Directive mandates minimum recycled content thresholds and reporting obligations for plastic packaging placed on the Italian market. Domestic converters must now maintain chain-of-custody documentation from flake sourcing through final article production. Food contact applications face the steepest compliance burden, with UNI EN 15343 traceability standards becoming a de facto barrier to supplying major retail chains.
Buyer consolidation among multinational beverage brands is compressing supplier negotiation cycles and demanding integrated design-to-delivery partnerships. Category managers now require converters to co-develop packaging solutions at the concept stage rather than bidding on specified drawings. This pattern concentrates procurement authority in Lombardy-based brand headquarters, marginalizing smaller converters without dedicated technical sales resources.
Italy Plastic Bottles Market Segmentation
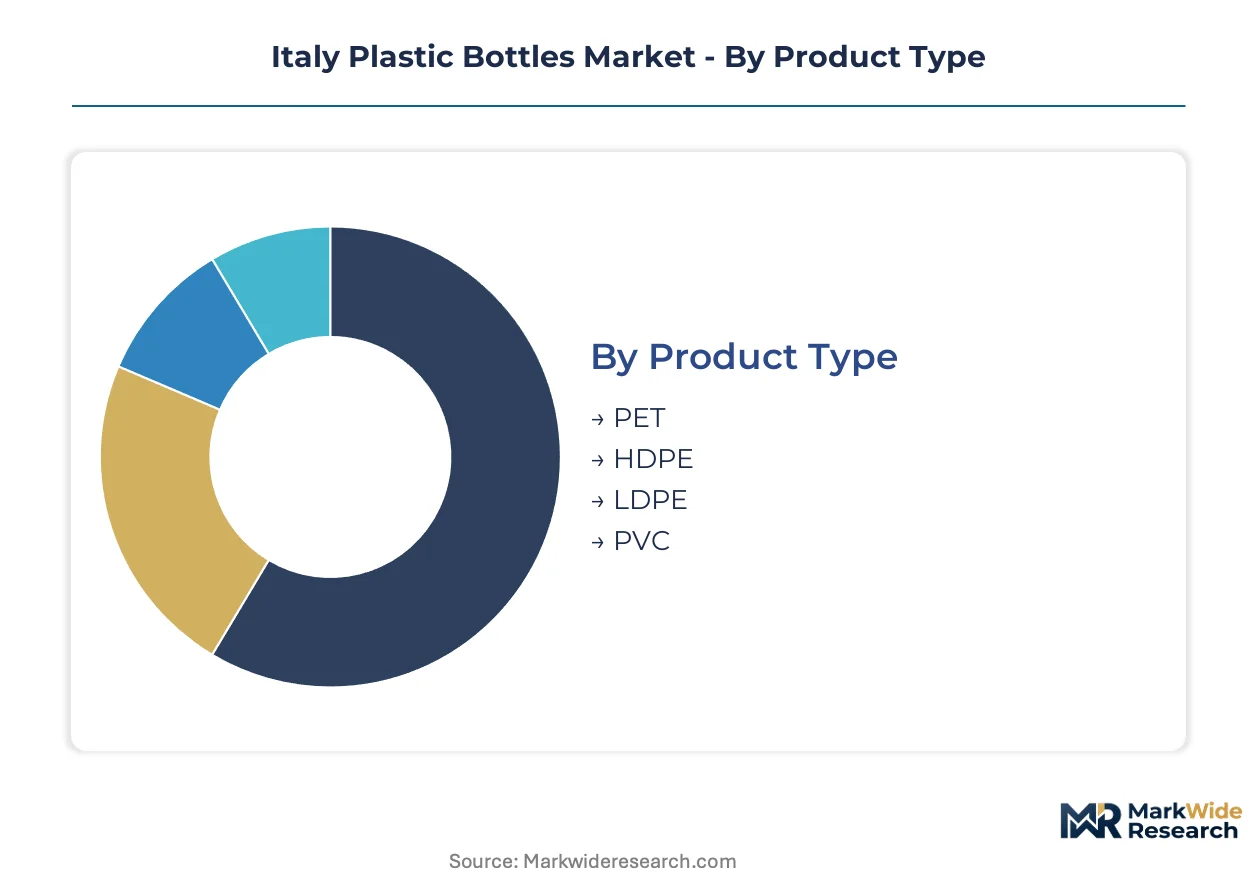
Material chemistry and end-use specifications determine converter investment priorities across Italy's plastic bottles landscape. CONAI fee modulation and beverage brand consolidation reward suppliers with certified recycling streams and barrier technology capabilities.
Product Type:
PET and HDPE formulations dominate converter capacity planning due to recycling infrastructure compatibility and end-use performance requirements.
- PET:Thermoplastic polyester with clarity and oxygen barrier properties suits carbonated beverages and sensitive food applications. Lombardy bottlers demand food-grade rPET integration under CONAI modulation schemes.
- HDPE:High-density polyethylene carries thicker wall specifications and chemical resistance for household cleaners and personal care. Emilia-Romagna converters command margin premiums over commodity PET water bottles.
- LDPE:Low-density variants serve squeeze-dispense applications in cosmetic packaging with softer hand-feel characteristics.
- PVC:Chlorinated polymer retains niche pharmaceutical blister and barrier film applications despite declining beverage adoption.
PET leads on scale; HDPE leads on momentum through personal care premiumization.
End User:
Customer procurement patterns split between multinational beverage consolidators and certification-heavy pharmaceutical buyers.
- Beverage Industry:Carbonated soft drink and mineral water bottlers drive volume demand with standardized neck finishes and barrier specifications. Northern Italy brand headquarters concentrate supplier negotiation authority.
- Personal Care:Milan and Bologna beauty brand clusters require just-in-time delivery and decorative finishing capabilities.
- Household Products:Chemical resistance and trigger-spray compatibility define HDPE bottle specifications for cleaning formulations.
- Pharmaceutical:UNI standards and cleanroom blow-molding requirements create compliance moats around certified converters serving Bormioli Pharma-tier specifications.
Beverage Industry leads on scale; Pharmaceutical leads on margin expansion through certification barriers.
Packaging Type:
Format selection reflects Italian retail channel structure and deposit-return infrastructure maturity.
- Single-Serve:Individual portion bottles for on-premise consumption and convenience retail carry lightweight specifications and tamper-evident closures.
- Bulk:Family-size and food-service formats optimize logistics economics through reduced packaging-to-product ratios.
- Refillable:Returnable glass-competitive formats circulate through dedicated mineral water retail channels with washing and tracking infrastructure.
- Disposable:One-way PET bottles face steepest CONAI fee pressure and rPET content mandates under Legislative Decree 196/2021.
Disposable leads on scale; Refillable leads on regulatory preference through circular economy alignment.
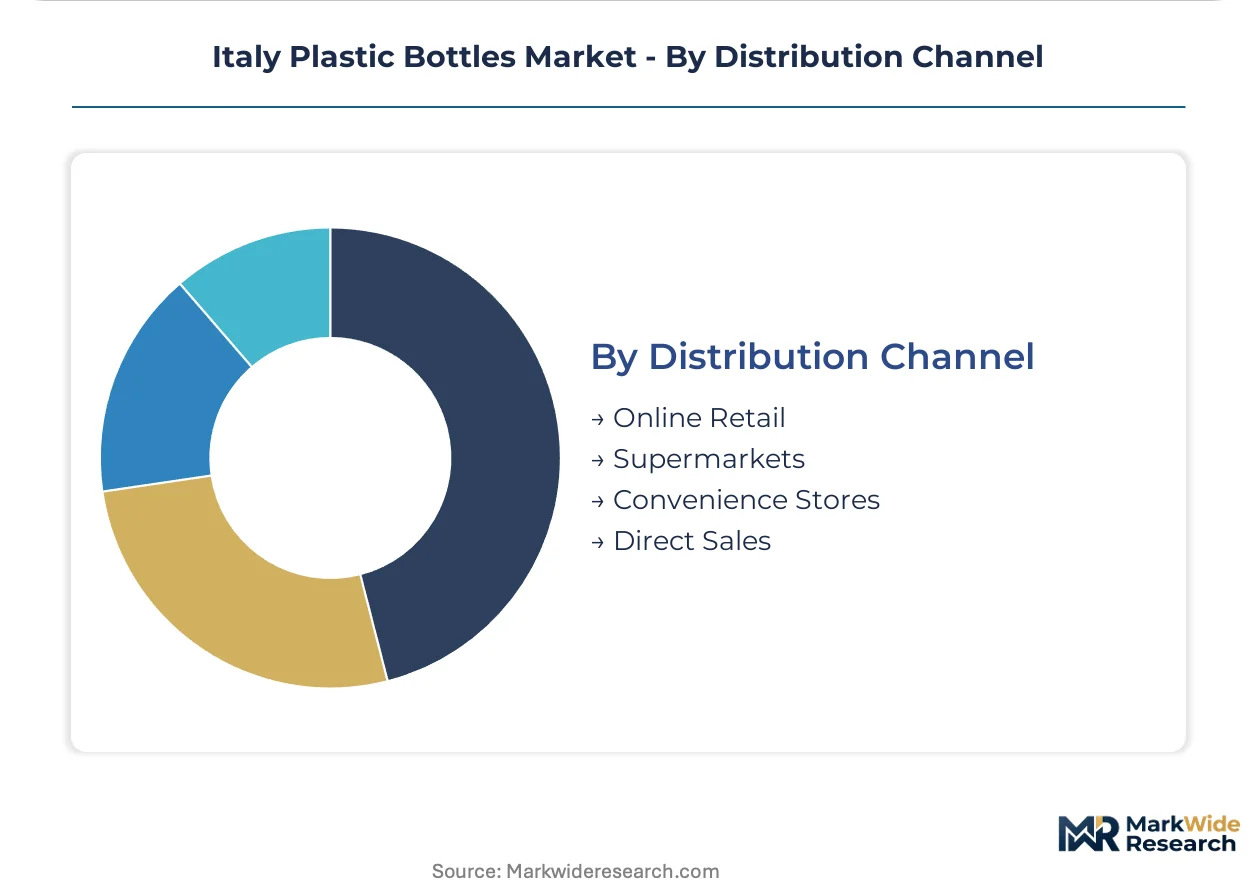
Distribution Channel:
Channel mix shapes converter delivery scheduling and inventory positioning across Northern Italy manufacturing clusters.
- Online Retail:E-commerce fulfillment demands damage-resistant secondary packaging and parcel-optimized bottle geometries.
- Supermarkets:Hypermarket and grocery chains drive high-volume procurement with private-label packaging specifications.
- Convenience Stores:Small-format retail prioritizes shelf-ready packaging and impulse-purchase single-serve formats.
- Direct Sales:Converter-to-brand direct relationships concentrate around Lombardy and Emilia-Romagna headquarters for co-development partnerships.
Supermarkets lead on scale; Direct Sales leads on strategic account control through integrated design partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher rPET integration rates than Italy, while France enforces stricter deposit-return schemes that reshape converter economics across Southern Europe. These divergent national approaches fragment procurement patterns for multinational beverage brands operating across the continent.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia source lightweight PET formats for carbonated drinks and mineral water. The national Packaging Act mandates minimum recycled content thresholds that exceed EU baselines. Cologne and Düsseldorf host converter clusters supplying barrier-enhanced bottles to Rhine-Ruhr brand headquarters.
France
Paris-based cosmetics houses drive demand for decorative HDPE and PET packaging with premium finishing requirements. The country's anti-waste law imposes extended producer responsibility fees that escalate for non-recyclable formats. Lyon and Marseille converters specialize in pharmaceutical-grade blow-molding for southern European distribution.
Spain
Catalonia's cava and wine producers purchase standard-neck PET bottles for sparkling beverage alternatives. Royal Decree 1055/2022 transposes EU single-use plastics rules with accelerated timelines for rPET mandates. Barcelona manufacturing corridors attract Italian converter investment seeking Mediterranean market access.
Netherlands
Rotterdam petrochemical proximity enables integrated resin-to-bottle supply chains for Benelux beverage brands. The national plastic pact commits signatories to recycled content targets above statutory minimums. Eindhoven packaging technology clusters develop inspection systems for recycled material quality verification.
Switzerland
Swissmedic-regulated pharmaceutical packaging demands exceed EU pharmaceutical-grade specifications for northern Italian suppliers. The federal ordinance on beverage containers maintains separate collection infrastructure that limits cross-border bottle circulation. Ticino converters leverage Italian-speaking workforce access to serve Lombardy brand procurement offices.
Italy Plastic Bottles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's plastic bottles sector. The market exhibits moderate consolidation, with multinational packaging groups holding volume leadership in beverage applications while regional converters defend niche positions in cosmetics and pharmaceuticals. Three archetypes dominate: integrated resin-to-bottle operators, barrier technology specialists, and certification-heavy pharmaceutical suppliers. Capacity expansion and rPET feedstock partnerships constitute the primary competitive vectors as converters race to secure certified recycling streams ahead of regulatory deadlines.
Within the integrated manufacturing tier, Alpla Group and Berry Global Inc. exemplify scale-driven positioning through Northern Italian production footprints. Bormioli Pharma SpA occupies a specialized position serving pharmaceutical compliance requirements that smaller converters cannot replicate. These three entities represent the strategic spectrum from commodity beverage volume through premium barrier applications to regulated healthcare packaging.
| Leading Market Players |
|---|
| Alpla Group |
| Berry Global Inc. |
| Gerresheimer AG |
| Bormioli Pharma SpA |
| Berlin Packaging Italy SpA |
| Valgroup Italia SRL |
| Daunia Plast SpA |
| Verve SpA |
| Plastopiave SRL |
| Others |
Pricing and Supply Chain Analysis
CONAI's packaging fee modulation gates qualified supply access and premium-tier pricing power across Italian converter operations, forcing rPET-certified producers into preferred supplier status while virgin-dependent competitors absorb margin compression.
Pricing Analysis
Capacity additions in Emilia-Romagna and Lombardy are reshaping price floors for commodity PET water bottles as integrated preform-to-bottle operators capture scale economies. Three-tier pricing structure across premium barrier-enhanced, standard food-grade, and economy non-certified levels stratifies converter margins. Pricing pressure stems from energy cost volatility in Northern Italy's manufacturing clusters, squeezing blow-molding operations disproportionately. Multinational beverage bottlers exhibit highest price sensitivity through consolidated procurement, while pharmaceutical buyers prioritize certification tiers over unit economics.
Supply Chain Analysis
Returnable bottle washing and tracking infrastructure creates reverse-logistics value recovery for mineral water channels competing with disposable formats. Raw material supply draws from Germany's petrochemical corridor, domestic rPET flake processing in Lombardy, and imported food-grade pellet streams from France and Spain. Supply chain risk centers on single-source vulnerability for certified rPET feedstock ahead of Legislative Decree 196/2021 mandates. Distribution runs through Lombardy-based brand headquarters for direct converter partnerships, with secondary flows via Emilia-Romagna logistics hubs serving supermarket and convenience retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy Plastic Bottles Market functions as a stable compounder, with regulatory-driven rPET integration providing predictable demand visibility across the projection horizon.
For Market Incumbents: Deploy backward integration into certified rPET sourcing to lock in CONAI-compliant feedstock ahead of competitor capacity additions. Consolidate barrier technology capabilities through co-injection system investments that multinational beverage brands now mandate for sensitive product lines. Defensive positioning requires preempting substitute material pressure from glass returnable formats in premium mineral water channels. For New Entrants and Emerging Players: Specialty pharmaceutical buyers seeking UNI-standard cleanroom blow-molding represent the most penetrable white-space target, as incumbent converters underinvest in pharma-grade capacity. Cosmetic brand procurement offices in Milan and Bologna enable just-in-time supply relationships without scale disadvantages. Go-to-market positioning should emphasize localized co-development partnerships rather than commodity bidding. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with certified recycling streams because CONAI modulation creates compliance moats that scale players cannot easily replicate. Long-term viability hinges on rPET integration depth rather than virgin resin processing scale. Acquisition targets should demonstrate verified chain-of-custody documentation and established relationships with Northern Italy brand headquarters. Monitor rPET pellet spot price spreads against virgin PET as the inflection indicator for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Feedstock Partnership | Secures CONAI-compliant supply ahead of Legislative Decree 196/2021 enforcement thresholds. |
| Barrier Technology Upgrade | Oxygen-scavenging co-injection systems unlock premium beverage applications with multinational bottlers. |
| Pharma Certification Investment | UNI-standard cleanroom capacity creates defensible positioning against commodity converter competition. |
| Direct Sales Channel Expansion | Lombardy brand headquarters proximity enables integrated design partnerships beyond transactional supply. |
| Refillable Infrastructure Modernization | Returnable bottle tracking systems capture circular economy preference in Italian mineral water culture. |
Research Methodology
Multiple input streams — converter production data, brand procurement specifications, and regulatory filing analysis — were reconciled to construct market estimates. Primary interviews with blow-molding operations managers, beverage category buyers, pharmaceutical packaging engineers, and CONAI compliance officers were validated against secondary sources including Legislative Decree 196/2021 transposition documents, UNI EN 15343 traceability standards, and customs trade records. Bottom-up capacity modeling and top-down demand aggregation were cross-checked for consistency.
Historical volume trajectories were cross-referenced against expert panel assessments to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include material chemistry, end-use industry, packaging format, and regional manufacturing cluster. CAGRs were derived from trend extrapolation moderated by rPET supply availability constraints and energy cost volatility assumptions specific to Northern Italy's industrial districts.
Inputs from CONAI fee schedules and EU Packaging and Packaging Waste Regulation drafts were available through the study window; gaps in post-consumer bale contamination rate data introduce uncertainty bands around rPET integration timelines. Forecasts reflect material balance assumptions and regulatory implementation pacing. Practitioners should monitor rPET pellet import flows and Lombardy electricity futures for early signals of margin pressure direction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Mexico Plastic Bottles Market