
 Corrugated Pallet Containers Market | 2026-2036
Corrugated Pallet Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Pallet Containers Market Outlook
Single-source corrugated supply agreements are shifting toward multi-source frameworks as brand owners seek resilience against fiber price volatility. DS Smith leverages its integrated recycling network to secure post-consumer fiber streams across European manufacturing hubs. Smurfit Kappa anchors its competitive stance through geographic density in Iberia and Eastern Europe. Mondi Group differentiates via performance-grade liners engineered for heavy-duty industrial applications.
Corrugated pallet containers are engineered from multi-layered kraft linerboard and fluted medium, typically achieving dynamic load capacities between 500 kg and 1,500 kg through triple-wall or heavy-duty double-wall construction, and serve primarily as one-way or limited-use shipping platforms for unitized goods. Stackable pallet containers lead volume share in industrial goods distribution where warehouse cube optimization drives procurement criteria, while nestable variants represent the fastest-expanding category in retail grocery backhaul networks where empty container return efficiency governs total cost. Custom pallet containers command premium positioning in pharmaceutical cold chain applications requiring validated dimensional tolerances and contamination-resistant coatings.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that elevate demand for recyclable corrugated formats over plastic alternatives, while FDA food contact substance notifications govern linerboard chemistry for U.S. food and beverage shipments. ISO 8611 pallet testing standards shape product qualification protocols for cross-border trade acceptance. Stakeholders must monitor fiber cost pass-through mechanisms and emerging national eco-modulation fees that will restructure total cost of ownership calculations across procurement cycles.
Market Dynamics
Corrugated pallet container supply chains are consolidating around integrated fiber-to-finished-goods networks as virgin kraft linerboard availability tightens and post-consumer fiber recovery costs escalate across European and North American manufacturing basins.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are elevating corrugated formats over plastic alternatives in German and Dutch retail distribution networks, accelerating format substitution in temperature-sensitive food logistics.
- Nestable design architecture:Collapsible return-trip efficiency is capturing procurement preference in European grocery backhaul systems where empty container cube reduction governs total landed cost calculations.
- Pharmaceutical cold chain validation:Custom-engineered pallet containers with contamination-resistant coatings and dimensional tolerances are penetrating validated supply lanes for temperature-sensitive biologics distribution.
Market Restraints
- Recycled fiber cost volatility:Post-consumer old corrugated container feedstock prices fluctuate with municipal collection economics and export demand from Asian paper mills, compressing converter margins unpredictably.
- Triple-wall structural limitations:Heavy-duty double-wall and triple-wall constructions face dynamic load capacity ceilings around 1,500 kg that exclude certain industrial machinery and dense metal component shipments.
- Plastic pallet residual competitiveness:Injection-molded HDPE pallets with multi-trip lifespans retain total cost of ownership advantages in closed-loop pool systems despite regulatory headwinds.
Strategic Opportunities
- Eco-modulation fee structures:Emerging national packaging fee frameworks in France and Italy will penalize non-recyclable formats, creating price-positioning advantages for corrugated pallet containers in premium logistics segments.
- Lightweighting through micro-flute engineering:F-flute and N-flute medium substitutions in double-wall constructions are enabling freight cost reductions in air cargo and parcel network applications.
- Digital print integration:Direct-to-corrugate branding and tracking code application is opening high-visibility retail display pallet opportunities in consumer electronics and cosmetics distribution.
Industry Challenges
- ISO 8611 cross-border harmonization:Pallet testing protocol discrepancies between EU member state enforcement bodies create qualification delays and redundant certification expenses for pan-European suppliers.
- Moisture resistance specification gaps:Wax-impregnated and polymer-coated linerboard chemistries face evolving FDA food contact substance notification requirements that extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Pallet Containers Market |
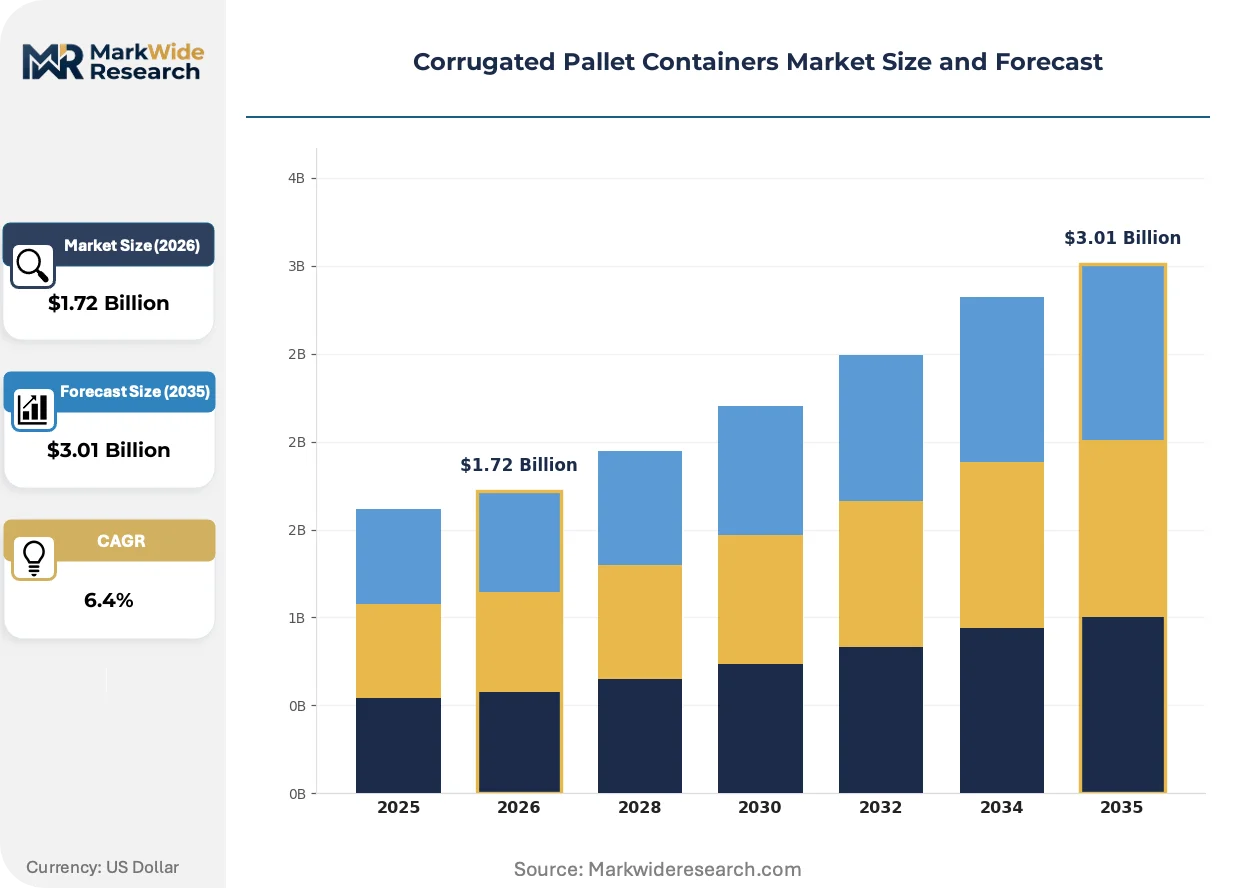
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pallet Containers, Nestable Pallet Containers, Stackable Pallet Containers, Custom Pallet Containers End User: Food & Beverage, Pharmaceuticals, Electronics, Industrial Goods Size: Small, Medium, Large, Extra Large Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DS Smith, Smurfit Kappa, International Paper, WestRock, Pratt Industries, Mondi Group, Packaging Corporation of America, Rengo, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Pallet Containers Market Strategic Shifts
Active innovation in corrugated pallet container engineering is compressing traditional trade-offs between structural performance, material efficiency, and end-of-life recoverability as fiber economics and regulatory thresholds tighten simultaneously.
High-performance micro-flute corrugated board is rewriting load-bearing assumptions in lightweight logistics applications. Pharmaceutical distributors and fresh produce exporters are adopting F-flute and N-flute double-wall constructions at accelerating rates. This substitution is enabling freight cost reductions in weight-sensitive air cargo lanes while maintaining stacking strength for unitized shipments.
REACH chemical registration requirements are reshaping coating chemistry development across European converter operations. Wax alternatives and bio-based moisture barriers face heightened substance scrutiny that extends formulation approval timelines. Food and beverage logistics operators in Germany and the Netherlands are responding by qualifying coated pallet containers earlier in procurement cycles to secure supply continuity.
Consolidated buying desks at multinational retail chains are compressing supplier rosters and extending contract durations in corrugated pallet container procurement. Traditional spot-market purchasing in Iberian and Eastern European distribution networks is giving way to multi-year framework agreements with volume commitments. This concentration is most visible in temperature-controlled grocery supply chains where format standardization reduces operational complexity.
Corrugated Pallet Containers Market Segmentation
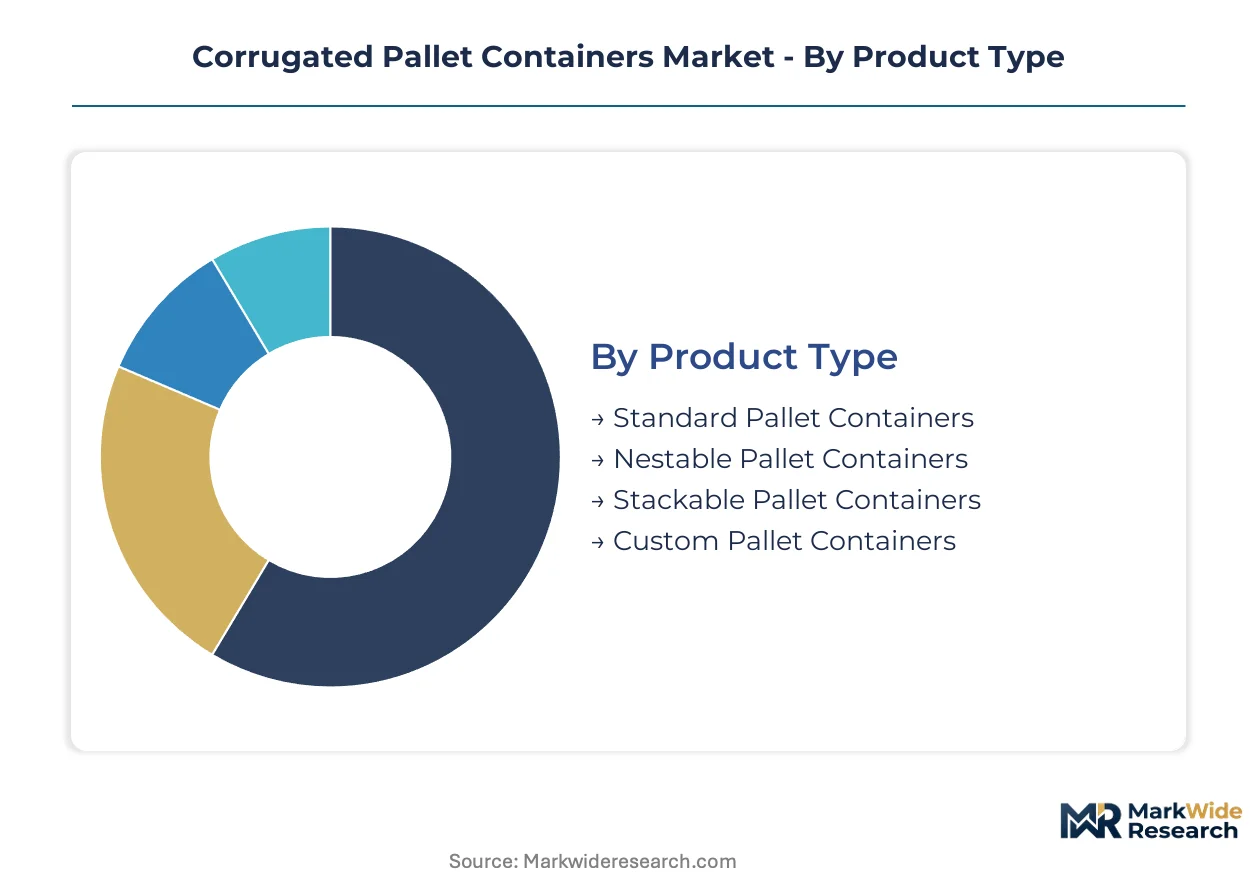
Corrugated pallet container procurement varies sharply across application contexts. Load-bearing specifications, return-trip efficiency requirements, and regulatory compliance thresholds reshape format selection at the category level.
Product Type:
Structural engineering choices determine dynamic load capacity, collapse ratios, and fiber consumption per unit.
- Stackable Pallet Containers:Triple-wall or heavy-duty double-wall constructions achieve dynamic load ratings between 500 kg and 1,500 kg. Warehouse cube optimization drives procurement concentration in German industrial goods distribution networks where vertical storage density governs facility economics.
- Nestable Pallet Containers:Collapsible sidewalls enable empty container volume reduction of 60-70%. European grocery backhaul systems in the Netherlands and Belgium prioritize this format for return-trip freight cost minimization.
- Standard Pallet Containers:Double-wall constructions serve general-purpose unitized shipping with moderate load requirements.
- Custom Pallet Containers:Validated dimensional tolerances and contamination-resistant coatings address pharmaceutical cold chain specifications.
Mature deployment sits with stackable formats. Newer deployment is concentrated in nestable configurations.
End User:
Regulatory intensity and product value density reshape linerboard chemistry and coating requirements.
- Food & Beverage:Temperature-sensitive logistics operators specify moisture-resistant liners compliant with FDA food contact substance notifications. Fresh produce exporters in Iberia adopt F-flute lightweighting for air cargo cost containment.
- Pharmaceuticals:Biologics distributors require validated pallet containers with dimensional stability across temperature excursions. REACH-registered coating alternatives face extended formulation timelines.
- Electronics:Anti-static linerboard treatments and retail-display-ready direct print capabilities gain priority.
- Industrial Goods:Heavy machinery shipments push against triple-wall load ceilings, limiting format applicability.
Volume concentration rests with food and beverage. Steepest expansion trajectory appears in pharmaceutical validation lanes.
Size:
Dimensional standardization versus customization trade-offs manifest across freight mode and handling equipment compatibility.
- Medium:Euro-pallet footprint compatibility (1200mm x 800mm) dominates cross-border European distribution. Retail grocery consolidation hubs in France and Germany standardize on this dimension for automated handling system integration.
- Large:ISO 8611-tested constructions serve industrial machinery and dense metal component unitization where dynamic load requirements approach format limits.
- Small:Parcel network and air cargo applications favor dimensional constraints for freight cost containment.
- Extra Large:Project cargo and bulk agricultural shipments require custom engineering for point-to-point logistics.
Procurement scale clusters in medium formats. Emerging demand concentrates in small sizes for e-commerce fulfillment.
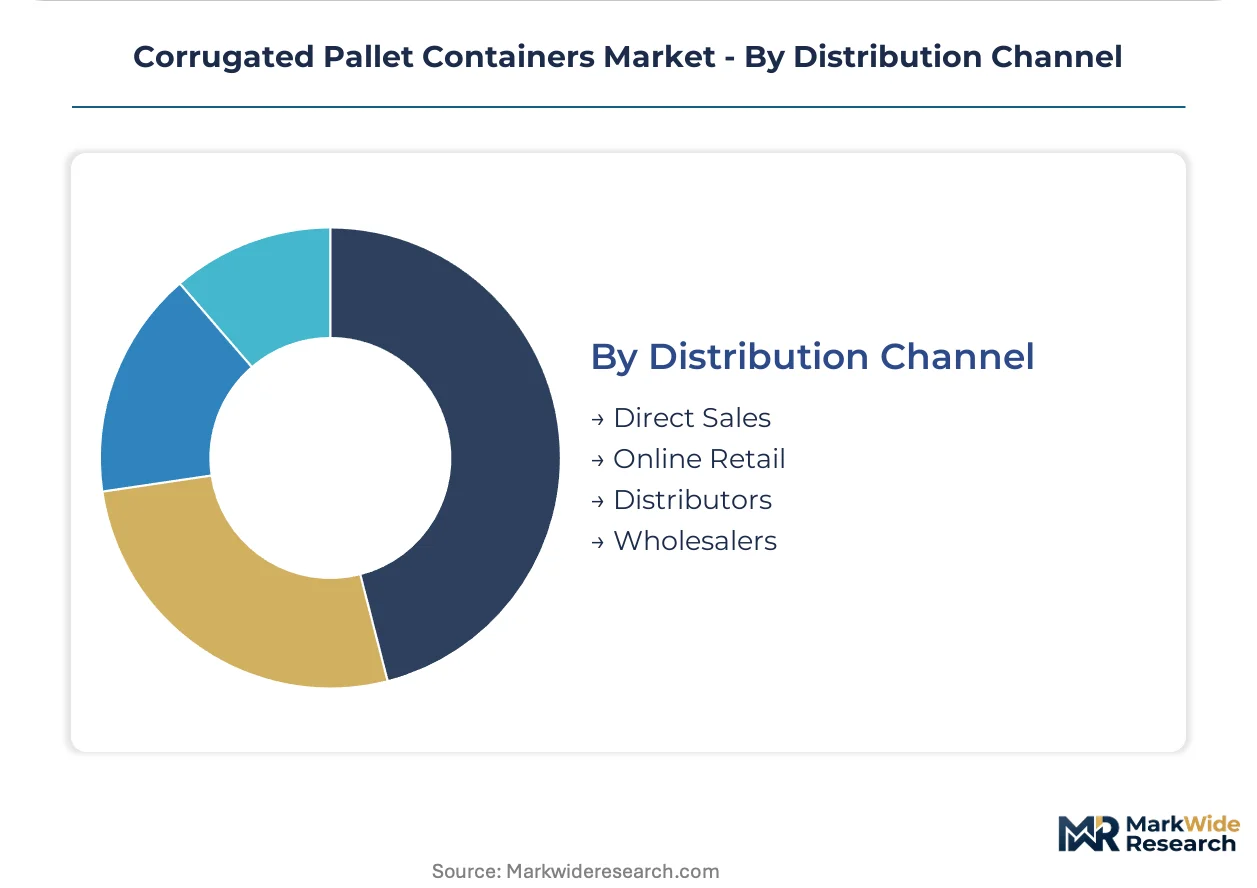
Distribution Channel:
Customer scale and contract duration reshape channel economics and supplier relationship structures.
- Direct Sales:Multinational retail chains consolidate buying desks and extend contract durations. Framework agreements with volume commitments displace spot-market purchasing in temperature-controlled grocery supply chains.
- Distributors:Geographic density in Iberia and Eastern Europe enables converter market access with reduced direct sales overhead.
- Online Retail:Small-batch procurement and rapid specification switching serve mid-market industrial customers.
- Wholesalers:Inventory carrying positions buffer converter production cycles against demand volatility.
Established volume flows through direct sales. Channel experimentation is concentrated in online retail for fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virgin kraft linerboard availability concentrates supply-side investment in Germany and the Netherlands, while post-consumer fiber recovery economics reshape converter margins across Iberia and Eastern Europe.
Germany
Automotive parts distributors and industrial machinery shippers specify triple-wall corrugated pallet containers for dense metal component unitization. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that elevate recyclable formats over plastic alternatives. The Ruhr industrial corridor and Stuttgart manufacturing basin anchor procurement concentration for heavy-duty stackable formats.
Netherlands
European grocery backhaul networks prioritize nestable pallet container architectures for empty container cube reduction. REACH chemical registration requirements extend coating formulation timelines for moisture-resistant linerboard alternatives. Rotterdam port logistics clusters and Eindhoven distribution hubs standardize on collapsible sidewall designs for return-trip freight optimization.
United States
Food and beverage logistics operators specify FDA food contact substance notification-compliant linerboard for temperature-sensitive shipments. EPA industrial emissions standards shape converter facility siting decisions in fiber-deficient regions. The Great Lakes manufacturing belt and Southeast distribution corridors drive volume concentration for heavy-duty double-wall constructions.
Spain
Fresh produce exporters adopt F-flute lightweighting for air cargo cost containment in weight-sensitive lanes. National eco-modulation fee frameworks penalize non-recyclable packaging formats, creating positioning advantages for corrugated alternatives. The Valencia agricultural export zone and Barcelona logistics hub concentrate procurement for medium-format Euro-pallet-compatible containers.
China
E-commerce fulfillment networks generate emerging demand for small-format corrugated pallet containers in parcel distribution applications. GB standards for packaging materials govern structural testing protocols for cross-border shipment acceptance. The Yangtze River Delta manufacturing cluster and Pearl River Delta export zones anchor production capacity for lightweight micro-flute constructions.
Corrugated Pallet Containers Market Competitive Environment
Global majors compete with regional champions across integrated fiber-to-finished-goods networks, creating a tiered structure where scale-driven converters anchor premium industrial segments while specialized fabricators capture niche validation requirements. The vendor base stratifies into three archetypes: integrated paperboard producers with captive recycling networks, independent converters serving fragmented regional demand, and specialty engineers targeting pharmaceutical cold chain specifications. Dominant competitive moves include backward integration into post-consumer fiber recovery assets and geographic density plays in high-volume distribution corridors.
Within the integrated producer tier, DS Smith and Smurfit Kappa occupy positions defined by geographic network coverage, with the former exemplifying multi-source fiber security strategies and the latter representing Iberian and Eastern European market density. International Paper anchors the North American scale-driven segment. These named entities sit within competitive archetypes rather than definitive market positions, reflecting procurement consolidation trends at multinational retail buying desks.
| Leading Market Players |
|---|
| DS Smith |
| Smurfit Kappa |
| International Paper |
| WestRock |
| Pratt Industries |
| Mondi Group |
| Packaging Corporation of America |
| Rengo |
| Stora Enso |
| Others |
Value Chain & Pricing Dynamics
The EU Packaging and Packaging Waste Regulation gates qualified supply and premium-tier pricing access for corrugated pallet container converters, as extended producer responsibility mandates favor fiber-recovery-integrated producers while penalizing non-compliant competitors with eco-modulation fee exposure.
Pricing Analysis
Service-bundling separates validated cold-chain warranty coverage from unbundled spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 8611 certification grade and volume commitment scale. Cost compression in standard-grade double-wall constructions is intensifying because post-consumer old corrugated container feedstock prices fluctuate with Asian export demand. Mid-market industrial distributors exhibit highest price sensitivity, while pharmaceutical logistics operators accept premium positioning for validated dimensional tolerances.
Supply Chain Analysis
Domestic-content mandates in France and Italy reshape sourcing toward EU-registered coating chemistries under REACH registration requirements. Virgin kraft linerboard availability concentrates in Germany, the Netherlands, and the United States, while post-consumer fiber recovery feeds from municipal collection economics across Iberia and Eastern Europe. Supply chain risk centers on single-source vulnerability for FDA food contact substance notification-compliant linerboard. Distribution runs through direct sales frameworks with multinational retail chains and geographic density plays via Iberian and Eastern European distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated pallet container market reads as a cost-of-compliance story, where the EU Packaging and Packaging Waste Regulation erects a barrier-to-entry moat that rewards integrated fiber-recovery players with qualified supply access and premium pricing power.
For Market Incumbents: Deepen backward integration into post-consumer fiber recovery assets to secure feedstock cost stability against Asian export demand volatility. Expand capacity in German and Dutch manufacturing basins where virgin kraft linerboard availability anchors premium industrial segment dominance. Defend against plastic pallet residual competitiveness in closed-loop pool systems by accelerating REACH-registered coating formulation timelines. For New Entrants and Emerging Players: The EU Packaging and Packaging Waste Regulation in Europe opens a window for specialty engineers targeting pharmaceutical cold chain validation requirements with contamination-resistant coating capabilities. White-space concentration sits with custom-engineered pallet containers for biologics distribution, where dimensional stability across temperature excursions commands premium positioning. Penetrate via direct-to-corrugate digital print integration for retail display pallet opportunities in consumer electronics. For Investors and Strategic Acquirers: Consolidated buying desk framework agreements at multinational retail chains is the leading indicator that procurement concentration will favor scaled converters with geographic density. Long-term viability frames toward integrated fiber-to-finished-goods networks with captive recycling infrastructure. Target acquisition archetype: regional champions with REACH-registered coating capabilities and established pharmaceutical validation lanes. Watch for eco-modulation fee implementation in France and Italy as inflection signal for format substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recovery | Captive post-consumer old corrugated container supply insulates margin compression from Asian export demand swings. |
| REACH-Registered Coating Development | Bio-based moisture barrier formulations secure pharmaceutical cold chain qualification ahead of regulatory deadlines. |
| Micro-Flute Lightweighting Investment | F-flute and N-flute engineering enables freight cost reductions in weight-sensitive air cargo lanes. |
| Digital Print Direct-to-Corrugate Capability | High-visibility retail display pallet positioning captures consumer electronics and cosmetics distribution demand. |
| Geographic Density Expansion in Iberia | Fresh produce export zone proximity reduces logistics overhead for F-flute lightweighting adoption. |
Study Parameters
Multi-period observation of fiber cost pass-through mechanisms and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with corrugated converter operations managers, pharmaceutical logistics procurement directors, retail chain buying desk leads, and REACH regulatory affairs specialists. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, FDA food contact substance notification databases, ISO 8611 testing protocol records, and fiber price benchmark indices. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and regional dimensions.
Input-output matrix framing structured the analytical framework, mapping virgin kraft linerboard availability, post-consumer fiber recovery economics, and regulatory compliance thresholds to volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed structural engineering format, industry application context, dimensional standardization tier, and distribution channel structure. CAGRs derived from trend extrapolation of historical fiber cost volatility patterns and regulatory-driven format substitution elasticities, with freight mode economics and automated handling system integration serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for wax-alternative moisture barrier chemistry would alter the outlook if bio-based formulations face extended substance scrutiny. Forecasts reflect documented assumptions regarding EU member state enforcement harmonization and fiber price pass-through elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Europe Lumber Pallet Market