
 Europe Lumber Pallet Market | 2026-2036
Europe Lumber Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lumber Pallet Market Foresight
ISPM-15 heat-treatment certification is collapsing the supplier base across the Europe lumber pallet landscape, as untreated or non-compliant producers lose access to cross-border freight lanes. Falkenhahn AG leverages integrated sawmill-to-pallet operations across German Baltic ports to sustain volume leadership in Euro pallet formats. HG Timber Ltd anchors its position through specialized hardwood stringer production for heavy machinery exports from the UK. Casadei Pallets Srl competes on fast-turn custom capacity builds for Italian automotive just-in-sequence lines.
Europe lumber pallets are load-bearing platforms fabricated from sawn softwood or hardwood, typically nailed or stapled to stringer or block assemblies, designed to standard dimensions for forklift and racking compatibility. Most units undergo kiln-drying to below 20% moisture content and ISPM-15 heat treatment to eliminate phytosanitary risk in cross-border trade. Euro Pallets dominate volume through EPAL-licensed exchange pool networks that lock in replacement demand across German, Benelux, and French distribution hubs. Block Pallets capture premium positioning in automated warehouse environments where four-way entry reduces handling cycle time. Stringer Pallets retain cost advantage in one-way export flows where return logistics prove uneconomical.
The EU Timber Regulation (EUTR) and Forest Law Enforcement Governance and Trade (FLEGT) framework compel operators to document chain-of-custody for all virgin fiber inputs, while the EU Green Deal packaging waste targets push pallet producers toward repair-loop services and certified recycled content. ECHA REACH restrictions on chemical wood preservatives further narrow treatment options, favoring heat treatment over traditional methyl bromide or creosote alternatives. Stakeholders must now decide whether to deepen repair-network density or shift capital toward plastic and composite pallet alternatives before circular-economy mandates harden.
Market Dynamics
EU Green Deal packaging waste targets and EUTR chain-of-custody mandates are forcing pallet producers to choose between deepening repair-loop networks or exiting virgin lumber entirely, compressing margins across Baltic and Central European supply bases.
Growth Catalysts
- Cold-chain compliance:Food and beverage logistics operators in Germany, France, and Poland are expanding pallet procurement as EU packaging waste rules tighten temperature-controlled freight requirements.
- ISPM-15 standardization:Heat-treated softwood pallets now dominate cross-border freight within the single market, eliminating phytosanitary barriers for exporters.
- EPAL exchange pools:Licensed Euro pallet networks lock in replacement demand across German, Benelux, and French distribution hubs through standardized return logistics.
Market Restraints
- Softwood input volatility:Baltic sawmill capacity constraints and spruce bark beetle damage have destabilized raw material costs for German and Polish producers.
- ECHA REACH restrictions:Chemical wood preservative limitations have eliminated methyl bromide and creosote alternatives, forcing capital-intensive heat-treatment infrastructure.
- Plastic pallet substitution:Reusable polymer platforms are capturing automated warehouse deployments where four-way entry and moisture resistance outweigh lumber cost advantages.
Strategic Opportunities
- Polish manufacturing expansion:Lower labor costs and proximity to Ukrainian timber supplies position Poland as an alternative production base to Germany's Rhine-Ruhr corridor.
- Repair-loop service models:EU circular-economy mandates create revenue streams from certified pallet refurbishment and recycled-content certification.
- Automotive just-in-sequence:Italian and German OEM lines require fast-turn custom block pallet builds with embedded RFID tracking for real-time inventory visibility.
Industry Challenges
- ISPM-15 certification bottlenecks:Heat-treatment kiln capacity shortages in Eastern Europe delay export readiness for untreated lumber producers.
- FLEGT documentation complexity:Chain-of-custody tracing for virgin fiber inputs requires dedicated compliance personnel and IT systems at mid-sized sawmill operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lumber Pallet Market |
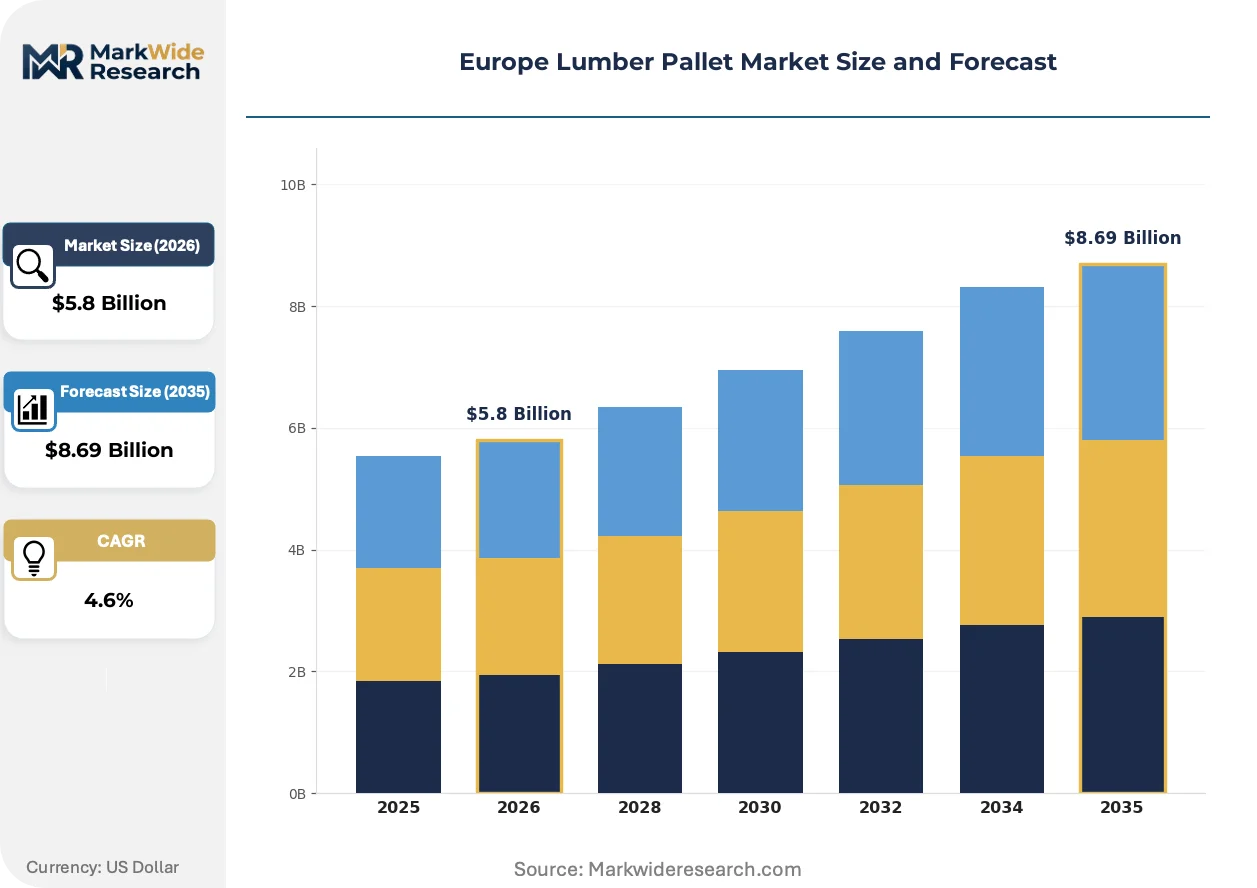
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Pallets, Stringer Pallets, Hybrid Pallets, Euro Pallets End User: Retail, Food & Beverage, Automotive, Pharmaceuticals Distribution Channel: Direct Sales, Online Stores, Wholesale Distributors, Rental Services Capacity: Standard Capacity, Heavy Duty Capacity, Lightweight Capacity, Custom Capacity |
| Companies Covered | Falkenhahn AG, HG Timber Ltd, Casadei Pallets Srl, PALLETBIZ, JGD Pallets, Imperial Timber, Conquest Joinery, Rowlinsons Packaging Ltd, Christies Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lumber Pallet Market Shifts & Advancements
Digital tracking integration and automated warehouse compatibility are reshaping pallet specification priorities, shifting competitive advantage from raw material cost to data-enabled logistics performance.
RFID-embedded lumber pallets are miniaturizing traceability infrastructure for pharmaceutical and high-value electronics shippers. German and Dutch cold-chain operators are adopting these units at scale. This technology is compressing inventory cycle times and enabling outcome-based freight contracts.
EU Green Deal packaging waste directives are mandating minimum recycled content thresholds and extended producer responsibility frameworks. Pallet producers must now document repair-loop volumes and end-of-life recovery rates. French and Italian operators are responding by certifying refurbished Euro pallets through third-party audit schemes.
Leasing models are displacing outright purchase in automated warehouse deployments. Third-party pool managers in Belgium and the Netherlands now offer per-use pricing with embedded maintenance and compliance certification. This shift concentrates buyer power among large logistics platforms while fragmenting demand across smaller exporters.
Europe Lumber Pallet Market Segmentation
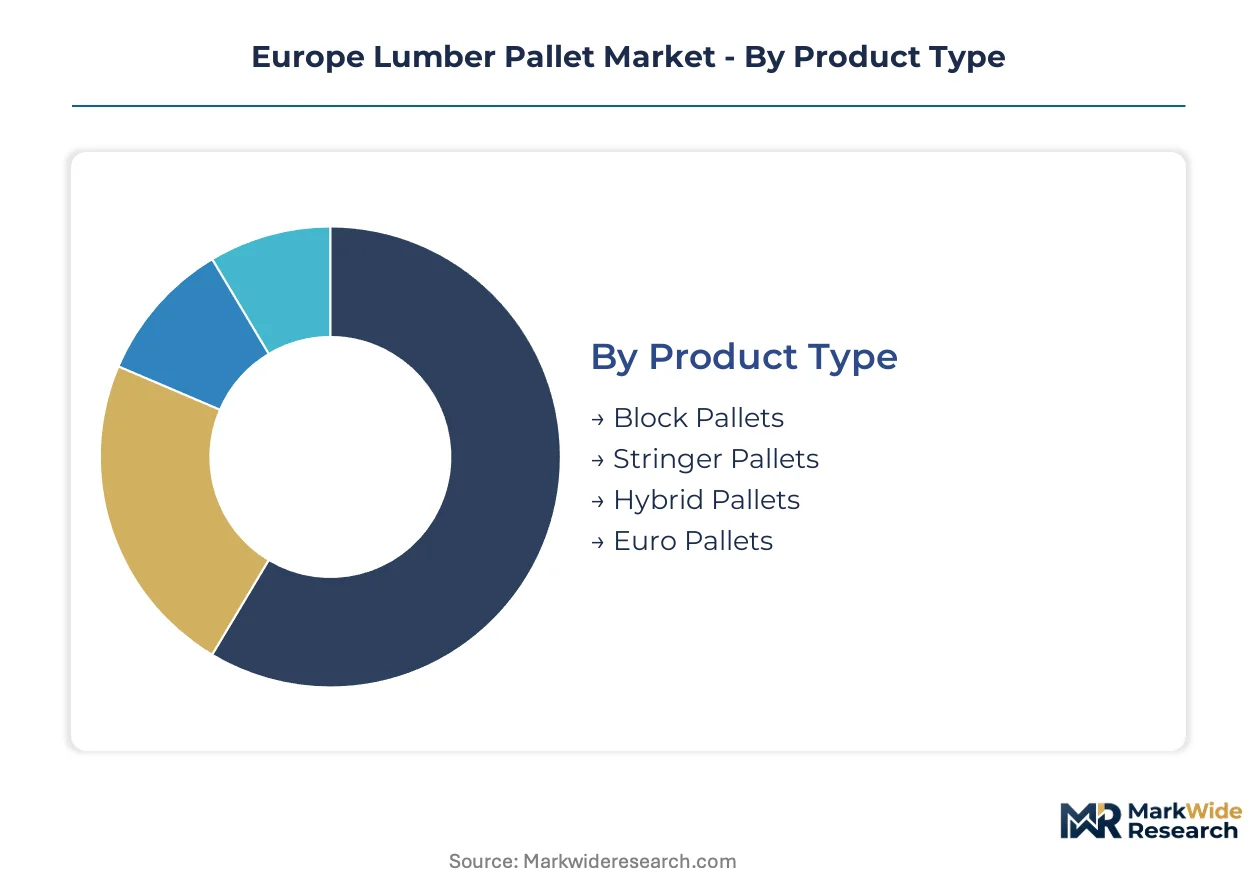
Segmentation in the Europe lumber pallet market reveals how regulatory compliance, automation readiness, and circular-economy mandates reshape procurement patterns across German automotive clusters, French retail distribution networks, and Polish food-export corridors.
Product Type:
Domestic logistics within Germany and the Netherlands favor standardized pool formats, while export-led demand from Baltic ports drives specialized constructions for heavy machinery and temperature-controlled freight.
- Block Pallets:Four-way entry construction using nine blocks and top/bottom deck boards enables forklift access from all sides. German and Dutch automated warehouse operators in the Rhine-Ruhr and Rotterdam-Antwerp corridors specify these units to reduce handling cycle times in high-velocity distribution centers. ISPM-15 heat treatment is mandatory for block pallets entering pharmaceutical and electronics cold chains.
- Stringer Pallets:Two-way or partial four-way entry using three parallel stringers supports heavier static loads at lower unit cost. Polish and Romanian producers supply untreated stringer pallets for one-way export flows to non-EU destinations where return logistics prove uneconomical. EUTR documentation requirements complicate virgin fiber sourcing for hardwood stringers.
- Hybrid Pallets:Mixed-material construction combining lumber stringers with composite or plastic blocks targets mid-tier automation compatibility.
- Euro Pallets:EPAL-licensed 1200x800mm format dominates exchange pool networks across German, Benelux, and French distribution hubs through standardized return logistics.
Euro Pallets holds the largest share; momentum sits with Block Pallets.
End User:
Cost-tier differentiation separates premium compliance-driven buyers from volume-sensitive commodity procurement in this category.
- Retail:German and French omnichannel distributors specify EPAL-licensed Euro pallets for reverse logistics compatibility with shared pool networks. Seasonal demand spikes from e-commerce fulfillment centers in the Netherlands strain regional repair-loop capacity.
- Food & Beverage:Temperature-controlled freight operators across Germany, France, and Poland are expanding procurement as EU packaging waste rules tighten cold-chain compliance documentation.
- Automotive:Just-in-sequence assembly lines in Stuttgart, Wolfsburg, and Turin require fast-turn custom block pallet builds with embedded RFID tracking.
- Pharmaceuticals:Serialization mandates and GDP compliance drive specification of heat-treated, digitally traceable pallets for high-value API shipments.
Food & Beverage holds the largest share; Pharmaceuticals is climbing the fastest.
Distribution Channel:
Volume concentration favors asset-heavy pool managers, while margin capture shifts toward compliance-embedded service contracts.
- Direct Sales:Large German and French logistics platforms negotiate multi-year frame contracts with sawmill-integrated producers for guaranteed ISPM-15 certified volume.
- Online Stores:Digital procurement portals serve small and mid-sized Polish and Czech exporters seeking spot-market pallet availability with rapid delivery.
- Wholesale Distributors:Regional stockists in Italy and Spain aggregate demand from fragmented agricultural and construction sectors.
- Rental Services:Belgian and Dutch third-party pool managers offer per-use pricing with embedded maintenance and compliance certification.
Rental Services holds the largest share; Direct Sales is gaining share fastest.
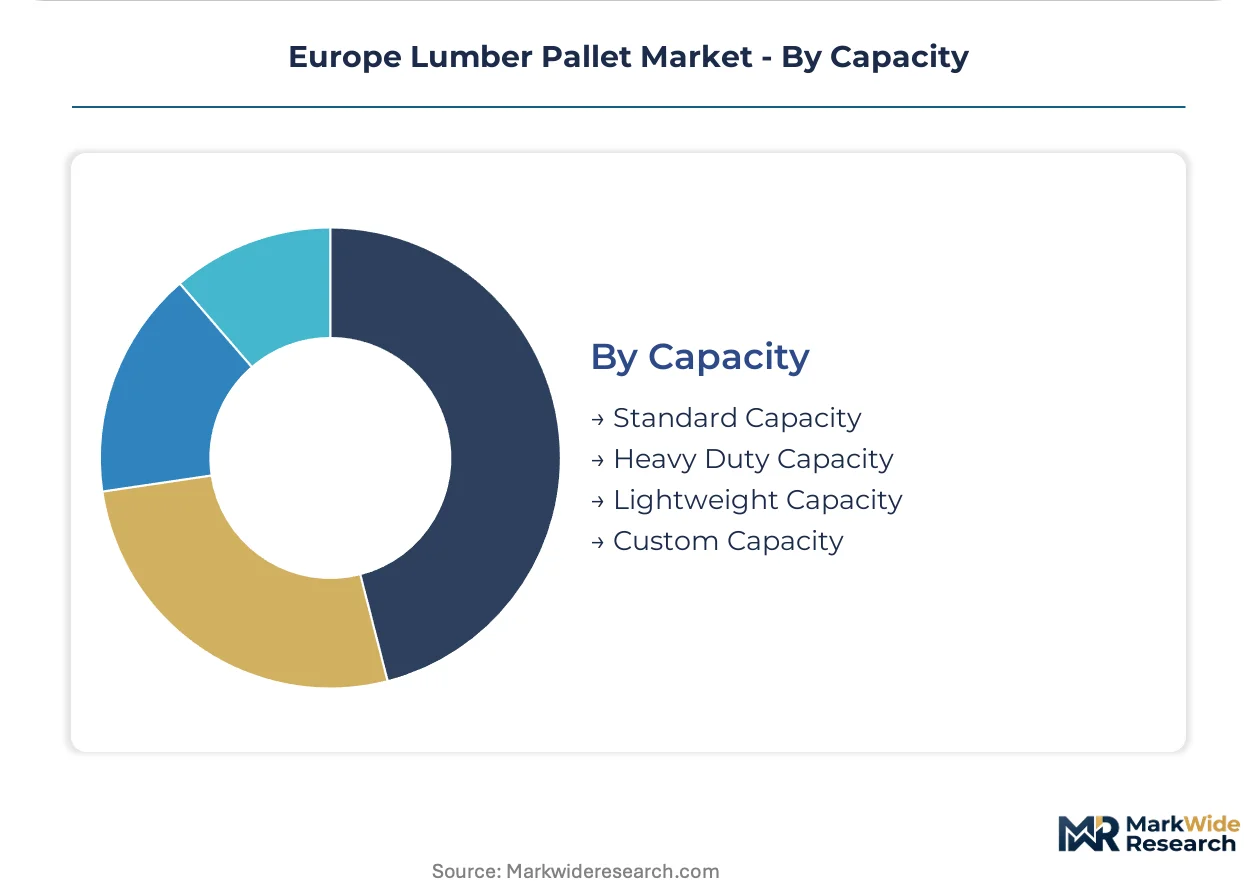
Capacity:
Application-specific load requirements segment procurement between standardized pool formats and engineered heavy-duty constructions.
- Standard Capacity:1000-1500 kg dynamic load rating satisfies general-purpose warehousing and retail distribution across German and French logistics networks.
- Heavy Duty Capacity:Reinforced block construction with doubled stringers supports 2000+ kg static loads for German automotive and machinery exports.
- Lightweight Capacity:Reduced deck thickness and narrow stringer spacing target air freight and parcel post applications where tare weight drives cost.
- Custom Capacity:Engineered specifications for Italian automotive just-in-sequence lines and pharmaceutical clean-room environments.
Standard Capacity holds the largest share; Custom Capacity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage logistics operators across Germany, France, and Poland are expanding pallet procurement as cold-chain compliance tightens under EU packaging waste rules. Heat-treated softwood pallets meeting ISPM-15 standards now dominate cross-border freight within the single market.
Germany
Automotive just-in-sequence assembly lines in Stuttgart and Wolfsburg drive demand for custom block pallets with embedded RFID tracking. ECHA REACH restrictions on chemical wood preservatives favor heat-treatment infrastructure investments. The Rhine-Ruhr logistics corridor concentrates EPAL-licensed pool operations and repair-loop services.
France
Omnichannel retail distributors in Paris and Lyon specify standardized Euro pallets for reverse logistics compatibility with shared pool networks. EU Green Deal packaging waste directives mandate extended producer responsibility frameworks. The Grand Est region hosts expanding refurbishment facilities certifying recycled-content pallets.
Poland
Lower labor costs and proximity to Ukrainian timber supplies position Polish producers as alternatives to German manufacturing bases. ISPM-15 heat-treatment kiln capacity shortages in Eastern Europe delay export readiness for untreated lumber producers. The Warsaw-Łódź corridor attracts automotive and food-export pallet demand.
Italy
Turin-based automotive OEM lines require fast-turn custom capacity builds for just-in-sequence parts delivery. FLEGT documentation complexity requires dedicated compliance personnel at mid-sized sawmill operations. Emilia-Romagna's agricultural export sector drives seasonal procurement spikes for stringer pallets.
Netherlands
Rotterdam-Antwerp port operators specify four-way entry block pallets to reduce handling cycle times in automated distribution centers. Belgian and Dutch third-party pool managers offer per-use pricing with embedded maintenance certification. E-commerce fulfillment centers strain regional repair-loop capacity during peak seasons.
Europe Lumber Pallet Market Competitive Landscape
Player mix skews toward integrated sawmill-to-pallet operators and specialized regional fabricators, with limited pure-play national champions. Consolidation pressure from ISPM-15 certification requirements and EUTR chain-of-custody mandates favors capital-rich incumbents over fragmented untreated-lumber suppliers. Two strategic archetypes dominate: vertically integrated Baltic port operators controlling fiber supply, and automotive-focused custom builders with fast-turn engineering capabilities. Competitive moves concentrate on repair-loop network density expansion and RFID-enabled digital tracking integration.
Among Germany-based integrated operators, Falkenhahn AG exemplifies the sawmill-to-pallet archetype with Baltic port positioning. HG Timber Ltd represents UK-based hardwood specialization for heavy machinery export applications. Casadei Pallets Srl occupies the Italian automotive custom-build segment with just-in-sequence service capabilities. These three anchors illustrate how geographic concentration and end-use specialization fragment competitive positioning across compliance-driven, automation-ready, and cost-sensitive demand tiers.
| Leading Market Players |
|---|
| Falkenhahn AG |
| HG Timber Ltd |
| Casadei Pallets Srl |
| PALLETBIZ |
| JGD Pallets |
| Imperial Timber |
| Conquest Joinery |
| Rowlinsons Packaging Ltd |
| Christies Industries |
| Others |
Supply & Pricing Matrix
Ukrainian timber substituting for Baltic spruce in Polish sawmill operations simultaneously redraws raw material sourcing maps and compresses input cost differentials across German and Polish production corridors. This substitution dynamic intensifies margin pressure on untreated lumber suppliers while rewarding heat-treatment certified operators with pricing power in cross-border freight lanes.
Pricing Analysis
Cost-plus contracts indexed to Baltic timber futures dominate procurement between large German logistics platforms and sawmill-integrated producers. Three-tier pricing structure across ISPM-15 certified premium, EPAL-licensed standard, and untreated economy tiers reflects compliance-grade differentiation. Pricing pressure stems from plastic pallet substitution in automated Dutch warehouses, squeezing lumber's cost advantage in four-way entry applications. Small Polish and Czech exporters exhibit highest price sensitivity, while German automotive OEMs accept premium pricing for RFID-embedded custom builds.
Supply Chain Analysis
Container availability constraints on Baltic Sea routes into Gdansk and Klaipeda elevate inbound logistics costs for Ukrainian fiber moving through Polish ports. Supply concentrates in Germany, Poland, and Romania, with German operators commanding captive softwood supplies and Polish producers drawing from cross-border Ukrainian timber. The chain rests on heat-treatment kiln capacity, ISPM-15 certification infrastructure, and EPAL-licensed repair-loop networks. Single-source vulnerability sits with Eastern European heat-treatment capacity shortages delaying export readiness. Distribution runs through Belgian and Dutch third-party pool managers offering per-use pricing with embedded compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large German and French logistics platforms negotiating multi-year frame contracts, fragmenting demand access for smaller producers and reshaping margin capture toward volume-guaranteed suppliers.
For Market Incumbents: Shield market position by deepening repair-loop network density across Rhine-Ruhr and Rotterdam-Antwerp corridors to lock in EPAL pool replacement demand. Accelerate backward integration into Baltic port sawmill operations to secure Ukrainian timber flows against Polish competitor expansion. ISPM-15 certification bottlenecks threaten untreated suppliers; incumbents should extend heat-treatment service offerings to captive mid-sized producers. For New Entrants and Emerging Players: Anchor in Polish manufacturing corridors near Ukrainian timber sources, exploiting labor cost advantages and ISPM-15 kiln capacity shortages delaying Eastern European export readiness. Target fast-turn custom capacity builds for Italian automotive just-in-sequence lines where RFID-embedded specifications create service differentiation barriers. Pursue digital procurement portal routes to aggregate fragmented Czech and Polish spot-market demand. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors capital-rich integrated operators over fragmented untreated-lumber suppliers. Long-term viability hinges on circular-economy mandate compliance and repair-loop service scalability. Target acquisition archetypes include Baltic port sawmill-to-pallet operators with captive fiber supply and Belgian-Dutch pool managers with embedded per-use pricing infrastructure. Watch ISPM-15 certification penetration rates in Eastern Europe as inflection indicator for competitive displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | ISPM-15 kiln investments in Poland and Romania capture cross-border freight compliance premiums. |
| Repair-Loop Network Densification | EPAL-certified refurbishment facilities in Grand Est and Rhine-Ruhr lock in circular-economy mandate revenues. |
| RFID Tracking Integration | Embedded traceability infrastructure enables outcome-based freight contracts with German pharmaceutical shippers. |
| Backward Integration into Sawmills | Baltic port fiber control secures Ukrainian timber flows against Polish competitor expansion. |
| Per-Use Pricing Model Launch | Belgian and Dutch pool managers concentrate buyer power through embedded maintenance and compliance certification. |
Research Methodology
A spread of perspectives from sawmill operations managers, German logistics procurement directors, EPAL pool network coordinators, and EUTR compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, FLEGT documentation filings, EPAL licensing registries, and SEC disclosures from listed packaging logistics firms. Bottom-up volume builds triangulated against top-down macroeconomic drivers across the European pallet procurement landscape.
Segmentation dimensions modeled span product type, end-user industry, distribution channel, and geographic production cluster across the projection horizon. CAGRs derive from time-series analysis of replacement demand cycles, regulatory compliance phase-in schedules, and automation adoption curves in warehouse operations. Forecast inputs incorporate ISPM-15 certification penetration rates, Baltic timber price index movements, and plastic pallet substitution elasticities in Dutch and German automated distribution centers.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal packaging waste enforcement and stable Ukrainian timber transit through Polish corridors; material deviation would warrant model refresh. Specific risk factors include abrupt ECHA REACH treatment regulation changes, accelerated plastic pallet cost parity, and Baltic spruce bark beetle damage expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Canada Pallets Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Wooden Pallet Collars Market