
 Copper Busbar and Profiles Market | 2026-2036
Copper Busbar and Profiles Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Busbar and Profiles Market Outlook
Project finance for utility-scale renewable installations is tilting procurement power toward developers with balance-sheet capacity to lock in multi-year copper supply contracts. ABB Ltd. anchors its position through captive extrusion capacity across European manufacturing hubs. Schneider Electric SE leverages its integrated switchgear-busbar architecture to control specification channels in data center builds. Southwire Company competes on rolling-mill scale, sustaining cost advantages in flat bar production for North American utilities.
Copper busbar and profiles are elongated conductive components, typically extruded or rolled from electrolytic tough pitch copper with conductivity exceeding 100% IACS, engineered to distribute high-current electricity with minimal resistive loss across switchgear, transformers, and power distribution assemblies. The flat bar segment dominates volume due to its ubiquity in switchboard and panel board construction, while profiles are gaining share in electric vehicle battery pack architectures where space-constrained bussing solutions command premium positioning. Among fabrication methods, extrusion leads in structural complexity for custom profiles, whereas rolling sustains throughput economics for standardized flat and round bar geometries.
US utilities navigate NERC reliability standards and EPA environmental compliance that mandate traceable copper sourcing and fire-resistant insulation ratings in substation deployments. India's BIS certification requirements for electrical conductors are tightening testing protocols, reshaping import eligibility for Southeast Asian suppliers. China's GB/T 5585 standards govern dimensional tolerances and conductivity benchmarks that determine domestic market access. Stakeholders must monitor how evolving grid interconnection codes and carbon-border adjustment mechanisms will reshape supplier qualification criteria and regional sourcing strategies.
Market Dynamics
Rack power densities in hyperscale data centers are forcing busbar specification upgrades from 600A to 1200A+ ratings, compressing procurement cycles and favoring suppliers with captive extrusion capacity.
Growth Catalysts
- Data center power infrastructure:AI training clusters are driving 48V DC busbar deployment at rack densities exceeding 50kW per cabinet, creating specification pull for high-conductivity flat bar configurations.
- India's western industrial corridor:Transmission projects from Gujarat to Maharashtra are accelerating procurement cycles for 132kV and 220kV substation busbar assemblies.
- China's GB/T 5585 conductivity standards:Tightening purity requirements above 100% IACS are filtering domestic suppliers and redirecting import demand toward certified Southeast Asian producers.
Market Restraints
- Copper price volatility:LME cathode pricing swings above 15% annually are compressing fabrication margins and forcing pass-through contract structures that deter long-term project financing.
- Chilean concentrate supply concentration:Over 60% of global mined copper originates from the Atacama region, exposing downstream busbar producers to export quota disruptions and water-access disputes.
- Aluminum busbar substitution:Weight-sensitive EV battery pack designers are specifying aluminum laminated busbar for cells above 150Ah, displacing copper in volume applications below 400A continuous rating.
Strategic Opportunities
- Vietnam's emerging fabrication base:New extrusion capacity in Binh Duong province offers tariff-advantaged export positioning for North American data center contractors seeking China+1 sourcing.
- Fire-resistant insulation mandates:IEC 61439-6 switchgear standards are creating specification pull for wrapped busbar with halogen-free insulation ratings above 850°C glow wire test thresholds.
- Digital twin integration:Convergence of 3D thermal modeling with extrusion die design is virtualizing prototyping cycles and compressing custom profile development from 12 weeks to under 4 weeks.
Industry Challenges
- Extrusion die engineering expertise:The shortage of tool-and-die craftsmen capable of machining complex hollow profiles with 0.1mm wall tolerance is constraining custom order fulfillment at European specialty houses.
- Multi-standard certification burden:Simultaneous compliance with UL 857, IEC 61439, and India's BIS IS 1897 requires parallel testing protocols that extend product qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Busbar and Profiles Market |
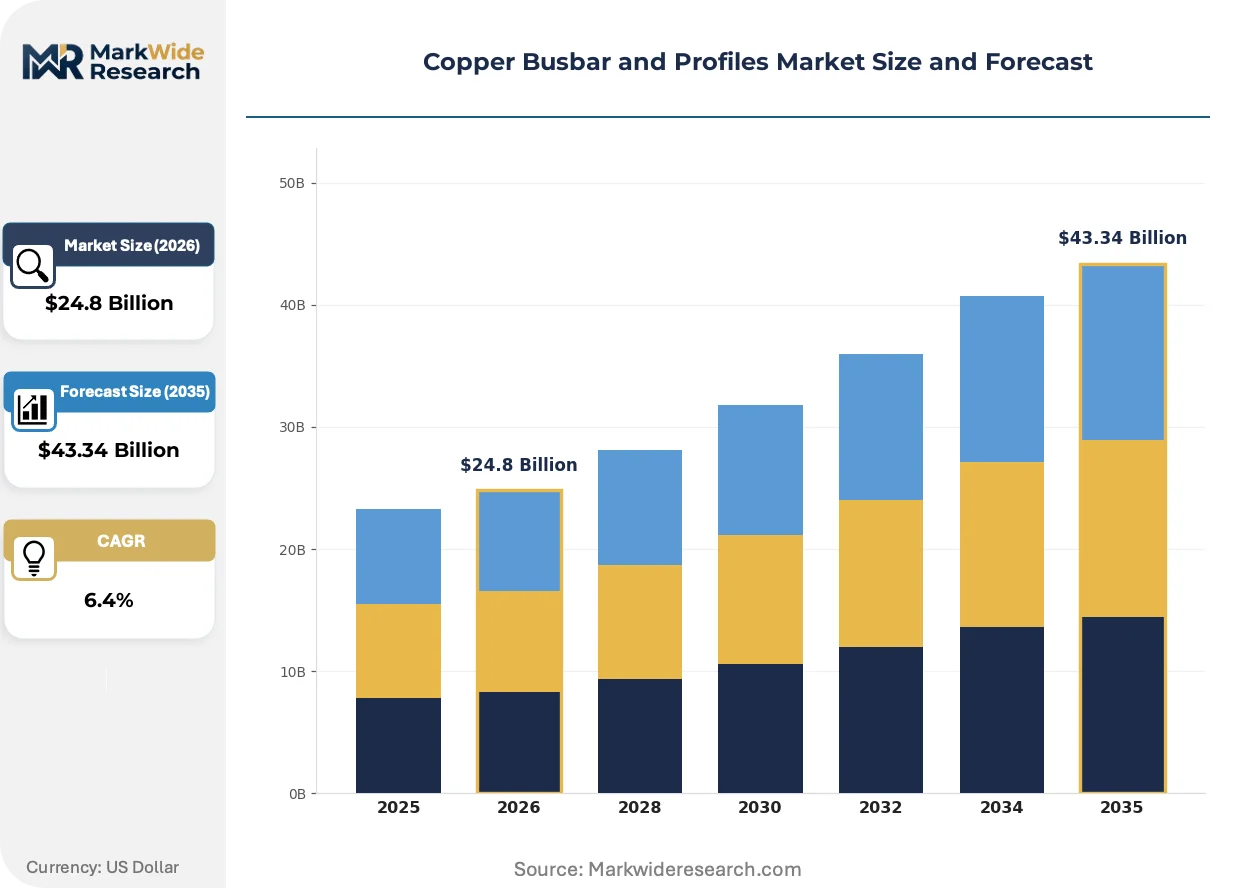
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bar, Round Bar, Profiles, Rod Application: Power Distribution, Automotive, Renewable Energy, Industrial Equipment End User: Utilities, Manufacturers, Construction, Telecommunications Fabrication Method: Extrusion, Casting, Rolling, Cutting |
| Companies Covered | TE Connectivity Ltd., ABB Ltd., Southwire Company, KME Group S.p.A., Hitachi Metals Ltd., Prysmian S.p.A., Schneider Electric SE, Pentair, Nexans S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Busbar and Profiles Market Strategic Shifts
Digital fabrication methods and material science advances are compressing development timelines while regulatory pressure on fire safety and carbon intensity is reshaping specification criteria across end-use verticals.
Additive manufacturing of copper-tungsten gradient materials is virtualizing thermal management in high-current switchgear applications. ABB and Schneider Electric pilot programs are validating laser powder bed fusion for complex busbar geometries that conventional extrusion cannot achieve. This technology is virtualizing the trade-off between conductivity and mechanical strength that has constrained profile design for decades.
REACH Annex XVII restrictions on halogenated flame retardants are mandating migration to magnesium hydroxide insulation systems in European switchgear builds. The regulation forces reformulation of PVC and XLPE wrapping compounds and accelerates qualification of silicone-based alternatives. German KBA type-approval processes for rail traction equipment are now rejecting legacy insulation chemistries that passed certification as recently as 2022.
Consolidated procurement by hyperscale data center operators is compressing supplier bases and unbundling after-sales service from hardware supply. Meta and Microsoft are specifying 10-year performance warranties with embedded thermal monitoring, displacing traditional distributor stocking models. This pattern is most visible in Northern Virginia's Data Center Alley, where direct OEM contracts now capture over 70% of busbar volume.
Copper Busbar and Profiles Market Segmentation
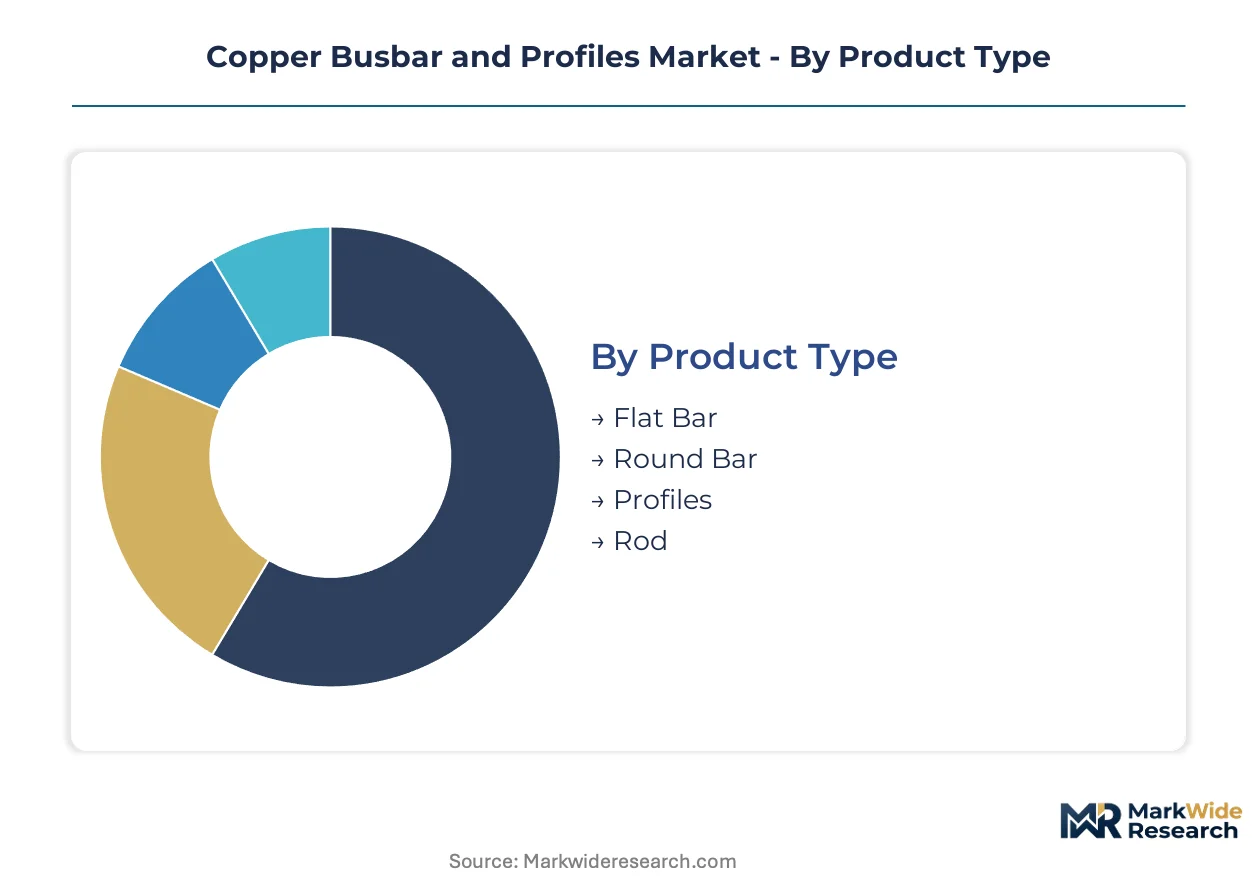
Copper busbar and profiles serve divergent technical requirements across power infrastructure, mobility, and industrial automation. Segmentation reveals how fabrication economics and conductivity specifications channel procurement decisions toward distinct supply bases.
Product Type:
Cost tier stratification separates high-volume standardized geometries from precision-engineered custom profiles commanding specification premiums.
- Flat Bar:Rolled electrolytic tough pitch copper with 100% IACS conductivity minimum serves switchboard and panel board construction. Procurement concentrates in North American utilities upgrading 600A to 1200A substation ratings under NERC reliability mandates.
- Profiles:Extruded hollow and channel geometries accommodate space-constrained battery pack architectures. Demand clusters in European EV manufacturing where 48V bussing solutions require 0.1mm wall tolerance capabilities.
- Round Bar:Standardized diameters for transformer winding applications.
- Rod:Feedstock for downstream fabrication and continuous casting operations.
Flat bar commands the established base. The steepest expansion runs through profiles.
Application:
End-use voltage levels and thermal cycling requirements determine conductivity thresholds and insulation specifications.
- Power Distribution:High-current busbar assemblies for switchgear and substations. Procurement accelerates in India's western industrial corridor from Gujarat to Maharashtra where 132kV and 220kV transmission projects compress delivery timelines.
- Automotive:Battery interconnects and inverter bussing for electrified powertrains. Aluminum substitution pressures copper below 400A continuous rating in cell designs above 150Ah.
- Renewable Energy:Inverter and collector system connections for utility-scale solar and wind installations.
- Industrial Equipment:Motor control centers and heavy machinery power feeds.
Power distribution absorbs the majority volume. Automotive applications are climbing the fastest.
End User:
Customer procurement sophistication ranges from standardized catalog purchasing to embedded thermal monitoring with decade-long performance warranties.
- Utilities:Transmission and distribution operators with multi-year supply contracts. US utilities navigate EPA environmental compliance and traceable copper sourcing requirements under federal procurement guidelines.
- Manufacturers:OEMs integrating busbar into switchgear, EV battery packs, and industrial drives. Direct contracting now captures over 70% of hyperscale data center volume in Northern Virginia's cluster.
- Construction:Commercial and infrastructure electrical contractors.
- Telecommunications:Data center power distribution and 5G edge computing facilities.
Utilities anchor the revenue base. Telecommunications infrastructure is expanding most quickly.
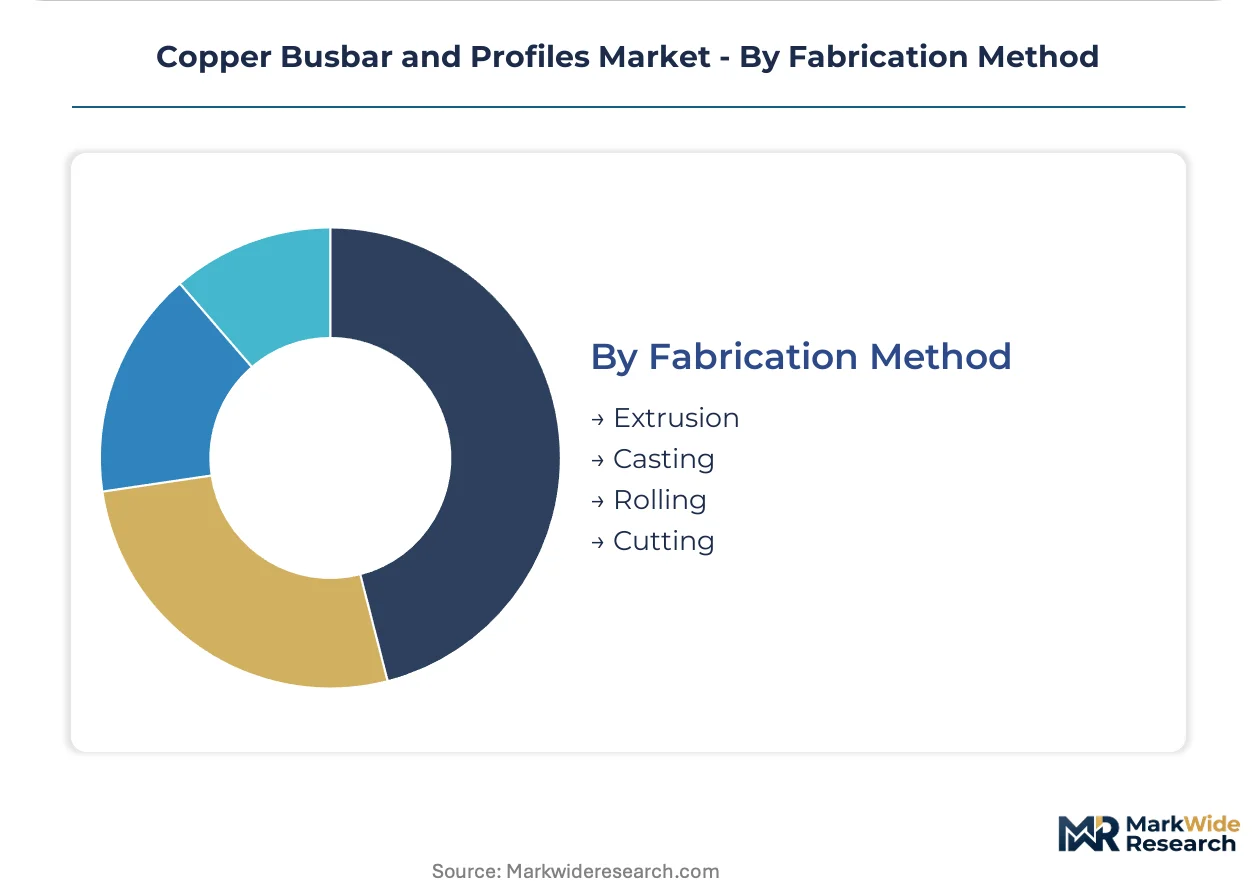
Fabrication Method:
Process selection trades structural complexity against throughput economics and die engineering lead times.
- Extrusion:Hot-forming through shaped dies achieves hollow profiles and complex cross-sections. European specialty houses face tool-and-die craftsman shortages constraining custom order fulfillment.
- Rolling:Continuous reduction mills sustain cost advantages for flat bar production. Southwire Company leverages rolling-mill scale for North American utility procurement.
- Casting:Continuous and sand casting for ingot and semi-finished feedstock.
- Cutting:Precision sawing and shearing for length specification.
Rolling dominates standardized output. Extrusion is gaining share fastest in custom applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in copper busbar and profiles are tilting toward fabrication hubs with tariff-advantaged export positioning. Import dependency is concentrating in markets with accelerating transmission buildouts and tightening domestic purity standards.
United States
NERC reliability mandates are compressing procurement timelines for 600A to 1200A substation upgrades. EPA traceable sourcing requirements and fire-resistant insulation ratings govern substation deployments. Northern Virginia's Data Center Alley now captures over 70% of regional busbar volume through direct OEM contracting.
China
GB/T 5585 standards are tightening conductivity benchmarks above 100% IACS, filtering domestic supplier bases. MIIT oversight of electrical equipment certification is redirecting import demand toward certified Southeast Asian producers. Yangtze River Delta extrusion capacity serves domestic switchgear and EV battery pack manufacturers.
India
Transmission projects from Gujarat to Maharashtra are accelerating 132kV and 220kV substation procurement cycles. BIS certification requirements under IS 1897 are tightening testing protocols for electrical conductors. Western industrial corridor demand is concentrating procurement power with developers holding multi-year supply contract capacity.
Germany
REACH Annex XVII restrictions on halogenated flame retardants are mandating magnesium hydroxide insulation migration. KBA type-approval processes for rail traction equipment are rejecting legacy chemistries certified as recently as 2022. Industrial clusters in North Rhine-Westphalia anchor European switchgear specification channels.
Vietnam
New extrusion capacity in Binh Duong province offers tariff-advantaged export positioning for North American data center contractors. Emerging fabrication infrastructure serves China+1 sourcing strategies. Binh Duong's industrial zones are attracting busbar specialists seeking alternative supply chain origination points.
Copper Busbar and Profiles Market Competitive Environment
On the supply side, the industry is consolidating around fabricators with captive upstream capacity and specification control through integrated architectures. Three archetypes dominate: diversified electrical equipment conglomerates with switchgear-busbar integration, scale-driven rolling-mill operators serving utility procurement, and specialty extrusion houses focused on custom profile tolerances. Competitive positioning hardens through backward integration into copper cathode sourcing and die engineering capability acquisition.
Among diversified electrical equipment conglomerates, ABB Ltd. and Schneider Electric SE exemplify the integrated architecture archetype, anchoring specification channels through captive manufacturing presence. Southwire Company occupies a position representing scale-driven rolling-mill specialization for standardized geometries. These three entities illustrate how competitive positioning stratifies between integrated system control, throughput economics, and precision fabrication expertise.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| ABB Ltd. |
| Southwire Company |
| KME Group S.p.A. |
| Hitachi Metals Ltd. |
| Prysmian S.p.A. |
| Schneider Electric SE |
| Pentair |
| Nexans S.A. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese extrusion hubs is compressing fabrication margins and forcing pass-through contract structures that deter long-term project financing. This utilization imbalance concentrates pricing power with rolling-mill operators in North America while squeezing specialty European houses dependent on custom die engineering.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with spot-market adjustments for copper cathode pass-through. Price differentiation separates IEC 61439-6 certified wrapped busbar from standard uninsulated flat bar, with volume scale and halogen-free insulation ratings commanding premiums. Cost compression in standard flat bar is intensifying because aluminum substitution pressures copper below 400A continuous rating. Utilities with multi-year supply agreements exhibit lowest price sensitivity, while commercial contractors in India's western corridor face acute margin pressure.
Supply Chain Analysis
Extended payment terms from hyperscale data center operators are straining working capital at mid-tier extrusion houses and accelerating consolidation toward balance-sheet-heavy conglomerates. Raw material sourcing draws from Chilean concentrate, Chinese cathode refining, and Southeast Asian scrap recovery, with fabrication concentrated in China, Vietnam, and Germany. Single-source vulnerability concentrates in Atacama region mining exposure. Distribution runs through direct OEM contracting for data center volumes and distributor stocking for utility maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against aluminum laminated busbar displacement in EV battery packs above 150Ah, where weight-sensitive designers are specifying copper only above 400A continuous rating.
For Market Incumbents: Entrench specification control through captive extrusion capacity and embedded thermal monitoring warranties that aluminum alternatives cannot match. Prioritize backward integration into copper cathode sourcing to neutralize LME volatility pass-through. Defend against Vietnam-based China+1 entrants by accelerating fire-resistant insulation certification under IEC 61439-6. For New Entrants and Emerging Players: Build out tariff-advantaged extrusion capacity in Binh Duong province to capture North American data center procurement seeking geographic diversification. Target Vietnam's emerging fabrication base with direct contracting models that bypass traditional distributor channels. Lead with digital twin integration capabilities that compress custom profile development timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated switchgear-busbar architecture providers with decade-long performance warranties. Long-term viability hinges on die engineering expertise scarcity and multi-standard certification barriers that protect incumbent positioning. Monitor aluminum busbar penetration rates in European EV manufacturing as inflection indicator for copper displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Cathode | Neutralizes LME volatility exposure for ABB and Schneider Electric contract structures. |
| Fire-Resistant Insulation Certification | REACH Annex XVII compliance secures German rail traction equipment specification channels. |
| Digital Twin Integration | Virtual prototyping compression from 12 weeks to 4 weeks accelerates custom order fulfillment. |
| Geographic Capacity Expansion | Binh Duong extrusion buildout captures China+1 sourcing for Northern Virginia data centers. |
| Long-Term Supply Agreement | Multi-year contracts with India's western corridor developers lock in procurement power. |
Study Parameters
Operator-level perspectives from switchgear procurement managers, extrusion plant engineers, data center power infrastructure directors, and utility transmission planners anchored the qualitative base. These interviews combined with secondary validation from customs trade data, SEC filings of electrical equipment conglomerates, BIS certification registries, and IEC standard documentation. Bottom-up and top-down triangulation cross-checked fabrication capacity estimates against end-use demand aggregation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by product type, application voltage level, fabrication method, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted demand curves incorporating copper price volatility assumptions and substitution elasticity parameters. Forecast inputs included rack density trajectories in hyperscale facilities and GB/T 5585 conductivity standard enforcement timelines.
Practitioners should monitor Chilean concentrate export quotas, REACH insulation chemistry restrictions, and aluminum busbar technical qualification for early signals of supply disruption or demand displacement. Forecasts reflect documented assumptions about copper price bands and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market