
 Global Fixed Resistor Market | 2026-2036
Global Fixed Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fixed Resistor Market Analysis
Thick film ruthenium oxide is broadening its addressable market as manufacturers substitute away from palladium-based formulations to manage precious metal cost volatility. Vishay Intertechnology leverages vertical integration across substrate production and laser trimming to sustain margin control in precision grades. Panasonic Corporation anchors high-volume supply to Japanese automotive tier-1 suppliers through captive ceramic substrate capacity. Yageo Corporation competes aggressively on scale in chip resistor production across Greater China manufacturing complexes.
Fixed resistors are passive electronic components that provide precise, stable opposition to current flow, typically manufactured from metal alloys, carbon compositions, or metal oxide films deposited on ceramic substrates and trimmed to tolerance within 0.1% or tighter. Their primary purpose spans voltage division, current limiting, signal conditioning, and bias stabilization across virtually every electronic circuit assembly. Metal film resistors command premium positioning in instrumentation and medical electronics where thermal stability and low noise coefficients justify higher unit economics. Wirewound construction retains dominance in high-power industrial motor drives and braking applications where surge tolerance exceeds 50 watts. Surface mount form factors now represent the dominant physical configuration, displacing through-hole insertion in consumer electronics and telecommunications hardware.
RoHS directives from the European Commission restrict cadmium and lead in termination finishes, compelling reformulation of solderable coatings across export-bound production lines. China's GB standards and MIIT administrative rules enforce parallel substance restrictions while promoting domestic NTC thermistor and precision resistor self-sufficiency. The US EPA and OSHA maintain workplace exposure limits on hexavalent chromium in plating processes that affect wirewound resistor manufacturing. Stakeholders must monitor raw material substitution timelines, qualification cycles for automotive AEC-Q200 compliance, and regional sourcing mandates that fragment previously centralized supply strategies.
Market Dynamics
Automotive electrification is compressing qualification timelines for precision resistors as OEMs demand AEC-Q200 compliance within 18-month product cycles rather than traditional 36-month horizons. This acceleration is forcing upstream substrate and thin-film deposition capacity to reconfigure around automotive-grade reliability rather than consumer electronics cost curves.
Growth Catalysts
- EV Power Electronics:Battery management systems and onboard chargers require precision metal film resistors with thermal coefficients below 25 ppm per degree Celsius. Automotive tier-1 suppliers in Germany and Japan are qualifying new resistor families for 800-volt architectures.
- RoHS Material Substitution:REACH restrictions on lead and cadmium in termination finishes are accelerating tin-bismium and nickel-palladium-gold plating adoption across European export-bound production lines.
- Thick Film Ruthenium Oxide:Manufacturers are substituting palladium-based formulations with ruthenium oxide to manage precious metal cost volatility in high-volume chip resistor production.
Market Restraints
- Palladium Price Volatility:Thick film resistor formulations depend on palladium silver conductor pastes, exposing margin structures to London Metal Exchange price swings that resistor makers cannot pass through immediately.
- Substrate Concentration:High-purity alumina ceramic substrate production concentrates in Japanese and Chinese suppliers, creating single-source risk for precision grades requiring 96% alumina or higher.
- Wirewound Power Density Limits:Industrial motor drives above 100 watts require wirewound construction that cannot be surface-mounted, constraining miniaturization in high-power applications.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and passive component production are attracting resistor packaging and testing investments to Gujarat and Tamil Nadu industrial corridors.
- Medical Imaging Upgrades:CT and MRI equipment refreshes in North American hospital systems are driving demand for ultra-stable metal foil resistors with 0.01% tolerance and sub-5 ppm thermal tracking.
- 5G Infrastructure Deployment:Massive MIMO base station rollouts in South Korea and China require high-frequency thin film resistors with minimal parasitic capacitance for millimeter-wave signal conditioning.
Industry Challenges
- Laser Trimming Talent Scarcity:Precision resistor manufacturing requires operators skilled in YAG laser ablation calibration, a competence pool concentrated in aging workforces at Japanese and European facilities.
- AEC-Q200 Certification Duration:Automotive qualification protocols demand 1,000-hour high-temperature operating life testing and temperature cycling across 1,000 cycles, extending new product introduction timelines.
- Legacy Through-Hole Obsolescence:Contract manufacturers face equipment retooling costs as axial and radial resistor formats decline below economically viable production batch sizes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fixed Resistor Market |
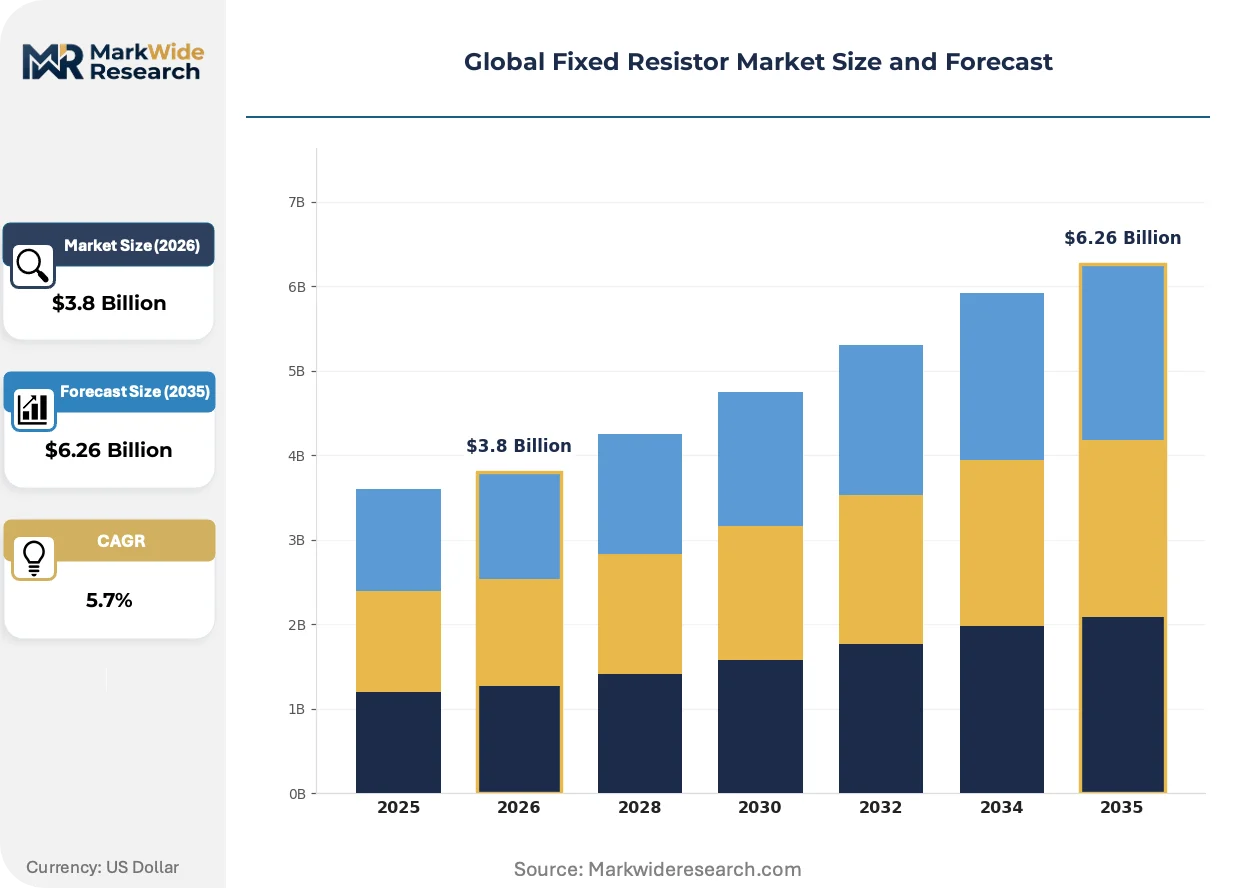
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Carbon Film, Metal Film, Wirewound, Thick Film Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications Power Rating: Low Power, Medium Power, High Power, Ultra High Power Form Factor: Through Hole, Surface Mount, Chip Resistors, Network Resistors |
| Companies Covered | Vishay Intertechnology, Panasonic Corporation, TE Connectivity, Yageo Corporation, ROHM, Bourns, Murata Manufacturing, KOA Corporation, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fixed Resistor Market Emerging Trajectories
Thin film deposition techniques are migrating from batch sputtering to continuous reel-to-reel processing, collapsing unit economics for precision grades while demanding new capital equipment configurations. This process shift is redrawing competitive boundaries between captive substrate producers and merchant thin film houses.
Thick film ruthenium oxide resistor formulations are consolidating market share in general-purpose applications as palladium silver pastes face sustained cost pressure. Industrial controls and white goods manufacturers in China and Southeast Asia are specifying ruthenium oxide for 5% tolerance grades previously dominated by carbon film. The technology is consolidating procurement specifications across mid-tier electronics assemblers who previously maintained dual-qualified material lists.
ECHA REACH candidate list expansions for Substances of Very High Concern are forcing termination metallurgy redesigns across European-bound production. Hexavalent chromium plating for wirewound resistor end caps faces sunset dates under authorization requirements, compelling nickel-tin and pure tin alternatives with inferior solderability profiles. German automotive suppliers are qualifying laser-marked ceramic cores to eliminate ink-based identification containing restricted solvents.
Consolidated procurement by Chinese EMS giants is compressing resistor supplier margins while demanding vendor-managed inventory commitments. Foxconn and BYD Electronics are consolidating passive component spend through centralized commodity management offices in Shenzhen, displacing traditional distributor relationships. This concentration is most visible in Greater China, where domestic resistor manufacturers now negotiate directly with platform assemblers for 52-week blanket orders with monthly pull schedules.
Global Fixed Resistor Market Segmentation
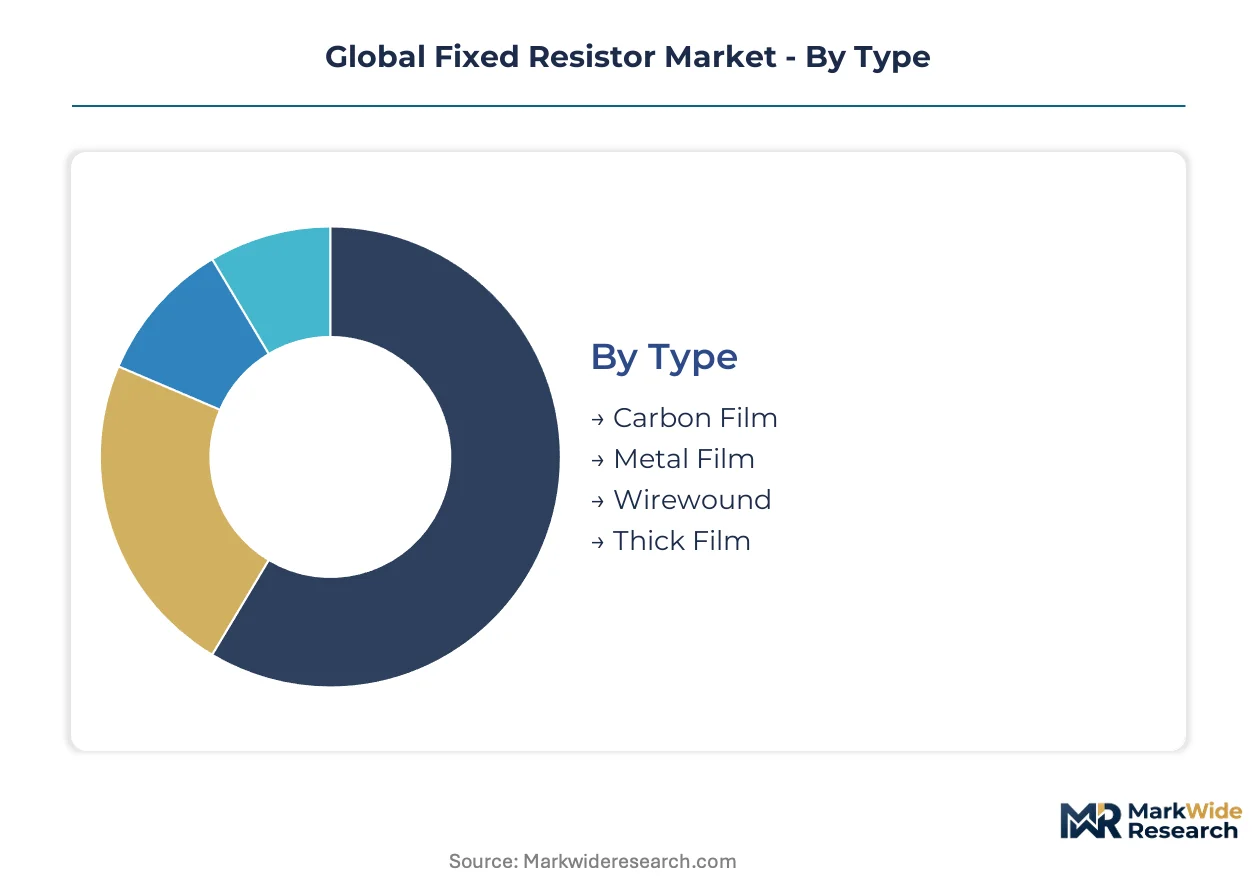
Fixed resistor segmentation reveals how manufacturers balance precision requirements against cost constraints across divergent end-use specifications. Technical differentiation in film composition and physical packaging determines margin capture and customer lock-in across automotive, industrial, and consumer electronics verticals.
Type:
Customization intensity varies sharply across resistor technologies, from commodity carbon formulations to precision metal films requiring proprietary deposition control.
- Metal Film:Nickel-chromium or tin-oxide thin films deposited on alumina substrates deliver temperature coefficients below 50 ppm per degree Celsius. Demand concentrates in German and Japanese automotive tier-1 suppliers qualifying 800-volt battery management systems for EV platforms.
- Thick Film:Ruthenium oxide or palladium-silver pastes screen-printed on ceramic substrates dominate high-volume consumer electronics. Chinese white goods and industrial control manufacturers are consolidating procurement specifications around ruthenium oxide to escape London Metal Exchange palladium volatility.
- Carbon Film:Pyrolytically deposited carbon layers on ceramic rods serve cost-sensitive applications with 5% tolerance requirements.
- Wirewound:Resistance wire wound on ceramic or fiberglass cores handles surge tolerance above 50 watts in motor drives and braking systems.
Leading the category by volume: Thick Film. Expanding most quickly: Metal Film.
Application:
End-use specifications fragment the market across reliability tiers, with automotive AEC-Q200 compliance demanding fundamentally different validation protocols than consumer electronics.
- Automotive:Battery management systems, onboard chargers, and inverter controls require precision resistors with 0.1% tolerance and thermal stability across -55°C to 155°C operating ranges. OEMs in Germany, Japan, and China are compressing qualification timelines from 36 months to 18 months for new resistor families.
- Consumer Electronics:Smartphones, tablets, and wearables drive surface-mount chip resistor consumption at extreme scale. Foxconn and BYD Electronics in China negotiate 52-week blanket orders with monthly pull schedules, compressing supplier margins while demanding vendor-managed inventory commitments.
- Industrial Equipment:Motor drives, power supplies, and automation systems specify wirewound and thick film resistors for surge tolerance and long-term stability.
- Telecommunications:5G massive MIMO base stations in South Korea and China require thin film resistors with minimal parasitic capacitance for millimeter-wave signal conditioning.
Highest specification intensity: Automotive. Steepest volume expansion: Consumer Electronics.
Power Rating:
Dissipation requirements stratify manufacturing processes, with thermal management becoming the dominant design constraint above 50 watts.
- Low Power:Surface-mount chip resistors below 0.25 watts dominate smartphone and IoT device assembly. Chinese EMS giants consolidate procurement through centralized commodity management offices in Shenzhen.
- High Power:Wirewound and aluminum-housed resistors above 5 watts serve industrial motor drives and braking applications where surge tolerance exceeds 50 watts. Japanese suppliers anchor supply to domestic automotive and industrial equipment manufacturers.
- Medium Power:Thick film and metal film resistors between 0.25 and 5 watts bridge consumer and industrial applications.
- Ultra High Power:Custom wirewound assemblies above 100 watts require through-hole mounting and active cooling in heavy industrial and traction systems.
Volume concentration: Low Power. Margin expansion: High Power.
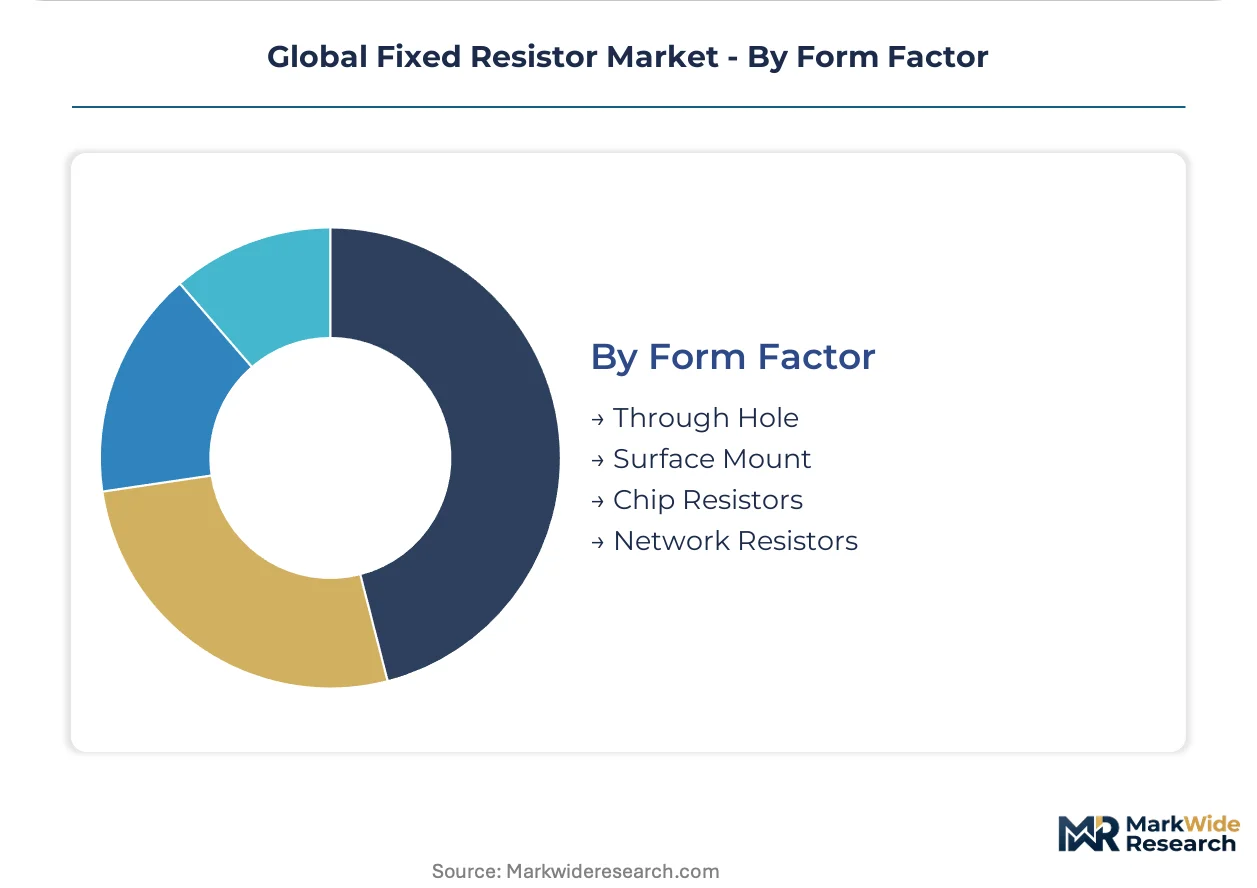
Form Factor:
Physical packaging determines assembly automation compatibility and dictates substrate material selection across insertion and surface-mount technologies.
- Surface Mount:Rectangular chip resistors with wraparound terminations enable high-speed pick-and-place assembly in consumer electronics and telecommunications hardware. Reel-to-reel processing is collapsing unit economics for precision grades while demanding new capital equipment configurations.
- Through Hole:Axial and radial leaded resistors persist in industrial equipment, automotive legacy systems, and repair markets. Contract manufacturers face equipment retooling costs as batch sizes decline below economically viable thresholds.
- Chip Resistors:Standardized 0402 to 2512 case sizes represent the dominant physical configuration across high-volume electronics assembly.
- Network Resistors:Integrated resistor arrays reduce board space in dense digital circuits and bus termination applications.
Unit volume leader: Chip Resistors. Technology transition: Through Hole to Surface Mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the majority of fixed resistor demand as domestic automotive electronics manufacturing scales rapidly. German and Japanese automotive tier-1 suppliers anchor precision metal film consumption for EV power electronics. Contract manufacturers in Vietnam and India are absorbing overflow capacity as Chinese EMS giants consolidate procurement.
China
Domestic battery management system production for BYD and CATL supply chains drives precision resistor qualification at automotive-grade tolerances. MIIT administrative rules and GB standards enforce RoHS-parallel substance restrictions while promoting NTC thermistor and precision resistor self-sufficiency. Manufacturing clusters in Shenzhen and Dongguan host Foxconn and BYD Electronics commodity management offices negotiating 52-week blanket orders.
Germany
Bosch and Continental are compressing AEC-Q200 qualification timelines to 18 months for 800-volt EV architectures. REACH restrictions on lead and cadmium in termination finishes accelerate tin-bismuth and nickel-palladium-gold plating adoption across export-bound production lines. Industrial corridors in Bavaria and Baden-Württemberg concentrate laser trimming competence for sub-25 ppm thermal coefficient resistors.
Japan
Captive ceramic substrate capacity at Tokyo and Osaka-area manufacturers anchors high-volume supply to domestic automotive tier-1 suppliers. METI industrial policy supports precision component manufacturing as a strategic sector amid supply chain security concerns. Nagoya and Kyoto facilities concentrate YAG laser ablation calibration expertise for 0.1% tolerance grades.
United States
CT and MRI equipment refreshes in hospital systems drive demand for ultra-stable metal foil resistors with 0.01% tolerance. EPA and OSHA workplace exposure limits on hexavalent chromium in plating processes affect wirewound resistor manufacturing configurations. Greater Boston and Silicon Valley clusters concentrate medical electronics and telecommunications hardware design-in activity.
India
PLI scheme incentives for semiconductor and passive component production attract resistor packaging and testing investments. Central Electricity Authority regulations and BIS standards govern electrical component safety and performance specifications for domestic market access. Gujarat and Tamil Nadu industrial corridors host emerging EMS operations serving automotive and industrial equipment export markets.
Global Fixed Resistor Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive substrate producers commanding premium positioning in automotive-grade precision while merchant houses compete on scale in consumer electronics. The vendor base organizes around three strategic archetypes: vertically integrated substrate-to-component manufacturers, precision-focused thin film specialists, and high-volume chip resistor scale operators. Consolidation pressure intensifies as automotive qualification costs rise and Chinese EMS procurement centralization compresses margins. Competitive moves concentrate on backward integration into alumina ceramic production and reel-to-reel deposition capacity expansion.
Among Japanese precision specialists, Panasonic Corporation and KOA Corporation exemplify the captive substrate archetype, leveraging in-house ceramic production to sustain margin control in AEC-Q200 qualified grades. Vishay Intertechnology anchors the vertically integrated model with upstream control over substrate manufacturing and laser trimming operations. Yageo Corporation represents the scale-driven competitive position, competing aggressively across Greater China manufacturing complexes for high-volume consumer electronics supply.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Panasonic Corporation |
| TE Connectivity |
| Yageo Corporation |
| ROHM |
| Bourns |
| Murata Manufacturing |
| KOA Corporation |
| ON Semiconductor |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists concentrated in Japan and Germany anchor pricing discipline through captive ceramic substrate production, insulating precision grades from the margin erosion that merchant houses face in high-volume consumer electronics supply. This ownership structure sustains long-term investment horizons for AEC-Q200 qualification cycles while limiting price responsiveness to palladium volatility on London Metal Exchange spot markets.
Pricing Analysis
Volume-mid-economy pricing differentiation separates automotive-grade precision resistors from commodity consumer electronics supply. Metal film and wirewound constructions command premium positioning through AEC-Q200 certification and sub-25 ppm thermal coefficients, while thick film ruthenium oxide competes on scale in 5% tolerance grades. Pricing pressure stems from Chinese EMS procurement centralization at Foxconn and BYD Electronics commodity management offices, where 52-week blanket orders compress supplier margins. Consumer electronics buyers exhibit highest price sensitivity, whereas German and Japanese automotive tier-1 suppliers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Laser trimming operator scarcity in Nagoya and Kyoto facilities constrains capacity expansion for 0.1% tolerance grades, tethering precision output to aging Japanese workforces. High-purity alumina ceramic substrate production concentrates in Japanese and Chinese suppliers, with 96% alumina grades drawing from single-source configurations. Ruthenium oxide and palladium-silver pastes rest on London Metal Exchange price volatility, while nickel-chromium thin films hinge on specialty alloy mill capacity. Single-source vulnerability persists in automotive-grade substrate supply. Distribution runs through centralized commodity management offices at Shenzhen-based EMS giants, displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AEC-Q200 automotive qualification protocols function as a cost-of-compliance moat, extending new product introduction timelines through 1,000-hour high-temperature operating life testing that excludes undercapitalized entrants from EV power electronics supply.
For Market Incumbents: Acquire reel-to-reel thin film deposition capacity to collapse unit economics for precision grades before merchant houses replicate the technology shift. Backward integration into alumina ceramic production defends margin control against Japanese and Chinese substrate concentration, while expanding captive laser trimming capacity in Bavaria and Baden-Württemberg industrial corridors counters workforce scarcity threats from aging Nagoya operator pools. For New Entrants and Emerging Players: Tier-2 automotive suppliers in India offer penetrable entry points where PLI scheme incentives attract packaging and testing investments without incumbent qualification backlogs. Medical imaging resistor demand in North American hospital systems presents white-space opportunity for ultra-stable metal foil specialists with 0.01% tolerance capability. Direct engagement with Gujarat and Tamil Nadu EMS operations bypasses Shenzhen procurement centralization. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-focused thin film specialists with existing AEC-Q200 qualification libraries in Germany and Japan, where automotive electrification compresses timelines but sustains long-term contract visibility. The 5-10 year viability window favors substrate-to-component integrated manufacturers over merchant scale operators exposed to Chinese EMS margin compression. Watch for palladium price inflection as signal for ruthenium oxide formulation consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Substrate Production | Captive 96% alumina supply insulates Panasonic and KOA from Japanese-Chinese concentration risk. |
| Reel-to-Reel Thin Film Deposition Expansion | Continuous processing collapses unit economics for metal film grades competing with batch sputtering. |
| AEC-Q200 Certification Acceleration | 18-month qualification cycles at Bosch and Continental lock out undercapitalized resistor entrants. |
| Termination Metallurgy Redesign | Tin-bismuth and nickel-palladium-gold plating adoption satisfies REACH restrictions on European-bound production. |
| Vendor-Managed Inventory Commitments | 52-week blanket orders with Foxconn and BYD Electronics secure volume but compress supplier margins. |
Methodological Framework
Independent corroboration across resistor manufacturer technical directors, automotive tier-1 procurement leads, and EMS commodity managers underwrites the qualitative findings on qualification timeline compression. Primary interviews with ceramic substrate production heads, laser trimming operators, and thin film deposition engineers combined with secondary validation from ECHA REACH candidate list updates, MIIT administrative rule publications, and SEC 10-K filings from listed component manufacturers. Bottom-up and top-down triangulation cross-checked capacity announcements against end-use demand signals from EV platform ramp schedules.
Rate-of-change decomposition across the analysis window isolates volume growth from value expansion in thick film versus metal film segments. The analytical framework models resistor demand by type, application, power rating, and form factor, with automotive content-per-vehicle and telecommunications infrastructure deployment as industry-specific forecast inputs. CAGRs derive from installed base replacement cycles, platform transition timelines, and regional production cluster expansion trajectories rather than extrapolated historical trends.
Caveats apply where palladium price spikes, REACH authorization timeline accelerations, or Chinese domestic sourcing mandate expansions could materially shift the outlook. Forecasts reflect assumptions on substrate capacity expansion, laser trimming workforce development, and automotive platform standardization across 800-volt architectures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market