
 Plastic Film Capacitors Market | 2026-2036
Plastic Film Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Film Capacitors Market Analytics
Market Context
China is fragmenting plastic film capacitor supply chains as domestic producers expand metallized polypropylene capacity. KEMET Corporation leverages vertical integration into raw film supply to sustain margin control against Asian competitors. Nichicon Corporation anchors high-reliability automotive grades through Japanese manufacturing precision, while TDK Corporation competes aggressively in surface mount segments for consumer electronics.
Technical Definition and Segment Structure
Plastic film capacitors store electrical energy in a thin polymer dielectric layer, typically polypropylene or polyester, sandwiched between metallized electrodes, with capacitance values ranging from picofarads to microfarads and voltage ratings spanning tens to thousands of volts. These components filter noise, couple signals, and buffer power in circuits where stability and low loss prove critical. Polypropylene film dominates industrial and renewable energy applications due to superior thermal endurance and self-healing properties, while polyester variants occupy cost-sensitive consumer electronics where volumetric efficiency matters more than precision. Surface mount technology leads volume shipments for miniaturized devices, though through-hole technology retains structural importance in high-voltage renewable energy inverters where mechanical robustness prevents board flex failures.
Regulatory Framework and Outlook
China's MIIT enforces GB standards for capacitor reliability in grid-connected equipment, while the EU F-Gas Regulation and REACH restrict fluorinated compounds and hazardous substances in dielectric manufacturing. Japan's METI promotes JIS standards that govern automotive-grade capacitor qualification for electrified powertrains. Stakeholders must monitor evolving material compliance thresholds and regional certification divergence when allocating capacity across manufacturing footprints.
Market Dynamics
Powertrain electrification across automotive OEMs is compressing capacitor qualification timelines while China's dual carbon goals force raw material compliance recalibration across dielectric supply chains.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated compounds in dielectric manufacturing accelerate metallized polypropylene substitution, opening capacity for capacitor-grade film producers.
- Electric vehicle inverters:Traction power electronics demand high-temperature film capacitors with self-healing properties, pulling volume from industrial into automotive-qualified production lines.
- East Asian manufacturing clusters:Concentrated polypropylene film capacity in China, Japan, and South Korea enables just-in-time supply to consumer electronics and renewable energy inverter assemblers.
Market Restraints
- Polypropylene resin volatility:Petrochemical feedstock cost swings compress margin predictability for film extruders and metallized electrode suppliers.
- Japanese high-reliability concentration:Automotive-grade qualification expertise clusters with METI-certified producers, creating supply bottleneck for European and North American EV programs.
- Aluminum electrolytic substitution:Cost-sensitive consumer electronics buyers tolerate higher ESR in aluminum capacitors where volumetric efficiency outweighs precision requirements.
Strategic Opportunities
- India BIS certification pathway:Localized testing infrastructure for GB-equivalent standards opens duty-advantaged supply to domestic solar inverter and railway electrification projects.
- Solid-state battery integration:Next-generation traction systems require DC-link capacitors with higher ripple current endurance, favoring polypropylene film over ceramic alternatives.
- China MIIT grid reliability mandates:Forced localization of capacitor content in state-backed renewable installations creates captive demand for domestic metallized film producers.
Industry Challenges
- Automotive AEC-Q200 qualification timelines:18-24 month validation cycles for high-voltage film capacitors misalign with EV platform launch schedules, forcing parallel sourcing strategies.
- REACH substance inventory compliance:Evolving SVHC candidate list for polymer additives requires continuous reformulation of dielectric films, disrupting multi-year supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Film Capacitors Market |
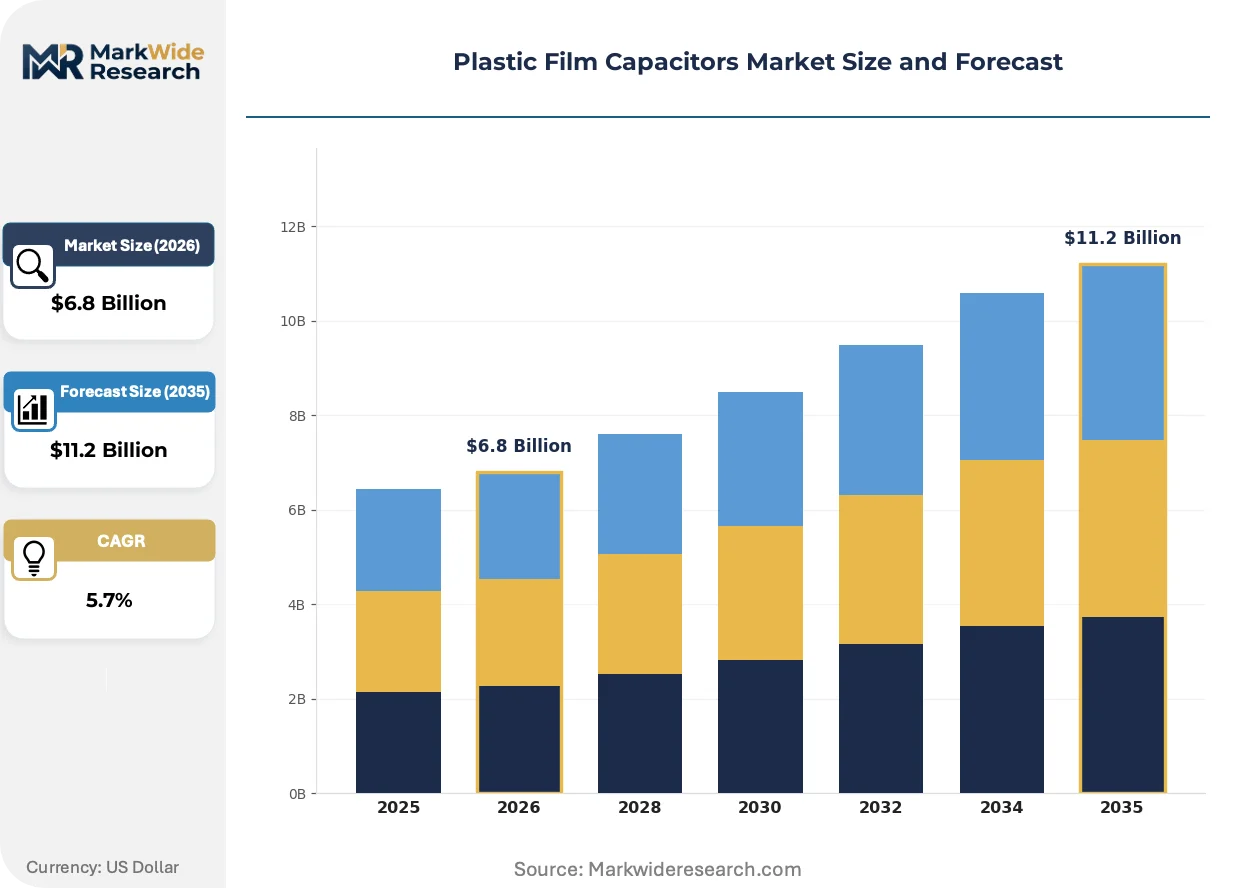
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Polyethylene Naphthalate, Others Application: Consumer Electronics, Industrial Automation, Automotive Electronics, Renewable Energy End User: Electronics Manufacturers, Automotive Companies, Energy Sector, Research Institutions Technology: Surface Mount Technology, Through-Hole Technology, Flexible Technology, Others |
| Companies Covered | KEMET Corporation, Nichicon Corporation, TDK Corporation, Cornell Dubilier Electronics, Wima GmbH & Co. KG, Vishay Intertechnology, KYOCERA AVX Components Corporation, Electro Technik Industries, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Film Capacitors Market Evolving Landscape
Capacitor manufacturers are reconfiguring product architectures around thermal endurance and miniaturization imperatives, with regulatory compliance and procurement centralization acting as concurrent forcing mechanisms.
Segmented metallization patterns in polypropylene film are collapsing the fault-current tolerance gap between standard industrial and automotive-grade capacitors. Tier-1 suppliers to EV powertrain integrators are adopting these films at compressed qualification schedules. The technology is collapsing the traditional three-tier supplier hierarchy into direct OEM-film producer relationships.
China's MIIT enforcement of GB/T standards for grid-connected inverters is mandating 85°C operational endurance minimums that exceed legacy IEC specifications. Domestic film producers are retooling extrusion lines to meet these thermal thresholds. European inverter manufacturers exporting to China must dual-certify components, adding 4-6 months to product release cycles.
Consolidated procurement by renewable energy EPCs is compressing supplier bases to single-source agreements with 3-5 year volume commitments. Tier-2 capacitor assemblers without captive film supply are exiting the solar inverter segment entirely. This concentration is most visible in Germany and Spain, where utility-scale project finance requires component traceability to qualified film extruders.
Plastic Film Capacitors Market Segmentation
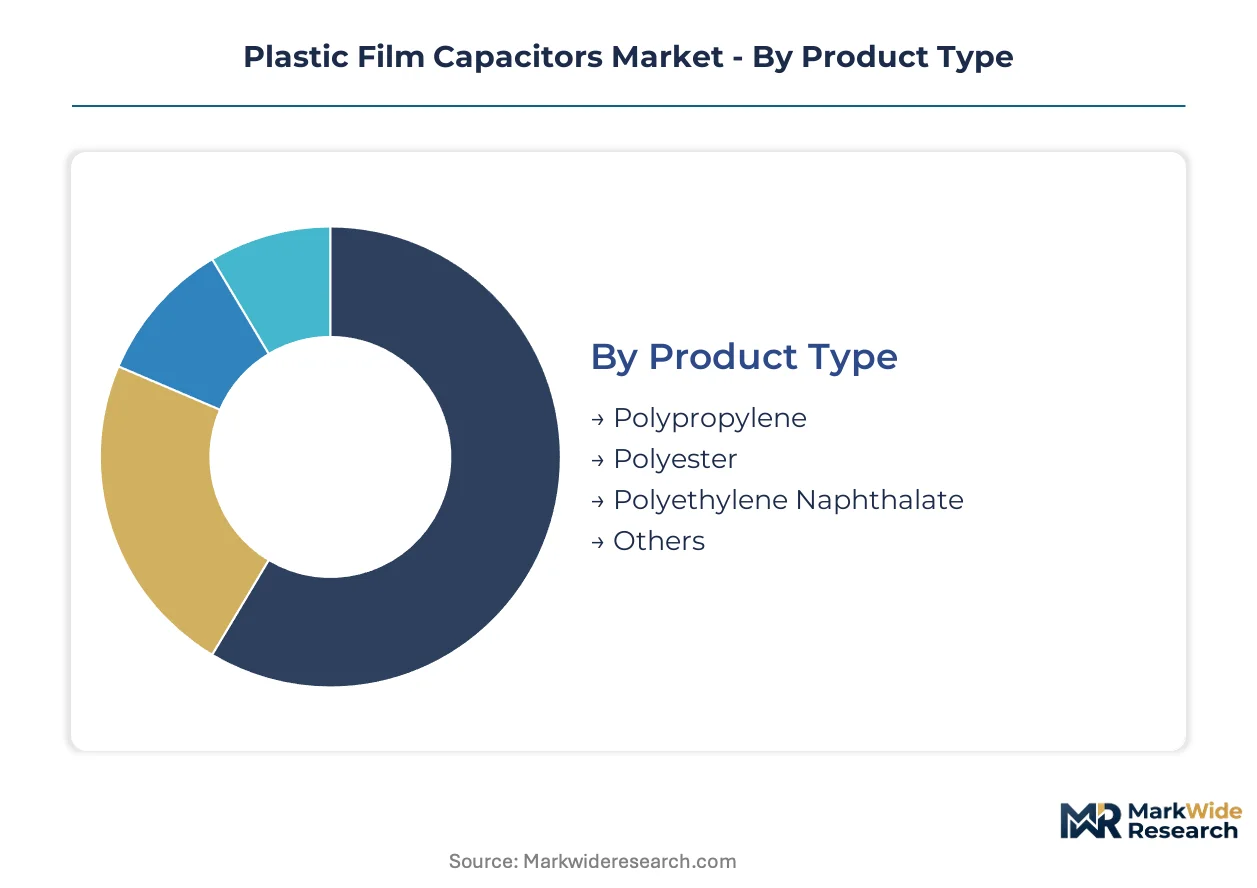
Segmentation in plastic film capacitors separates material chemistry from mounting architecture and end-use reliability requirements. Each dimension carries distinct procurement patterns and qualification barriers that reshape supplier economics.
Product Type:
Cost tier determines thermal ceiling and self-healing performance across dielectric chemistries.
- Polypropylene:Biaxially oriented polypropylene film delivers superior thermal endurance and self-healing properties under overvoltage stress. Demand concentrates in automotive traction inverters and renewable energy DC-link applications where AEC-Q200 qualification and IEC 61071 compliance compress supplier lists to Japanese and Korean metallized film producers.
- Polyester:Polyethylene terephthalate film offers higher dielectric constant and volumetric efficiency at lower unit cost. Consumer electronics assemblers in China and Taiwan specify polyester for power supply filtering where precision matters less than board space optimization.
- Polyethylene Naphthalate:PEN film bridges the thermal gap between polyester and polypropylene with 125°C operational ratings.
- Others:Polyphenylene sulfide and polycarbonate films serve niche high-frequency and precision timing circuits.
Polypropylene holds installed capacity. Polyethylene naphthalate is rotating up the share rankings.
Application:
Application scope maps directly to voltage rating hierarchies and certification stringency tiers.
- Consumer Electronics:Miniaturized surface mount capacitors populate smartphone chargers and laptop adapters with capacitance values below 10 microfarads. Procurement concentrates with EMS providers in Shenzhen and Dongguan who negotiate six-month rolling forecasts against spot resin pricing.
- Automotive Electronics:High-voltage DC-link capacitors in traction inverters demand metallized polypropylene with segmented electrode patterns and 10,000-hour life ratings. European EV programs source through METI-certified Japanese producers due to 18-24 month qualification timelines that outpace domestic supplier development.
- Industrial Automation:Motor drive filters and UPS systems specify through-hole polypropylene with 630V to 2kV ratings.
- Renewable Energy:Solar and wind inverters require high ripple current endurance across temperature extremes.
Consumer electronics holds installed capacity. Automotive electronics is climbing the fastest.
End User:
Customer type dictates contract structure from spot purchasing to multi-year volume commitments.
- Electronics Manufacturers:EMS and ODM operations in East Asia drive surface mount volume through consolidated procurement platforms. Component traceability requirements from German and Spanish renewable EPCs are forcing tier-2 assemblers to dual-source from qualified film extruders.
- Automotive Companies:OEM powertrain divisions and Tier-1 inverter suppliers specify automotive-grade film with direct extruder relationships. China's MIIT enforcement of GB/T standards for grid-connected equipment is mandating 85°C minimums that exceed legacy IEC specifications.
- Energy Sector:Utility-scale solar and wind developers negotiate 3-5 year single-source agreements with capacitor assemblers who control captive film supply.
- Research Institutions:National laboratories and university engineering centers prototype next-generation dielectric formulations.
Electronics manufacturers holds installed capacity. Automotive companies is expanding most quickly.
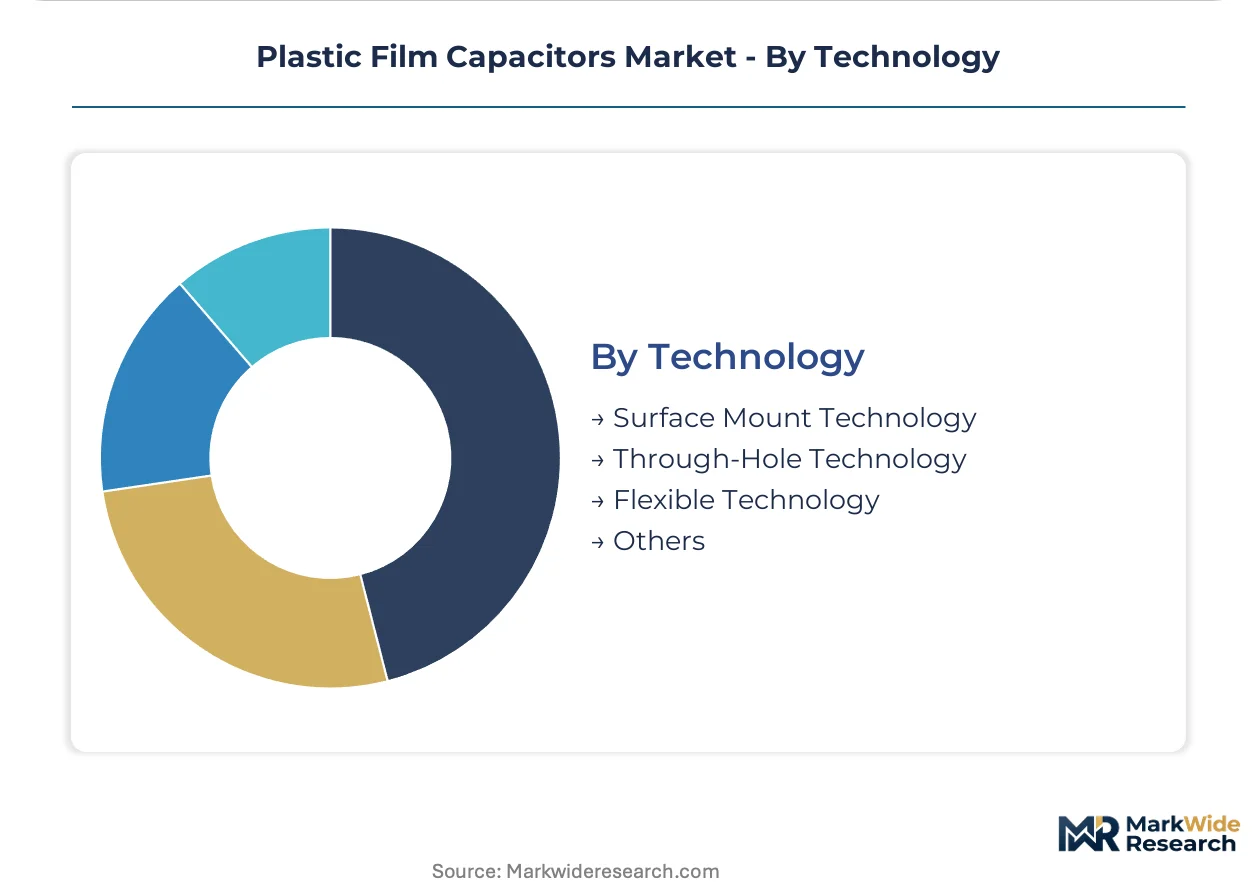
Technology:
Mounting architecture separates miniaturization imperatives from mechanical robustness requirements.
- Surface Mount Technology:Tape-and-reel packaging enables high-speed placement on multilayer PCBs with footprints below 10mm square. Consumer electronics assemblers in South Korea and Taiwan specify SMD film capacitors for smartphone and tablet power management where volumetric density outweighs thermal margin.
- Through-Hole Technology:Radial and axial leaded construction provides mechanical strain relief against board flex in high-voltage applications. German and Chinese renewable inverter manufacturers retain through-hole designs for 900V DC-link positions where solder joint integrity prevents field failures.
- Flexible Technology:Thin-film deposition on polyimide substrates enables conformal mounting in wearable and medical devices.
- Others:Embedded dielectric films and chip-on-flex configurations serve aerospace and defense applications.
Through-hole technology holds installed capacity. Surface mount technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallized polypropylene film capacity clusters in East Asian manufacturing hubs, with Chinese domestic producers expanding capacity while Japanese and Korean suppliers retain automotive-grade qualification dominance. Regional regulatory divergence around carbon compliance and grid reliability standards is fragmenting procurement patterns across major demand centers.
China
Electric vehicle powertrain electrification and state-backed renewable installations drive capacitor demand across automotive and grid-scale inverter applications. MIIT enforcement of GB/T standards for grid-connected equipment mandates thermal endurance thresholds exceeding legacy IEC specifications. Yangtze River Delta and Pearl River Delta manufacturing clusters host expanding metallized film extrusion capacity serving domestic solar inverter assemblers.
Japan
Automotive-grade film capacitor qualification expertise concentrates with METI-certified producers supplying European and North American EV programs. METI promotes JIS standards governing electrified powertrain component reliability. Kansai and Chubu industrial corridors anchor precision manufacturing operations for high-temperature DC-link capacitors with segmented electrode patterns.
Germany
Utility-scale solar and wind developers negotiate multi-year single-source agreements requiring component traceability to qualified film extruders. EU F-Gas Regulation restrictions on fluorinated compounds accelerate metallized polypropylene substitution in dielectric manufacturing. Bavaria and Baden-Württemberg host renewable energy EPC procurement consolidation driving supplier base compression.
South Korea
Consumer electronics EMS operations drive surface mount film capacitor volume through consolidated procurement platforms. MFDS-aligned quality frameworks support automotive supplier development alongside consumer-grade production. Seoul Capital Area and Busan-Ulsan manufacturing zones supply smartphone and tablet power management components.
United States
Domestic EV powertrain programs source high-reliability film capacitors through extended qualification timelines that outpace local supplier development. EPA industrial emissions frameworks intersect with state-level clean energy procurement standards. Midwest automotive manufacturing corridors and Texas renewable energy clusters generate parallel demand for industrial and automotive-grade components.
Plastic Film Capacitors Market Competitive Landscape
Vertically integrated film producers and specialized capacitor assemblers split the market into upstream-controlled and assembly-focused tiers. Japanese and Korean suppliers anchor automotive-grade qualification dominance while Chinese producers expand metallized polypropylene capacity for domestic renewable installations. Three archetypes define competitive positioning: captive film extruders with backward integration into raw polymer supply, tier-1 assemblers with direct OEM relationships, and commodity specialists serving cost-sensitive consumer electronics. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Within the vertically integrated tier, KEMET Corporation and Nichicon Corporation exemplify upstream-controlled positioning through captive film supply operations. TDK Corporation occupies a position among surface mount specialists competing aggressively in consumer electronics segments. These three anchors represent distinct strategic postures: KEMET with backward integration into raw film supply, Nichicon with Japanese manufacturing precision in automotive grades, and TDK with volume-driven surface mount technology leadership.
| Leading Market Players |
|---|
| KEMET Corporation |
| Nichicon Corporation |
| TDK Corporation |
| Cornell Dubilier Electronics |
| Wima GmbH & Co. KG |
| Vishay Intertechnology |
| KYOCERA AVX Components Corporation |
| Electro Technik Industries |
| Panasonic Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta freight corridors linking Shanghai to inland polypropylene film extruders impose cost premiums that compound with EU F-Gas Regulation compliance burdens, segmenting pricing power between automotive-grade Japanese suppliers and cost-optimized Chinese assemblers serving consumer electronics.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across metallized film capacitor supply. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 qualified automotive grades from industrial and consumer variants. Price differentiation rests on certification tier and volume scale, with automotive OEMs least sensitive due to 18-24 month qualification lock-ins. Cost compression in consumer-grade polyester capacitors is intensifying because EMS providers in Shenzhen negotiate six-month rolling forecasts against spot resin pricing.
Supply Chain Analysis
EMS operations in Dongguan and Taipei hold dominant surface mount assembly capacity for consumer-grade film capacitors. Geographic supply concentrates in China, Japan, and South Korea, with raw material dependencies on biaxially oriented polypropylene resin, metallized aluminum electrodes, and PET substrate films. Single-source vulnerability runs through Japanese high-reliability qualification expertise clustered with METI-certified producers. Distribution runs through direct OEM relationships for automotive grades and consolidated procurement platforms for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic film capacitors sit in early-cycle expansion as electric vehicle powertrain electrification accelerates capacitor demand faster than supplier qualification capacity can expand.
For Market Incumbents: Harden automotive-grade certification moats by accelerating AEC-Q200 pre-qualification programs ahead of EV platform launches. Deepen backward integration into polypropylene film extrusion to defend margin control against resin volatility and emerging Chinese metallized film competitors. For New Entrants and Emerging Players: India's BIS certification pathway for GB-equivalent standards offers the most penetrable geographic entry point. Target domestic solar inverter and railway electrification projects with localized testing infrastructure that bypasses duty disadvantages. Pursue joint development agreements with European renewable EPCs seeking dual-source alternatives to Japanese automotive-grade suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated film producers with captive polypropylene extrusion and direct OEM relationships. Long-term viability hinges on qualification timeline compression and solid-state battery DC-link capacitor development. Watch for MIIT enforcement of GB/T grid reliability mandates as inflection signal for domestic Chinese supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | KEMET Corporation's captive polypropylene supply anchors margin control against Asian competitors. |
| AEC-Q200 Pre-Qualification Acceleration | Nichicon Corporation's METI-certified expertise compresses validation cycles for European EV programs. |
| Surface Mount Technology Expansion | TDK Corporation's volume leadership in consumer electronics captures smartphone and tablet power management demand. |
| India BIS Certification Localization | Domestic testing infrastructure opens duty-advantaged supply to solar inverter and railway electrification projects. |
| Segmented Metallization Pattern Adoption | Tier-1 EV powertrain suppliers collapse fault-current tolerance gaps between industrial and automotive grades. |
Research Methodology
A spread of perspectives from capacitor design engineers, automotive Tier-1 procurement managers, renewable energy EPC technical buyers, and metallized film extrusion plant managers converged on the working assumptions. Primary fieldwork combined with secondary validation from MIIT GB standard filings, METI JIS certification databases, EU F-Gas Regulation compliance registries, and customs trade data for polypropylene resin flows. Bottom-up segment sizing and top-down macroeconomic cross-checks established triangulation boundaries.
Demand-supply balance modeling across the projection horizon incorporated polypropylene film chemistry, mounting architecture, end-use reliability tier, and regional regulatory cluster as segmentation dimensions. CAGRs derived from weighted average of historical trend extrapolation and adoption curve analysis for electric vehicle inverter content per vehicle and renewable energy installation growth. Industry-specific inputs included AEC-Q200 qualification timeline distributions and MIIT GB/T thermal endurance mandate enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed metallized film producers or accelerated solid-state battery commercialization would shift outcomes. Quarterly review of MIIT enforcement actions, EU F-Gas substance restriction updates, and automotive OEM platform launch schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market