
 Europe Busbar Market | 2026-2036
Europe Busbar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Busbar Market Intelligence
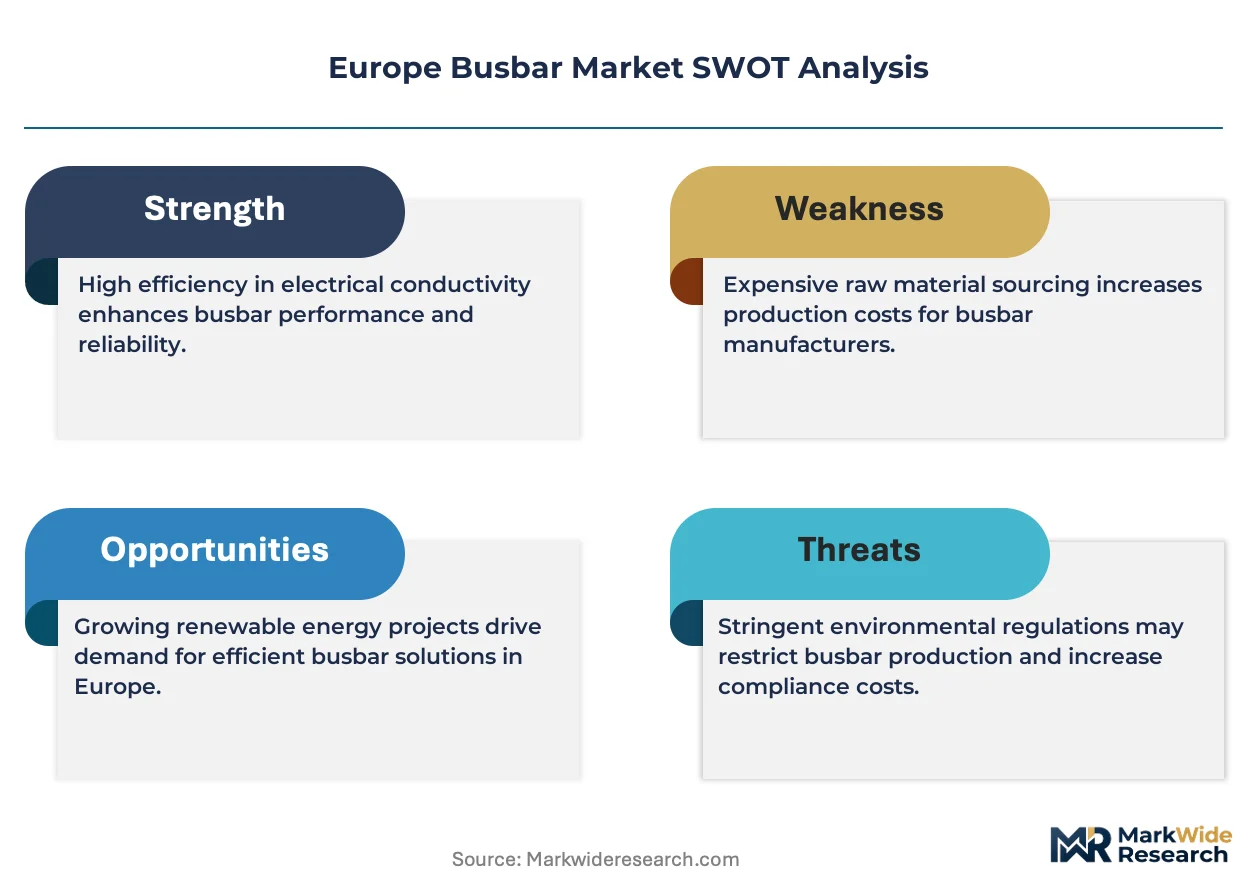
Power distribution channels across European utilities and hyperscale data center operators is rewriting procurement patterns for low-loss electrical infrastructure. Eaton Corporation leverages its integrated power management portfolio to anchor projects across Nordic renewable zones. Siemens AG dominates rail electrification and industrial busbar specifications through its DIN-standard manufacturing depth. ABB Ltd. competes on digital monitoring integration, embedding temperature and current sensors directly into laminated busbar assemblies.
A busbar is a metallic strip or bar, typically fabricated from electrolytic copper or aluminum alloy, engineered to conduct substantial electrical current within switchgear, distribution boards, and substation enclosures. European manufacturers commonly extrude, roll, or laminate these conductors with epoxy powder coating or heat-shrink insulation to achieve IP54+ protection ratings and thermal stability up to 105°C continuous operation. Copper busbars sustain premium positioning in high-current industrial and data center applications where conductivity losses must be minimized across compact footprints. Aluminum busbars occupy cost-sensitive utility and renewable energy installations where weight reduction and raw material economics offset higher resistivity. Insulated busbars lead growth in modular data hall architectures across Frankfurt and Amsterdam, where plug-and-play busway systems slash installation labor and improve safety compliance.
CE marking under the EU Low Voltage Directive governs electrical safety conformity, while REACH restricts hazardous substances in conductor coatings and insulation polymers across member states. Germany's KBA and France's ANSM enforce sector-specific electrical standards that filter into rail and healthcare infrastructure procurement, tightening supplier qualification requirements. ECHA substance evaluations are reshaping coating chemistries, pushing manufacturers toward halogen-free insulation systems. Stakeholders must monitor how the EU AI Act and forthcoming grid digitalization mandates intersect with smart busbar monitoring investments.
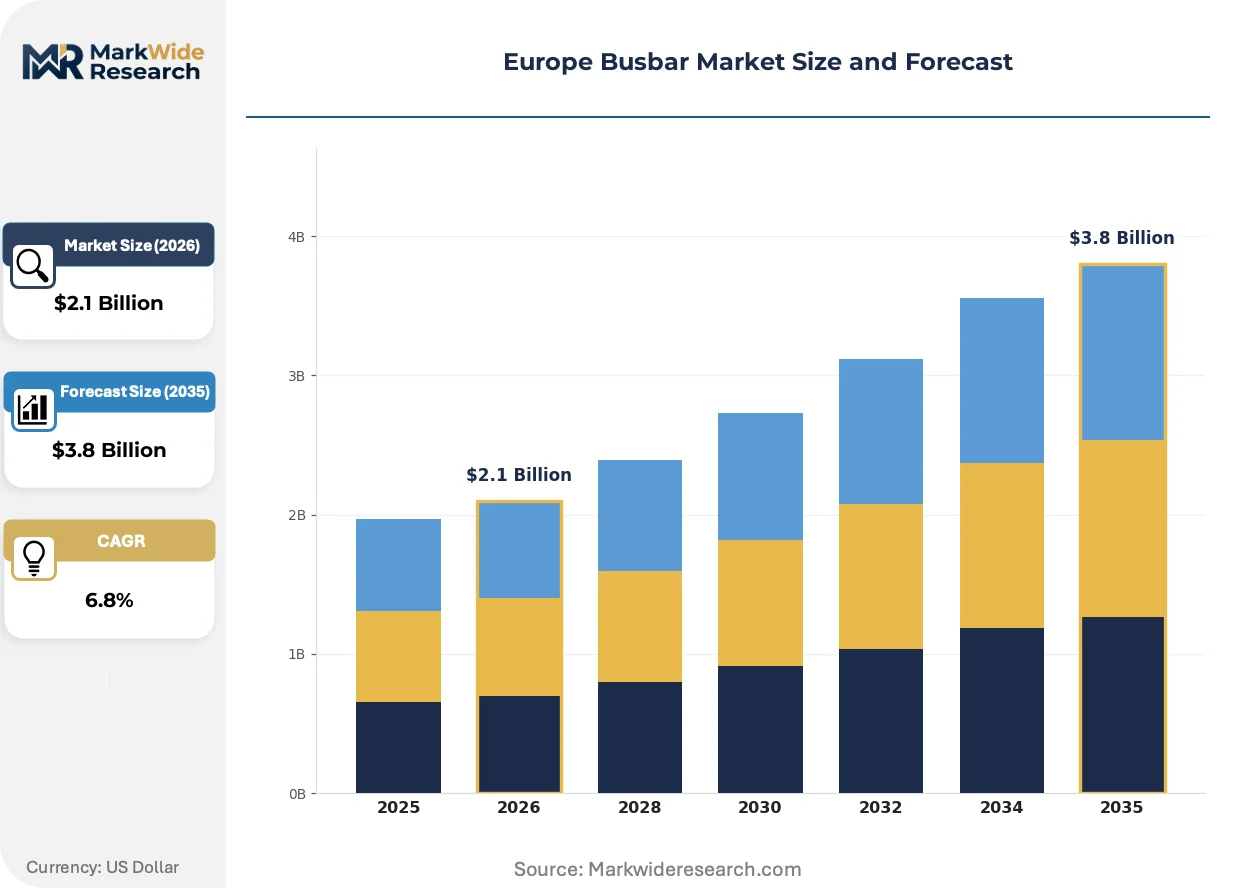
Market Dynamics
Copper and aluminum substitution cycles are accelerating across European power infrastructure as the EU Green Deal and F-Gas Regulation force cable-to-busbar conversions in data centers and renewable integration projects.
Growth Catalysts
- EU Green Deal mandates:Carbon neutrality targets require high-efficiency power distribution in industrial corridors, pushing German and French utilities toward low-loss busbar architectures.
- Data center densification:Hyperscale operators in Frankfurt and Amsterdam are specifying plug-and-play busway systems to reduce installation labor and improve thermal management in modular halls.
- Electrolytic copper conductivity:Premium copper busbars sustain demand in high-current applications where resistivity losses across compact footprints justify material cost premiums.
Market Restraints
- LME copper volatility:Raw material price swings compress fabrication margins and deter long-term procurement commitments from cost-sensitive utility buyers.
- REACH substance restrictions:ECHA evaluations of halogenated coatings force reformulation cycles that extend qualification timelines for insulated busbar suppliers.
- Aluminum resistivity limitations:Higher ohmic losses restrict aluminum busbar penetration in precision manufacturing and healthcare power distribution where voltage stability is critical.
Strategic Opportunities
- Nordic renewable zones:Wind and solar integration projects in Denmark and Sweden create demand for weather-resistant outdoor busbar installations with extended temperature ratings.
- Smart monitoring convergence:Embedded temperature and current sensors within laminated assemblies enable predictive maintenance contracts for rail electrification operators.
- CE marking harmonization:Unified Low Voltage Directive compliance across member states reduces certification fragmentation for pan-European suppliers.
Industry Challenges
- DIN standard mastery:German rail and industrial specifications require specialized tooling and metallurgical expertise that limits supplier qualification pools.
- Legacy switchgear integration:Retrofit projects demand custom busbar geometries that extend engineering cycles and strain fabrication capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Busbar Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Busbars, Aluminum Busbars, Insulated Busbars, Power Busbars Application: Power Distribution, Renewable Energy, Industrial Applications, Commercial Applications End User: Utilities, Manufacturing, Data Centers, Transportation Installation Type: Indoor Installation, Outdoor Installation, Modular Installation, Custom Installation |
| Companies Covered | Eaton Corporation, Mersen, ABB Ltd., Infineon Technologies AG, TE Connectivity, Schneider Electric, Legrand, General Electric Company, Siemens AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Busbar Market Strategic Shifts & Innovations
Digitalization of power distribution hardware is compressing traditional equipment lifecycles and rewriting supplier value propositions across European electrical infrastructure.
Epoxy powder coating with embedded fiber-optic sensing is rendering obsolete conventional heat-shrink insulation in data center busway deployments. Colocation operators in Frankfurt are specifying these intelligent assemblies to enable real-time thermal mapping. The technology is rendering obsolete scheduled maintenance protocols by shifting operators toward condition-based service models.
F-Gas Regulation phase-down schedules are accelerating aluminum busbar adoption in utility-scale solar farms across Spain and Italy. The restriction on fluorinated greenhouse gases in switchgear insulation is redirecting procurement toward air-insulated busbar systems. Renewable developers in the Iberian Peninsula are responding by consolidating specifications around halogen-free epoxy systems.
Buyers are consolidating vendor relationships around integrated power management portfolios rather than discrete component sourcing. Industrial procurement teams in Germany's Ruhr corridor now require busbar suppliers to bundle digital monitoring platforms with hardware deliveries. This concentration is most visible in automotive manufacturing electrification projects where single-source accountability reduces interface risk.
Europe Busbar Market Segmentation
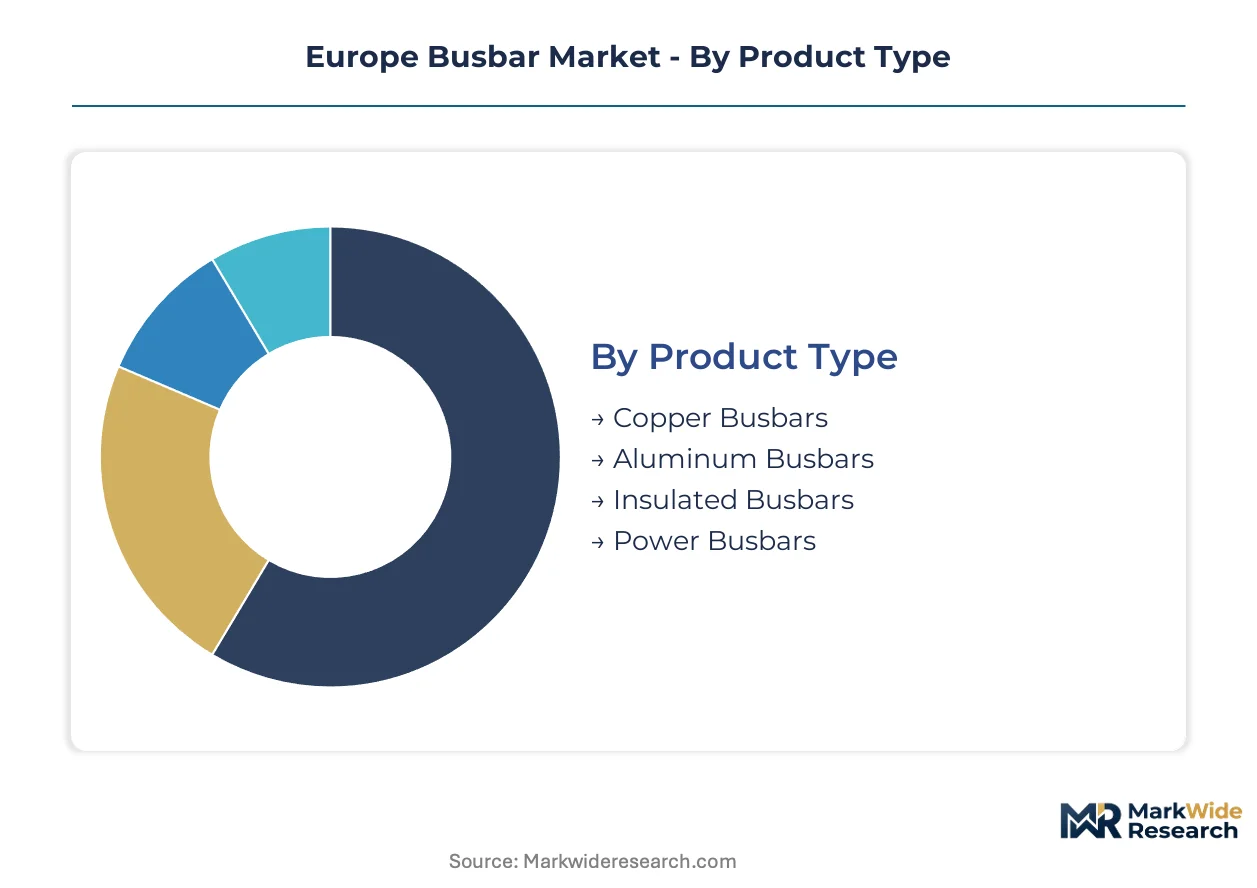
Busbar procurement patterns across Europe diverge sharply by conductor material, deployment environment, and end-use power density requirements. Each segmentation axis reveals distinct technical specifications, regulatory compliance burdens, and margin structures that reshape supplier positioning.
Product Type:
Material selection spans conductivity premiums against weight and cost constraints, with coating technologies increasingly determining competitive differentiation.
- Copper Busbars:Electrolytic copper grades achieve conductivity ratings exceeding 100% IACS, sustaining premium positioning in Frankfurt data centers and German automotive electrification projects where resistive losses compound across compact footprints. German DIN standards and French rail specifications enforce strict metallurgical purity thresholds that filter supplier pools.
- Aluminum Busbars:Aluminum alloy 6101-T6 delivers conductivity at one-third the density of copper, dominating Nordic wind farm collector systems and Spanish utility-scale solar installations where span lengths and structural loads outweigh ohmic loss concerns. REACH substance evaluations on conductor coatings extend qualification timelines for insulated aluminum variants.
- Insulated Busbars:Epoxy powder-coated or heat-shrink wrapped assemblies achieve IP54+ ratings for Amsterdam colocation facilities and modular data hall architectures across the Netherlands.
- Power Busbars:High-current laminated configurations serve industrial substations and rail traction power across France's SNCF network and Germany's Deutsche Bahn corridors.
Established volume favors copper busbars; emerging adoption favors insulated busbars.
Application:
Deployment context dictates thermal management, fault current ratings, and integration complexity across European infrastructure.
- Power Distribution:Utility substations and industrial switchgear across Germany's Ruhr corridor and northern Italy deploy rigid busbar systems for 4000A+ continuous operation. CE marking under the EU Low Voltage Directive governs safety conformity, while F-Gas Regulation phase-downs redirect procurement toward air-insulated architectures.
- Renewable Energy:Wind turbine nacelles and solar inverter skids in Denmark and Sweden specify weather-resistant outdoor busbar with extended temperature ratings from -40°C to 105°C. ECHA evaluations of halogenated coatings push developers toward halogen-free epoxy systems.
- Industrial Applications:Precision manufacturing in Bavaria and automotive electrification in Stuttgart demand voltage-stable copper distribution with embedded temperature monitoring.
- Commercial Applications:Office complexes and retail distribution centers across France and Belgium prioritize plug-and-play busway for tenant flexibility and reduced installation labor.
Industrial applications command the steepest expansion trajectory; commercial applications climb fastest on modular retrofit demand.
End User:
Procurement sophistication varies from centralized utility tenders to hyperscale operator specifications.
- Utilities:Transmission and distribution operators in France, Germany, and Spain consolidate specifications around IEC 61439 compliance for low-voltage switchgear assemblies. Long-term framework agreements favor suppliers with integrated power management portfolios over discrete component vendors.
- Manufacturing:Automotive electrification projects in Germany's industrial corridor require busbar suppliers to bundle digital monitoring platforms with hardware deliveries, reducing interface risk through single-source accountability.
- Data Centers:Hyperscale operators in Frankfurt and Amsterdam specify intelligent busway with embedded fiber-optic thermal sensing for real-time mapping and condition-based maintenance.
- Transportation:Rail electrification operators across SNCF and Deutsche Bahn networks prioritize predictive maintenance contracts enabled by sensor-embedded laminated assemblies.
Utilities anchor procurement volume; data centers gain share fastest on densification mandates.
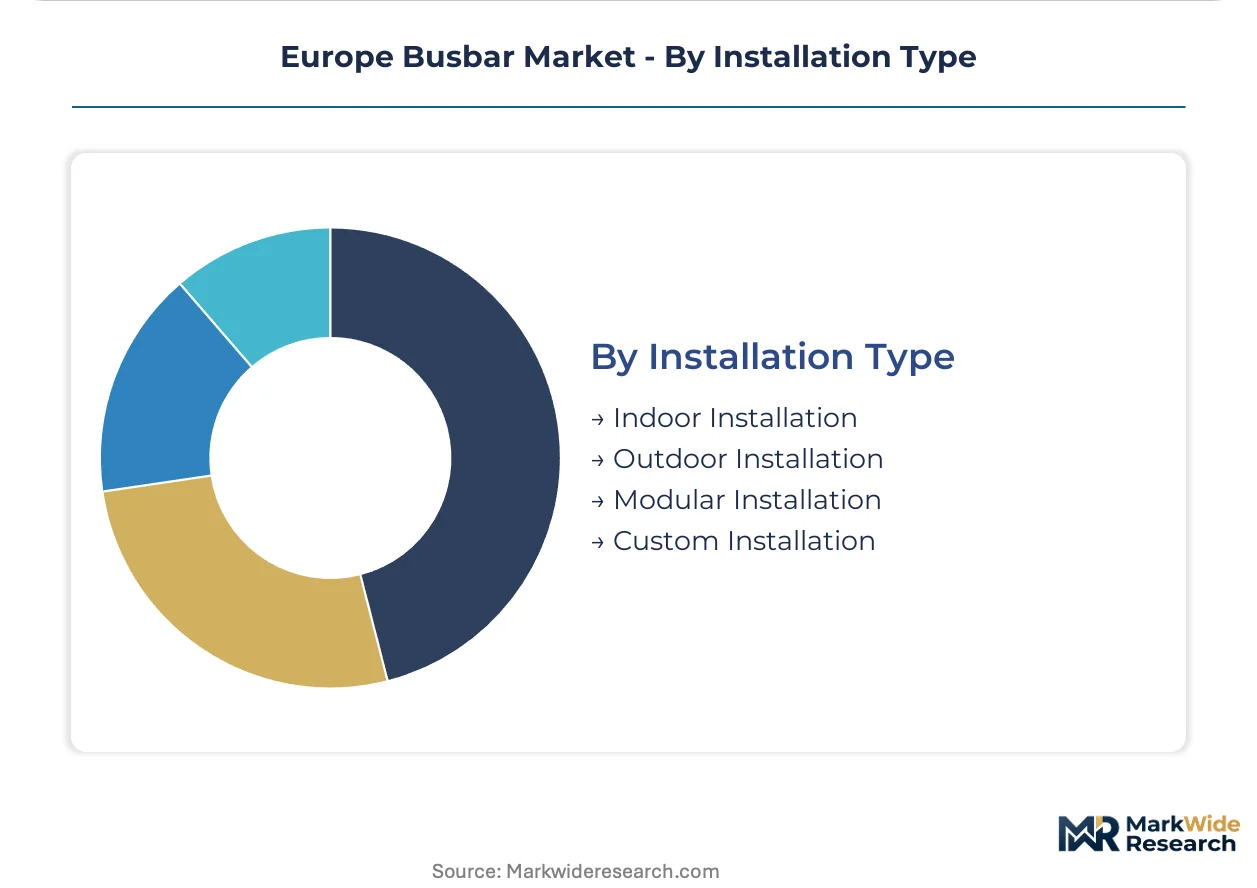
Installation Type:
Physical deployment mode determines engineering cycles, labor economics, and retrofit feasibility.
- Indoor Installation:Climate-controlled switchgear rooms and data halls across Frankfurt and Amsterdam specify IP2X minimum protection with epoxy-coated copper or aluminum conductors. Standardized geometries reduce engineering overhead for repeat deployments.
- Outdoor Installation:Nordic renewable zones and Iberian solar farms demand IP65+ enclosures with UV-stable insulation and extended temperature cycling resistance.
- Modular Installation:Prefabricated busway sections with quick-connect joints slash commissioning time for Amsterdam colocation expansions and modular data hall builds.
- Custom Installation:Legacy switchgear retrofits and heritage building integrations across Paris and Milan require bespoke geometries that strain fabrication capacity and extend lead times.
Modular installation expands most quickly on speed-to-market pressure; custom installation retains premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators capture pricing premiums through DIN-standard mastery, while Spanish suppliers compete on raw material arbitrage and solar farm proximity. This asymmetry concentrates high-margin industrial procurement in Central Europe while Iberian producers serve cost-sensitive renewable installations.
Germany
Automotive electrification in Stuttgart and Bavarian precision manufacturing drive copper busbar demand for voltage-stable distribution. KBA rail standards and EU Green Deal carbon mandates tighten supplier qualification pools. The Ruhr industrial corridor consolidates procurement around integrated power management portfolios with embedded monitoring.
France
SNCF rail electrification and nuclear power infrastructure sustain demand for high-current laminated assemblies. ANSM healthcare electrical standards filter into hospital power distribution specifications. The Île-de-France data center cluster near Paris adopts plug-and-play busway for modular hall expansions.
Netherlands
Amsterdam colocation operators specify intelligent busway with fiber-optic thermal sensing for real-time mapping. REACH substance evaluations on halogenated coatings push developers toward halogen-free epoxy systems. Randstad logistics hubs deploy prefabricated busway sections to slash commissioning times.
Spain
Utility-scale solar farms across Andalusia and the Iberian interior favor aluminum busbars for span length and structural load advantages. F-Gas Regulation phase-downs redirect procurement toward air-insulated architectures. Renewable developers consolidate specifications around weather-resistant outdoor installations with UV-stable insulation.
Sweden
Wind turbine nacelles in Nordic renewable zones specify extended temperature ratings from -40°C to 105°C. ECHA coating chemistry evaluations extend qualification timelines for insulated aluminum variants. Danish and Swedish offshore wind integration projects create demand for compact substation busbar configurations.
Europe Busbar Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on material and fabrication expertise. The European busbar market structures around three tiers: diversified electrical conglomerates with integrated power portfolios, specialized busbar fabricators with metallurgical depth, and regional component suppliers serving retrofit and maintenance channels. Consolidation pressure intensifies as procurement teams demand single-source accountability for complex electrification projects. Strategic moves center on backward integration into copper and aluminum supply chains and technology licensing for embedded sensor integration.
Among diversified electrical conglomerates, Siemens AG and ABB Ltd. exemplify platform integrators bundling hardware with digital monitoring platforms. Eaton Corporation occupies a position bridging industrial specification authority with data center application expertise. These three anchors represent contrasting archetypes: DIN-standard manufacturing depth, sensor-embedded smart infrastructure, and integrated power management portfolios.
| Leading Market Players |
|---|
| Eaton Corporation |
| Mersen |
| ABB Ltd. |
| Infineon Technologies AG |
| TE Connectivity |
| Schneider Electric |
| Legrand |
| General Electric Company |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's volatile container rates compress fabrication margins for German copper busbar mills while amplifying price spreads between configured-to-order and standard catalog products. Downstream buyers in Amsterdam data centers and Stuttgart automotive plants face divergent landed costs depending on metallurgical certification tiers and insulation system complexity.
Pricing Analysis
The customization-premium spread separates DIN-certified copper assemblies for Deutsche Bahn traction power from standard aluminum extrusions for Iberian solar farms. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking depth, REACH coating compliance, and embedded sensor integration. Cost compression in economy-grade aluminum busbars is intensifying because Spanish renewable developers consolidate procurement around halogen-free epoxy specifications. Utility buyers in France and Germany exhibit lowest price sensitivity due to long-term framework agreements, while Dutch colocation operators prioritize speed-to-market over unit cost.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and supply-chain finance facilities anchored by Nordic wind farm EPCs structure working capital dynamics across European busbar fabricators. Raw material sourcing draws from Chilean copper cathode, Norwegian aluminum smelters, and Belgian epoxy resin producers. Single-source vulnerability concentrates in electrolytic copper refining capacity, with Iberian solar developers particularly exposed to LME price swings. Distribution runs through regional electrical wholesalers in the Ruhr corridor, direct OEM contracts for rail electrification, and prefabricated busway specialists serving Amsterdam data hall expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Busbar Market sits in early-cycle expansion as EU Green Deal carbon mandates force cable-to-busbar substitution across industrial power distribution. F-Gas Regulation phase-downs accelerate this displacement in data center and renewable integration projects.
For Market Incumbents: Entrench DIN-standard manufacturing depth through captive control of electrolytic copper supply from Nordic smelters. Acquire specialized lamination capabilities for sensor-embedded assemblies before REACH coating reformulations disqualify legacy suppliers. The threat of aluminum busbar commoditization in Spanish solar farms demands certification investment in halogen-free insulation systems.
For New Entrants and Emerging Players: Eastern European industrial corridors outside Germany's Ruhr heartland offer white-space expansion for mid-voltage busway serving automotive electrification projects. Target Polish and Czech manufacturing zones with modular plug-and-play architectures that slash installation labor. A go-to-market angle bundling digital thermal monitoring with hardware deliveries bypasses entrenched specification authority.
For Investors and Strategic Acquirers: The EU AI Act's grid digitalization mandates reshape the acquisition landscape toward sensor-embedded busbar fabricators with predictive maintenance platforms. Long-term viability centers on suppliers bridging hardware metallurgy with software-enabled service contracts. The signal to watch is consolidation of vendor relationships by hyperscale data center operators around integrated power management portfolios rather than discrete component sourcing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Supply | Captive electrolytic cathode sourcing from Chilean-Chinese offtake agreements insulates German mills from LME volatility. |
| Sensor-Embedded Lamination Investment | Fiber-optic thermal sensing integration enables predictive maintenance contracts for SNCF and Deutsche Bahn electrification networks. |
| Halogen-Free Coating Certification | REACH-compliant epoxy systems qualify suppliers for Amsterdam data center specifications ahead of ECHA substance restrictions. |
| Modular Busway Platform Launch | Prefabricated quick-connect sections slash commissioning time for Frankfurt hyperscale expansions and Randstad logistics hubs. |
| Nordic Renewable Zone Partnership | Weather-resistant outdoor installations with extended temperature ratings capture Danish-Swedish wind integration project demand. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU customs trade data, ECHA substance evaluation registers, SEC filings from listed electrical conglomerates, and DIN standard certification databases. Plant managers at German copper extrusion facilities, procurement leads at French utility EDF, EPC contractors for Iberian solar farms, and technical directors at Amsterdam colocation operators provided operational validation. Bottom-up triangulation against top-down macroeconomic drivers ensures segmentation integrity across material grades and installation types.
Forecast inputs span electrolytic copper price trajectories, EU Green Deal implementation timelines, data center power density specifications, and F-Gas Regulation phase-down schedules. The analytical framework models conductor material, deployment environment, end-use power density, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base replacement cycles, renewable capacity addition pipelines, and penetration assumptions for intelligent busway in modular data hall architectures.
Practitioners should monitor LME copper volatility, REACH coating chemistry evaluations, and hyperscale data center capex commitments for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
DC Contactor Market