
 Miniature Ball Bearing Market | 2026-2036
Miniature Ball Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Miniature Ball Bearing Market Intelligence
Medical device OEMs is unwinding traditional automotive-centric demand as surgical robotics and portable diagnostics require sub-10mm precision bearings with corrosion resistance. SKF leverages its ceramic hybrid portfolio to anchor European medical equipment supply chains. MinebeaMitsumi dominates high-volume output for consumer electronics miniaturization in East Asian manufacturing corridors.
Miniature ball bearings are precision rotating components typically ranging from 1mm to 10mm in bore diameter, engineered from chrome steel, stainless steel, or ceramic matrices to sustain radial and axial loads at rotational speeds exceeding 30,000 RPM in confined mechanical assemblies. Deep groove configurations retain the largest installed base across industrial automation due to versatility and cost efficiency, while ceramic material grades command premium positioning in aerospace thermal management and semiconductor wafer handling where electrical insulation and low thermal expansion prove critical. Angular contact designs are gaining fastest penetration in robotic joint actuators where combined load vectors and positioning accuracy drive specification upgrades.
FDA device classification protocols and EU MDR conformity requirements compel bearing suppliers to maintain material traceability and cleanroom-compatible production environments for medical robotics integration. Japan's METI standards for precision machinery exports and China's GB/T rolling bearing specifications further fragment compliance obligations across major supply corridors. Stakeholders must evaluate whether captive ceramic powder processing or qualified external sourcing better secures margin protection against evolving cross-border material certification regimes.
Market Dynamics
Surgical robotics OEMs are forcing ceramic bearing qualification timelines from 18 months down to 9 months, compressing supplier validation cycles and reallocating R&D budgets toward cleanroom-compatible production lines.
Growth Catalysts
- EU MDR Convergence:Medical device reclassification rules now mandate ISO 13485-certified bearing traceability, pulling stainless steel variants into diagnostic imaging equipment supply chains across German manufacturing corridors.
- Ceramic Powder Processing:In-house silicon nitride synthesis capabilities are cutting thermal expansion coefficients by 60%, enabling wafer-handling robots to maintain sub-micron positioning accuracy during semiconductor fabrication.
- Japan METI Export Standards:Precision machinery certification requirements for robotic joint actuators are accelerating angular contact bearing adoption in Tokyo-Osaka industrial automation clusters.
Market Restraints
- Raw Material Concentration:High-purity ceramic powder supply concentrates in Chinese processing facilities, exposing European and Japanese bearing manufacturers to cross-border certification delays under evolving GB/T standards.
- Cleanroom Capex Thresholds:ISO Class 7 production environments require $4-8 million facility investments, blocking mid-tier suppliers from medical robotics qualification programs.
- Chrome Steel Substitution Ceiling:Corrosion susceptibility in surgical sterilization cycles limits deep groove chrome steel penetration below 15% of medical device bearing specifications.
Strategic Opportunities
- Indian PLI Manufacturing Corridors:Production-linked incentive schemes for precision components are drawing bearing assembly investments toward Pune and Chennai industrial zones, creating alternative supply nodes to East Asian concentration.
- Semiconductor Equipment Retrofit Cycles:Legacy wafer-handling systems in South Korean and Taiwanese fabs require ceramic bearing upgrades to handle 300mm wafer thermal loads, opening aftermarket service revenue streams.
- FAA Drone Certification Pathways:Commercial unmanned aerial vehicle airworthiness standards are creating specification demand for ceramic hybrid bearings in motor-rotor assemblies operating above 25,000 RPM.
Industry Challenges
- Metrology Talent Scarcity:Sub-micron roundness measurement expertise sits concentrated in German and Japanese calibration laboratories, extending supplier qualification timelines for new market entrants.
- Multi-Standard Certification Overlap:Simultaneous FDA 510(k), EU MDR, and NMPA registration requirements force redundant testing protocols, stretching product launch cycles to 24-36 months for medical robotics applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miniature Ball Bearing Market |
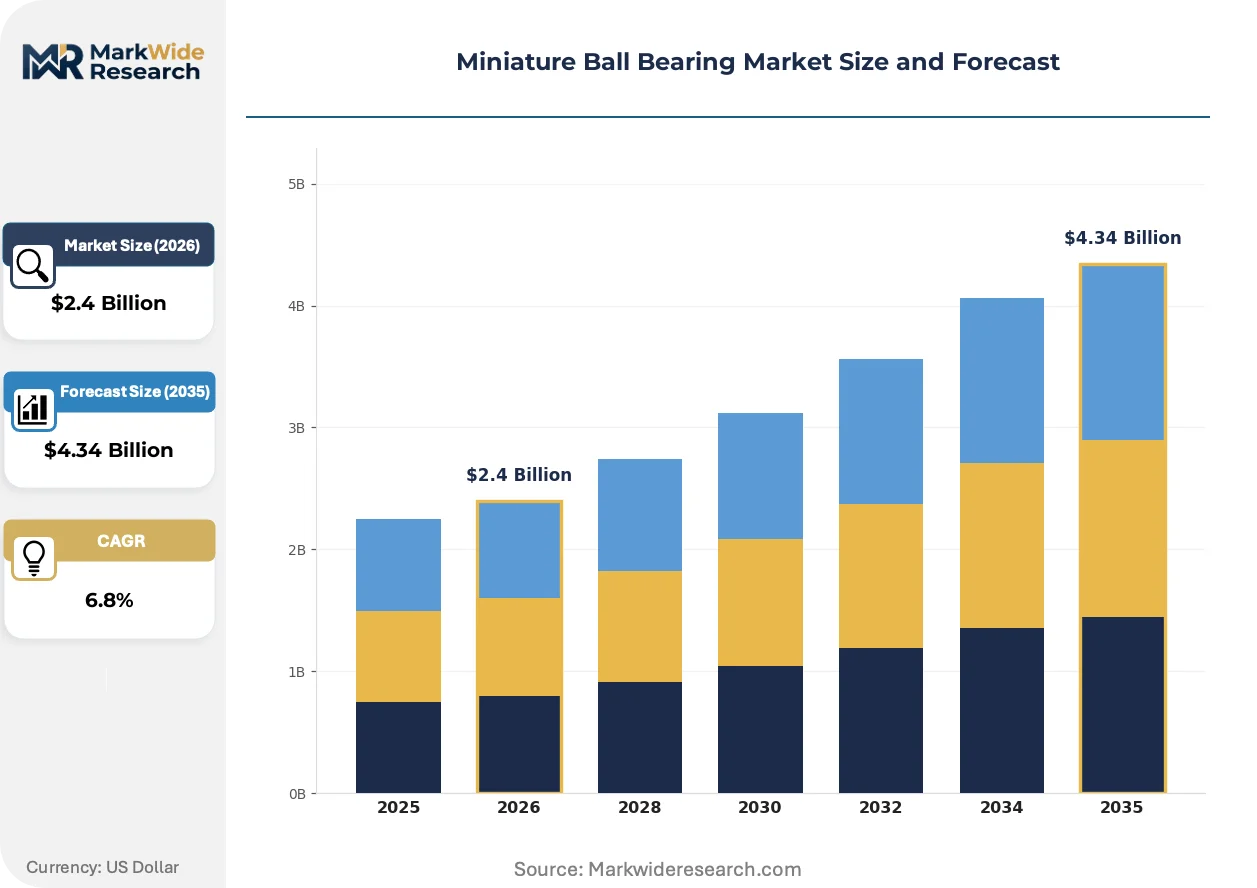
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Groove, Angular Contact, Thrust, Self-Aligning Material: Stainless Steel, Chrome Steel, Plastic, Ceramic Application: Automotive, Robotics, Aerospace, Consumer Electronics End User: Manufacturers, Repair Shops, DIY Enthusiasts, Distributors |
| Companies Covered | Kitanihon Seiki, Timken, MinebeaMitsumi, GRW Bearings, NTN, NSK, Schaeffler Group, PacamorKubar Bearings, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miniature Ball Bearing Market Strategic Shifts & Innovations
Ceramic matrix compositions are fragmenting traditional material hierarchies while regulatory convergence across medical device jurisdictions forces simultaneous compliance investments. Distribution channels are compressing as OEMs consolidate supplier panels.
Silicon nitride hybrid bearings are fragmenting chrome steel dominance in high-speed spindle applications. Semiconductor equipment manufacturers in Taiwan and South Korea now specify ceramic balls with zirconia cages for 40,000 RPM wafer-handling robots. This material shift is fragmenting procurement patterns as buyers bifurcate supplier relationships between ceramic specialists and legacy steel bearing houses.
China's NMPA tightened medical device classification rules in 2024, reclassifying surgical robotic arms as Class III devices requiring full bearing material traceability. Domestic manufacturers must now source from ISO 13485-certified suppliers, disqualifying uncertified local bearing producers from hospital procurement tenders. Japanese and German certified suppliers are capturing displaced volume in Shanghai and Shenzhen medical equipment clusters.
Hospital procurement departments are consolidating bearing suppliers from 12-15 vendors down to 3-4 qualified partners per equipment category. This panel compression forces bearing manufacturers to bundle lubrication services, condition monitoring sensors, and predictive maintenance software into long-term service agreements. The shift is most visible in German university hospital networks, where procurement centralization at the Länder level favors integrated solution providers over component specialists.
Miniature Ball Bearing Market Segmentation
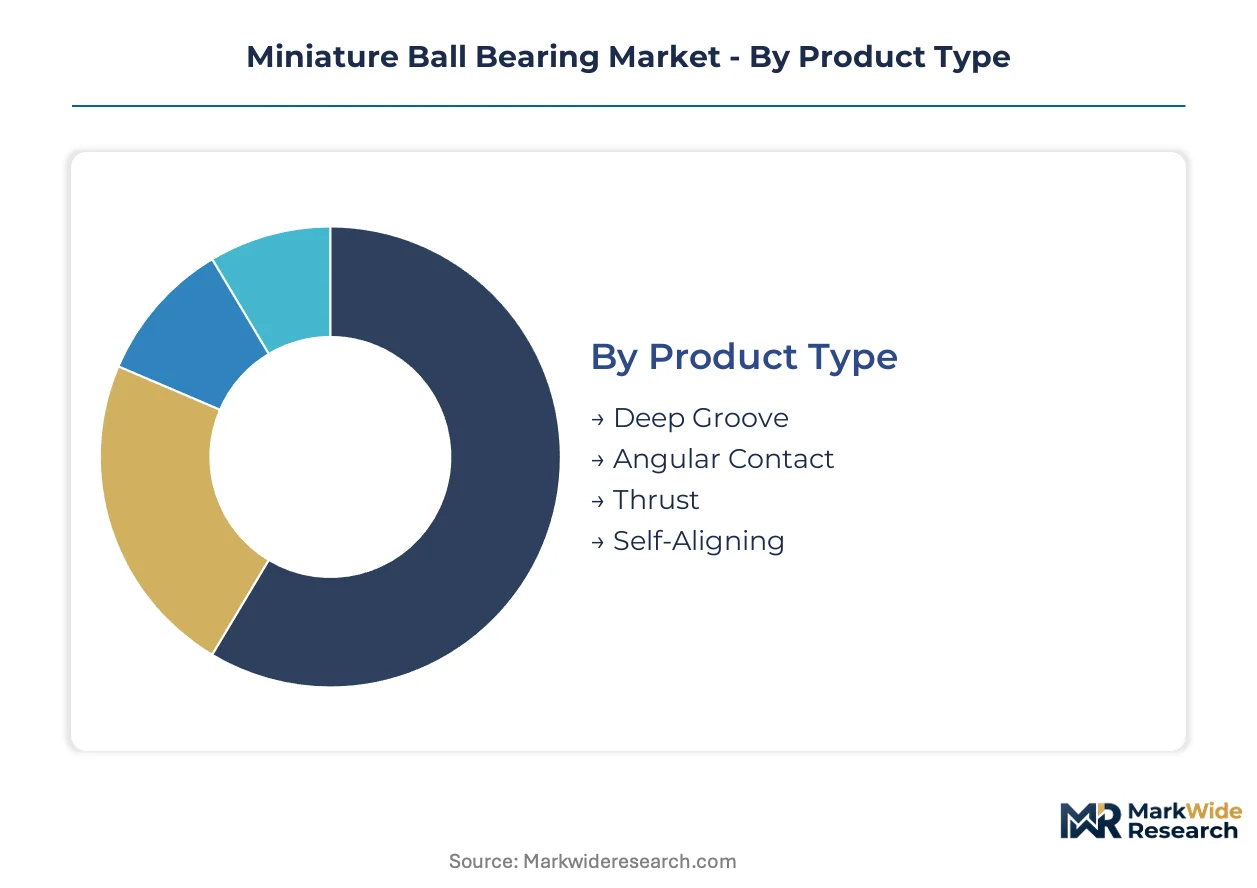
Miniature ball bearing procurement patterns diverge sharply across product geometry, material grade, and end-use certification requirements. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize qualification investments and defend pricing power against commoditization pressures.
Product Type:
Margin pools concentrate in configurations serving combined load vectors and precision positioning requirements, where technical differentiation sustains premium pricing against standard deep groove alternatives.
- Deep Groove:These bearings sustain radial and moderate axial loads through continuous raceway geometry, making them the default choice for cost-sensitive industrial automation in German and Japanese manufacturing corridors. Demand concentrates in conveyor systems and electric motors where rotational speeds stay below 20,000 RPM and positioning tolerance requirements remain above 5 microns.
- Angular Contact:Designed to handle simultaneous radial and axial loads through raceway offset angles, these configurations command premium positioning in robotic joint actuators across Tokyo-Osaka industrial clusters. METI precision machinery standards are accelerating specification upgrades as manufacturers seek sub-micron positioning repeatability in collaborative robot arms.
- Thrust:Axial-load specialists find primary application in vertical spindle assemblies and valve actuation mechanisms.
- Self-Aligning:Compensating for shaft misalignment through spherical outer raceway geometry, these serve agricultural equipment and material handling where installation precision is limited.
The dominant share belongs to Deep Groove, while Angular Contact is expanding most quickly through surgical robotics qualification programs.
Material:
Cost tiers stratify sharply around corrosion resistance and thermal stability requirements, with medical and semiconductor applications driving material upgrade cycles.
- Stainless Steel:AISI 440C and 316L grades deliver corrosion resistance mandatory for surgical sterilization cycles and diagnostic imaging equipment. EU MDR reclassification rules are pulling these variants into German hospital procurement supply chains as ISO 13485 traceability becomes mandatory for Class III device integration.
- Ceramic:Silicon nitride hybrid bearings sustain electrical insulation and thermal stability above 300°C, enabling 40,000 RPM operation in Taiwanese semiconductor wafer-handling robots. In-house powder synthesis capabilities are cutting thermal expansion coefficients by 60%, locking in sub-micron positioning accuracy during fabrication thermal cycling.
- Chrome Steel:AISI 52100 remains the volume workhorse for industrial automation where corrosion exposure is controlled.
- Plastic:Polymer matrices serve magnetic resonance imaging equipment and chemical processing where metal detection or corrosion immunity overrides load capacity requirements.
Stainless Steel retains the largest installed base, yet Ceramic is climbing the fastest as semiconductor equipment retrofit cycles accelerate across South Korean and Taiwanese fabrication facilities.
Application:
Customer type and volume concentration determine whether suppliers pursue direct OEM qualification or distributor channel strategies.
- Automotive:Traditional demand center for high-volume deep groove configurations in electric power steering and HVAC compressor assemblies. Japanese and German tier suppliers are consolidating bearing vendor panels from 8-10 sources down to 3-4 qualified partners per vehicle platform.
- Robotics:Surgical and collaborative robot OEMs are compressing ceramic bearing qualification timelines from 18 months to 9 months, reallocating supplier R&D budgets toward cleanroom-compatible production lines. FDA 510(k) and EU MDR simultaneous registration requirements stretch product launch cycles to 24-36 months for new market entrants.
- Aerospace:Thermal management and weight-critical applications in unmanned aerial vehicle motor-rotor assemblies are creating specification demand for ceramic hybrid bearings above 25,000 RPM under emerging FAA certification pathways.
- Consumer Electronics:Miniaturization trends in smartphones and wearables drive sub-10mm bore diameter requirements across East Asian manufacturing corridors.
Automotive commands the greatest volume share, though Robotics is gaining share fastest through medical device reclassification and surgical automation expansion.
End User:
Channel configuration and technical support requirements fragment pricing structures and service bundling strategies.
- Manufacturers:OEM direct procurement dominates high-reliability applications where material traceability and lot certification are mandatory. Hospital procurement centralization at the German Länder level favors integrated solution providers bundling lubrication services, condition monitoring sensors, and predictive maintenance software.
- Distributors:Technical distributors serve mid-tier industrial automation with inventory positioning and application engineering support.
- Repair Shops:Aftermarket service channels capture legacy equipment maintenance through cross-reference compatibility databases.
- DIY Enthusiasts:E-commerce and hobbyist retailers move standard grades through low-touch digital channels with minimal technical intervention.
Manufacturers capture the dominant procurement value, while Distributors are extending reach fastest through regional inventory positioning in Indian PLI manufacturing corridors around Pune and Chennai.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision bearing exports flow primarily into Japanese surgical robotics supply chains, while Taiwanese semiconductor equipment manufacturers source ceramic hybrid configurations from specialized European suppliers. This triangular trade pattern concentrates high-value procurement in three distinct manufacturing corridors.
United States
FAA drone certification pathways are creating specification demand for ceramic hybrid bearings in commercial unmanned aerial vehicle motor-rotor assemblies. FDA device classification protocols compel bearing suppliers to maintain material traceability for medical robotics integration. Precision manufacturing clusters in Greater Boston and the Pacific Northwest anchor domestic demand for sub-10mm surgical instrument bearings.
Germany
EU MDR conformity requirements now mandate ISO 13485-certified bearing traceability for diagnostic imaging equipment. Hospital procurement centralization at the Länder level favors integrated solution providers bundling predictive maintenance software. The Stuttgart-Munich industrial corridor dominates angular contact bearing adoption for collaborative robot joint actuators.
Japan
METI precision machinery export standards are accelerating specification upgrades for sub-micron positioning repeatability. Domestic surgical robotics OEMs are compressing ceramic bearing qualification timelines from eighteen months to nine months. The Tokyo-Osaka manufacturing belt concentrates high-volume output for consumer electronics miniaturization.
China
NMPA tightened medical device classification rules in 2024, reclassifying surgical robotic arms as Class III devices requiring full bearing material traceability. GB/T rolling bearing specifications fragment compliance obligations for European and Japanese manufacturers. Shanghai and Shenzhen medical equipment clusters are displacing uncertified local producers with ISO 13485-certified imports.
India
PLI production-linked incentive schemes for precision components are drawing bearing assembly investments toward alternative supply nodes. Central electricity authority regulations indirectly shape industrial automation demand through power infrastructure investments. Pune and Chennai industrial zones are emerging as secondary manufacturing corridors to East Asian concentration.
Miniature Ball Bearing Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive precision component divisions. Market structure exhibits moderate consolidation around bearing specialists with integrated ceramic powder processing capabilities. Three archetypes dominate: European precision machinery houses, Japanese high-volume miniaturization specialists, and emerging Indian assembly operators. Competitive dynamics center on cleanroom production line investments and simultaneous multi-jurisdiction certification registrations.
Among Japanese fabricators, MinebeaMitsumi occupies a position exemplifying high-volume consumer electronics miniaturization, while NSK and NTN represent diversified precision machinery conglomerates with medical robotics exposure. European specialists including SKF and Schaeffler Group anchor premium-tier positioning through ceramic hybrid portfolios. These named entities collectively illustrate the geographic bifurcation between East Asian scale production and European certification-heavy medical supply chains.
| Leading Market Players |
|---|
| Kitanihon Seiki |
| Timken |
| MinebeaMitsumi |
| GRW Bearings |
| NTN |
| NSK |
| Schaeffler Group |
| PacamorKubar Bearings |
| SKF |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification gates simultaneously constrain supplier qualification and stratify price tiers, as medical device OEMs withhold procurement volume from uncertified producers while paying premiums for traceable ceramic and stainless steel grades. This regulatory threshold fragments the supply base into certified premium suppliers and excluded commodity producers, concentrating pricing power with qualified European and Japanese manufacturers.
Pricing Analysis
Ceramic hybrid bearings command three-to-four-fold premiums over chrome steel equivalents, while next-generation silicon nitride formulations with in-house powder synthesis are pushing toward five-fold multiples against legacy grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal performance specifications, with ISO 13485 traceability and sub-micron roundness tolerances driving the widest spreads. Cost compression in standard chrome steel tiers is intensifying because of overcapacity in East Asian manufacturing corridors. Automotive tier suppliers exhibit highest price sensitivity, while surgical robotics OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Inventory buffers for high-purity ceramic powder have compressed to six-to-eight-week coverage, exposing European and Japanese bearing houses to qualification delays when Chinese processing facilities face regulatory inspections. Supply concentrates in China for ceramic powder synthesis, Japan for precision grinding equipment, and Germany for metrology calibration standards. Raw material dependencies span silicon nitride precursor chemicals, AISI 440C stainless steel rod stock, and specialized grinding wheel abrasives. Single-source vulnerability concentrates in Chinese ceramic powder facilities certified to evolving GB/T standards. Distribution runs through OEM direct procurement for medical applications and technical distributors for industrial automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EU MDR, and NMPA jurisdictions is carving out specialist niches, as simultaneous multi-certification requirements exceed the compliance bandwidth of generalized bearing producers. This fragmentation rewards focused players with concentrated certification investments.
For Market Incumbents: Consolidate supplier panel positions by acquiring captive ceramic powder processing capabilities, defending against margin erosion from qualified Chinese competitors. Lock in multi-year service agreements with German hospital procurement centralization at the Länder level, bundling predictive maintenance software to raise switching costs. Priority lever sits with backward integration into silicon nitride synthesis, cutting thermal expansion coefficients and securing sub-micron positioning accuracy claims. For New Entrants and Emerging Players: Aftermarket ceramic bearing retrofit services for legacy semiconductor wafer-handling systems represent a service-layer gap, as incumbent OEMs prioritize new equipment sales over maintenance revenue. Target South Korean and Taiwanese fabrication facilities with 300mm wafer thermal load upgrades, where equipment age exceeds fifteen years and ceramic replacement cycles accelerate. Go-to-market angle centers on rapid qualification partnerships with existing metrology laboratories in Stuttgart or Tokyo, bypassing the eighteen-month internal calibration buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cleanroom-compatible production lines, as ISO Class 7 facility investments of four-to-eight million dollars block mid-tier suppliers from medical robotics programs. Long-term viability favors specialists with simultaneous FDA 510(k), EU MDR, and NMPA registrations already completed, compressing competitive response windows to twenty-four-to-thirty-six months. Acquisition target archetype: mid-scale ceramic bearing producers with qualified cleanroom capacity but under-optimized aftermarket service attach rates. Signal to watch: NMPA inspection backlogs at Shanghai and Shenzhen medical equipment clusters, which would accelerate import substitution toward certified Japanese and European suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Production Line Investment | ISO Class 7 certification unlocks surgical robotics procurement from FDA-regulated OEMs. |
| Ceramic Powder Synthesis Integration | In-house silicon nitride production cuts thermal expansion coefficients by sixty percent for wafer-handling accuracy. |
| Multi-Jurisdiction Certification Registration | Simultaneous FDA 510(k), EU MDR, and NMPA filings compress competitor entry timelines. |
| Aftermarket Service Bundling | Predictive maintenance software raises switching costs with German hospital procurement centralization. |
| Regional Assembly Footprint Expansion | Indian PLI schemes in Pune and Chennai diversify supply nodes beyond East Asian concentration. |
Research Approach
A standing panel of surgical robotics procurement directors, precision bearing plant managers, semiconductor equipment reliability engineers, and hospital biomedical equipment specialists provided ongoing calibration across primary interview cycles. This practitioner input combined with secondary validation from FDA 510(k) filing databases, EU MDR notified body registration records, NMPA medical device classification announcements, and METI precision machinery export statistics. Bottom-up demand modeling from OEM specification sheets triangulated against top-down trade flow analysis from customs declarations.
Consistency checks validated volume and value outputs against external benchmarks including industrial automation capex surveys and medical device production indices across the analysis window. Segmentation dimensions modeled encompass product geometry, material grade, end-use certification requirements, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to equipment replacement cycles and technology substitution patterns. Industry-specific forecast inputs incorporated semiconductor fab capacity expansion announcements and surgical robotics OEM qualification pipeline disclosures.
Underlying assumptions cover continued NMPA enforcement of Class III device traceability requirements, with deviation risk concentrated in ceramic powder supply disruptions from Chinese GB/T standard revisions. Forecasts reflect these assumptions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market