
 Germany MLCC Market | 2026-2036
Germany MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Germany MLCC Market Insights
A shift from single-source to multi-source procurement is broadening supplier qualification programs across German automotive tier networks. Murata Manufacturing sustains its technology leadership through advanced dielectric formulations for high-voltage traction systems. TDK Corporation anchors regional supply security with expanded European distribution infrastructure. Würth Elektronik differentiates through specialized logistics capabilities serving mid-volume industrial OEMs.
Multilayer ceramic capacitors are passive electronic components constructed from alternating layers of ceramic dielectric and metal electrodes, sintered into monolithic blocks that achieve capacitance densities exceeding ten microfarads per cubic millimeter; they function primarily for decoupling, filtering, and energy buffering in high-frequency circuits. Ceramic-type MLCCs dominate volume shipments across German industrial automation and telecommunications infrastructure, while automotive-grade variants command premium positioning due to AEC-Q200 qualification requirements and extended temperature specifications. Surface mount technology leads assembly integration across all end-user segments, though through-hole configurations retain niche demand in power supply modules requiring enhanced mechanical stability.
KBA type-approval protocols and EU RoHS substance restrictions constrain material compositions and mandate comprehensive supply chain documentation for automotive-qualified components. REACH chemical registration requirements and the EU Green Deal circular economy mandates are progressively extending producer responsibility for end-of-life capacitor recovery. Stakeholders must monitor evolving battery-electric vehicle platform architectures and their cascading effects on DC-link capacitance requirements and voltage rating thresholds.
Market Dynamics
Automotive electrification is restructuring MLCC procurement across German OEM supply chains, forcing tier suppliers to qualify multiple sources for high-voltage traction components. The EU Green Deal's circular economy mandates are tightening material traceability requirements from mine to module.
Growth Catalysts
- Battery-electric vehicle platforms:German automakers are scaling 800V architectures that demand AEC-Q200 qualified MLCCs with extended temperature ratings. Tier-1 suppliers in Baden-Württemberg are expanding capacitor banks for DC-link stabilization.
- REACH chemical registration:Progressive compliance deadlines are filtering out non-compliant suppliers and consolidating procurement toward certified European distributors with full material documentation.
- Industrial automation retrofit cycles:Manufacturing facilities across Bavaria are upgrading servo drives and motor controls, generating sustained demand for high-frequency decoupling capacitors in surface-mount configurations.
Market Restraints
- Palladium and nickel price volatility:Terminal electrode materials constitute significant input cost exposure, compressing margins for mid-volume industrial OEMs locked into annual supply agreements.
- East Asian dielectric powder concentration:Sourcing of barium titanate formulations remains concentrated among specialized chemical producers, creating single-source risk for European MLCC manufacturers.
- RoHS substance restrictions:Exemptions for high-lead content in certain automotive-grade dielectrics are narrowing, forcing reformulation investments without guaranteed performance parity.
Strategic Opportunities
- Saxony semiconductor corridor:Emerging wafer fab investments near Dresden are creating localized demand for cleanroom-qualified passive components with ultra-low defect specifications.
- EU Green Deal battery passport mandates:Component-level traceability requirements are opening service revenue streams for distributors offering blockchain-verified supply chain documentation.
- Solid-state battery convergence:Next-generation cell architectures require redesigned protection circuitry, creating specification windows for MLCCs with higher ripple current tolerance.
Industry Challenges
- AEC-Q200 certification timelines:Extended qualification cycles for automotive-grade variants delay supplier onboarding, straining tier-2 manufacturers attempting to diversify beyond incumbent sources.
- Dielectric formulation IP complexity:Patent thickets around high-voltage X7R and C0G compositions create licensing friction for European manufacturers developing proprietary ceramic blends.
- Legacy through-hole inventory:Power supply modules in industrial automation retain mechanical stability requirements that conflict with surface-mount transition roadmaps, forcing dual-process manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany MLCC Market |
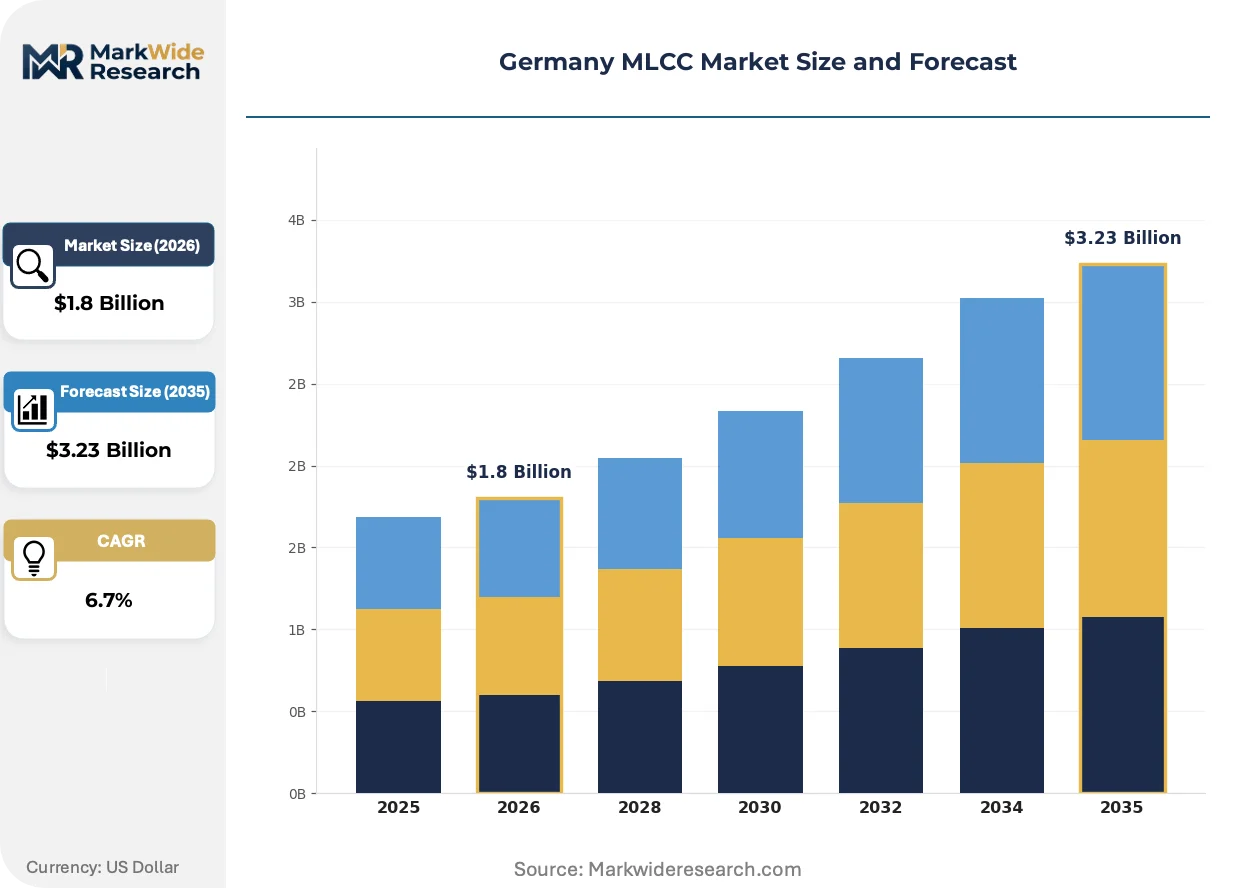
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer, Ceramic, Tantalum, Film End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Power Supply, Signal Processing, Energy Storage, RF Applications Technology: Surface Mount, Through-Hole, Carbonyl, Polymer |
| Companies Covered | Murata Manufacturing Co., Ltd, TDK Corporation, KYOCERA AVX Components Corporation, Samsung Electro-Mechanics Co., Ltd, Yageo Corporation, Taiyo Yuden Co., Ltd, Würth Elektronik GmbH & Co. KG, Vishay Intertechnology Inc., Walsin Technology Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany MLCC Market Trends and Innovations
Dielectric material science and procurement digitization are converging to reshape how German manufacturers specify and source passive components. Three developments merit close monitoring.
Nanoscale ceramic layering is decentralizing capacitor function integration across power electronics subsystems. Traction inverters from Stuttgart-based suppliers now embed distributed MLCC arrays rather than centralized capacitor banks, reducing loop inductance and enabling more compact thermal packaging. This topology shift is compressing the addressable market for discrete high-capacitance units while expanding unit volumes for mid-range voltage ratings.
REACH authorization procedures are tightening supply chain disclosure obligations for ceramic dielectric precursors. German compounders must now submit full substance flow analyses for barium titanate processing aids, extending lead times for new material qualifications. Automotive tier suppliers are responding by pre-qualifying alternative dielectric formulations ahead of sunset dates for legacy chemistries.
Consolidated vendor-managed inventory programs are displacing traditional spot purchasing for high-volume automotive programs. Tier-1 electronics manufacturers in Bavaria now integrate directly with distributor ERP systems, shifting working capital burden while demanding real-time consumption visibility. This arrangement is most advanced among battery pack assemblers facing just-in-sequence delivery requirements from OEM final assembly lines.
Germany MLCC Market Segmentation
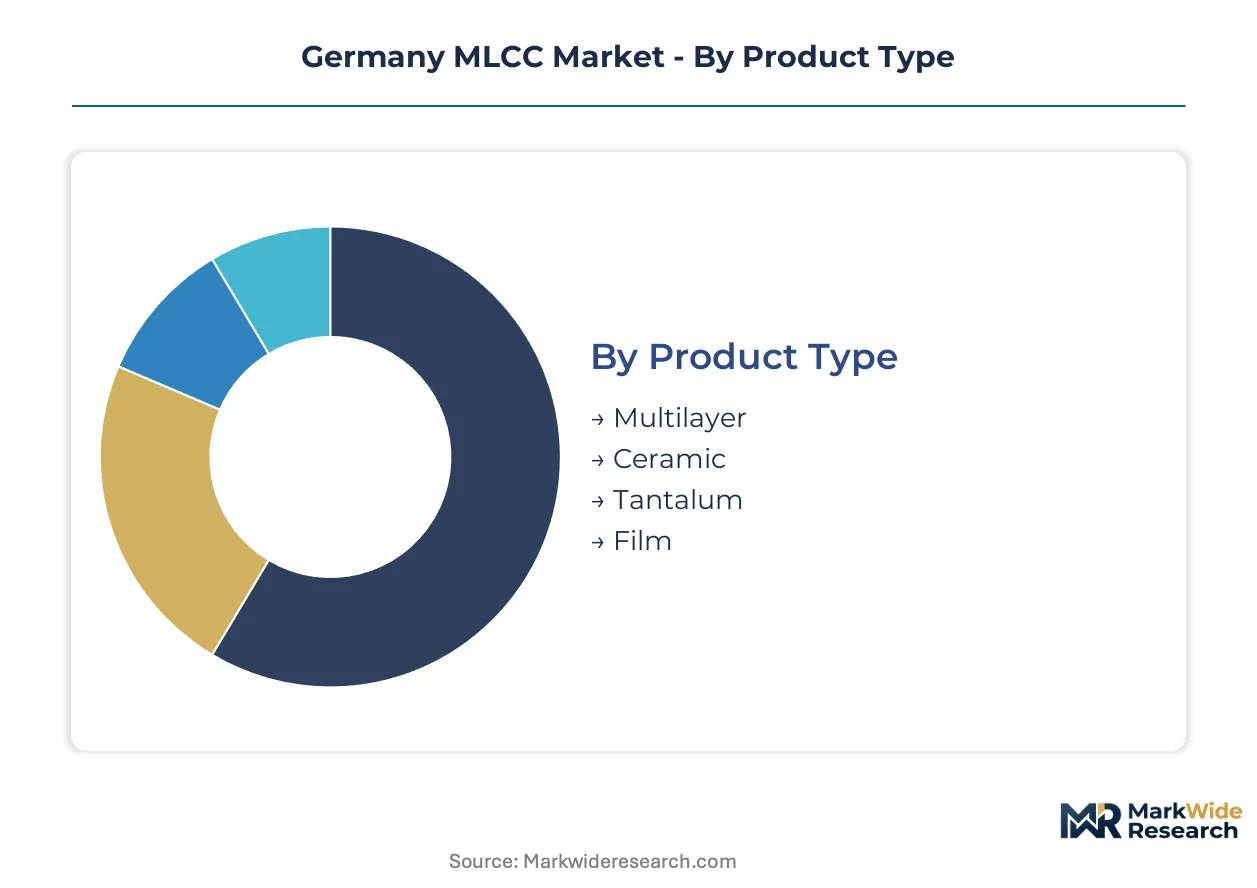
MLCC procurement in Germany stratifies sharply across product architectures and end-use requirements. Capital allocation decisions differ fundamentally between automotive-grade qualification programs and industrial volume plays.
Product Type:
Multilayer ceramic variants demand the heaviest upfront investment in dielectric formulation R&D and precision sintering equipment.
- Multilayer:Stacked alternating ceramic dielectric and metal electrode layers achieve capacitance densities exceeding ten microfarads per cubic millimeter. Demand concentrates in Baden-Württemberg traction inverter programs where distributed capacitor arrays replace centralized banks for reduced loop inductance.
- Ceramic:Barium titanate-based formulations dominate volume shipments across German industrial automation, though REACH authorization deadlines for processing aids are extending qualification lead times. Automotive-grade variants command premium positioning due to AEC-Q200 requirements and extended temperature specifications.
- Tantalum:Manganese dioxide and polymer cathode configurations serve niche aerospace and medical applications requiring stable capacitance under bias.
- Film:Polypropylene and polyester dielectrics retain position in power correction and motor run applications where self-healing properties outweigh MLCC density advantages.
Most installed capacity flows through Ceramic. Expansion is steepest in Multilayer.
End User:
Customer procurement patterns split between long-term automotive supply agreements and spot-driven industrial purchasing.
- Automotive:Battery-electric vehicle platforms scaling 800V architectures require AEC-Q200 qualified components with extended temperature ratings. Tier-1 suppliers in Baden-Württemberg are expanding capacitor banks for DC-link stabilization under KBA type-approval protocols.
- Industrial:Servo drive and motor control retrofit cycles across Bavaria generate sustained demand for high-frequency decoupling capacitors. Manufacturing facilities favor surface-mount configurations for automated assembly integration.
- Consumer Electronics:Smartphone and wearable OEMs prioritize compact case sizes and low equivalent series resistance for battery efficiency.
- Telecommunications:5G base station deployments drive demand for RF-grade MLCCs with tight capacitance tolerance and low dissipation factor.
Automotive commands the highest unit margins. Industrial delivers the steadiest volume throughput.
Application:
Functional requirements determine voltage rating hierarchies and dielectric material selection.
- Power Supply:Input filtering and output smoothing circuits in industrial drives require high ripple current tolerance and stable capacitance across temperature extremes.
- Signal Processing:Coupling and bypass functions in telecommunications infrastructure prioritize tight tolerance and low equivalent series inductance.
- Energy Storage:DC-link stabilization in electric vehicle inverters demands high volumetric efficiency and reliability under thermal cycling stress.
- RF Applications:Impedance matching and filtering in wireless base stations require ultra-low dissipation factor and precise capacitance control.
Power Supply absorbs the greatest dielectric tonnage. RF Applications expand most quickly with 5G infrastructure rollout.
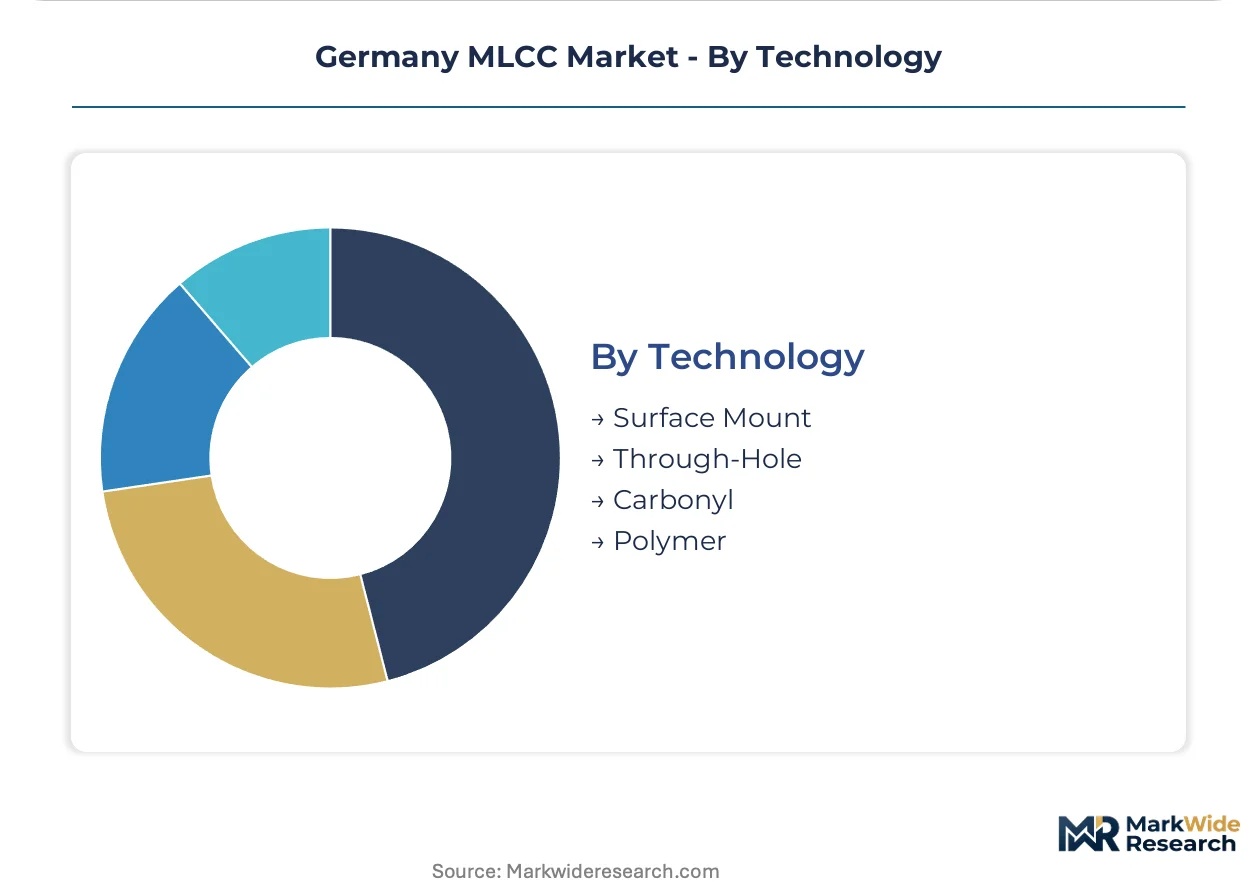
Technology:
Assembly method selection locks manufacturers into specific equipment footprints and process flows.
- Surface Mount:Tape-and-reel packaging dominates high-volume automated assembly across all end-user segments, enabling compact PCB layouts and reduced manufacturing labor content.
- Through-Hole:Radial and axial lead configurations retain demand in power supply modules requiring enhanced mechanical stability and thermal dissipation through the PCB.
- Carbonyl:Iron powder core inductors paired with MLCCs serve high-current DC-DC converter applications in automotive power distribution units.
- Polymer:Conductive polymer cathode technologies in hybrid configurations address low-ESR requirements for fast-switching processor power delivery.
Surface Mount represents the dominant installed base. Through-Hole maintains defensive positions in legacy industrial equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps under REACH and RoHS regimes are redirecting MLCC procurement flows toward jurisdictions with established chemical registration infrastructure. German manufacturers face stricter material documentation requirements than competitors in neighboring markets, creating localized sourcing advantages for distributors with pre-certified supply chains.
Bavaria
Semiconductor wafer fab investments near Dresden are generating demand for cleanroom-qualified passive components with ultra-low defect specifications. The EU Green Deal battery passport mandates are accelerating blockchain-verified supply chain documentation adoption among Munich-based distributors. Industrial automation clusters around Ingolstadt and Regensburg are retrofitting servo drives with high-frequency decoupling capacitors.
Baden-Württemberg
Traction inverter programs from Stuttgart-based suppliers are embedding distributed MLCC arrays rather than centralized capacitor banks. KBA type-approval protocols constrain material compositions for automotive-qualified components. The region's automotive electronics corridor is expanding capacitor procurement for 800V battery-electric vehicle architectures.
North Rhine-Westphalia
Chemical processing facilities in the Ruhr industrial belt are supplying barium titanate precursors under tightening REACH authorization deadlines. Düsseldorf-based distributors are consolidating vendor-managed inventory programs for high-volume automotive tier suppliers. Industrial equipment manufacturers in Cologne are transitioning power supply modules from through-hole to surface-mount configurations.
Lower Saxony
Volkswagen Group's battery cell production mandates are tightening material sourcing requirements for Wolfsburg-area procurement teams. The region's emerging semiconductor packaging facilities are creating demand for RF-grade MLCCs with tight capacitance tolerance. Hanover-based industrial automation OEMs are qualifying alternative dielectric formulations ahead of legacy chemistry sunset dates.
Hesse
Frankfurt's financial and logistics infrastructure is anchoring European distribution networks for East Asian MLCC manufacturers. The state's chemical sector is investing in dielectric powder formulation capabilities to reduce single-source dependency. Darmstadt-area research institutions are collaborating with compounders on next-generation ceramic material science.
Germany MLCC Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized logistics and traceability services. The Germany MLCC market exhibits a tiered structure with technology leaders, regional distributors, and mid-volume specialists competing across distinct value propositions. Three archetypes dominate: Japanese and Korean manufacturers with dielectric formulation IP, European distributors with supply security infrastructure, and specialized logistics providers serving industrial OEMs. Competitive moves concentrate on multi-source qualification programs and blockchain-enabled supply chain documentation.
Within the technology leadership tier, Murata Manufacturing Co., Ltd and TDK Corporation exemplify established players with advanced material capabilities. Würth Elektronik GmbH & Co. KG anchors the specialized logistics archetype, serving mid-volume industrial segments with differentiated distribution services. These three companies represent distinct competitive positions: dielectric formulation expertise, regional supply security, and targeted logistics capabilities respectively.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd |
| TDK Corporation |
| KYOCERA AVX Components Corporation |
| Samsung Electro-Mechanics Co., Ltd |
| Yageo Corporation |
| Taiyo Yuden Co., Ltd |
| Würth Elektronik GmbH & Co. KG |
| Vishay Intertechnology Inc. |
| Walsin Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
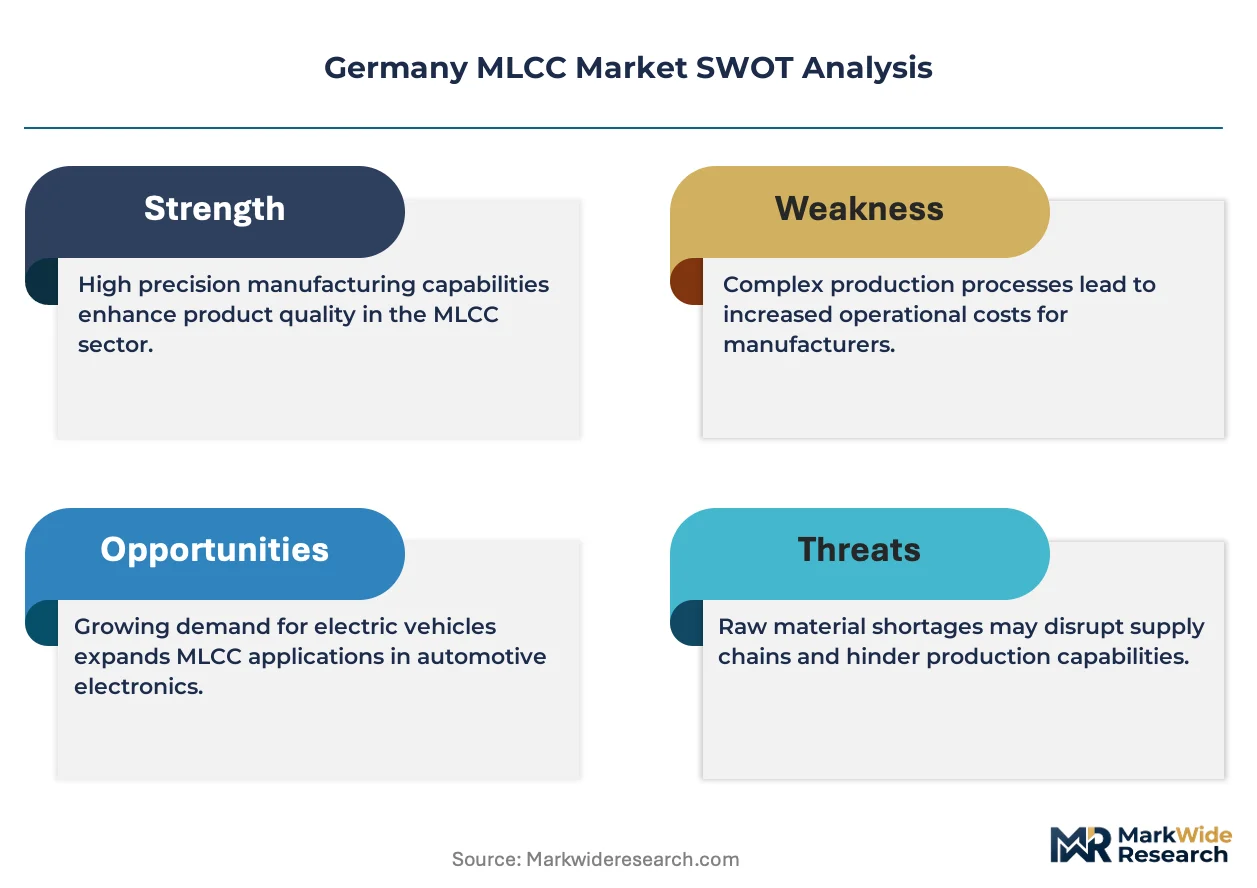
Automotive OEM consolidation around 800V battery-electric platforms is forcing tier suppliers to absorb dielectric powder cost volatility while maintaining fixed-price annual contracts. This procurement pressure is compressing margins for mid-volume industrial manufacturers and accelerating distributor consolidation toward vendors with captive barium titanate sourcing.
Pricing Analysis
Input-cost pass-through from palladium and nickel terminal electrode materials is fragmenting pricing power across supplier tiers. Three-tier pricing structure across automotive-grade, industrial-standard, and economy-level dielectric formulations separates AEC-Q200 certified components from general-purpose variants. Cost compression in industrial segments is intensifying because spot purchasers lack volume leverage against East Asian chemical producers. Mid-volume Bavarian automation OEMs exhibit the highest price sensitivity, while Baden-Württemberg traction inverter programs prioritize supply security over unit economics.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Munich anchor hub-and-spoke patterns serving automotive clusters across southern Germany. Manufacturing concentrates in Japan, South Korea, and Taiwan, with European compounding facilities in Hesse and North Rhine-Westphalia performing final dielectric formulation. Raw material dependencies span barium titanate precursors, palladium for inner electrodes, and nickel for termination layers. Single-source vulnerability in East Asian dielectric powder production creates exposure to logistics chokepoints through Rotterdam and Hamburg ports. Distribution runs through vendor-managed inventory programs that shift working capital burden to distributors with ERP integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in German MLCC procurement rests on dielectric formulation IP premiumization and distributor consolidation around blockchain-verified traceability services. Cost-down pressure from REACH compliance investments is filtering non-compliant suppliers and concentrating procurement toward certified European channels.
For Market Incumbents: Lock in multi-year qualification cycles with Baden-Württemberg tier-1 suppliers before AEC-Q200 certification timelines extend further. Defend against emerging logistics specialists by deepening backward integration into barium titanate precursor processing at Hesse compounding facilities. Prioritize patent licensing around high-voltage X7R formulations to extract royalty streams from European manufacturers developing proprietary ceramic blends.
For New Entrants and Emerging Players: Specialized distributors with blockchain documentation capabilities represent the most penetrable channel layer, as Munich-based battery pack assemblers face EU Green Deal battery passport mandates. Target Saxony's emerging semiconductor corridor near Dresden with cleanroom-qualified ultra-low defect components. Pursue vendor-managed inventory partnerships with Ingolstadt industrial automation clusters seeking consumption visibility without ERP infrastructure investment.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap European compounders possessing REACH-authorized dielectric formulations and established KBA type-approval documentation. Long-term viability in this market hinges on controlling ceramic powder processing rather than finished component assembly. Watch for inflection signals in solid-state battery platform announcements from Stuttgart-based OEMs, which would trigger specification windows for higher ripple current tolerance MLCCs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Precursors | Hesse compounders reduce single-source dependency on East Asian barium titanate suppliers. |
| Blockchain-Verified Supply Chain Documentation | Munich distributors capture service revenue from EU Green Deal battery passport mandates. |
| AEC-Q200 Certification Investment | Tier-2 manufacturers unlock procurement from 800V traction inverter programs in Baden-Württemberg. |
| Vendor-Managed Inventory Expansion | Bavarian distributors shift working capital burden while securing just-in-sequence delivery contracts. |
| High-Voltage Dielectric Formulation R&D | Patent holders extract licensing fees from European manufacturers developing proprietary ceramic blends. |
Research Methodology
Coverage spans Germany's federal states, with primary inputs from each major industrial cluster. The analysis combines structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, dielectric compounder technical directors, and distributor operations heads with secondary validation from KBA type-approval databases, REACH authorization registries, SEC filings of listed component manufacturers, and European customs trade data. Bottom-up demand modeling across automotive and industrial segments triangulates against top-down market sizing from production volume disclosures.
Granularity-level modeling disaggregates the projection horizon by product architecture, end-use qualification tier, voltage rating band, and regional procurement cluster. Segmentation dimensions include dielectric material class, AEC-Q200 certification status, assembly technology, and application function. CAGRs were derived from installed base turnover rates and content-per-vehicle trajectories across battery-electric platform rollouts. Forecast inputs incorporate DC-link capacitance specifications from 800V architecture disclosures and servo drive retrofit cycles across Bavarian manufacturing facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery commercialization timelines and REACH authorization sunset dates for legacy dielectric processing aids. Outputs reflect documented assumptions around OEM platform standardization and chemical registration compliance trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market