
 High Density Interconnect Market | 2026-2036
High Density Interconnect Market Size, Share, and Industry Trends Forecast 2026-2036
High Density Interconnect Market Intelligence
The substitution of traditional FR-4 substrates with advanced low-loss dielectric materials is expanding the performance envelope for high-frequency applications. TTM Technologies leverages its expertise in complex HDI for the aerospace and defense sectors. AT&S specializes in substrate-like PCB (SLP) technology for premium mobile devices. Unimicron Technology sustains its market position through large-volume manufacturing for the computing and consumer electronics industries.
High Density Interconnect refers to a class of printed circuit boards featuring finer lines and spaces, smaller vias, and higher connection pad density. These boards utilize microvia technology, often with diameters below 150 microns, to facilitate complex routing in a smaller footprint. While mobile devices drive volume for rigid-flex HDI formats, the telecommunication equipment segment commands the highest value with complex, multi-layer rigid HDI boards. Laser drilling and sequential lamination remain core technologies for achieving the required density.
Material selection and manufacturing processes are governed by a web of international standards, including Europe's RoHS and REACH directives which restrict hazardous substances. For defense applications in the United States, fabrication may need to comply with ITAR regulations, controlling the export of sensitive technologies. Suppliers must continuously balance investments in next-generation microvia and stacking technologies against cost pressures from high-volume consumer electronics clients.
Market Dynamics
The central dynamic in the High Density Interconnect market is the tension between relentless miniaturization driven by consumer electronics and the stringent reliability and material demands from the automotive, aerospace, and telecommunications sectors, forcing complex manufacturing trade-offs.
Growth Catalysts
- Automotive Electronics Proliferation:The integration of advanced driver-assistance systems (ADAS) and in-vehicle infotainment requires increasingly dense and complex HDI boards to manage high data rates within constrained spaces.
- Manufacturing Ecosystem Concentration:Established semiconductor and display ecosystems in Taiwan and South Korea create a powerful network effect, accelerating innovation and scaling up production for substrate-like PCBs and advanced HDI.
- Wearable Technology Miniaturization:The demand for smaller, lighter, and more functional wearable devices, from smartwatches to health monitors, directly fuels the need for rigid-flex HDI formats that can fit into unconventional form factors.
Market Restraints
- Advanced Material Costs:The substitution of standard FR-4 with specialized low-loss dielectric materials for high-frequency performance significantly increases raw material costs, pressuring margins in volume-driven segments.
- Yield and Reliability Challenges:As line and space widths shrink and microvia counts increase, maintaining high manufacturing yields becomes progressively more difficult, raising the risk of defects and field failures.
- Geopolitical Supply Chain Risk:The intense concentration of advanced HDI and substrate manufacturing in Taiwan and South Korea exposes the global electronics industry to significant disruption from regional political instability or natural disasters.
Strategic Opportunities
- High-Frequency Telecom Infrastructure:The rollout of 5G and future 6G networks creates a substantial opportunity for complex, multi-layer rigid HDI boards used in base stations, antennas, and backhaul equipment.
- Medical Device Integration:The convergence of HDI with flexible substrates enables the development of sophisticated medical implants and diagnostic tools that require biocompatible materials and high-density, reliable connections.
- Defense Modernization Programs:Government initiatives in the United States and Europe to upgrade defense and aerospace systems provide opportunities for ITAR-compliant fabricators specializing in high-reliability, ruggedized HDI boards.
Industry Challenges
- Capital Expenditure Intensity:The acquisition and maintenance of state-of-the-art equipment, such as laser drilling systems and automated optical inspection tools, require continuous and substantial capital investment to remain competitive. *Regulatory Compliance Overhead: Manufacturers must navigate a complex web of global standards, including Europe's RoHS and REACH directives on hazardous substances and the US ITAR regulations for defense products.
- Signal Integrity Expertise Gap:Designing high-speed HDI boards requires specialized engineering talent with deep knowledge of signal integrity, power integrity, and RF principles, a skill set that is in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density Interconnect Market |
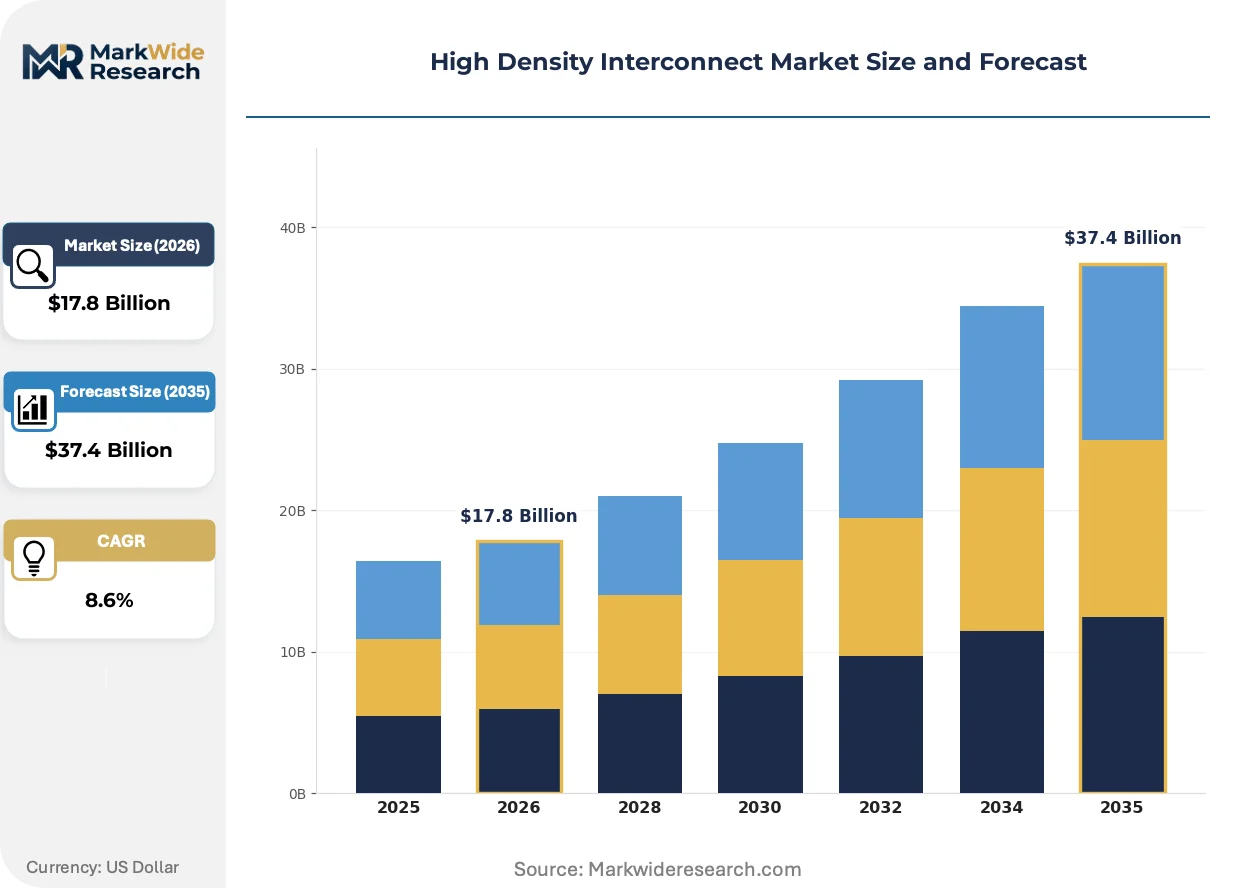
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $37.4 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid HDI, Flexible HDI, Rigid-Flex HDI, Semi-Flex HDI Technology: Laser Drilling, Sequential Lamination, Microvia, Via-in-Pad, Buried Via Application: Mobile Devices, Consumer Gadgets, Aerospace Electronics, Telecommunication Equipment, Wearable Tech End User: Contract Manufacturers, Telecom Operators, Defense Systems, Consumer Electronics Firms |
| Companies Covered | TTM Technologies, Compeq Co., Unimicron Technology, AT&S, Zhen Ding Technology, Ibiden Co., Samsung Electro-Mechanics, Tripod Technology, Nippon Mektron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density Interconnect Market Strategic Shifts & Innovations
Material science advancements are expanding the performance envelope for high-frequency designs. This push for higher performance is balanced by a parallel trend of increasing regulatory scrutiny over materials and manufacturing processes across key end markets like automotive and consumer electronics.
Substrate-like PCB (SLP) technology provides a crucial bridge between conventional printed circuit boards and advanced semiconductor packaging. Premium mobile device manufacturers are rapidly adopting SLP to achieve greater component density and improved electrical performance. This technology adoption is decentralizing interconnect complexity from the main logic board to the substrate itself, altering system-level design approaches.
Europe's REACH directive is forcing a significant re-evaluation of materials used in PCB fabrication. The regulation restricts a growing list of chemical substances, compelling suppliers to invest in R&D for compliant laminates, resins, and surface finishes. The consumer electronics and automotive segments, which have extensive supply chains into the EU, are most affected and are actively qualifying alternative materials.
A notable shift in buyer behavior is the move toward early-stage co-design partnerships, especially for complex applications. Instead of a transactional procurement process based on a finalized design, customers in the aerospace and defense sectors are engaging HDI fabricators during initial system architecture. This collaborative approach is most prominent in the United States for developing next-generation radar and communication systems.
High Density Interconnect Market Segmentation
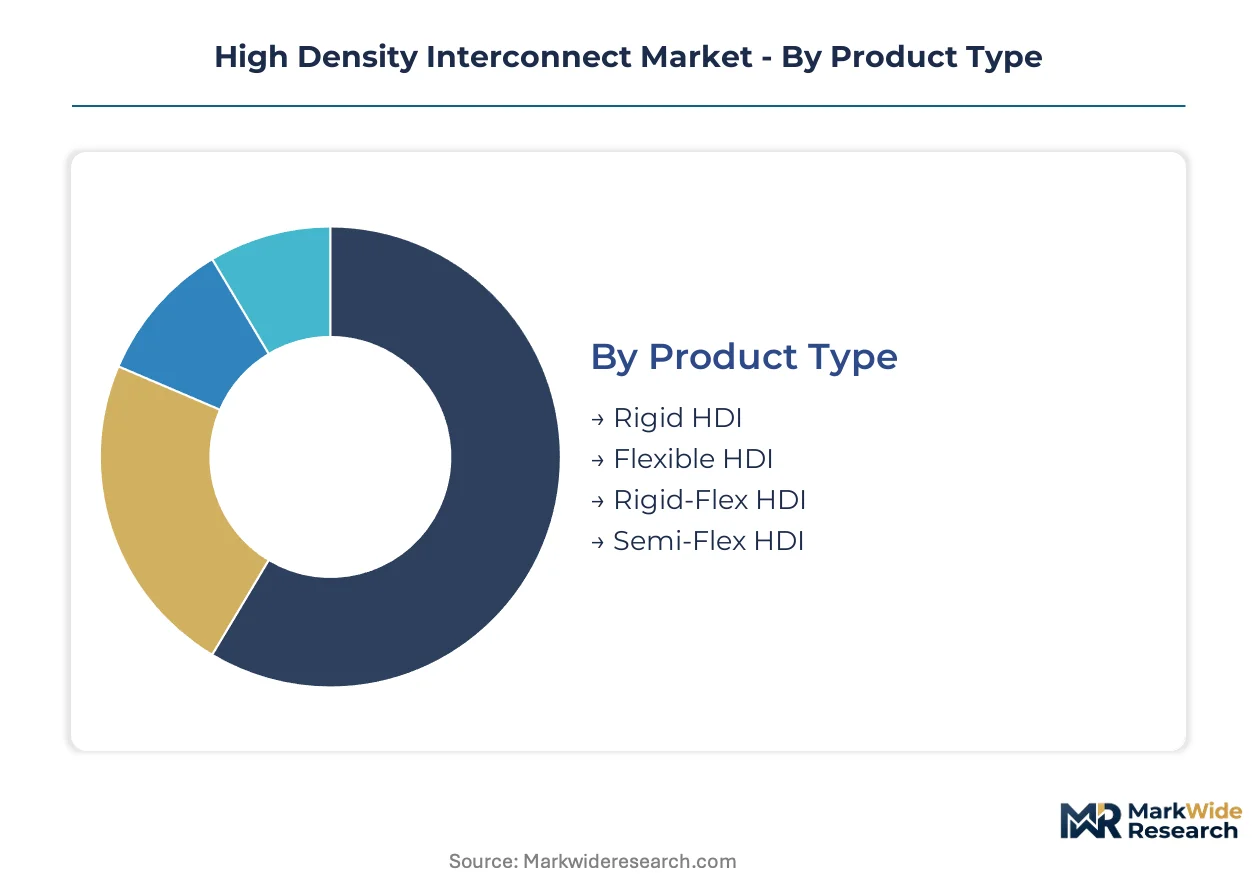
The High Density Interconnect market segments across various product types, core manufacturing technologies, diverse applications, and distinct end-user industries. Understanding these categories is critical for assessing specific demand drivers, technological adoption rates, and the competitive landscape for specialized fabrication services.
Product Type:
The various product types define the physical and electrical characteristics of the interconnect solutions available in the market.
- Rigid-Flex HDI:These boards combine rigid and flexible substrates, allowing for dynamic bending and complex three-dimensional packaging. Mobile devices and wearable technology miniaturization drive significant volume for these formats.
- Rigid HDI:Constructed from inflexible dielectric materials, these multi-layer boards offer high connection density and robust electrical performance. Telecommunication equipment and automotive electronics command the highest value for complex rigid HDI boards.
- Flexible HDI:Built on flexible substrates, these boards accommodate dynamic applications where bending or folding is essential. Medical device integration increasingly leverages flexible HDI for compact, implantable solutions.
- Semi-Flex HDI:These boards offer limited flexibility in specific areas, providing a cost-effective alternative for designs requiring some conformational capability. Industrial control systems utilize semi-flex HDI for space-constrained modules.
Rigid-Flex HDI leads on scale; Rigid HDI leads on momentum.
Technology:
Manufacturing precision and material manipulation define the core technologies employed in High Density Interconnect production.
- Laser Drilling:This advanced process creates microvias with diameters below 150 microns, enabling high-density routing and reduced board size. Laser drilling is essential for multi-layer HDI structures in premium mobile devices.
- Microvia:These small-diameter vias connect layers within an HDI board, significantly increasing connection density and reducing signal path lengths. The proliferation of advanced driver-assistance systems (ADAS) demands extensive microvia integration.
- Sequential Lamination:This technique builds HDI boards layer by layer, allowing for the embedding of components and creation of complex internal structures. Aerospace and defense applications frequently rely on sequential lamination for high reliability.
- Via-in-Pad:Placing vias directly within component pads saves board space and improves electrical performance by shortening traces. High-frequency telecom infrastructure benefits from Via-in-Pad technology for signal integrity.
- Buried Via:These vias connect internal layers without passing through all layers, optimizing routing channels and reducing electromagnetic interference. Complex computing and networking equipment utilize buried vias for signal integrity.
Laser Drilling technology maintains market dominance; Microvia fabrication is gaining share fastest.
Application:
The functional requirements of specific end-use applications dictate the design and performance parameters for HDI boards.
- Mobile Devices:Smartphones and tablets require ultra-compact, high-density boards to integrate numerous components within limited space. Substrate-like PCB (SLP) technology adoption is widespread in premium mobile devices.
- Telecommunication Equipment:Base stations, routers, and 5G infrastructure demand complex, multi-layer HDI boards capable of handling high data rates and signal integrity. High-frequency telecom infrastructure creates a substantial opportunity for these boards.
- Consumer Gadgets:Laptops, cameras, and gaming consoles utilize HDI for miniaturization and enhanced functionality. Unimicron Technology sustains its market position through large-volume manufacturing for consumer electronics.
- Aerospace Electronics:Avionics systems and satellite components require ruggedized, high-reliability HDI boards capable of operating in extreme environments. TTM Technologies leverages its expertise in complex HDI for this sector.
- Wearable Tech:Smartwatches, fitness trackers, and health monitors necessitate rigid-flex HDI formats that conform to irregular shapes. The demand for smaller, lighter wearable devices directly fuels HDI needs.
Mobile Devices drive significant volume demand; Telecommunication Equipment exhibits the steepest expansion trajectory.
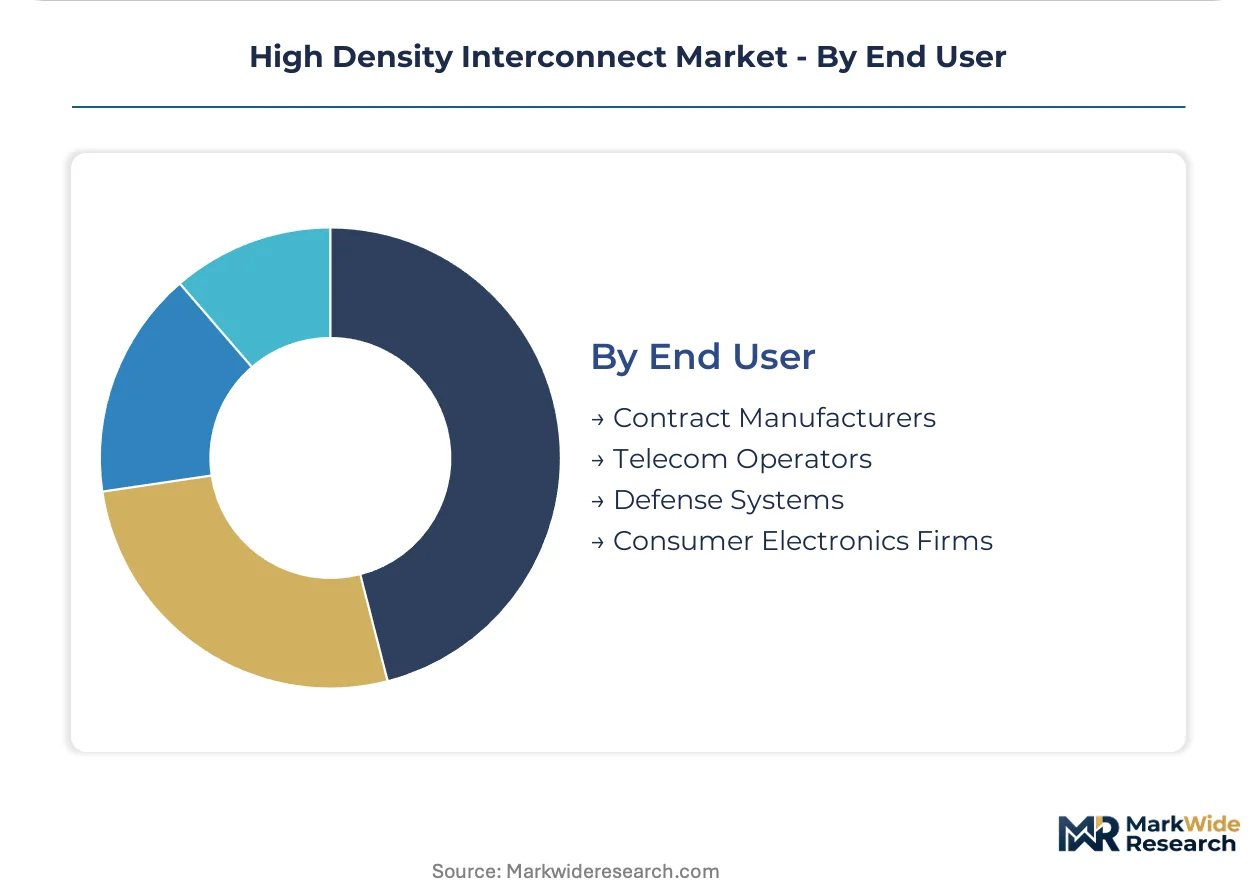
End User:
The diverse procurement patterns and technical demands of different end-user industries shape the customization and production scale of HDI solutions.
- Consumer Electronics Firms:These companies demand high-volume production of cost-effective HDI solutions for products like smartphones and laptops. Cost pressures from high-volume consumer electronics clients influence supplier investments.
- Defense Systems:Government contractors require ITAR-compliant, highly reliable, and ruggedized HDI boards for military communication and radar systems. Defense modernization programs provide opportunities for specialized fabricators.
- Contract Manufacturers:These firms produce HDI boards for various clients across different industries, offering specialized fabrication services. Manufacturing concentration in South Korea and Taiwan supports these operations.
- Telecom Operators:Companies deploying and maintaining network infrastructure procure HDI boards for base stations and networking equipment. The rollout of 5G and future 6G networks creates substantial demand.
Consumer Electronics Firms represent the largest customer base; Defense Systems command the highest value per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's established semiconductor ecosystem drives significant demand for advanced High Density Interconnect solutions across Asia. This concentration of manufacturing capabilities and technological expertise influences global supply chains for complex electronics. Key regions worldwide exhibit distinct demand patterns and regulatory frameworks for HDI.
South Korea
South Korea's robust mobile device industry fuels demand for advanced HDI and substrate-like PCB technologies. The country's Ministry of Food and Drug Safety (MFDS) influences material selection for medical device applications. Manufacturers in the Seoul Capital Area continuously innovate in microvia and stacking technologies.
Taiwan
Taiwan's strong computing and consumer electronics sectors require high-volume HDI production. The Industrial Development Bureau supports advanced manufacturing initiatives within the Hsinchu Science Park. This region remains a critical hub for substrate-like PCB fabrication.
United States
Defense modernization programs in the United States necessitate ruggedized, high-reliability HDI boards. ITAR regulations govern the export of sensitive aerospace and defense technologies from US fabricators. Silicon Valley and Arizona act as innovation centers for specialized HDI applications.
Germany
Germany's automotive industry demands complex HDI for advanced driver-assistance systems and in-vehicle infotainment. European directives like RoHS and REACH restrict hazardous substances in electronic components. Manufacturers in Bavaria focus on high-reliability solutions for industrial and automotive sectors.
Japan
Japan's consumer electronics and telecommunication equipment sectors drive demand for compact, high-performance HDI. The Ministry of Economy, Trade and Industry (METI) supports research into next-generation materials. Companies in the Kanto region specialize in high-frequency board designs.
High Density Interconnect Market Key Industry Players
Continuous capital investment dominates the current landscape for High Density Interconnect fabrication. The market exhibits a tiered structure, with specialized players coexisting alongside high-volume manufacturers. Strategic archetypes include advanced technology innovators, high-reliability specialists, and cost-efficient mass producers. Technology specialization and capacity expansion remain primary competitive moves.
Specialists in advanced HDI solutions include TTM Technologies, which represents expertise in complex designs for aerospace and defense applications requiring stringent reliability and performance in extreme environments. AT&S occupies a position as a leader in substrate-like PCB technology, particularly for premium mobile devices demanding higher component density and improved electrical performance. Unimicron Technology anchors the high-volume segment, exemplifying large-scale manufacturing capabilities for the computing and consumer electronics industries, sustaining its market position through efficiency and scale.
| Leading Market Players |
|---|
| TTM Technologies |
| Compeq Co. |
| Unimicron Technology |
| AT&S |
| Zhen Ding Technology |
| Ibiden Co. |
| Samsung Electro-Mechanics |
| Tripod Technology |
| Nippon Mektron |
| Others |
Cost & Logistics Intelligence
Consumer Electronics Firms, demanding high-volume HDI solutions, primarily drive transactional per-unit pricing. This dynamic places continuous cost pressure on suppliers, influencing material selection and manufacturing process investments.
Pricing Analysis
Input material costs, especially for advanced low-loss dielectric substrates, significantly impact HDI pricing. Per-unit transactional pricing dominates for high-volume consumer electronics, while contract-based long-term agreements characterize defense and aerospace procurement. Price differentiation stems from quality grade, ITAR compliance, and customization levels. Consumer Electronics Firms exhibit the highest price sensitivity, contrasting sharply with Defense Systems' focus on reliability over cost.
Supply Chain Analysis
Direct-to-OEM channels facilitate the supply of HDI boards to major consumer electronics and automotive manufacturers. Supply concentration centers heavily on Taiwan and South Korea, which are critical for advanced substrate manufacturing. Raw material dependencies include specialized low-loss dielectric materials and advanced laser drilling systems. Geopolitical instability in these concentrated regions presents a significant supply chain risk for global electronics industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Density Interconnect market represents a late-cycle quality narrative, driven by premium specifications required for advanced driver-assistance systems (ADAS) and 5G infrastructure. This shift necessitates higher reliability and performance characteristics from HDI solutions.
For Market Incumbents: Anchor market position through continuous investment in next-generation microvia and stacking technologies. Develop strategic co-design partnerships with aerospace and defense clients to mitigate cost pressures from high-volume consumer electronics. Expanding ITAR-compliant fabrication capacity in the United States strengthens resilience against geopolitical supply chain risks. Prioritizing R&D into low-loss dielectric materials maintains a performance edge.
For New Entrants and Emerging Players: Begin with niche, high-value applications such as medical device integration that demand specialized biocompatible flexible HDI. Target high-frequency telecom infrastructure, focusing on complex multi-layer rigid HDI boards for 5G and future 6G networks. A go-to-market strategy emphasizing rapid prototyping and specialized certification for specific end-use cases can create market entry.
For Investors and Strategic Acquirers: Telecommunication infrastructure providers are the most active strategic acquirers in this space, seeking to secure critical HDI supply for 5G and 6G buildouts. The market exhibits long-term viability, driven by essential integration into automotive, telecom, and medical devices. Target specialized fabricators possessing ITAR compliance or advanced substrate-like PCB (SLP) technology. Watch for sustained capital expenditure intensity in laser drilling and sequential lamination as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in ITAR-Compliant Facilities | This secures supply for defense modernization programs in the United States. |
| Advanced Material R&D Investment | This expands performance envelopes for high-frequency 5G and 6G applications. |
| Co-Design Partnership with Automotive OEMs | This ensures HDI solutions meet stringent reliability and data rate demands for ADAS. |
| Substrate-Like PCB Technology Acquisition | This enables greater component density and electrical performance for premium mobile devices. |
| Microvia Technology Specialization | This supports miniaturization trends in wearable technology and medical implants. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and internal databases — were reconciled for this analysis. Interviews engaged HDI fabricator R&D directors, automotive electronics procurement managers, and telecom equipment design engineers. Secondary data drew from industry association reports, government trade data, and technical journals. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Data-stream reconciliation established a robust analytical framework leveraging historical trends and quantitative modeling across the analysis window. Segmentation covered product type, manufacturing technology, application, and end-user industry. Compound annual growth rates were derived from projected future demand. Key forecast inputs included ADAS penetration rates and global 5G/6G network deployment schedules.
Several conditions sit outside the modeled scope, including specific component-level pricing variations and detailed geopolitical conflict scenarios. Forecasts reflect base assumptions and are subject to revision from unforeseen regulatory changes or rapid material science advancements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market