
 Laminated Busbar Market | 2026-2036
Laminated Busbar Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Busbar Market Analysis
Copper is restructuring laminated busbar economics as aluminum substitution stalls in high-current EV and data center applications. Rogers Corporation leverages its epoxy-based insulation expertise to dominate thermal management segments. Zhuzhou CRRC Times Electric anchors rail and grid infrastructure demand through captive copper processing. Amphenol Corporation differentiates via connector-integrated busbar architectures that reduce assembly complexity for OEM customers.
A laminated busbar consists of multiple conductive layers—typically copper or aluminum sheeting—bonded with dielectric films and compressed under heat and pressure to form a low-inductance, high-current distribution path rated from hundreds to thousands of amperes. The primary purpose centers on compact, reliable power distribution in confined spaces where traditional cable harnesses generate excessive heat and electromagnetic interference. Rigid busbars occupy the mature utility and industrial machinery base where standardization sustains margin compression, while flexible busbars capture the fastest expansion in electric vehicle battery packs and renewable energy inverters where vibration tolerance and thermal cycling resistance command premium positioning. Pre-insulated variants are gaining share in data center and commercial building deployments where installation labor costs drive specification toward plug-and-play modularity.
The US NHTSA and EPA are tightening electrical safety and efficiency mandates for EV powertrains, directly influencing busbar insulation ratings and conductive material selection. China's GB standards and MIIT technical rules for energy storage systems are accelerating hybrid material adoption to meet dual carbon goals without sacrificing current density. Europe's REACH and RoHS frameworks restrict certain flame retardants in dielectric films, pushing Mersen Group and Ryoden Kasei toward halogen-free polymer development. Stakeholders must monitor how regional material compliance timelines diverge, as certification lags in one jurisdiction can lock suppliers out of multi-year procurement cycles.
Market Dynamics
Copper-intensive flexible busbar assemblies are displacing aluminum alternatives in high-voltage battery packs as thermal management requirements intensify across electric vehicle platforms. This material pivot is compressing supplier margins while elevating technical barriers for new entrants.
Growth Catalysts
- GB Standard Upgrades:China's NMPA and MIIT are mandating enhanced electrical safety protocols for energy storage systems, compelling manufacturers to adopt higher-grade dielectric films and hybrid conductive materials.
- EV Battery Pack Integration:Automotive OEMs in Germany's industrial corridor are specifying laminated busbars for power conversion modules to manage thermal loads in confined chassis spaces.
- Data Center Density:Pre-insulated busbar variants are capturing share in hyperscale facilities where installation labor costs and electromagnetic interference suppression drive specification toward modular plug-and-play architectures.
Market Restraints
- Copper Price Volatility:Raw material cost swings in copper concentrates are compressing fabrication margins and destabilizing long-term procurement contracts for tier-two suppliers.
- REACH Compliance Burden:Europe's restrictions on halogenated flame retardants in dielectric films are forcing Mersen Group and Ryoden Kasei toward expensive polymer redevelopment cycles.
- Aluminum Substitution Ceiling:Technical limitations in current-carrying capacity and thermal cycling resistance prevent aluminum busbars from penetrating amperage ratings above 800A in EV applications.
Strategic Opportunities
- US Grid Modernization:The IRA's clean energy tax credits are accelerating utility-scale battery deployments where laminated busbars reduce inverter footprint and maintenance cycles.
- Connector-Busbar Convergence:Integration of power distribution and signal interconnect functions is enabling single-source procurement models that reduce OEM assembly complexity.
- Rail Electrification:Zhuzhou CRRC Times Electric's captive copper processing infrastructure positions laminated busbar suppliers for traction power upgrades across China's high-speed network.
Industry Challenges
- Dielectric Film Certification:Multi-jurisdiction testing protocols for thermal class ratings and flame propagation resistance are extending product qualification timelines by 12-18 months.
- Skilled Lamination Technicians:Shortages in heat-press operators and polymer bonding specialists are constraining capacity expansion at mid-tier fabrication facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Busbar Market |
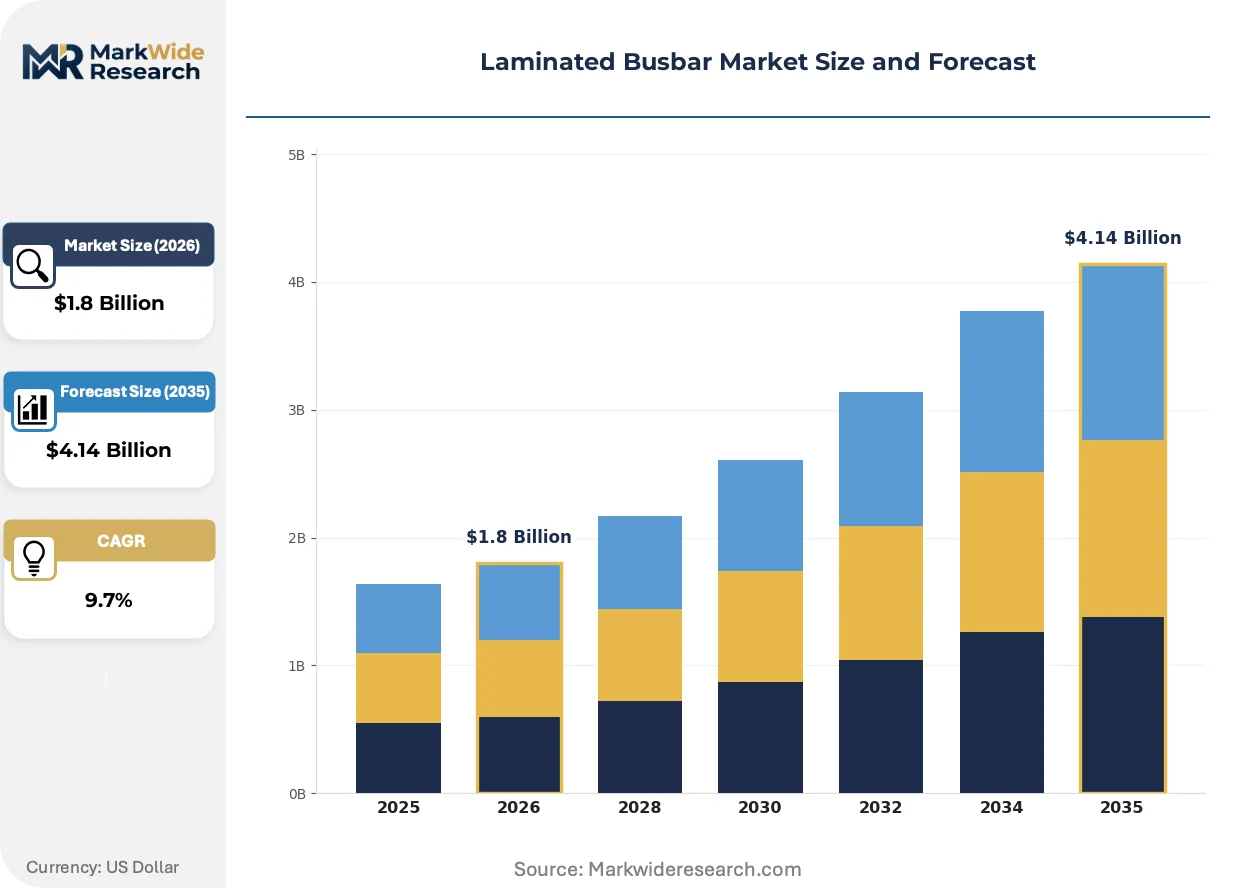
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Busbars, Rigid Busbars, Pre-insulated Busbars, Composite Busbars Application: Power Distribution, Renewable Energy, Electric Vehicles, Industrial Machinery Material: Copper, Aluminum, Silver, Hybrid Materials End User: Commercial Buildings, Utilities, Manufacturing Plants, Data Centers |
| Companies Covered | Rogers Corporation, Zhuzhou CRRC Times Electric, Amphenol Corporation, Storm Power Components, Ryoden Kasei, Methode Electronics, Sun.King Power Electronics Group, Electronic Systems Packaging, Mersen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Busbar Market Emerging Trajectories
Flexible busbar architectures are converging with thermal interface materials to create multifunctional power distribution assemblies. This convergence is compressing the supplier base toward integrated subsystem providers.
Hybrid copper-aluminum layered constructions are converging with epoxy-based insulation systems to reduce weight without sacrificing current density. EV battery pack integrators in Germany and China are adopting these configurations for vibration-tolerant cell-to-pack connections. The technology is converging with automated lamination processes that compress unit economics for high-volume contracts.
Europe's REACH and RoHS frameworks are restricting certain brominated flame retardants in busbar dielectric films, compelling material suppliers toward phosphorus-nitrogen halogen-free alternatives. The industrial consequence is a 15-20% cost premium for compliant films that must be absorbed or passed through. Grid-scale battery integrators in Germany and data center operators in France are responding by consolidating procurement around certified suppliers with pre-validated material stacks.
Automotive OEMs are unbundling power distribution subsystem design from final vehicle assembly, creating direct procurement relationships with busbar specialists rather than tier-one harness suppliers. This disintermediation is visible most acutely in Germany's automotive corridor, where BMW and Volkswagen Group have established dedicated engineering teams for high-voltage busbar specification. Tier-one electrical suppliers are responding by acquiring lamination capabilities or exiting the high-amperage segment entirely.
Laminated Busbar Market Segmentation
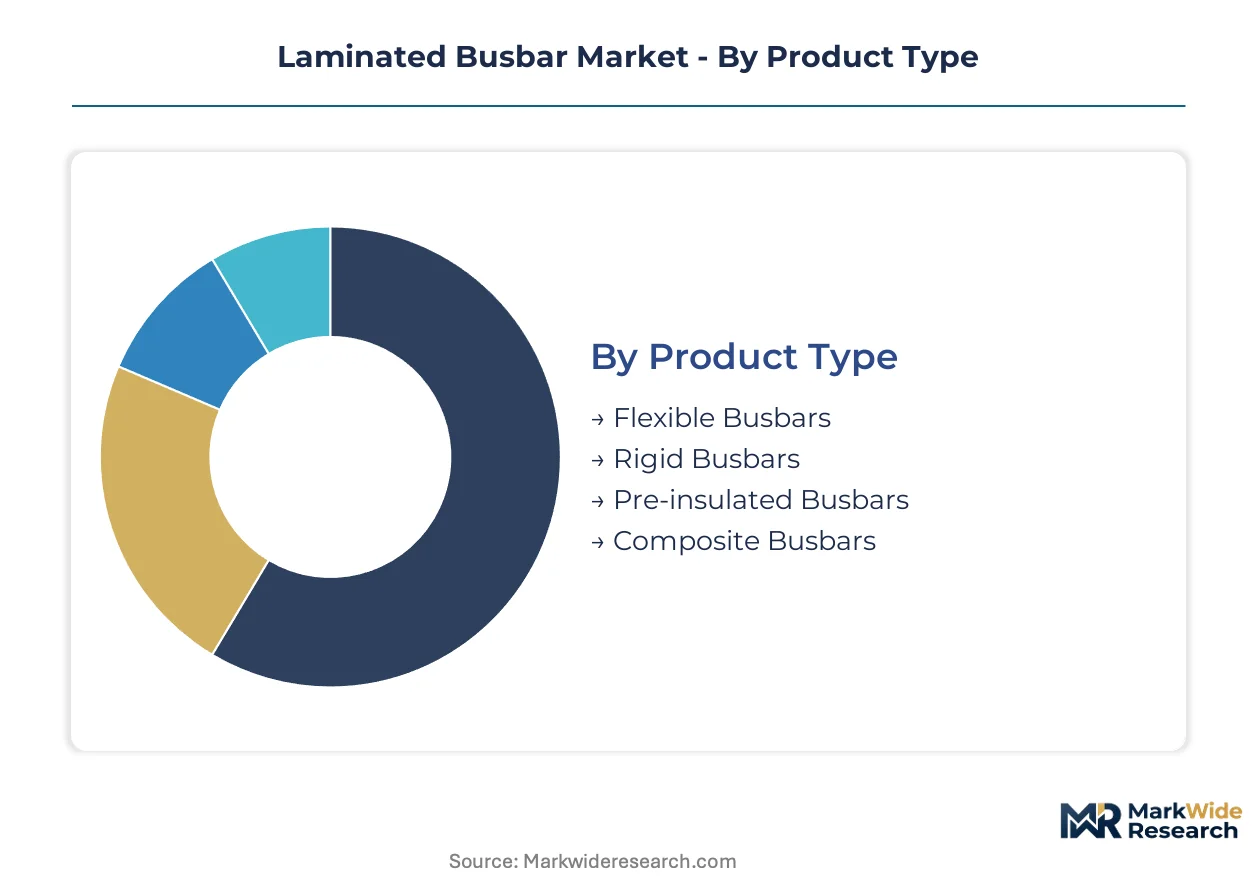
Segmentation in laminated busbars reveals how technical specifications diverge across thermal load, vibration tolerance, and installation constraints. Buyers prioritize fundamentally different performance envelopes depending on whether they manage megawatt-scale inverter farms or confined battery pack architectures.
Product Type:
Cost tiers separate buyers seeking commodity replacement parts from those procuring integrated thermal-electrical subsystems.
- Flexible Busbars:Multi-layer copper or aluminum foils laminated with polyimide or epoxy films enable tight-radius bending and vibration absorption. Automotive OEMs in Germany's industrial corridor specify these for cell-to-pack connections where thermal cycling and chassis flexure demand mechanical compliance.
- Rigid Busbars:Solid copper or aluminum bars with bonded insulation layers deliver fixed-form power distribution in utility switchgear and industrial motor control centers. Standardization sustains margin compression as buyers treat these as commodity electrical infrastructure.
- Pre-insulated Busbars:Factory-terminated plug-and-play modules reduce on-site labor for data center and commercial building contractors.
- Composite Busbars:Hybrid metal-polymer constructions target weight-sensitive aerospace and rail electrification applications.
Rigid busbars lead volumes today; flexible variants are gaining share fastest.
Application:
Volume concentration tracks electrification investment cycles across mobility and grid infrastructure.
- Electric Vehicles:High-voltage battery packs and power conversion modules demand compact, low-inductance distribution paths rated to 800V and beyond. China's MIIT technical rules for energy storage safety are accelerating specification upgrades in domestic EV platforms.
- Renewable Energy:Solar inverters and wind turbine converters require busbars that minimize parasitic inductance in high-frequency switching environments. The US IRA's clean energy tax credits are expanding procurement pipelines for utility-scale battery-integrated solar farms.
- Power Distribution:Substations and switchgear sustain replacement demand across mature grid infrastructure.
- Industrial Machinery:Motor drives and welding equipment consume standardized copper busbar assemblies.
Power distribution leads volumes today; electric vehicles are climbing the fastest.
Material:
Conductive material selection hinges on current density requirements versus weight and cost constraints.
- Copper:Superior electrical conductivity and thermal dissipation dominate high-amperage EV battery packs and data center busway systems. Raw material price volatility is compressing fabrication margins and destabilizing long-term procurement contracts.
- Aluminum:Lower density and cost suit applications below 800A where current-carrying capacity and thermal cycling resistance are less critical. Technical limitations prevent penetration into premium EV and high-performance computing power distribution.
- Silver:Plated contact surfaces enhance conductivity in specialized high-reliability connectors.
- Hybrid Materials:Copper-aluminum layered constructions reduce weight without sacrificing current density in aerospace and premium automotive applications.
Copper leads volumes today; hybrid materials show the steepest expansion trajectory.
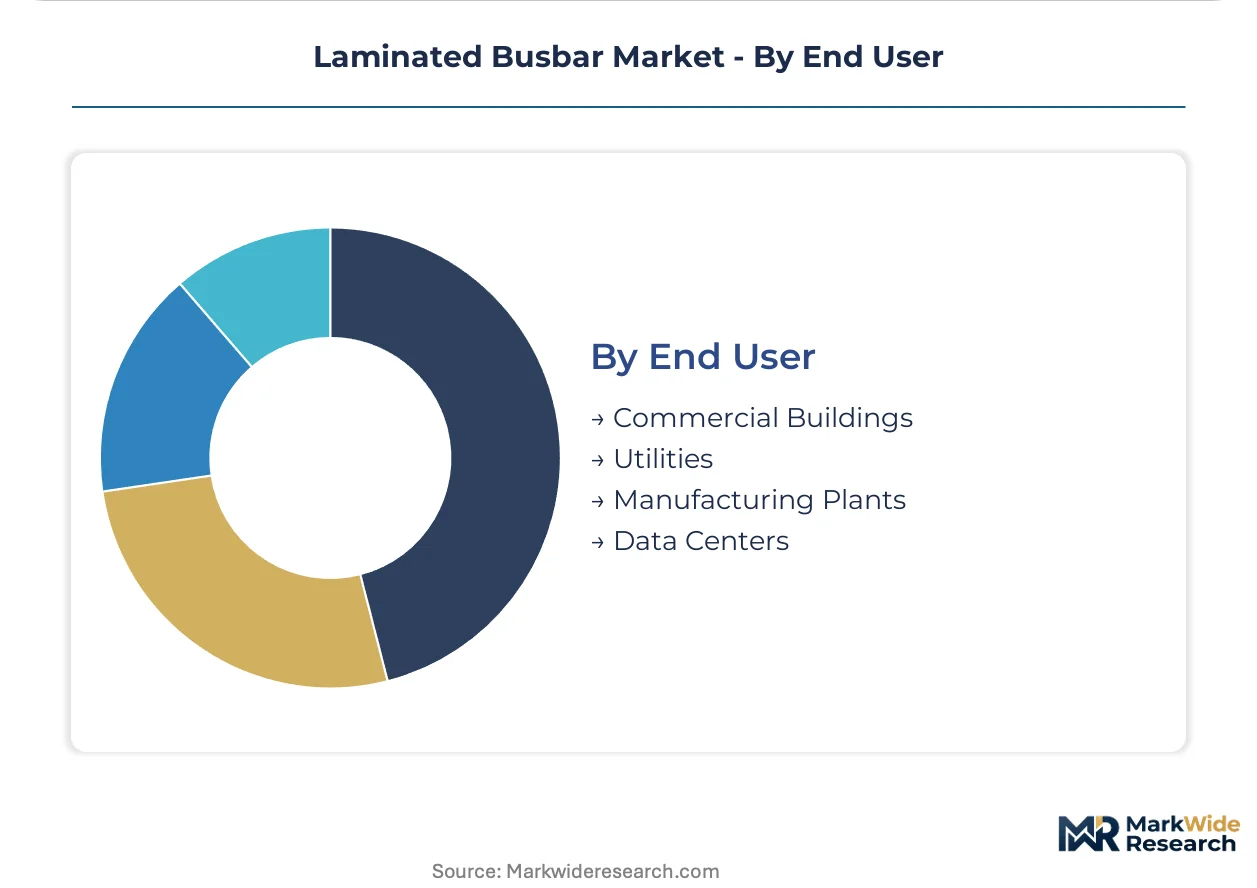
End User:
Customer procurement sophistication ranges from specification-driven engineering teams to cost-focused facilities managers.
- Data Centers:Hyperscale operators prioritize pre-insulated modular busbars that compress installation timelines and suppress electromagnetic interference in dense server environments. France-based operators are consolidating procurement around REACH-compliant suppliers with pre-validated halogen-free material stacks.
- Utilities:Grid-scale battery integrators specify laminated busbars for inverter footprint reduction and maintenance cycle extension. Germany's transmission operators are embedding these in power conversion modules for frequency regulation services.
- Commercial Buildings:Electrical contractors favor plug-and-play busbar trunking for retail and office fit-outs.
- Manufacturing Plants:Industrial motor control centers sustain replacement demand for rigid copper assemblies.
Manufacturing plants lead volumes today; data centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor concentrates laminated busbar demand from automotive OEMs and grid-scale battery integrators specifying power conversion modules. Regulatory divergence across major economies is fragmenting certification timelines and procurement patterns. Material compliance mandates in China and Europe are accelerating hybrid conductive material adoption while compressing supplier margins.
United States
Utility-scale battery deployments and data center expansions drive laminated busbar procurement for inverter footprint reduction. The IRA's clean energy tax credits accelerate grid modernization projects where busbars reduce maintenance cycles. Texas and California host the densest concentrations of hyperscale facilities specifying pre-insulated modular architectures.
China
High-speed rail electrification and domestic EV platform expansion anchor copper-intensive flexible busbar demand. MIIT technical rules and GB standard upgrades for energy storage safety compel manufacturers toward higher-grade dielectric films. Zhuzhou and Shenzhen industrial clusters concentrate captive copper processing and automated lamination capacity.
Germany
Automotive OEMs disintermediate tier-one harness suppliers to establish direct procurement relationships with busbar specialists. REACH restrictions on halogenated flame retardants force polymer redevelopment toward phosphorus-nitrogen alternatives. Bavaria's automotive corridor hosts dedicated engineering teams from BMW and Volkswagen Group specifying high-voltage busbar architectures.
Japan
Industrial machinery replacement demand and rail infrastructure upgrades sustain rigid busbar volumes in motor control applications. METI efficiency mandates influence conductive material selection for high-current distribution systems. Osaka and Nagoya manufacturing clusters concentrate precision lamination expertise for vibration-tolerant assemblies.
France
Data center operators consolidate procurement around REACH-compliant suppliers with pre-validated halogen-free material stacks. ECHA enforcement of RoHS flame retardant restrictions elevates certification barriers for dielectric film suppliers. Île-de-France hyperscale facilities prioritize plug-and-play modular busbar trunking to compress installation timelines.
Laminated Busbar Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and captive material processing. The vendor base stratifies into three tiers: integrated subsystem providers with connector-convergence expertise, captive copper processors serving rail and grid infrastructure, and specialized laminators focused on thermal management dielectrics. Consolidation pressure intensifies as automotive OEMs unbundle power distribution design from final assembly. Dominant competitive moves include backward integration into polymer film production and strategic partnerships with battery pack integrators for co-development contracts.
Within the integrated subsystem tier, Rogers Corporation and Amphenol Corporation exemplify players converging power distribution with signal interconnect functions to reduce OEM assembly complexity. Zhuzhou CRRC Times Electric anchors the captive processing archetype through in-house copper refining and rail-sector relationships. Mersen Group and Ryoden Kasei occupy positions within the dielectric specialization segment, navigating REACH compliance burdens through halogen-free polymer redevelopment. These archetypes represent how technical differentiation and regulatory adaptation separate sustainable positioning from margin compression.
| Leading Market Players |
|---|
| Rogers Corporation |
| Zhuzhou CRRC Times Electric |
| Amphenol Corporation |
| Storm Power Components |
| Ryoden Kasei |
| Methode Electronics |
| Sun.King Power Electronics Group |
| Electronic Systems Packaging |
| Mersen Group |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement teams in Germany's industrial corridor command the dominant pricing model through multi-year volume contracts that lock in copper-intensive flexible busbar supply. Tier-one electrical suppliers face compressed margins as these buyers disintermediate traditional harness providers to negotiate directly with lamination specialists.
Pricing Analysis
Copper concentrate cost pass-through dominates contract negotiations, with fabrication margins tethered to London Metal Exchange spot movements and quarterly adjustment clauses. Three-tier pricing structure across REACH-certified premium, standard industrial-grade, and economy aluminum-substitute tiers separates buyers by thermal class rating and flame retardant compliance. Pricing pressure stems from raw material volatility and skilled technician shortages constraining throughput. Data center operators exhibit lowest price sensitivity due to installation labor savings from pre-insulated modular architectures, while commercial building contractors drive hardest bargain on per-meter trunking costs.
Supply Chain Analysis
Skilled heat-press operators and polymer bonding specialists remain scarce across China's Zhuzhou-Shenzhen industrial corridor, Germany's Bavaria automotive cluster, and Japan's Osaka-Nagoya manufacturing belt. Supply concentration draws from Chinese captive copper processing, German precision lamination expertise, and Japanese dielectric film development. Raw material dependencies rest on Chilean copper concentrates, South Korean polyimide films, and halogen-free phosphorus-nitrogen polymer formulations. Single-source vulnerability pervades certified dielectric film supply as REACH compliance timelines diverge across jurisdictions. Distribution runs through direct OEM engineering relationships for automotive and grid-scale battery integrators, with distributor channels serving replacement demand in industrial machinery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in thermal management integration and REACH-certified premium tier migration as installation labor costs and regulatory compliance elevate buyer willingness-to-pay for validated material stacks.
For Market Incumbents: Deploy backward integration into halogen-free polymer film production to capture dielectric cost premiums and lock out uncertified competitors. Amphenol-style connector-busbar convergence represents a second lever to reduce OEM assembly complexity and deepen switching costs. Aluminum substitution threats from below and emerging Chinese lamination capacity from above compress breathing room for mid-tier specialists lacking captive material processing or integrated subsystem expertise. For New Entrants and Emerging Players: Enter via data center pre-insulated modular architectures where procurement consolidation around REACH-compliant suppliers creates white-space for certified new sources. France's Île-de-France hyperscale corridor and Texas-California facilities present most penetrable geographies given incumbent capacity constraints. Co-development partnerships with battery pack integrators offer fastest path to automotive qualification without tier-one harness supplier sponsorship. For Investors and Strategic Acquirers: Automotive OEM vertical integration teams are the most active acquirer in this space, seeking lamination capabilities to replace disintermediated harness suppliers. Long-term viability favors integrated subsystem providers with connector expertise and captive thermal interface material processing over pure-play laminators exposed to copper volatility. Watch dielectric film certification backlog duration as inflection indicator—qualification timeline extension beyond eighteen months signals supply constraint severe enough to trigger acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Production | Captures REACH compliance premiums and secures dielectric supply against certification bottlenecks. |
| Connector-Busbar Convergence | Amphenol-style integration reduces OEM assembly steps and deepens procurement switching costs. |
| Automated Lamination Capacity Expansion | Zhuzhou CRRC-style captive processing compresses unit economics for high-volume rail and EV contracts. |
| Halogen-Free Material Stack Certification | Mersen Group and Ryoden Kasei investments unlock data center and automotive procurement access. |
| Direct OEM Engineering Relationships | BMW and Volkswagen Group disintermediation bypasses tier-one harness supplier margin extraction. |
Methodological Framework
Coverage spans Germany, China, the United States, Japan, and France, with primary inputs from each market's automotive OEM platform engineers, tier-one supplier procurement directors, data center facilities managers, rail electrification project developers, and dielectric film polymer chemists. Secondary validation draws from MIIT technical rule filings, ECHA REACH substance restrictions, NHTSA electrical safety guidance, customs trade data for copper concentrate flows, and SEC filings from listed electrical component suppliers. Bottom-up project pipeline enumeration triangulates against top-down electrification investment forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type architecture, conductive material grade, end-use application intensity, and regional regulatory compliance cluster. CAGRs derive from fitted growth curves applied to disclosed capacity expansion timelines and procurement contract visibility. Industry-specific forecast inputs incorporate EV platform launch schedules and utility-scale battery deployment pipelines under the IRA and EU Green Deal frameworks.
Inputs from OEM engineering teams and polymer film suppliers were available through the study window; gaps in multi-jurisdiction dielectric certification timeline data introduce uncertainty bands around market share projections. Forecasts embed assumptions regarding copper price regime stability and REACH enforcement consistency. Material deviation in named triggers—qualification backlog extension, sudden copper concentrate supply disruption, or automotive OEM reversion to tier-one harness sourcing—warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Label Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
United States Electric Insulator Market