
 Soft Ferrite Market | 2026-2036
Soft Ferrite Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Ferrite Market Outlook
China's soft ferrite capacity expansion is reshaping competitive dynamics across the magnetic materials sector. TDK Corporation leverages its deep R&D portfolio in Mn-Zn ferrite formulations to sustain technology leadership in high-frequency applications. JFE Ferrite Co., Ltd. anchors Japanese supply security through integrated oxide powder production. DMEGC competes aggressively on manufacturing scale, operating some of the world's largest ferrite core facilities out of Zhejiang province.
Soft ferrite comprises ceramic, iron-oxide-based magnetic materials engineered with controlled porosity and grain structure to minimize eddy current losses at frequencies above 1 kHz, serving primarily as core material for transformers, inductors, and electromagnetic interference suppression components. Mn-Zn ferrites dominate volume consumption in power transformer applications where permeability above 2000 enables compact winding designs, while Ni-Zn ferrites lead in telecommunications filters and RF circuits demanding resistivity above 10^5 ohm-cm. The chip form segment captures expanding share in surface-mount inductor assemblies for consumer electronics miniaturization, whereas powder formulations retain margin concentration in customized magnetic compound supply to motor manufacturers.
China's GB standards for energy-efficient transformers, Japan's METI Top Runner program for industrial equipment efficiency, and the EU Ecodesign Directive collectively tighten core loss specifications and drive material substitution toward higher-grade ferrite compositions. REACH compliance in Europe and evolving RoHS thresholds further constrain allowable dopants and sintering additives, elevating purity requirements across export-oriented production. Stakeholders must monitor regulatory divergence between Asian efficiency labeling schemes and European material restriction frameworks when configuring regional product portfolios and certification investments.
Market Dynamics
China's dual carbon goals and updated GB energy efficiency standards are forcing rapid substitution toward high-grade Mn-Zn ferrite compositions across transformer and inductor supply chains. This regulatory compression is accelerating material upgrading faster than production capacity can adapt.
Growth Catalysts
- Electric vehicle powertrain electrification:Automakers in Germany, Japan, and South Korea are expanding high-frequency inverter and onboard charger programs that consume premium soft ferrite cores for magnetic isolation.
- REACH and RoHS compliance evolution:Europe's tightening material restriction frameworks are disqualifying legacy ferrite dopants and sintering additives, creating certified-supplier premiums for purified oxide formulations.
- Surface-mount inductor miniaturization:Consumer electronics manufacturers in Shenzhen and Seoul are scaling chip-form ferrite assembly for smartphone and wearable power management circuits.
Market Restraints
- Iron oxide and rare earth dopant cost volatility:Raw material input prices for high-purity Fe2O3 and controlled MnO sources fluctuate with mining output constraints and export licensing in supplier countries.
- East Asian production concentration risk:Over 70% of global ferrite core manufacturing capacity sits in Zhejiang province and surrounding industrial clusters, exposing buyers to single-region logistics disruptions.
- Amorphous metal and nanocrystalline ribbon substitution:Next-generation magnetic materials with lower core loss at frequencies above 100 kHz are displacing ferrite in high-efficiency transformer designs.
Strategic Opportunities
- India industrial motor retrofit programs:Bureau of Energy Efficiency standards for agricultural pump and industrial motor efficiency are creating import demand for Mn-Zn ferrite cores in domestic rewinding shops.
- 5G base station filter expansion:Ni-Zn ferrite formulations with resistivity above 10^5 ohm-cm are capturing share in telecommunications infrastructure RF suppression components.
- EU Ecodesign Directive tiered compliance:The staged implementation of maximum core loss limits is generating premium pricing windows for ferrite grades that exceed baseline specifications by 15-20%.
Industry Challenges
- Specialized ceramic engineering talent scarcity:Sintering process control and grain boundary engineering expertise required for sub-100 kHz power ferrite production concentrates in aging workforce pools in Japan and Germany.
- Multi-certification timeline compression:Simultaneous compliance with China's GB standards, Japan's JIS specifications, and EU REACH documentation creates 18-24 month product qualification cycles.
- Legacy transformer fleet replacement friction:Utilities and industrial facilities face capital allocation conflicts between immediate efficiency upgrades and extended depreciation schedules for installed ferrite-core equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Ferrite Market |
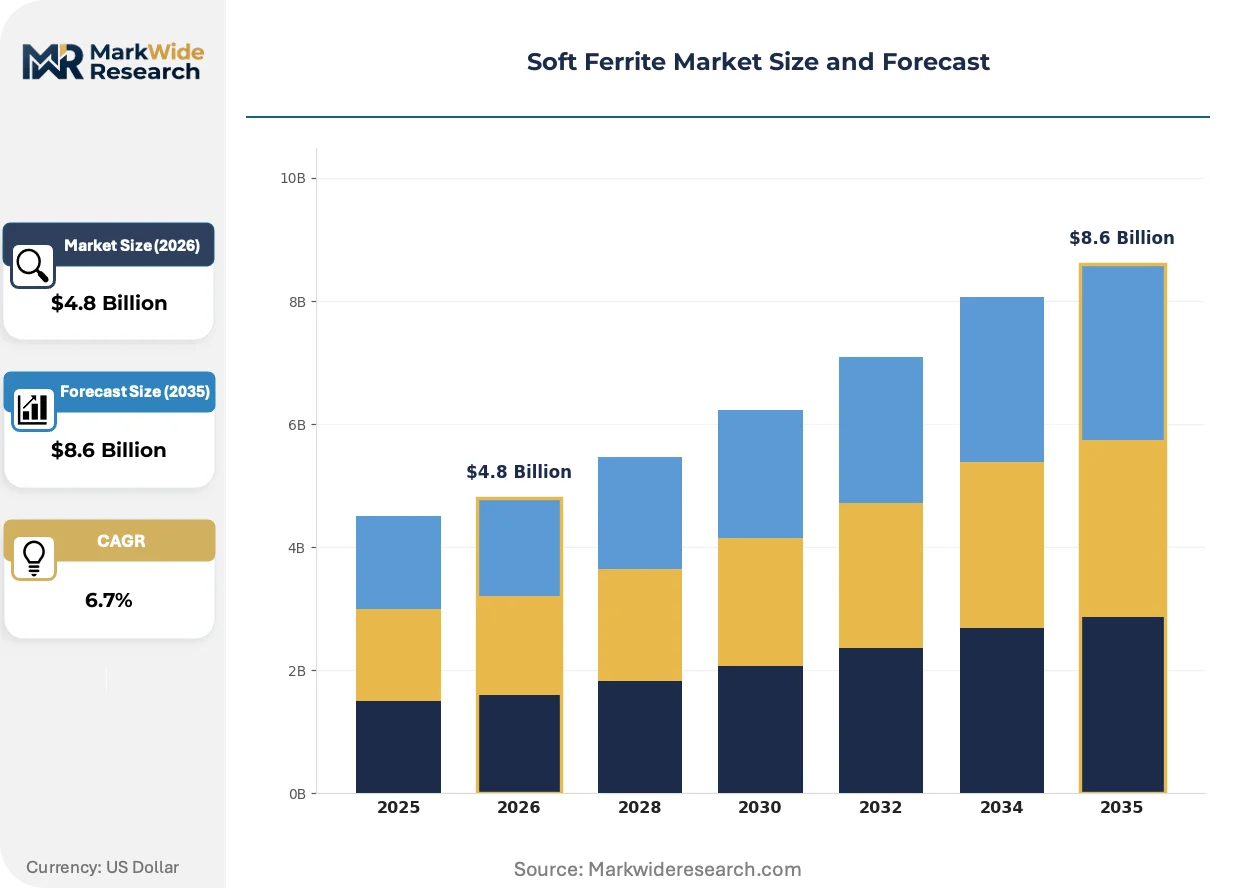
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mn-Zn Ferrites, Ni-Zn Ferrites, Cu-Zn Ferrites, Mg-Zn Ferrites End User: Consumer Electronics, Automotive Applications, Telecommunication, Industrial Equipment Form: Powder, Core, Chip, Rod Application: Magnetic Recording, Transformers, Inductors, Common Mode Chokes |
| Companies Covered | Ferroxcube, JFE Ferrite Co., Ltd., TDK Corporation, Fair-Rite Products Corp., Samwha Electronics, DMEGC, Hitachi Metals, Ltd., Samsung Electro-Mechanics, Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Ferrite Market Strategic Shifts
Computational materials science and process sensor networks are transforming how ferrite manufacturers optimize grain structure and porosity. These digital capabilities are compressing formulation development cycles and enabling predictive quality control.
Additive manufacturing of ferrite-polymer composite cores is digitizing prototyping workflows for custom inductor geometries. Motor and power supply designers in automotive and renewable energy sectors are adopting 3D-printed magnetic components for rapid validation. This capability is digitizing the traditional tooling-intensive sample production process, reducing iteration time from weeks to days.
Japan's METI Top Runner program for industrial equipment efficiency is mandating progressive core loss reductions in distribution transformers. The regulation forces ferrite suppliers to document permeability stability across temperature ranges with standardized test protocols. High-frequency power supply manufacturers targeting Japanese export markets are prioritizing certified material suppliers to preempt compliance verification delays.
Direct mill-to-winder supply contracts are displacing layered distribution networks for standardized ferrite cores. Large transformer OEMs in South Korea and Germany are negotiating volume commitments with oxide powder producers to secure allocation priority. This consolidation is most visible in the industrial motor and renewable energy inverter segments where annual offtake volumes exceed 500 metric tons.
Soft Ferrite Market Segmentation
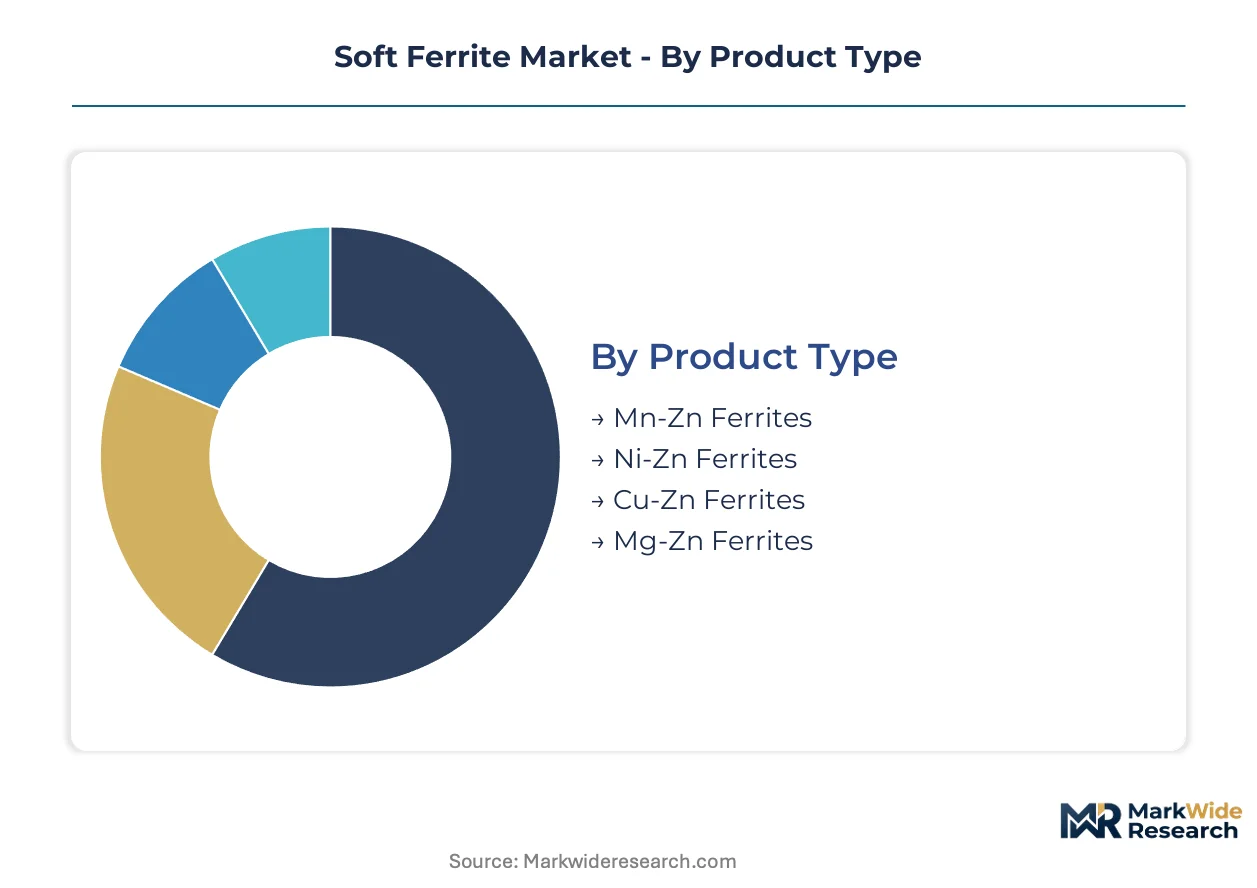
Soft ferrite segmentation reveals how material chemistry, physical geometry, and end-use requirements intersect to determine procurement patterns. Manufacturers configure product portfolios across four distinct category systems to match performance specifications with cost constraints.
Product Type:
Material chemistry governs permeability, resistivity, and temperature stability across the frequency spectrum from power conversion to RF suppression.
- Mn-Zn Ferrites:Manganese-zinc formulations deliver permeability above 2000 with controlled grain structure for sub-500 kHz power transformers. Demand concentrates in Shenzhen manufacturing clusters where high-efficiency inverter production for electric vehicle powertrains is scaling rapidly.
- Ni-Zn Ferrites:Nickel-zinc compositions achieve resistivity exceeding 10^5 ohm-cm, enabling stable performance in telecommunications filters above 1 MHz. Seoul-based RF component manufacturers are expanding procurement for 5G base station filter assemblies.
- Cu-Zn Ferrites:Copper-zinc variants occupy intermediate frequency ranges with cost-adjusted magnetic properties for consumer appliance motors.
- Mg-Zn Ferrites:Magnesium-zinc grades serve specialized high-temperature applications where thermal stability exceeds standard Mn-Zn limits.
The dominant share belongs to Mn-Zn ferrites, while Ni-Zn ferrites are closing the gap fastest.
End User:
Customer procurement scale and certification requirements create tiered supply relationships from commodity spot purchases to multi-year framework agreements.
- Consumer Electronics:Smartphone and wearable manufacturers in Shenzhen and Seoul drive chip-form ferrite consumption for surface-mount power management circuits. Miniaturization mandates are compressing core dimensions while maintaining inductance stability.
- Automotive Applications:German and South Korean automakers specify premium-grade Mn-Zn cores for onboard chargers and DC-DC converters. NHTSA electromagnetic compatibility requirements and equivalent EU type-approval standards are tightening material documentation protocols.
- Telecommunication:Base station infrastructure deployment is expanding Ni-Zn ferrite demand for RF interference suppression in 5G macro cells.
- Industrial Equipment:Motor rewind shops and transformer OEMs source standardized core geometries through distributor networks with volume-based pricing tiers.
Automotive procurement is expanding most quickly, though consumer electronics retains the largest volume position.
Form:
Physical configuration determines manufacturing process compatibility and assembly automation potential across discrete and integrated magnetic components.
- Core:Toroidal, E-core, and U-core geometries dominate transformer and inductor winding operations. German industrial motor manufacturers specify custom core dimensions through direct mill contracts to secure allocation priority.
- Chip:Surface-mount ferrite assemblies enable automated pick-and-place integration in high-density PCBs. Shenzhen consumer electronics fabs are scaling chip-form capacity for smartphone power management ICs.
- Powder:Granulated ferrite compounds feed compression molding and custom compound blending for motor manufacturers requiring tailored magnetic properties.
- Rod:Cylindrical ferrite elements serve antenna and inductor applications where axial winding geometries are specified.
Core forms command the largest installed base, while chip configurations are gaining share fastest through surface-mount adoption.
Application:
Functional performance requirements dictate ferrite grade selection, with core loss specifications and frequency response defining material substitution boundaries.
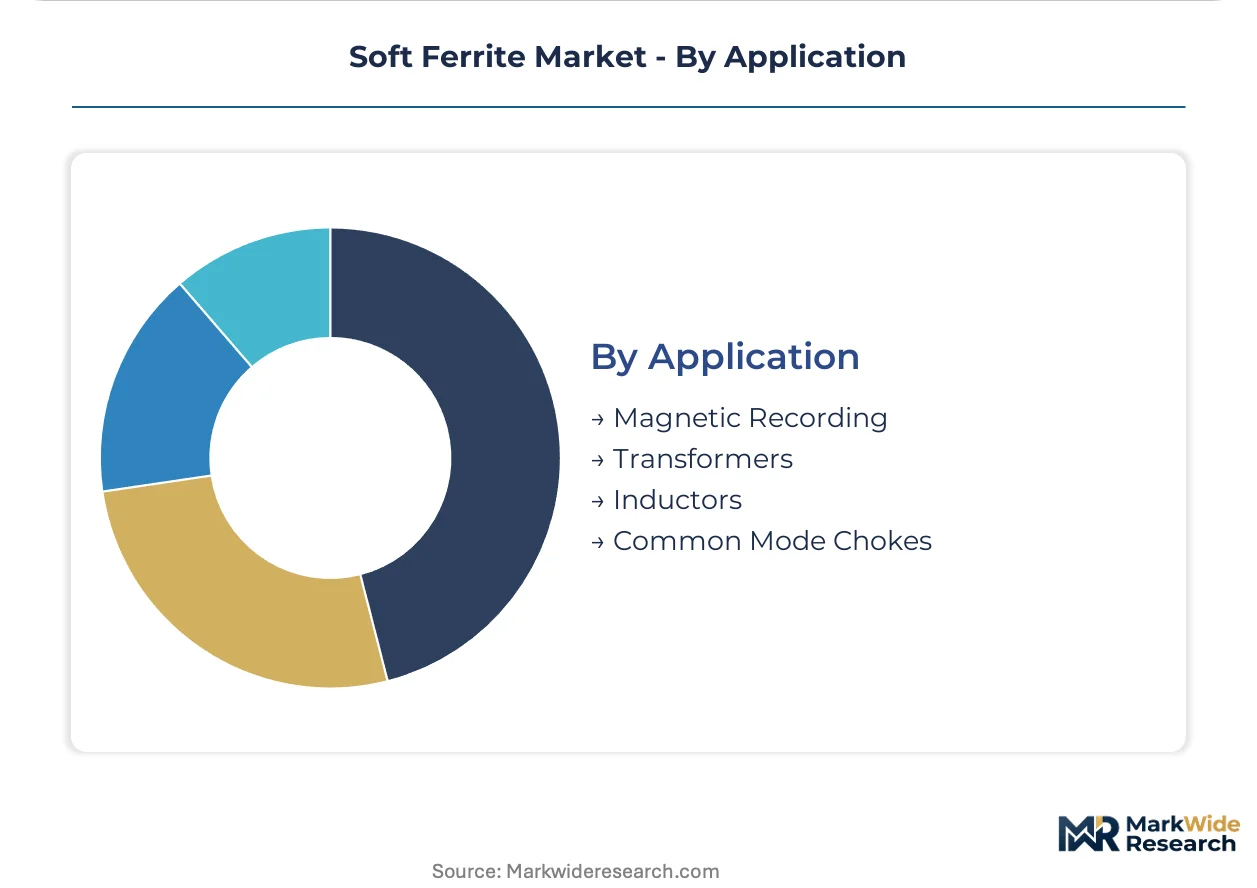
- Transformers:Power conversion applications from grid distribution to switched-mode supplies consume Mn-Zn ferrites with documented core loss curves across temperature ranges. China's GB energy efficiency standards are disqualifying legacy-grade materials from new transformer installations.
- Inductors:Energy storage and filtering functions in power electronics require permeability stability under DC bias conditions. Automotive inverter manufacturers specify certified grades to preempt METI and EU Ecodesign compliance verification delays.
- Common Mode Chokes:Electromagnetic interference suppression in cable and PCB assemblies employs high-permeability ferrites for noise attenuation across conducted emission frequency bands.
- Magnetic Recording:Specialized ferrite formulations serve legacy data storage and emerging sensor applications with remanence and coercivity control.
Transformer applications retain the dominant volume position, while inductor demand is climbing fastest through electric vehicle powertrain electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over seventy percent of ferrite core manufacturing capacity sits in Zhejiang province and surrounding East Asian industrial clusters. Buyers face concentrated logistics exposure to this single-region supply base. Regulatory divergence across efficiency labeling schemes is forcing suppliers to maintain parallel certification portfolios.
China
Electric vehicle powertrain electrification and renewable energy inverter production drive premium Mn-Zn ferrite consumption in Shenzhen manufacturing clusters. MIIT energy efficiency standards and dual carbon goals are disqualifying legacy-grade materials from new transformer installations. DMEGC operates large-scale ferrite core facilities in Zhejiang province where capacity expansion is reshaping competitive dynamics.
Japan
Automotive onboard charger programs and industrial equipment efficiency mandates sustain demand for high-frequency ferrite formulations. METI Top Runner program forces documented permeability stability across temperature ranges with standardized test protocols. JFE Ferrite Co., Ltd. anchors domestic supply security through integrated oxide powder production in Chubu industrial corridors.
Germany
Industrial motor manufacturers and transformer OEMs source custom core geometries through direct mill contracts to secure allocation priority. EU Ecodesign Directive tiered compliance generates premium pricing windows for ferrite grades exceeding baseline core loss specifications. Production concentrates in Baden-Württemberg and Bavaria where automotive inverter supply chains intersect with precision engineering capabilities.
South Korea
5G base station filter expansion and smartphone power management circuit miniaturization drive Ni-Zn and chip-form ferrite procurement. Large transformer OEMs negotiate volume commitments with oxide powder producers for annual offtake exceeding 500 metric tons. Seoul-based RF component manufacturers are scaling procurement for telecommunications infrastructure deployment.
United States
NHTSA electromagnetic compatibility requirements and renewable energy inverter installations sustain import demand for certified ferrite grades. EPA and FERC efficiency frameworks intersect with state-level clean energy procurement mandates. Industrial motor rewind shops in Midwest manufacturing belts source standardized core geometries through distributor networks with volume-based pricing tiers.
Soft Ferrite Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The market exhibits tiered concentration with a handful of integrated oxide-to-core manufacturers controlling premium-grade supply while numerous regional fabricators compete on standardized geometries. Two strategic archetypes dominate: integrated material science platforms with captive powder production, and scale-driven specialists operating large-format sintering facilities. Competitive moves center on direct mill-to-winder supply contract consolidation and backward integration into high-purity oxide refining.
Among Japanese and Korean fabricators, TDK Corporation and Samsung Electro-Mechanics exemplify the integrated platform archetype, while DMEGC occupies a position representing Chinese scale-driven manufacturing. JFE Ferrite Co., Ltd. anchors the upstream material security tier through in-house oxide production. These three company structures illustrate how geographic origin and corporate form correlate with strategic positioning across the ferrite value chain.
| Leading Market Players |
|---|
| Ferroxcube |
| JFE Ferrite Co., Ltd. |
| TDK Corporation |
| Fair-Rite Products Corp. |
| Samwha Electronics |
| DMEGC |
| Hitachi Metals, Ltd. |
| Samsung Electro-Mechanics |
| Magnetics |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's ferrite core manufacturing clusters concentrate over seventy percent of global capacity, compressing buyer leverage and amplifying supplier pricing power across transformer and inductor procurement networks. This geographic chokepoint forces downstream OEMs into volume-commitment contracts to secure allocation priority.
Pricing Analysis
EU Ecodesign Directive dictates the pricing tier structure across soft ferrite procurement, separating certified high-efficiency grades from legacy compositions through documented core loss specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from amorphous metal substitution in high-frequency transformer designs above 100 kHz. Industrial motor rewind shops exhibit highest price sensitivity, while automotive inverter manufacturers accept premium positioning for compliance-certain supply.
Supply Chain Analysis
Export licensing controls on high-purity Fe2O3 and controlled MnO sources constrain raw material flows from supplier countries, elevating purification costs across the oxide powder tier. Manufacturing capacity concentrates in China, Japan, and South Korea, with sintered core production drawing from iron oxide, manganese oxide, and nickel oxide feedstocks. Single-region logistics exposure in East Asian clusters creates vulnerability to port congestion and customs processing delays. Distribution runs through direct mill-to-winder contracts for large transformer OEMs and distributor networks for standardized geometries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical certification services and formulation consulting are expanding faster than hardware sales, creating recurring-revenue layers that attach to core supply contracts. This service-attach dynamic reshapes how suppliers capture lifetime customer value.
For Market Incumbents: Harden supply security through backward integration into high-purity oxide refining to preempt raw material allocation disputes. Expand sintering capacity in Chubu industrial corridors to anchor Japanese domestic production against Zhejiang capacity surges. METI Top Runner compliance documentation requirements favor suppliers with in-house testing laboratories.
For New Entrants and Emerging Players: Pursue India industrial motor retrofit demand where Bureau of Energy Efficiency standards are disqualifying legacy transformer cores. Agricultural pump rewinding shops represent the most penetrable buyer segment given fragmented procurement and price-sensitive spot purchasing. Lead with certified Mn-Zn ferrite grades that preempt multi-certification timeline compression for export markets.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because specialized ceramic engineering talent scarcity concentrates in aging workforce pools across Japan and Germany. Acquisition targets with captive oxide production and documented grain boundary engineering capabilities command structural scarcity premiums. Watch for inflection when amorphous metal core loss advantages expand below 50 kHz, threatening ferrite's power transformer dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxide Refining | Captive Fe2O3 supply secures allocation priority ahead of export licensing constraints. |
| Multi-Certification Investment | Parallel GB, JIS, and REACH documentation compresses 18-24 month qualification cycles for premium grades. |
| Direct Mill-to-Winder Contracts | Volume commitments exceeding 500 metric tons displace layered distribution for industrial motor OEMs. |
| Computational Materials Science Capability | Process sensor networks and grain structure simulation accelerate formulation development cycles. |
| Additive Manufacturing Prototyping | 3D-printed ferrite-polymer composite cores digitize custom inductor validation for automotive power electronics. |
Study Parameters
The analysis maps Mn-Zn ferrite power grades, Ni-Zn RF formulations, chip-form surface-mount assemblies, and powder compound supply, each validated through ceramic engineering directors, transformer OEM procurement leads, automotive inverter platform engineers, and distributor network managers. Primary interview intelligence triangulates against customs trade data, MIIT energy efficiency filings, SEC 10-K disclosures from listed magnetic materials suppliers, and METI industrial equipment efficiency reports. Bottom-up capacity assessments and top-down end-use consumption models converge on volume estimates.
Assumptions held fixed include GB standard enforcement timelines, REACH compliance thresholds, and amorphous metal cost curves; variables tested include electric vehicle powertrain electrification rates and 5G base station deployment cadence. Segmentation dimensions span material chemistry, physical form, end-use industry, and application function across the projection horizon. CAGRs derive from regression against historical ferrite consumption intensity in power electronics and projected inverter content per vehicle. Forecast inputs incorporate oxide powder price trajectories and sintering capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in mining output from major Fe2O3 supplier countries or shipping cost volatility through East Asian ports would shift the trajectory. Material shifts in EU Ecodesign Directive tiered implementation schedules or breakthrough nanocrystalline ribbon cost reduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market