
 Passive Infrared Sensor Market | 2026-2036
Passive Infrared Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Infrared Sensor Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for European suppliers, forcing reformulation of pyroelectric materials and third-party certification spend. STMicroelectronics N.V. leverages its MEMS foundry scale to absorb these compliance costs internally. Nippon Ceramic Co. Ltd anchors its position through captive ceramic element production in Japan. Honeywell International Inc. competes by extending its building automation channel reach across North American commercial installations.
A passive infrared sensor detects thermal radiation emitted by objects within its field of view, typically employing pyroelectric crystals such as lithium tantalate that generate electrical charge when subjected to temperature fluctuations above 0.5°C. These devices serve primarily in motion detection, occupancy sensing, and energy management systems where contactless thermal monitoring eliminates mechanical wear. Smart sensors command the steepest margin pools due to embedded processing and IoT connectivity requirements, while standalone sensors dominate unit volume in price-sensitive residential channels. HVAC control applications represent the fastest-expanding demand segment as building codes tighten operational energy thresholds.
The EU Green Deal and F-Gas Regulation shape European product specifications by mandating lower standby power and refrigerant-linked climate controls. EPA Energy Star specifications and FCC Part 15 emissions rules govern US market access, with California Title 24 extending requirements to daylight harvesting integration. Stakeholders must monitor divergence between regional certification regimes when planning platform architectures.
Market Dynamics
Smart building automation mandates are compressing sensor replacement cycles while REACH compliance forces material reformulation across European supply chains, creating simultaneous pull and push pressures on procurement budgets.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Retrofit installations in commercial real estate now require occupancy-based HVAC controls, accelerating bulk sensor procurement across Germany's industrial corridor.
- Pyroelectric crystal miniaturization:Advances in lithium tantalate wafer processing enable multi-element arrays within standard package footprints, expanding deployment in space-constrained residential fixtures.
- F-Gas Regulation climate controls:Refrigerant-linked building management systems in the EU now integrate PIR-driven demand ventilation, creating specification pull-through for certified sensor modules.
Market Restraints
- Raw material concentration:High-purity lithium tantalate supply concentrates among Japanese specialty ceramic producers, exposing procurement to yen-denominated volatility and single-source risk.
- REACH certification friction:ECHA substance restrictions on pyroelectric dopants extend third-party testing timelines by 8-14 months, delaying new product introductions.
- Millimeter-wave radar substitution:Automotive and high-security installations increasingly specify radar-based presence detection for immunity to thermal drift and sunlight interference.
Strategic Opportunities
- India building code modernization:Bureau of Energy Efficiency mandates for commercial cooling load management create first-mover advantage for PIR-integrated thermostat suppliers in Mumbai and Bangalore.
- AI-enabled edge processing convergence:Embedding TinyML inference on sensor modules enables occupancy counting and behavioral pattern recognition without cloud dependency.
- California Title 24 daylight harvesting:Mandatory integration of occupancy sensing with automated dimming drives specification upgrades in new commercial construction across Los Angeles and San Francisco metro areas.
Industry Challenges
- MEMS process engineering talent scarcity:Foundry-scale production of thermal sensing arrays requires specialized wafer-level packaging expertise concentrated among legacy automotive sensor suppliers.
- Multi-certification timeline compression:Simultaneous FCC Part 15, CE marking, and BIS compliance for unified product platforms extends validation cycles and strains regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Infrared Sensor Market |
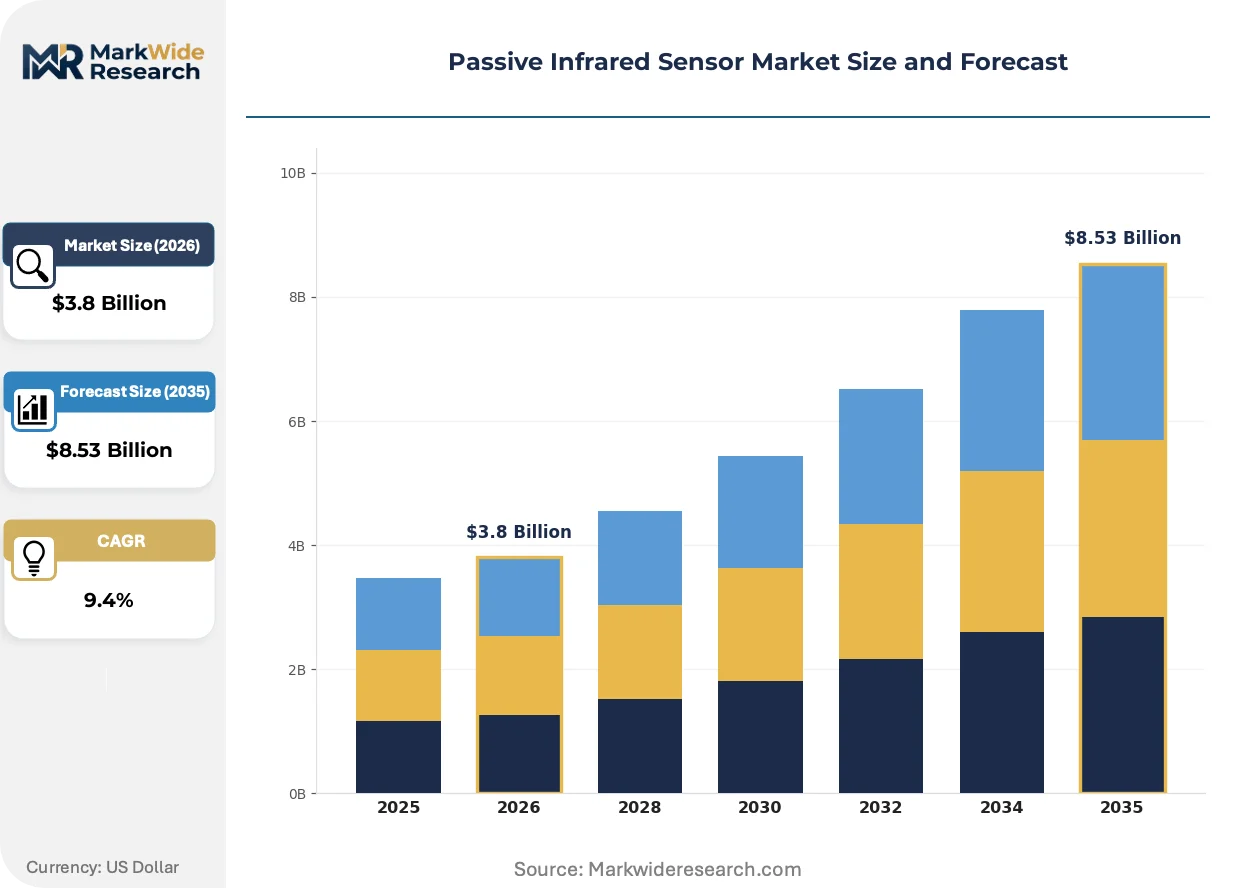
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Sensor, Integrated Sensor, Wireless Sensor, Smart Sensor Application: Security Systems, Lighting Control, Occupancy Detection, HVAC Control Technology: Passive Infrared, Dual-Tech, Multi-Tech, Active Infrared End User: Residential, Commercial, Industrial, Government |
| Companies Covered | STMicroelectronics N.V, Nippon Ceramic Co. Ltd, Honeywell International Inc, Axis Communications AB, SENBA Sensing Technology Co. Ltd, Excelitas Technologies Corp., Panasonic Corporation, InfraTec GmbH, Murata Manufacturing Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Infrared Sensor Market Strategic Shifts
Embedded intelligence and wireless connectivity are redefining sensor value propositions, shifting competitive differentiation from detection range to data integration capabilities and predictive maintenance enablement.
Multi-pixel thermal arrays is automating granular occupancy mapping within single sensor housings. Facility managers in Class A office developments are specifying these modules for space utilization analytics and hot-desking optimization. The technology is automating the displacement of binary motion detectors in premium building automation segments where zone-level intelligence commands hardware premiums.
EPA Energy Star Version 3.0 standby power specifications are tightening quiescent current budgets for wall-mounted and ceiling-embedded devices. Manufacturers must redesign analog front-ends and sleep-state logic to maintain detection sensitivity below 50 microwatts idle draw. North American residential channel suppliers face the steepest redesign burden as existing product lines approach end-of-certification.
Building automation procurement is consolidating around integrated platform vendors rather than standalone sensor specialists. Mechanical contractors in Texas and Florida now specify complete HVAC control stacks where PIR modules ship pre-calibrated to thermostat ecosystems. This bundling compresses component-level pricing power while expanding attach rates for firmware-enabled feature unlocks.
Passive Infrared Sensor Market Segmentation
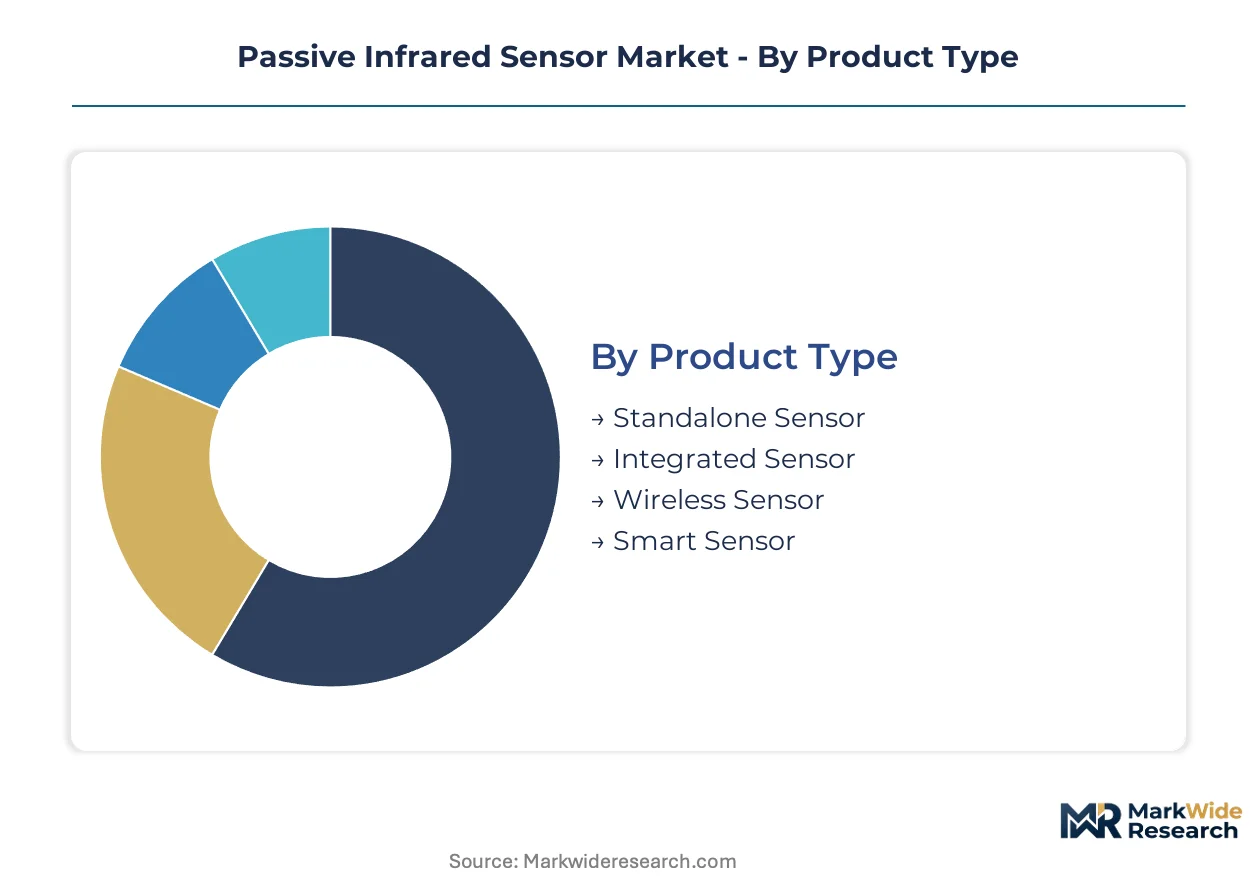
Segmentation in the Passive Infrared Sensor Market reveals divergent margin structures and procurement patterns across product architectures and deployment contexts. Smart building mandates and REACH compliance are reshaping specification requirements differently across each category, forcing suppliers to maintain parallel product roadmaps.
Product Type:
Technology sophistication defines cost structures and integration depth across the four product architectures.
- Smart Sensor:Embedded processing units combine pyroelectric detection with TinyML inference and IoT connectivity protocols. Demand concentrates in Class A commercial developments across Germany and California where space utilization analytics command hardware premiums. EPA Energy Star Version 3.0 standby power specifications are compressing quiescent current budgets below 50 microwatts.
- Integrated Sensor:Pre-calibrated modules ship within complete HVAC control stacks specified by mechanical contractors in Texas and Florida. Building automation procurement consolidation favors these bundled configurations over standalone alternatives. Firmware-enabled feature unlocks expand attach rates while compressing component-level pricing power.
- Standalone Sensor:Binary motion detectors dominate residential channel volume in price-sensitive segments. These units serve basic security and lighting automation without network connectivity.
- Wireless Sensor:Battery-operated devices eliminate wiring infrastructure for retrofit installations in EU commercial real estate. EU Green Deal energy efficiency mandates accelerate deployment in Germany's industrial corridor.
Integrated sensors lead on scale; smart sensors lead on momentum.
Application:
End-use requirements drive specification divergence across detection range, environmental immunity, and data output granularity.
- HVAC Control:Occupancy-based demand ventilation systems integrate PIR modules with refrigerant-linked climate controls under EU F-Gas Regulation. Bureau of Energy Efficiency mandates in India are creating first-mover opportunities for thermostat-integrated suppliers in Mumbai and Bangalore. California Title 24 mandates daylight harvesting integration in Los Angeles and San Francisco metro areas.
- Security Systems:High-security installations increasingly specify dual-tech configurations combining PIR with microwave detection for immunity to thermal drift. Automotive and perimeter applications face substitution pressure from millimeter-wave radar.
- Lighting Control:Automated dimming systems in commercial real estate require rapid response times and wide detection angles. Standalone sensors dominate this price-sensitive segment.
- Occupancy Detection:Multi-pixel thermal arrays enable granular zone-level mapping for hot-desking optimization in premium office developments. Binary detectors suffice for basic space management.
HVAC control commands the steepest specification upgrades; occupancy detection is expanding most quickly through analytics integration.
Technology:
Detection methodology determines environmental robustness and unit economics across deployment scenarios.
- Dual-Tech:Combined PIR and microwave detection eliminates false triggers from thermal drift and air currents. High-security government installations and automotive specifications favor this architecture despite cost premiums.
- Passive Infrared:Pyroelectric crystal detection remains the baseline technology for cost-sensitive residential and commercial applications. Lithium tantalate wafer processing advances enable multi-element arrays within standard footprints.
- Multi-Tech:Three-sensor fusion incorporating PIR, microwave, and acoustic detection serves mission-critical infrastructure. Limited deployment due to calibration complexity and power consumption.
- Active Infrared:Emitter-detector pairs function as beam interruption systems rather than thermal detectors. Distinct use case in perimeter security with minimal overlap in PIR procurement decisions.
Passive infrared leads on scale; dual-tech leads on specification premiums.
End User:
Procurement authority and compliance exposure vary sharply across customer types, dictating sales channel strategy.
- Commercial:Class A office developers and retail chains specify smart sensors with space analytics capabilities. Consolidated procurement through building automation platform vendors dominates this segment.
- Industrial:Factory modernization across Germany's industrial corridor drives bulk sensor procurement for energy management. Harsh environment requirements favor ruggedized housing and extended temperature ranges.
- Residential:Price-sensitive channel volume concentrates in standalone sensors for security and lighting automation. FCC Part 15 emissions compliance and EPA Energy Star certification govern market access.
- Government:Federal and municipal facilities specify dual-tech and multi-tech configurations for high-security applications. Extended certification timelines and specialized procurement processes limit supplier participation.
Commercial leads on revenue concentration; industrial leads on volume expansion through retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passive infrared sensor technology achieved commercial scale through Japanese pyroelectric ceramic innovation in the 1970s, with Nippon Ceramic and Murata establishing the foundational wafer processing techniques that enabled modern motion detection architectures.
United States
Commercial building automation drives sensor deployment across California and Texas metro areas. EPA Energy Star Version 3.0 standby power specifications and FCC Part 15 emissions rules govern market access for wall-mounted and ceiling-embedded devices. Los Angeles and San Francisco construction markets mandate Title 24 daylight harvesting integration, forcing specification upgrades in new commercial developments.
Germany
Factory modernization across the industrial corridor powers bulk procurement for energy management systems. EU Green Deal energy efficiency mandates and F-Gas Regulation climate controls compel retrofit installations with occupancy-based HVAC integration. The Rhine-Ruhr and Stuttgart manufacturing clusters specify multi-element arrays for space utilization analytics in Class A office developments.
Japan
Captive ceramic element production anchors global supply for high-purity lithium tantalate substrates. METI industrial standards and JIS certification requirements shape domestic product specifications. Tokyo and Osaka electronics clusters concentrate pyroelectric crystal miniaturization expertise for multi-element array manufacturing within standard package footprints.
India
Bureau of Energy Efficiency mandates for commercial cooling load management create first-mover opportunities in Mumbai and Bangalore. BIS compliance requirements and CDSCO medical device regulations govern sensor specifications for healthcare applications. The Delhi-NCR and Hyderabad industrial corridors drive procurement for smart building automation in premium commercial real estate.
China
Domestic sensor fabrication scales through MIIT industrial policy support and GB standards certification. Dual carbon goals accelerate building efficiency retrofits in Beijing and Shanghai commercial districts. The Yangtze River Delta and Pearl River Delta manufacturing bases concentrate MEMS foundry capacity for thermal sensing array production.
Passive Infrared Sensor Market Competitive Environment
The competitive structure tilts toward diversified electronics conglomerates with captive material processing capabilities. Foundry-scale MEMS production and pyroelectric ceramic supply chain control separate sustainable participants from module assemblers. Two strategic archetypes dominate: integrated semiconductor manufacturers with internal wafer processing, and specialized sensor houses with backward integration into ceramic element production. Capacity expansion and strategic partnerships represent the dominant competitive moves as certification timelines extend.
Within the integrated semiconductor tier, STMicroelectronics N.V. exemplifies foundry-scale absorption of compliance costs, while Nippon Ceramic Co. Ltd anchors the specialist archetype through captive ceramic production. Honeywell International Inc. occupies a position bridging industrial automation channel reach with building automation platform integration. These three represent divergent responses to REACH material reformulation pressures and smart sensor margin pool capture.
| Leading Market Players |
|---|
| STMicroelectronics N.V |
| Nippon Ceramic Co. Ltd |
| Honeywell International Inc |
| Axis Communications AB |
| SENBA Sensing Technology Co. Ltd |
| Excelitas Technologies Corp. |
| Panasonic Corporation |
| InfraTec GmbH |
| Murata Manufacturing Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Pyroelectric crystal miniaturization advances in lithium tantalate wafer processing are compressing unit economics while simultaneously concentrating supply among Japanese specialty ceramic producers with captive foundry capacity. This dual effect squeezes margin pools for module assemblers lacking backward integration into ceramic element production.
Pricing Analysis
Bundled HVAC control stacks versus unbundled standalone sensors now define the pricing architecture. Three-tier pricing structure across premium smart sensors, standard integrated modules, and economy standalone units reflects certification grade and firmware-enabled feature depth. Cost compression in residential channels is intensifying because EPA Energy Star Version 3.0 redesign requirements force analog front-end investments. Price sensitivity peaks among residential security installers; commercial building automation platforms exhibit lowest sensitivity due to lifecycle cost framing.
Supply Chain Analysis
Freight cost volatility from yen-denominated lithium tantalate shipments between Japan and German industrial corridors is amplifying landed cost uncertainty for European module assemblers. High-purity pyroelectric substrate supply draws from Japan, China, and South Korea, with wafer processing concentrated in Tokyo and Osaka electronics clusters. Single-source vulnerability persists for specialty ceramic dopants subject to ECHA REACH restrictions. Distribution runs through building automation platform vendors consolidating procurement authority across North American and European commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU Green Deal energy efficiency mandates and California Title 24 daylight harvesting requirements are shifting specification authority toward premium smart sensors with embedded analytics.
For Market Incumbents: Deepen captive ceramic element production to absorb REACH compliance costs internally and defend against millimeter-wave radar substitution in automotive and high-security verticals. Expand MEMS foundry capacity in Germany's industrial corridor to capture bulk procurement from factory modernization programs. Prioritize firmware-enabled feature unlocks to maintain attach rates as platform bundling compresses component-level pricing power. For New Entrants and Emerging Players: Direct-to-contractor digital channels targeting mechanical contractors in Texas and Florida offer lowest-friction entry points. India's Bureau of Energy Efficiency mandates for commercial cooling load management represent the most penetrable geography, with Mumbai and Bangalore offering first-mover positioning. Lead with pre-calibrated thermostat integration to bypass incumbent channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone sensor specialists lacking ceramic supply chain integration. Long-term viability favors foundry-scale MEMS producers with internal wafer processing capabilities over module assemblers exposed to raw material concentration. Watch for ECHA substance restriction announcements as inflection indicators for compliance cost absorption advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Element Production | Captive lithium tantalate supply insulates margins from yen volatility and REACH certification friction. |
| MEMS Foundry Capacity Expansion | Scale economies enable absorption of EPA Energy Star redesign costs for sub-50 microwatt idle draw specifications. |
| Firmware-Enabled Feature Unlock Platform | Recurring revenue streams offset hardware margin compression from building automation procurement consolidation. |
| Multi-Element Array Product Launch | Granular occupancy mapping commands hardware premiums in Class A office developments across Germany and California. |
| Strategic Partnership with HVAC Control Stack Vendors | Pre-calibrated module integration secures specification pull-through in Texas and Florida mechanical contractor channels. |
Study Parameters
Direct dialogue with MEMS foundry operations managers, building automation procurement leads at Class A commercial developers, mechanical contractors specifying HVAC control stacks, and regulatory affairs specialists navigating ECHA REACH certification grounded the qualitative framework. Secondary validation drew from EPA Energy Star certification databases, FCC Part 15 equipment authorization filings, EU F-Gas Regulation implementation reports, and Bureau of Energy Efficiency mandate documentation. Bottom-up sensor shipment estimates triangulated against top-down building automation spend allocation across the analysis window.
Segment-level value outputs reflect modeling across product architecture, application vertical, detection technology, and end-user procurement authority. CAGRs derived from regression against historical retrofit installation rates, regulatory mandate phase-in schedules, and platform vendor consolidation patterns. Forecast inputs incorporated lithium tantalate wafer processing yield improvements and multi-certification timeline compression effects.
The model assumes a particular technology adoption path; alternative pathways for millimeter-wave radar presence detection would alter the outlook for pyroelectric sensor demand in automotive and high-security installations. Forecasts reflect assumptions about REACH substance restriction scope, EPA standby power specification enforcement timing, and MEMS process engineering talent availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Fuse Market