
 Ceramic Insulator Market | 2026-2036
Ceramic Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Insulator Market Analysis
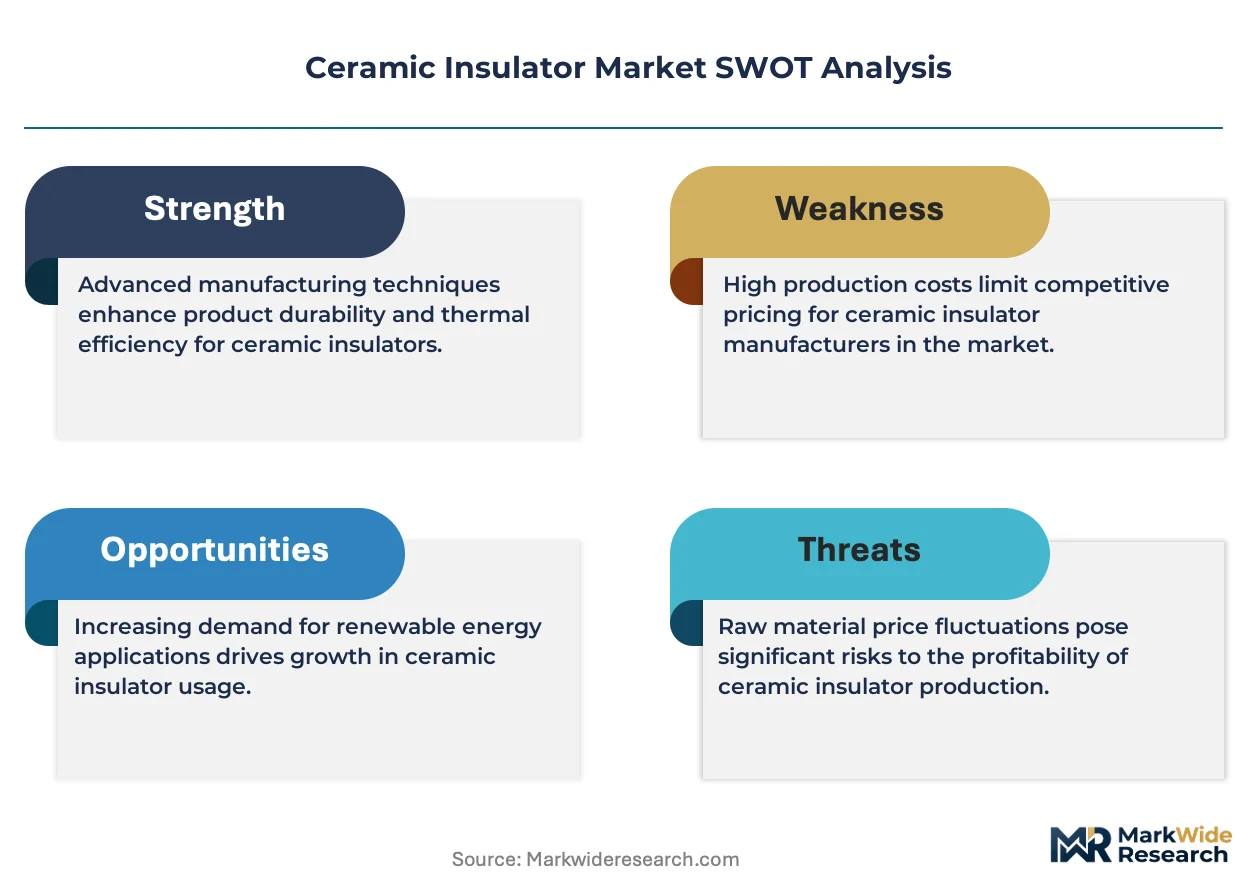
High-voltage direct current integration is tilting the technology stack toward ultra-high-strength alumina insulators capable of withstanding elevated electrical and mechanical loads. NGK Insulators Ltd leverages decades of ceramic formulation expertise to anchor premium suspension insulator supply for Asian utilities. Siemens Energy Ltd competes through integrated grid solutions that bundle insulators with converter station packages. Hubbell Power Systems Inc dominates North American distribution networks with specialized line post designs.
Ceramic insulators are non-conductive components manufactured from alumina, porcelain, or steatite through sintering or pressing processes, engineered to mechanically support and electrically isolate conductors in transmission and distribution systems rated from 11 kV to 1,100 kV. Suspension insulators command the largest volume share due to universal deployment on high-voltage transmission towers, while renewable energy applications represent the fastest-growing segment as offshore wind and solar farms require specialized pollution-resistant designs. Pin insulators retain cost advantages in rural distribution networks across developing economies.
FERC Order 2023 and the EU Green Deal's grid expansion targets are tightening mechanical load and pollution performance requirements, directly influencing insulator design standards and procurement specifications. China's GB standards and India's CEA technical regulations mandate localized testing protocols that shape market access for foreign suppliers. Stakeholders must monitor evolving material substitution risks from composite polymer alternatives while positioning ceramic portfolios around extreme-temperature and contamination-resistant performance tiers.
Market Dynamics
Grid decarbonization mandates are forcing utilities to replace legacy porcelain with alumina-rich formulations capable of handling higher mechanical loads from renewable interconnection. This material transition is compressing supplier margins while elevating technical barriers to market entry.
Growth Catalysts
- FERC Order 2023:Grid reliability mandates in the United States are accelerating procurement cycles for high-voltage suspension insulators rated above 230 kV.
- Offshore wind expansion:North Sea and East Asian offshore wind clusters are generating specialized demand for pollution-resistant ceramic designs with enhanced hydrophobic glazing.
- India's CEA technical regulations:Mandatory localized testing protocols are creating captive demand for domestic manufacturing capacity expansion.
Market Restraints
- Alumina price volatility:Raw material concentration in Australian and Guinean bauxite supply chains exposes manufacturers to input cost swings exceeding 20 percent annually.
- Composite polymer substitution:Silicone rubber insulators are capturing distribution voltage segments below 72.5 kV due to weight advantages and vandalism resistance.
- REACH compliance burdens:European chemical registration requirements for glaze additives are extending product certification timelines by 8-14 months.
Strategic Opportunities
- Saudi Arabia's grid expansion:NEOM and Red Sea tourism projects are creating greenfield demand for ultra-high-voltage insulator strings in desert contamination environments.
- Digital twin integration:Convergence of ceramic sensor embedding with IoT monitoring systems enables predictive maintenance contracts for transmission operators.
- Brazil's ANEEL auctions:Renewable energy transmission concessions are mandating 30-year service life guarantees that favor premium alumina formulations.
Industry Challenges
- Specialized kiln engineering talent:Sintering process expertise for high-purity alumina is concentrated among retiring cohorts in Japanese and German manufacturing clusters.
- IEC 60383 certification delays:Multi-stage type testing for mechanical and electrical performance is creating 18-24 month product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Insulator Market |
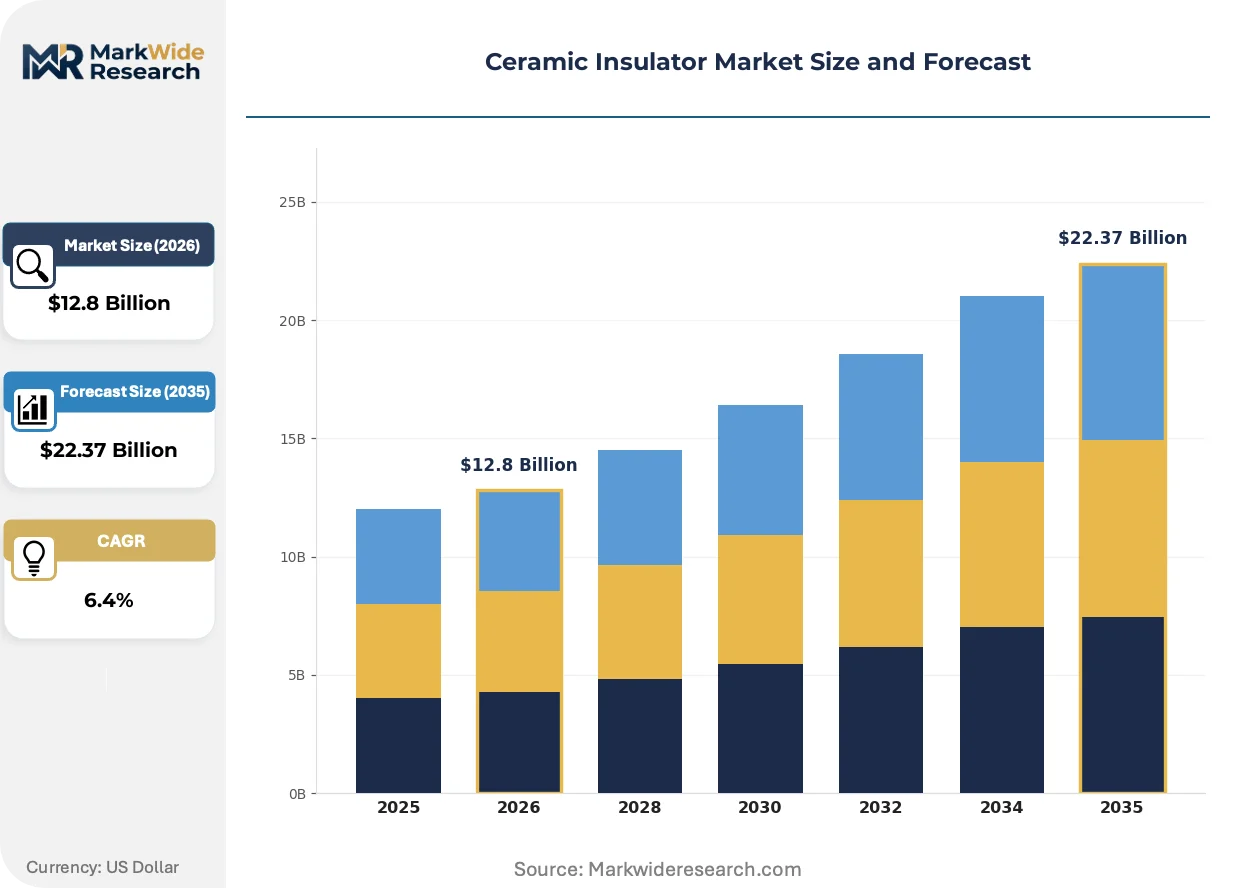
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin Insulators, Suspension Insulators, Line Post Insulators, Shackle Insulators Technology: Sintering, Pressing, Extrusion, Casting End User: Utilities, Railways, Industrial, Telecommunications Application: Transmission Lines, Distribution Lines, Substations, Renewable Energy |
| Companies Covered | Siemens Energy AG, Lapp Insulators GmbH, NGK Insulators Ltd, Toshiba Corporation, Hitachi Energy Ltd, Hubbell Power Systems Inc, General Electric Company, Aditya Birla Insulators, MacLean Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Insulator Market Emerging Trajectories
Material science breakthroughs and digitalization are compressing traditional product lifecycles while opening premium pricing tiers for performance-differentiated ceramic formulations.
Isostatic pressing of high-purity alumina is rendering obsolete conventional dry-press porcelain in suspension insulator applications above 400 kV. State-grid operators in China and India are specifying isostatically pressed cores for new ultra-high-voltage corridors. This manufacturing shift is rendering obsolete older kiln infrastructure and consolidating supply among capital-intensive producers.
EU Green Deal grid expansion targets are tightening pollution performance classifications under CENELEC standards. Insulator designs must now demonstrate equivalent salt deposit density endurance above 60 mg per square centimeter for North Sea offshore eligibility. German and Danish transmission system operators are rewriting procurement specifications to mandate ceramic formulations with proprietary hydrophobic surface treatments.
Consolidated utility procurement is compressing supplier bases to single-source frameworks with 10-year master service agreements. Tier-1 transmission operators in the United States and United Kingdom are unbundling hardware supply from installation services, forcing manufacturers to compete on total cost of ownership metrics rather than unit pricing. This behavioral shift is most visible in offshore wind collector systems where lifecycle replacement costs dominate capital expenditure decisions.
Ceramic Insulator Market Segmentation
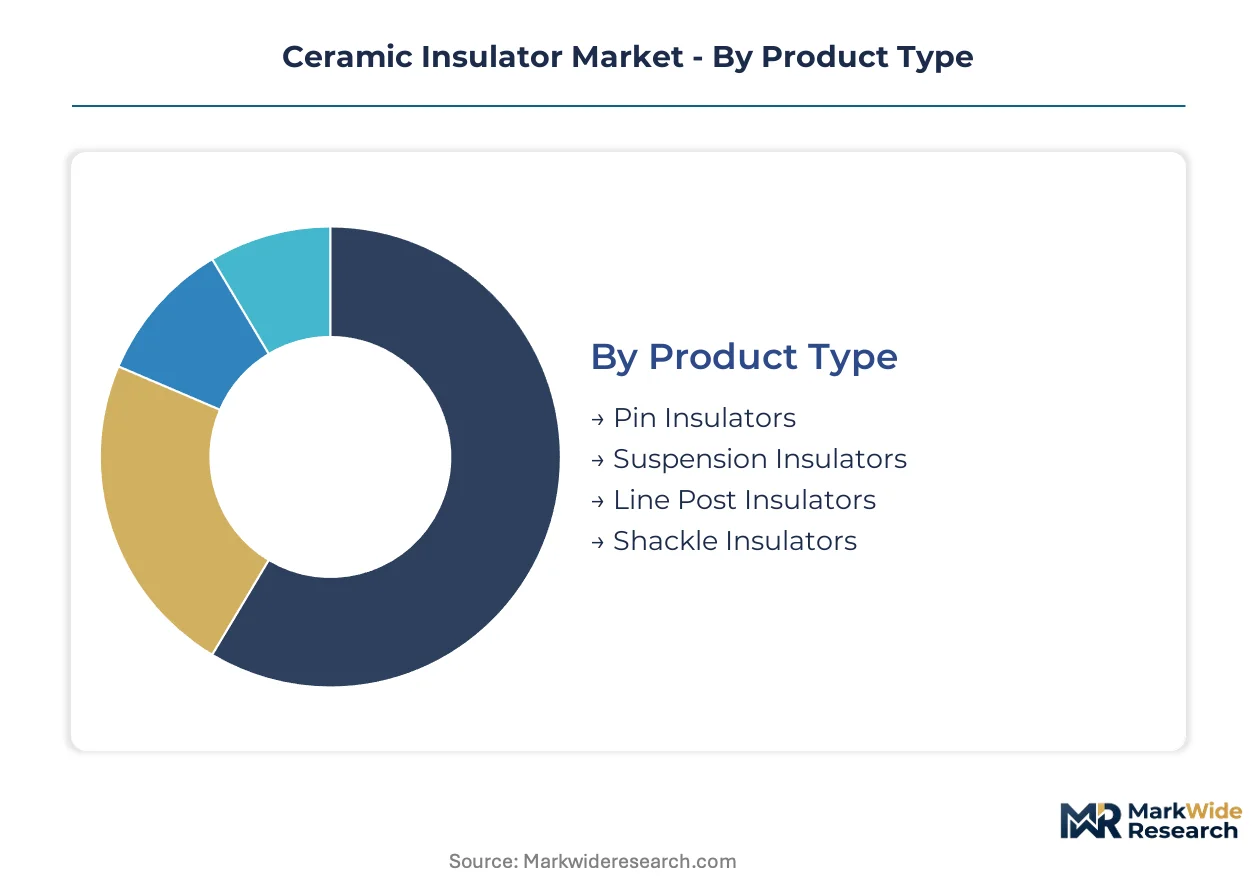
Ceramic insulator procurement varies sharply across voltage classes and contamination environments, forcing manufacturers to maintain parallel production lines for radically different specification bands. Understanding segment-level technical requirements reveals where formulation expertise commands premium pricing versus where commoditization pressures dominate.
Product Type:
Utilities deploy distinct mechanical support architectures depending on conductor tension, tower geometry, and pollution severity across their networks.
- Suspension Insulators:These multi-unit strings of disc-shaped porcelain or alumina components handle mechanical loads exceeding 50 kN while maintaining electrical isolation across 230 kV to 1,100 kV corridors. China's State Grid and India's Power Grid Corporation are procuring isostatically pressed variants for new ultra-high-voltage direct current links connecting remote renewable zones to coastal demand centers.
- Pin Insulators:Single-piece designs mounted directly on cross-arms dominate rural distribution below 33 kV where cost sensitivity outweighs performance optimization. Indian utilities under CEA procurement guidelines specify pin insulators for village electrification schemes where vandalism resistance and simple installation matter more than longevity.
- Line Post Insulators:Vertical cantilever designs integrate mounting hardware directly into the ceramic body, reducing installation complexity for distribution automation projects. Hubbell Power Systems has specialized in polymer-core line post hybrids for North American utilities seeking reduced weight without abandoning ceramic surface properties.
- Shackle Insulators:Compact dumbbell-shaped units serve low-voltage distribution dead-ends and short spans where space constraints prevent larger assemblies. These retain niche demand in legacy European distribution networks and developing economy refurbishment programs.
Established volume favors suspension designs for transmission infrastructure; emerging adoption favors line post configurations as distribution automation accelerates.
Technology:
Manufacturing process selection determines achievable purity, mechanical strength, and dimensional precision for each voltage class.
- Sintering:High-temperature firing of alumina powder at 1,600°C produces dense crystalline structures with dielectric strength exceeding 15 kV per millimeter. Japanese and German manufacturers control the specialized tunnel kiln engineering required for consistent high-purity output, creating supply bottlenecks as experienced operators retire.
- Pressing:Dry-press and wet-press methods shape porcelain formulations for standard distribution insulators where cost minimization trumps performance margins. Chinese producers dominate pressed porcelain output through integrated clay beneficiation and scale-driven automation.
- Extrusion:Continuous forming of hollow cores enables complex internal profiles for post insulators and bushings requiring precise electric field grading. This process serves specialized substation applications rather than volume transmission hardware.
- Casting:Slip casting of complex geometries supports prototype development and small-batch production of custom terminal bushings for industrial equipment. Casting remains marginal for grid-scale procurement due to cycle time limitations.
Process economics concentrate sintering leadership among capital-intensive specialists; pressing scale advantages cluster with integrated raw material processors.
End User:
Customer procurement patterns diverge between regulated utilities with decade-long master agreements and industrial buyers with project-driven spot purchasing.
- Utilities:Transmission system operators specify IEC 60383-certified products with 30-year service life guarantees, unbundling hardware supply from installation services. FERC Order 2023 reliability mandates are accelerating replacement cycles for aging suspension strings in the United States.
- Railways:Electrified rail networks require specialized tension insulators for catenary systems exposed to vibration, pollution, and mechanical shock from passing trains. European and Chinese high-speed corridors are standardizing on composite-ceramic hybrids for reduced maintenance access.
- Industrial:Heavy manufacturing facilities purchase terminal bushings and station post insulators for switchgear integration, prioritizing short lead times over lifecycle optimization. Oil and gas, steel, and cement sectors drive demand for high-temperature-resistant formulations.
- Telecommunications:Antenna support structures and fiber optic cable termination points use compact shackle and stay insulators with minimal mechanical loading requirements. This segment faces substitution pressure from all-polymer alternatives.
Utility procurement consolidation favors suppliers with certification depth; industrial spot buying rewards flexible manufacturing footprints.
Application:
Operating environment severity dictates glaze chemistry, shed profile geometry, and pollution resistance specifications.
- Transmission Lines:Long-distance overhead corridors expose insulators to salt spray, desert dust, and industrial contamination across decades of service. Offshore wind collector systems in the North Sea and East Asian waters are demanding hydrophobic glazed formulations with equivalent salt deposit density endurance above 60 mg per square centimeter.
- Renewable Energy:Solar farms and wind installations require insulators optimized for rapid thermal cycling and UV exposure in remote locations. This application is climbing the fastest as decarbonization targets force renewable interconnection buildouts across China, India, and Brazil.
- Distribution Lines:Dense urban networks and rural radial systems prioritize vandalism resistance and simple installation over extreme performance margins. Composite polymers are capturing share below 72.5 kV where weight reduction enables lighter support structures.
- Substations:Station post and bushing insulators must manage complex electric field distributions in compact switchgear layouts. Gas-insulated substation proliferation is shifting demand toward precision-machined alumina components with tight dimensional tolerances.
Transmission replacement cycles anchor near-term revenue; renewable interconnection projects drive steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply suspension insulators to India's transmission expansion and Saudi Arabia's desert grid projects. Germany exports precision-sintered components to North Sea offshore wind clusters. Trade corridors reflect regional specialization in voltage classes and contamination-resistant formulations.
China
State Grid Corporation procures isostatically pressed alumina cores for 800 kV ultra-high-voltage direct current corridors linking western renewables to coastal demand centers. GB standards mandate localized testing protocols that shape procurement specifications. Manufacturing concentrates in Jiangsu and Zhejiang provinces where tunnel kiln infrastructure supports high-purity sintering output.
India
Power Grid Corporation accelerates procurement of suspension strings for renewable energy evacuation infrastructure under national green hydrogen mandates. CEA technical regulations require domestic testing certification that favors local manufacturing expansion. Production clusters in Gujarat and Maharashtra supply village electrification schemes with cost-optimized pin insulators.
United States
FERC Order 2023 reliability mandates accelerate replacement cycles for aging porcelain suspension strings above 230 kV. Utilities unbundle hardware supply from installation services under consolidated master agreements. Manufacturing and procurement activity concentrates in Texas and the Midwest where transmission buildouts accommodate wind interconnection from the Great Plains.
Germany
Tennet and 50Hertz rewrite procurement specifications for North Sea offshore wind collector systems requiring hydrophobic glazed formulations. EU Green Deal grid expansion targets tighten pollution performance classifications under CENELEC standards. Industrial activity clusters in Bavaria and North Rhine-Westphalia where precision ceramics expertise supports substation bushing production.
Saudi Arabia
NEOM and Red Sea tourism projects generate greenfield demand for ultra-high-voltage insulator strings in extreme desert contamination environments. The kingdom's grid expansion program prioritizes 30-year service life guarantees that favor premium alumina formulations. Procurement activity concentrates in the Eastern Province where new transmission corridors connect renewable zones to industrial demand centers.
Ceramic Insulator Market Vendor Landscape
On the supply side, the industry is consolidating around capital-intensive specialists with captive sintering expertise and integrated raw material processing. Japanese and German manufacturers control high-purity alumina tunnel kiln engineering while Chinese producers dominate pressed porcelain scale. Three archetypes define competitive positioning: formulation specialists commanding premium suspension insulator tiers, integrated grid solution providers bundling hardware with converter stations, and regional fabricators serving cost-sensitive distribution segments. Dominant competitive moves include backward integration into alumina beneficiation and strategic partnerships for offshore wind certification.
Within the formulation specialist tier, NGK Insulators Ltd and Lapp Insulators GmbH exemplify premium-tier positioning through decades of ceramic expertise. Siemens Energy AG occupies a position among integrated solution providers bundling insulators with power conversion infrastructure. Hubbell Power Systems Inc anchors North American distribution network supply with specialized line post designs.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Lapp Insulators GmbH |
| NGK Insulators Ltd |
| Toshiba Corporation |
| Hitachi Energy Ltd |
| Hubbell Power Systems Inc |
| General Electric Company |
| Aditya Birla Insulators |
| MacLean Power Systems |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese pressed porcelain kilns is compressing margins across standard distribution tiers while forcing premium sintering specialists in Japan and Germany to defend pricing power through certification depth and performance guarantees. This utilization asymmetry rewards capital-intensive producers with captive alumina processing and punishes commodity fabricators exposed to spot bauxite volatility.
Pricing Analysis
Isostatically pressed alumina cores command substantial premiums over conventional dry-press porcelain and wet-press alternatives, with next-generation hydrophobic glazed formulations opening additional price stratification. Three-tier pricing structure across premium IEC 60383-certified, standard utility-grade, and economy pin insulator levels reflects divergent buyer sophistication and lifecycle cost accounting. Pricing pressure stems from composite polymer substitution below 72.5 kV where silicone rubber weight advantages enable lighter support structures. Distribution utilities exhibit highest price sensitivity due to unbundled procurement frameworks, while offshore wind developers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus as CEA technical regulations mandate localized testing certification. Manufacturing concentrates in Jiangsu and Zhejiang provinces for pressed porcelain, Bavaria and North Rhine-Westphalia for precision-sintered components, and Gujarat and Maharashtra for India-compliant production. Bauxite feedstock draws from Australian and Guinean mining operations, high-purity alumina refining clusters in China and Germany, and specialized glaze additive suppliers subject to REACH compliance delays. Single-source vulnerability sits with Japanese tunnel kiln engineering expertise as experienced operators retire. Distribution runs through utility master service agreements, EPC contractor specifications, and industrial spot purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment: IEC 60383 certification timelines and CEA mandatory testing protocols create structural barriers that compound with each procurement cycle renewal.
For Market Incumbents: Entrench position through backward integration into alumina beneficiation and captive sintering capacity expansion in India and Saudi Arabia to satisfy localized content requirements. Composite polymer substitution below 72.5 kV threatens legacy porcelain volumes; defend through embedded sensor development for predictive maintenance contracts that polymers cannot replicate. Certification investment in North Sea offshore wind specifications represents the critical lever for premium tier retention. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANEEL auction pipeline where 30-year service life guarantees favor new premium alumina formulations without incumbent relationship lock-in. India's CEA-mandated domestic testing creates white-space for local manufacturing joint ventures with technology licensing from German or Japanese specialists. Target industrial spot purchasing for substation bushings and switchgear integration where lead time flexibility outweighs brand preference. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulation specialists with decade-long utility master service agreements and embedded base maintenance contracts. Long-term viability centers on sintering process expertise concentration that cannot be rapidly replicated. Acquisition target archetype: mid-cap specialists with captive tunnel kiln infrastructure and IEC 60383 certification depth. The signal to watch is offshore wind procurement specification tightening that disqualifies commodity suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Beneficiation | Captive raw material supply insulates margin compression from Australian and Guinean bauxite price swings. |
| Offshore Wind Certification Investment | Hydrophobic glazing expertise under CENELEC standards unlocks North Sea and East Asian collector system procurement. |
| Digital Twin Sensor Embedding | IoT-enabled predictive maintenance contracts differentiate ceramic portfolios from composite polymer alternatives. |
| India Manufacturing Joint Venture | CEA technical regulations mandate localized testing that favors domestic production capacity expansion. |
| Specialized Kiln Engineering Talent Retention | Sintering process expertise concentration among retiring Japanese and German cohorts creates acquisition scarcity value. |
Methodological Framework
A standing panel of transmission system operator procurement directors, EPC contractor specification engineers, utility planning officers, and ceramic manufacturing plant managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FERC Order 2023 filings, CEA technical regulation updates, IEC 60383 certification databases, EU Green Deal grid expansion targets, and customs trade data for alumina and insulator shipments. Bottom-up segment modeling triangulated against top-down utility capital expenditure tracking.
Scenario bracketing around grid decarbonization pace, composite polymer substitution velocity, and alumina price volatility shaped probabilistic output ranges across the projection horizon. Segmentation dimensions included voltage class, manufacturing process technology, end-user procurement archetype, and contamination environment severity. CAGRs derived from utility master agreement renewal patterns and renewable interconnection project pipelines. Forecast inputs incorporated State Grid UHV corridor buildout schedules and ANEEL auction transmission concession awards.
Sensitivities concentrate around FERC reliability mandate enforcement intensity, REACH compliance timeline extensions for glaze additives, and Chinese GB standard revisions affecting import acceptance criteria. Forecasts reflect documented assumptions regarding kiln capacity utilization and certification backlog durations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Elastomeric Connectors Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Chip Resistor Market