
 Integrated Passive Devices (Ipds) Market | 2026-2036
Integrated Passive Devices (Ipds) Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Passive Devices (Ipds) Market Foresight
Software-defined tuning and calibration services for RF front-end modules is restructuring how integrated passive device vendors capture recurring value beyond component sales. Murata Manufacturing Co., Ltd. leverages its ceramic material science leadership to dominate high-frequency filter applications for 5G infrastructure. STMicroelectronics anchors European supply security through captive 8-inch silicon IPD fabrication in France and Italy. Infineon Technologies AG specializes in automotive-grade integrated passives that meet AEC-Q200 reliability standards for electric powertrain systems.
Integrated Passive Devices combine resistors, capacitors, inductors, and filters into single-substrate assemblies using thin-film sputtering or thick-film screen-printing on silicon, glass, or ceramic carriers, achieving footprint reductions exceeding 70% versus discrete components while operating at frequencies up to 6 GHz for RF and millimeter-wave applications. Capacitors and filters generate the dominant revenue share due to their irreplaceable role in impedance matching and signal conditioning for wireless communications. Thin-film technology leads in precision applications where tight tolerance and thermal stability command premium positioning, while MEMS-based IPDs represent the fastest-growing fabrication category as manufacturers exploit semiconductor batch processing for acoustic resonators and tunable components.
FCC Part 15 emissions rules in the United States and EU Radio Equipment Directive compliance frameworks shape product certification requirements for IPDs deployed in telecommunications and automotive radar systems, directly influencing design cycles and testing expenditures. ECHA REACH substance restrictions and RoHS hazardous material bans constrain electrode metallurgy choices, particularly for nickel and lead-bearing termination finishes used in high-volume consumer electronics. China's GB standards and MIIT radio transmission regulations mandate domestic testing protocols that foreign suppliers must navigate for market access. Stakeholders must monitor evolving spectrum allocation decisions and material compliance deadlines to align R&D roadmaps with regulatory enforcement timelines.
Market Dynamics
Automotive electrification is compressing design cycles for power-dense passive networks, forcing IPD suppliers to pre-validate AEC-Q200 performance tiers before vehicle platform lock-in. This pressure cascades through material selection, thermal modeling, and foundry capacity allocation across the value chain.
Growth Catalysts
- EU RoHS material bans:Lead-free electrode metallurgy mandates are accelerating thin-film IPD adoption in consumer electronics, as manufacturers abandon tin-lead termination finishes.
- 5G millimeter-wave infrastructure:Base station OEMs in China are absorbing high-frequency filter IPDs at scale, driven by MIIT spectrum allocation deadlines for sub-6 GHz and mmWave bands.
- Silicon carbide power modules:Electric vehicle traction inverters require integrated snubber capacitors and gate resistors that IPD formats uniquely accommodate within tight thermal envelopes.
Market Restraints
- Palladium price volatility:Electrode paste formulations depend on palladium-silver alloys, exposing margins to London Metal Exchange price swings that resist hedging at IPD scale.
- 8-inch silicon wafer tightness:Captive fabrication at STMicroelectronics and others concentrates supply risk in French and Italian foundry corridors, limiting second-source options.
- Discrete component substitution:Low-frequency applications below 1 GHz tolerate larger discrete RLC networks that undercut IPD cost structures in price-sensitive consumer tiers.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic assembly incentives under the Modified Programme for Semiconductors are attracting IPD packaging investments for telecom and automotive export hubs.
- MEMS-acoustic convergence:RF front-end modules are integrating IPD-based impedance matching with MEMS resonators, opening design wins in true wireless stereo earbuds and wearables.
- Glass substrate revival:Corning and Schott glass carriers enable ultra-low-loss IPDs for 6G research programs, bypassing silicon's conductivity limitations at terahertz frequencies.
Industry Challenges
- Electromagnetic simulation talent scarcity:Full-wave modeling for 3D-integrated passives requires rare expertise in HFSS and CST tools that RF foundries struggle to staff.
- Multi-physics qualification timelines:Simultaneous thermal cycling, vibration, and humidity testing for automotive IPDs extends AEC-Q200 certification to 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Passive Devices (Ipds) Market |
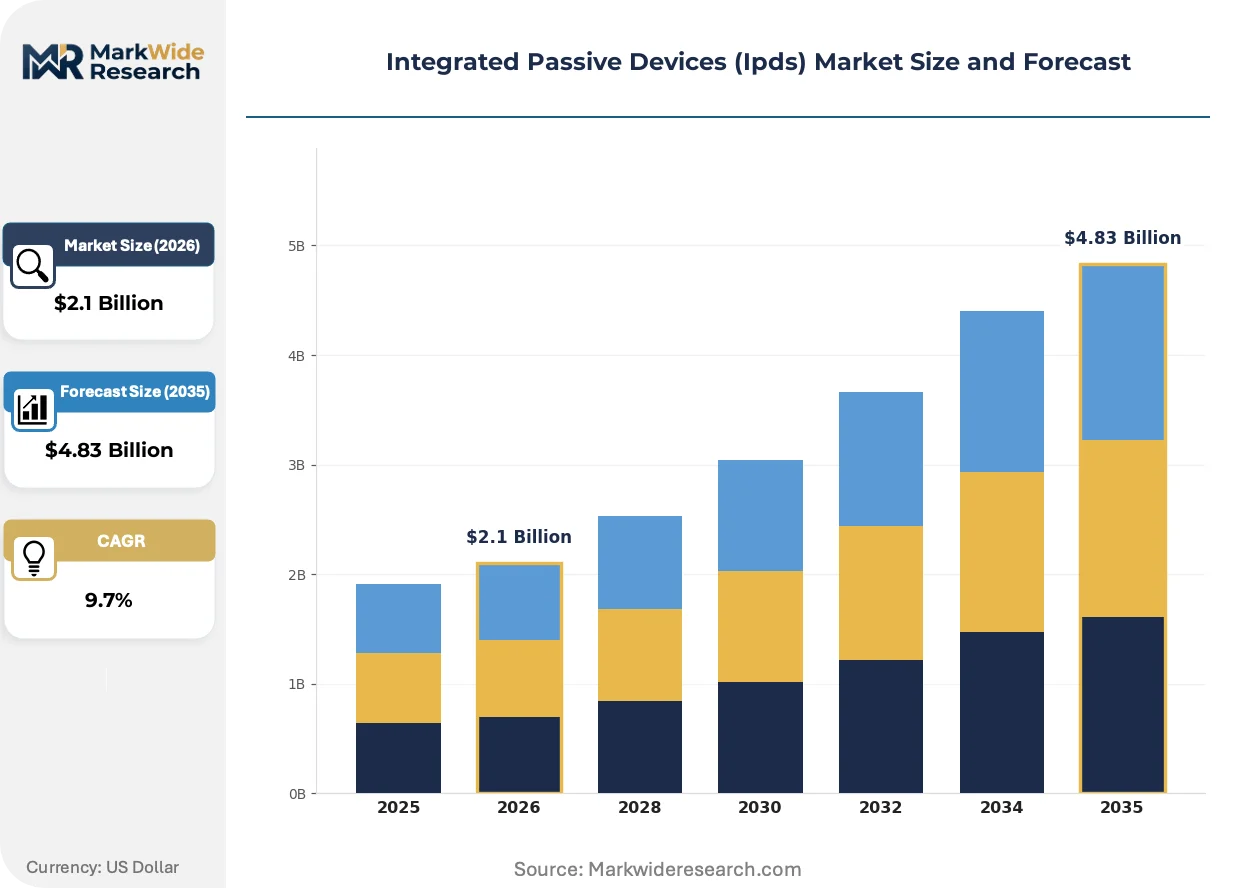
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitors, Resistors, Inductors, Filters Technology: Thin Film, Thick Film, Ceramic, MEMS End User: Telecommunications, Consumer Electronics, Automotive, Aerospace Form Factor: Surface Mount, Chip, Module, Array |
| Companies Covered | Murata Manufacturing Co., Ltd., STMicroelectronics, Broadcom Inc., Infineon Technologies AG, Samsung Electro-Mechanics Co., Ltd., Taiyo Yuden Co., Ltd., Vishay Intertechnology, Inc., NXP Semiconductors, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Passive Devices (Ipds) Market Shifts & Advancements
RF system architects are abandoning discrete component stacking in favor of substrate-level integration, compressing bill-of-materials complexity while elevating electromagnetic co-design requirements. This shift redefines supplier relationships and technical validation protocols.
Thin-film barium strontium titanate (BST) varactors are enabling voltage-tunable matching networks for 5G beamforming modules. Smartphone OEMs in South Korea and Japan are qualifying these devices for sub-6 GHz antenna tuners. The technology is decentralizing RF front-end design authority from discrete component vendors to substrate-integrated solution providers.
ECHA REACH substance restrictions are tightening nickel exposure limits in electrode finishes, forcing reformulation of barrier metallization stacks. Industrial consequence spans rework of qualification databases and supply chain re-approval cycles. High-volume consumer electronics manufacturers in Germany and the Netherlands face the steepest compliance cost escalation.
Automotive Tier-1 suppliers are consolidating passive procurement through direct substrate sourcing, bypassing traditional distributor channels for IPD wafers and known-good-die. This disintermediation concentrates negotiation leverage with captive foundries. The pattern is most pronounced in Bavarian and Baden-Württemberg automotive electronics clusters serving Mercedes-Benz and BMW electric platforms.
Integrated Passive Devices (Ipds) Market Segmentation
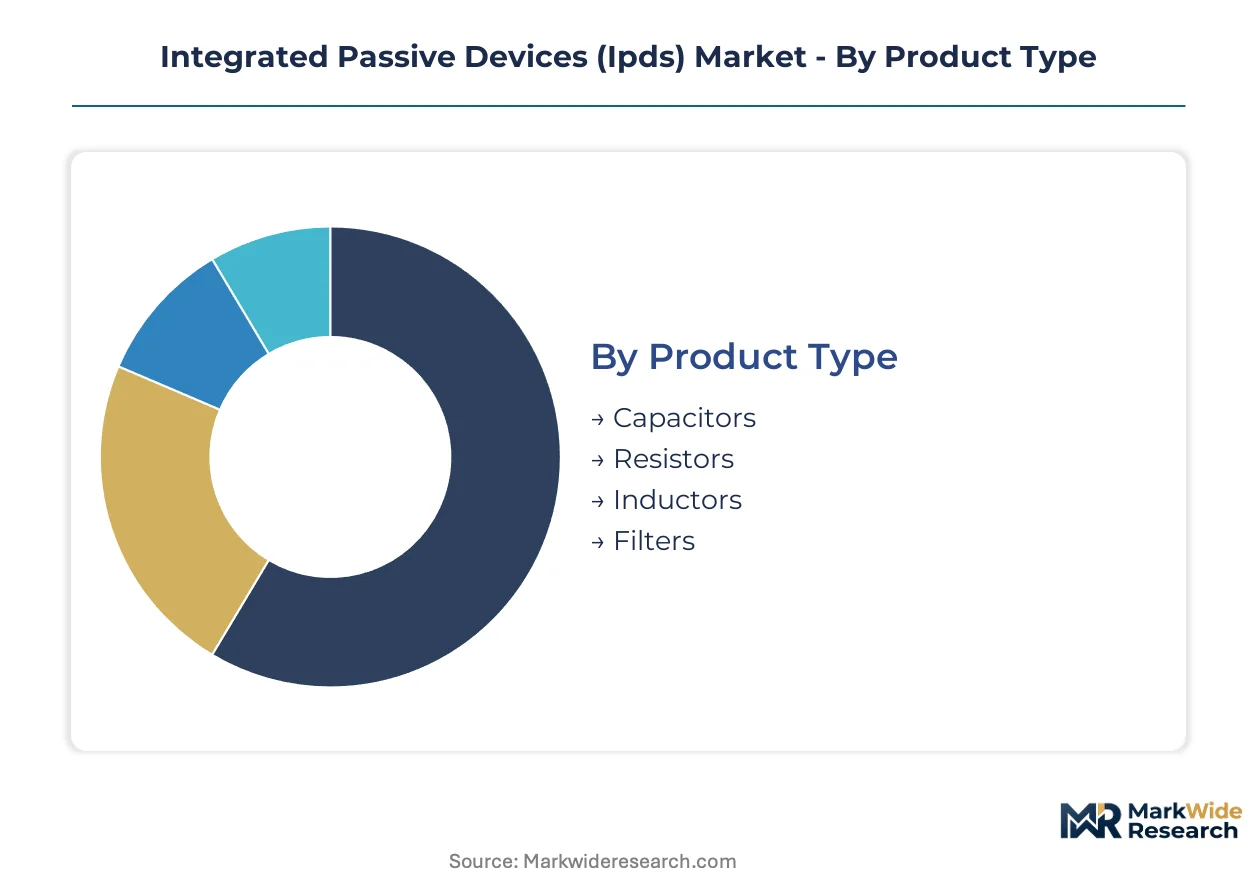
IPD segmentation reveals how integration depth varies dramatically across applications. Standalone surface-mount devices serve cost-optimized consumer tiers, while embedded module formats capture automotive and telecommunications platforms demanding 70% footprint reduction.
Product Type:
Integration depth splits sharply between discrete-function components and multi-element assemblies, with standalone capacitors and resistors dominating high-volume consumer tiers while filter arrays penetrate RF-intensive telecommunications infrastructure.
- Capacitors:Thin-film and ceramic dielectric stacks deliver nanofarad-range capacitance density for decoupling and energy storage. Demand concentrates in 5G base station power distribution networks across China, driven by MIIT spectrum deployment deadlines requiring high-reliability passive integration.
- Filters:Multi-pole LC and ceramic resonator assemblies perform band-selection and interference suppression at frequencies exceeding 6 GHz. Automotive radar modules in Germany absorb these devices as BMW and Mercedes-Benz integrate 77 GHz front-ends for adaptive cruise control systems.
- Resistors:Precision thin-film networks achieve tolerance below 0.1% for analog signal conditioning.
- Inductors:Spiral and solenoid geometries on silicon or ceramic substrates provide microhenry-range inductance for DC-DC converters.
Capacitors lead volumes today; filters are gaining share fastest.
Technology:
Cost tier stratification separates precision-oriented thin-film processes from high-throughput thick-film alternatives, with MEMS batch fabrication disrupting acoustic and tunable component economics.
- Thin Film:Sputtered metal and dielectric layers on silicon or glass achieve sub-micron patterning for tight tolerance RF applications. Telecommunications infrastructure OEMs in South Korea specify these devices for millimeter-wave beamforming modules where phase consistency commands premium positioning.
- MEMS:Semiconductor-compatible surface micromachining produces acoustic resonators and variable capacitors with wafer-scale uniformity. True wireless stereo earbud manufacturers in Japan integrate MEMS-based IPDs for antenna matching networks in space-constrained wearable designs.
- Thick Film:Screen-printed conductive and resistive pastes on ceramic substrates serve cost-sensitive automotive sensor applications.
- Ceramic:Co-fired multilayer processes stack hundreds of alternating electrode and dielectric layers for high-capacitance-density applications.
Thin-film processes anchor premium pricing today; MEMS is climbing the fastest.
End User:
Application-specific qualification requirements create divergent supply chains, with automotive AEC-Q200 validation timelines extending 18-24 months versus 6-12 months for consumer electronics.
- Automotive:AEC-Q200 Grade 0 and Grade 1 qualification mandates temperature cycling to 150°C and mechanical shock resistance for powertrain and chassis electronics. Electric vehicle traction inverter manufacturers in Bavaria specify integrated snubber capacitors and gate resistor networks that survive 10-year vehicle lifespans.
- Telecommunications:Base station and small cell deployments absorb high-frequency filter and impedance-matching IPDs at scale. China's three major carriers drive procurement as MIIT sub-6 GHz and millimeter-wave spectrum allocations compress network rollout schedules.
- Consumer Electronics:Smartphone and tablet OEMs prioritize footprint minimization and cost optimization over extended temperature ranges.
- Aerospace:MIL-PRF-38534 and space-grade qualification requirements govern satellite and avionics applications with radiation tolerance specifications.
Telecommunications commands the steepest expansion trajectory; automotive is climbing fastest.
Form Factor:
Customer type differentiation separates merchant market surface-mount devices from captive module production, with array formats capturing high-pin-count telecommunications ASICs.
- Module:Multi-function passive assemblies integrate resistors, capacitors, inductors, and filters on single substrates with wire-bond or flip-chip interconnect. Automotive Tier-1 suppliers in Baden-Württemberg source these directly from foundries, bypassing distributor channels for electric platform programs.
- Surface Mount:Standardized 0402, 0603, and 0805 footprints enable pick-and-place assembly compatibility with existing PCB infrastructure. High-volume consumer electronics contract manufacturers in Shenzhen deploy these for cost-optimized smartphone and tablet motherboards.
- Chip:Bare die formats support system-in-package and 3D stacking configurations for advanced mobile processors.
- Array:Grid arrangements of identical passive elements serve memory termination and parallel bus applications.
Surface-mount formats dominate shipment volumes today; module integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting IPD production toward jurisdictions with lower compliance friction. Manufacturers are relocating thin-film fabrication to exploit gaps between EU REACH enforcement and Asian material standards.
China
MIIT spectrum deadlines for sub-6 GHz and millimeter-wave bands are absorbing high-frequency filter IPDs at unprecedented scale. Domestic semiconductor self-sufficiency programs under the 14th Five-Year Plan accelerate local consumption across Shenzhen and Dongguan manufacturing clusters. Three state-owned carriers drive procurement compression as network rollout schedules tighten.
Germany
BMW and Mercedes-Benz electric platform programs in Bavaria and Baden-Württemberg specify automotive-grade integrated passives for traction inverters. KBA type-approval requirements for 77 GHz radar modules mandate AEC-Q200 Grade 0 qualification timelines extending 18-24 months. Stuttgart automotive electronics clusters are consolidating procurement through direct substrate sourcing from captive foundries.
United States
FCC Part 15 emissions rules shape certification requirements for telecommunications and automotive radar deployments. Silicon Valley RF front-end designers specify thin-film IPDs for 5G infrastructure buildouts. Austin and Phoenix semiconductor corridors attract packaging investments serving defense and aerospace applications with MIL-PRF-38534 qualification demands.
Japan
METI technology roadmaps prioritize MEMS-acoustic convergence for true wireless stereo earbud manufacturers in Tokyo and Osaka. JIS standards for high-frequency passive components create technical barriers for foreign suppliers. Kyoto and Nagoya ceramic material science clusters supply BST varactors for smartphone antenna tuners.
South Korea
Base station OEMs in Seoul and Suwon specify thin-film IPDs for millimeter-wave beamforming modules where phase consistency commands premium positioning. MFDS radio equipment certification aligns with EU RED frameworks but maintains domestic testing protocols. Pangyo and Hwaseong semiconductor complexes concentrate RF system architect talent for substrate-level integration.
Integrated Passive Devices (Ipds) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around captive foundry operators and merchant ceramic specialists, with thin-film precision players occupying premium tiers. Three archetypes dominate: Japanese material science leaders, European supply security anchors, and Korean scale-driven fabricators. Competitive moves center on foundry capacity allocation and direct Tier-1 automotive partnerships bypassing distributor channels.
Within the material science tier, Murata Manufacturing Co., Ltd. exemplifies ceramic expertise leveraged across high-frequency applications. STMicroelectronics anchors European supply security through captive fabrication footprints in France and Italy. Infineon Technologies AG occupies a position within automotive-grade specialization, representing the AEC-Q200 qualification tier for electric powertrain systems.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| STMicroelectronics |
| Broadcom Inc. |
| Infineon Technologies AG |
| Samsung Electro-Mechanics Co., Ltd. |
| Taiyo Yuden Co., Ltd. |
| Vishay Intertechnology, Inc. |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| Others |
Supply & Pricing Matrix
Electromagnetic simulation talent concentration in South Korea's Pangyo semiconductor corridor feeds labor-cost differentials that widen pricing spreads between premium thin-film precision tiers and commodity thick-film alternatives. Thin-film sputtering specialists command compensation premiums that filter into AEC-Q200 Grade 0 component pricing, while thick-film screen-printing operations in China's Pearl River Delta sustain economy-tier positioning through accessible technical labor pools.
Pricing Analysis
Capacity additions in China's Dongguan manufacturing clusters are reshaping price floors for ceramic-based IPD formats as domestic foundries scale thick-film production. Three-tier pricing structure across AEC-Q200 certified, industrial-grade, and consumer-grade levels separates automotive traction inverter specifications from smartphone motherboard applications. Cost compression in consumer-grade tiers intensifies because MEMS batch-fabrication economics displace traditional ceramic processes. Smartphone OEMs in Shenzhen exhibit highest price sensitivity; Bavarian automotive Tier-1 suppliers demonstrate lowest sensitivity due to 10-year reliability warranties.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Baden-Württemberg automotive electronics clusters, bypassing traditional distributor markups for electric platform programs. Raw material dependencies draw from palladium-silver electrode paste formulations, silicon wafer substrates, and BST ceramic dielectric precursors sourced from Japanese material science suppliers. Geographic supply concentration centers on France and Italy for captive 8-inch silicon fabrication, China for ceramic substrate processing, and Japan for high-frequency dielectric materials. Single-source vulnerability in 8-inch silicon wafer supply creates structural risk as STMicroelectronics and Infineon concentrate captive capacity in European foundry corridors. Distribution runs through direct substrate sourcing agreements for automotive Tier-1 procurement, with merchant channels serving consumer electronics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated Passive Devices represent a late-cycle quality story as automotive electrification and 5G infrastructure deployment shift procurement specifications toward AEC-Q200 Grade 0 and millimeter-wave precision tiers that command sustainable margin premiums.
For Market Incumbents: Anchor AEC-Q200 qualification leadership through captive foundry capacity expansion in European supply security corridors, defending against MEMS-based acoustic resonator substitution in wearable applications. Prioritize backward integration into ceramic dielectric precursor supply to offset palladium price volatility exposure from London Metal Exchange swings. Direct Tier-1 automotive partnerships in Bavaria and Baden-Württemberg consolidate negotiation leverage against distributor channel disintermediation. For New Entrants and Emerging Players: MEMS-acoustic convergence for true wireless stereo earbud antenna matching networks offers the most penetrable white-space target, exploiting semiconductor batch-processing economics against incumbent ceramic expertise. India's Modified Programme for Semiconductors assembly incentives create geographic entry opportunity for telecom and automotive export hub positioning. Lead with software-defined tuning services for RF front-end modules to capture recurring value beyond component transactional sales. For Investors and Strategic Acquirers: Automotive semiconductor suppliers are the most active acquirer in this space, seeking IPD capabilities to complete powertrain electrification portfolios. Long-term viability centers on substrate-level integration expertise that displaces discrete component stacking across 5G and 6G research programs. Target acquisition archetype: thin-film precision specialists with established MIIT or FCC certification databases. Watch for MIIT spectrum allocation acceleration as inflection indicator for China demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | STMicroelectronics and Infineon secure European supply security against 8-inch silicon wafer tightness. |
| MEMS-Acoustic Convergence Development | Japanese manufacturers integrate resonator technology with impedance matching for wearable RF modules. |
| Software-Defined Tuning Services Launch | Murata captures recurring revenue streams beyond component sales through calibration subscriptions. |
| India PLI Packaging Investment | Domestic assembly incentives attract IPD operations for telecom and automotive export corridors. |
| Glass Substrate Process Qualification | Corning and Schott enable ultra-low-loss IPDs for 6G terahertz frequency research programs. |
Research Methodology
Bottom-up telecommunications and automotive platform modeling reconciled against top-down foundry capacity and material supply tracking forms the analytical core of this study. Primary interviews with RF system architects, automotive Tier-1 procurement directors, ceramic material scientists, and semiconductor foundry operations managers combined with secondary validation from SEC 10-K filings, MIIT spectrum allocation announcements, ECHA REACH substance restriction updates, and AEC-Q200 qualification database records. Triangulation between demand-side deployment schedules and supply-side capacity constraints ensures cross-verified volume and value estimates.
Historical trendline analysis of thin-film versus thick-film adoption patterns, MEMS batch-fabrication scaling curves, and automotive electrification content-per-vehicle trajectories informed projection framework construction across the analysis window. Segmentation dimensions modeled include integration depth (standalone versus embedded module), fabrication technology (thin-film, MEMS, thick-film, ceramic), end-use qualification tier (AEC-Q200 Grade 0/1, industrial, consumer), and geographic regulatory cluster (FCC Part 15, EU RED, MIIT GB standards, METI JIS). CAGRs derive from fitted growth curves against named spectrum deadlines and vehicle platform launch schedules, with sensitivity analysis around palladium price volatility and 8-inch silicon wafer availability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT spectrum reallocation, ECHA nickel exposure limit tightening, and silicon carbide power module adoption velocity. Forecasts reflect documented assumptions regarding automotive electrification penetration and 5G infrastructure buildout cadence. Periodic stress-testing of base assumptions against foundry utilization rates and material compliance deadline enforcement is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market