
 Thick Film Resistor Market | 2026-2036
Thick Film Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Thick Film Resistor Market Analysis
The EU Green Deal is expanding material traceability requirements for passive electronic components. YAGEO Corporation leverages its vertical integration across ceramic substrate and conductive paste production to secure supply chain stability. Vishay Intertechnology Inc. anchors its competitive position through specialized high-reliability product lines serving automotive and aerospace buyers. Panasonic Holdings Corporation sustains manufacturing scale advantages through automated thick film printing operations in multiple Asian facilities.
Thick film resistors are passive electronic components manufactured by depositing resistive paste—typically composed of ruthenium oxide, glass frit, and organic binders—onto ceramic substrates through screen printing, then firing at temperatures exceeding 800°C to achieve stable ohmic values. These components function primarily as current limiters, voltage dividers, and load elements across circuits requiring cost-effective thermal stability and surge tolerance. Standard Thick Film products dominate unit volumes due to their broad applicability in consumer electronics and general industrial equipment, while High Power Thick Film segments capture disproportionate margin pools from electric vehicle inverters and renewable energy converters. The Automotive end user category represents the fastest structural expansion as electrified powertrains multiply resistor counts per vehicle for battery monitoring, motor control, and DC-DC conversion functions.
REACH in Europe restricts hazardous substance content in electronic components, compelling reformulation of traditional resistive pastes and recertification of supply chains. China's SAMR enforces GB standards for passive component reliability in domestic automotive and telecommunications equipment, creating compliance barriers for non-certified imports. The US EPA oversees waste handling from ruthenium mining and paste manufacturing under hazardous material protocols. Stakeholders must monitor evolving substance restrictions and regional certification divergence to maintain market access across major manufacturing and consumption zones.
Market Dynamics
Automotive electrification is compressing design cycles for precision resistive components as battery management systems multiply resistor counts per vehicle. Ruthenium paste supply concentration in East Asian refining clusters creates asymmetric pricing power that ripples through component cost structures.
Growth Catalysts
- Automotive Electrification:Battery management systems in electric vehicles require precision resistive networks for cell monitoring and thermal regulation. Each electrified powertrain adds 15-25 thick film resistors for DC-DC conversion and motor control functions.
- REACH Compliance:European hazardous substance restrictions are forcing paste reformulation toward lead-free glass frit systems. Manufacturers achieving early certification capture preferential placement in EU automotive supply chains.
- East Asian Manufacturing Clusters:Concentrated ceramic substrate and conductive paste production in Japan, South Korea, and Taiwan enables rapid scale-up for consumer electronics and industrial equipment demand.
Market Restraints
- Ruthenium Price Volatility:Mining concentration in South African and Russian deposits exposes paste costs to geopolitical supply disruptions. Spot price swings above 40% annually compress resistor gross margins unpredictably.
- Technical Performance Ceiling:Thick film temperature coefficients of resistance (TCR) bottom out near ±50 ppm/°C, limiting penetration into precision instrumentation where thin film or metal foil alternatives dominate.
- Substitution by Integrated Solutions:Application-specific integrated circuits (ASICs) with built-in resistive elements are displacing discrete components in compact consumer electronics designs.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and passive component assembly are attracting thick film resistor investments. Domestic automotive and telecom equipment demand creates captive offtake.
- High-Temperature Applications:Silicon carbide (SiC) power modules in EV inverters require resistors rated above 200°C ambient. Specialized thick film formulations with noble metal additives address this thermal envelope.
- Renewable Energy Converters:Grid-tied solar inverters and wind turbine power electronics need surge-tolerant load resistors. This application segment values reliability over unit cost, supporting margin expansion.
Industry Challenges
- Screen Printing Expertise Gap:Firing profile optimization for ruthenium-glass systems requires 10-15 years of process engineering experience. Talent scarcity in Japanese and Taiwanese facilities constrains capacity expansion.
- Multi-Geography Certification Burden:Simultaneous compliance with REACH, China's GB standards, and US EPA hazardous waste protocols extends new product qualification timelines by 8-12 months.
- Legacy Equipment Integration:Automated thick film lines from 1990s-era installations lack data connectivity for modern MES systems. Retrofit costs compete with greenfield automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thick Film Resistor Market |
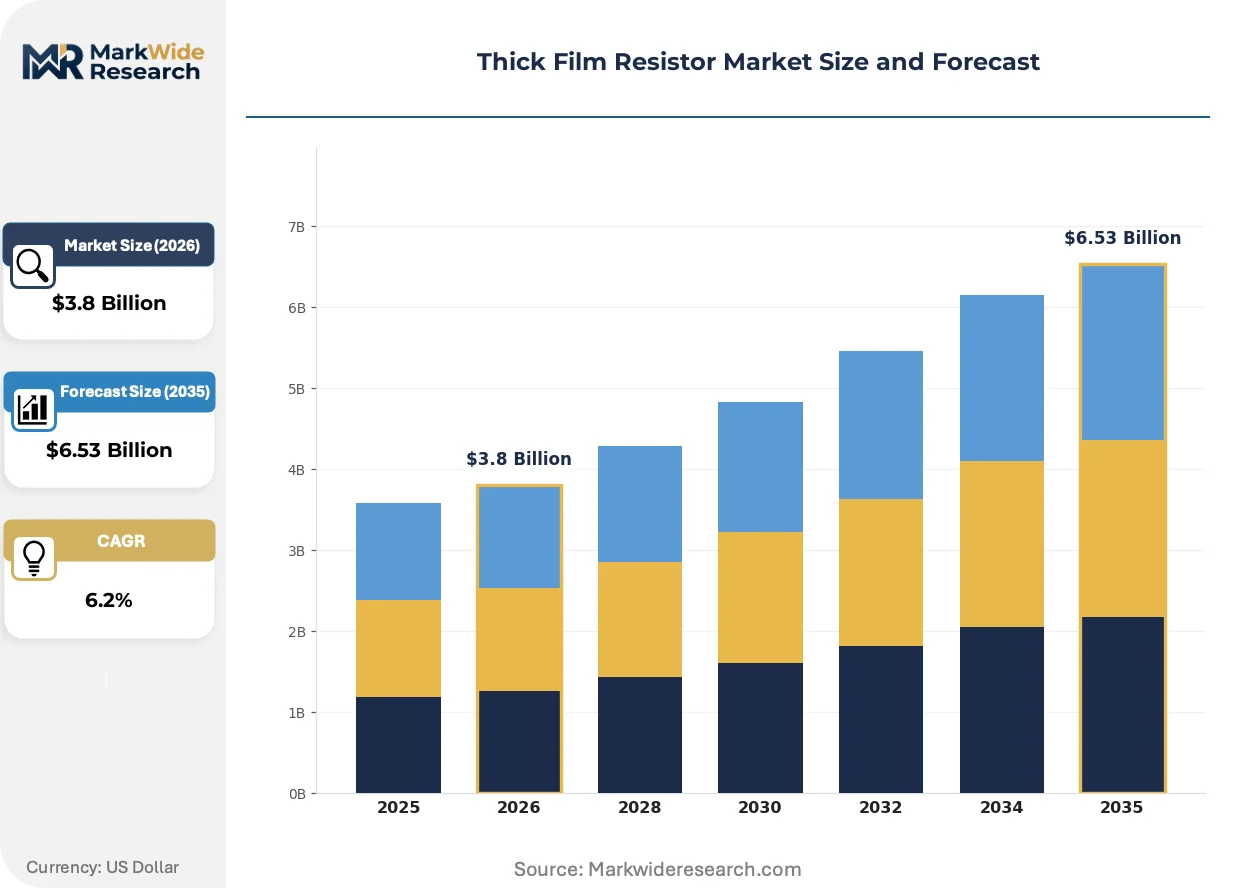
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Thick Film, High Power Thick Film, High Voltage Thick Film, Thin Film End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Application: Power Supply, Signal Conditioning, Medical Devices, Control Systems Technology: Mixed Signal, Analog Technology, Digital Technology, Others |
| Companies Covered | YAGEO Corporation, Vishay Intertechnology Inc., Panasonic Holdings Corporation, KOA Corporation, Rohm Semiconductor, Murata Manufacturing Co. Ltd., TE Connectivity Ltd., Bourns Inc., TT Electronics plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thick Film Resistor Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape resistor manufacturing processes. The industry is pivoting from traditional ruthenium oxide formulations toward alternative resistive systems that balance performance with environmental compliance.
Copper-nickel alloy thick film systems are consolidating as the primary alternative to ruthenium-based pastes for mid-precision applications. Automotive tier-1 suppliers in Germany and Japan are qualifying these formulations for battery management systems where TCR requirements are less stringent than aerospace grades. This substitution is compressing ruthenium demand growth and redirecting R&D investment toward alloy sintering process control.
China's SAMR enforcement of GB standards for passive component reliability is tightening domestic automotive supply chain entry. Foreign manufacturers must establish in-country testing laboratories or partner with certified local entities to access EV platform programs. Japanese suppliers with existing Suzhou and Shenzhen facilities are adapting fastest to documentation and traceability requirements.
Long-term supply agreements are displacing spot purchasing for ruthenium paste and ceramic substrates. Automotive OEMs in South Korea and Germany are mandating 3-5 year fixed-price contracts with volume commitments to secure allocation during raw material shortages. This contractual shift transfers inventory risk upstream to resistor manufacturers while stabilizing OEM bill-of-materials forecasting.
Thick Film Resistor Market Segmentation
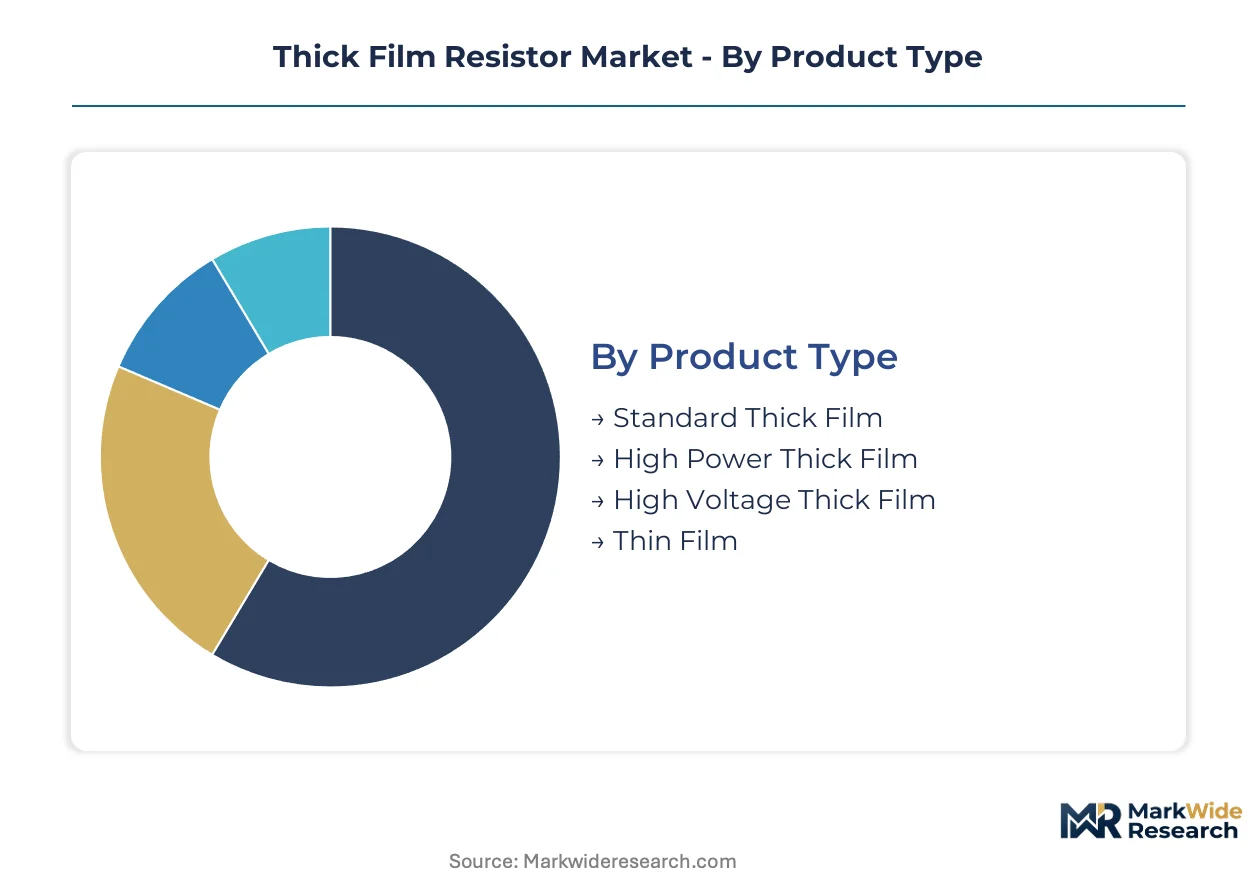
Thick film resistor segmentation reveals divergent certification pathways and margin structures across product tiers. Each category carries distinct regulatory burdens that reshape competitive positioning and sourcing decisions.
Product Type:
REACH compliance in Europe and China's SAMR GB standards impose tiered certification requirements: automotive-grade segments demand full material traceability, while consumer-grade products face lighter documentation loads.
- Standard Thick Film:Ruthenium oxide-glass frit formulations deposited on alumina substrates deliver cost-effective thermal stability for general-purpose circuits. Consumer electronics manufacturing in Taiwan and South Korea consumes the majority of unit volume, though automotive electrification is redirecting some capacity toward battery management qualification programs.
- High Power Thick Film:Noble metal additives and specialized ceramic substrates enable continuous operation above 200°C ambient in silicon carbide power modules. Electric vehicle inverter programs in Germany and South Korea specify these components for DC-DC conversion stages, where failure tolerance approaches zero.
- High Voltage Thick Film:Extended resistor bodies and optimized termination geometries address insulation requirements above 1kV. Medical imaging equipment and industrial motor drives in Japan represent primary demand concentration.
- Thin Film:Sputtered nickel-chromium alloys on polished ceramic achieve precision TCR below ±25 ppm/°C. Aerospace instrumentation and laboratory equipment in Switzerland and the United States specify these for measurement circuits where thick film performance ceilings prove prohibitive.
Leading the category by volume: Standard Thick Film. Growing fastest: High Power Thick Film.
End User:
Cost tier stratification separates premium reliability grades from economy offerings, with automotive and medical applications commanding 3-5x unit price multiples over consumer segments.
- Automotive:Battery management systems and motor control circuits in electrified powertrains require AEC-Q200 qualification and full PPAP documentation. Each EV platform adds 15-25 thick film resistors for cell monitoring and thermal regulation functions.
- Consumer Electronics:Smartphones, tablets, and wearables prioritize miniaturization and unit cost over precision specifications. Assembly operations in Shenzhen and Ho Chi Minh City drive high-volume, low-margin procurement patterns.
- Telecommunications:Base station power amplifiers and network infrastructure equipment demand surge tolerance and long-term stability. 5G rollout programs in India and Brazil are expanding addressable demand.
- Industrial Equipment:Factory automation, process control, and robotics applications balance reliability requirements with cost constraints. German and Japanese machinery OEMs specify thick film resistors for motor drives and power supply stages.
Automotive commands the steepest margin expansion. Consumer Electronics retains dominant unit share.
Application:
Supply concentration in East Asian ceramic substrate and paste production creates geographic lock-in effects that vary by application criticality.
- Power Supply:Input filtering, snubber networks, and current sensing in AC-DC and DC-DC converters. Server farms and data centers in Virginia and Frankfurt specify high-reliability grades for 24/7 operation.
- Signal Conditioning:Voltage division and impedance matching in analog front-end circuits. Precision instrumentation in Switzerland and Massachusetts favors thin film alternatives where TCR requirements exceed thick film capabilities.
- Medical Devices:Patient monitoring equipment and diagnostic imaging systems require biocompatibility documentation and failure mode analysis. FDA and EMA quality system regulations extend qualification timelines.
- Control Systems:Feedback networks and protection circuits in industrial automation. Japanese and German robotics manufacturers specify thick film resistors for servo motor controllers.
Power Supply leads absolute consumption. Medical Devices shows the steepest expansion trajectory.
Technology:
Customer type fragmentation separates OEM captive production from merchant market procurement, with mixed-signal designs increasingly dominating new product introductions.
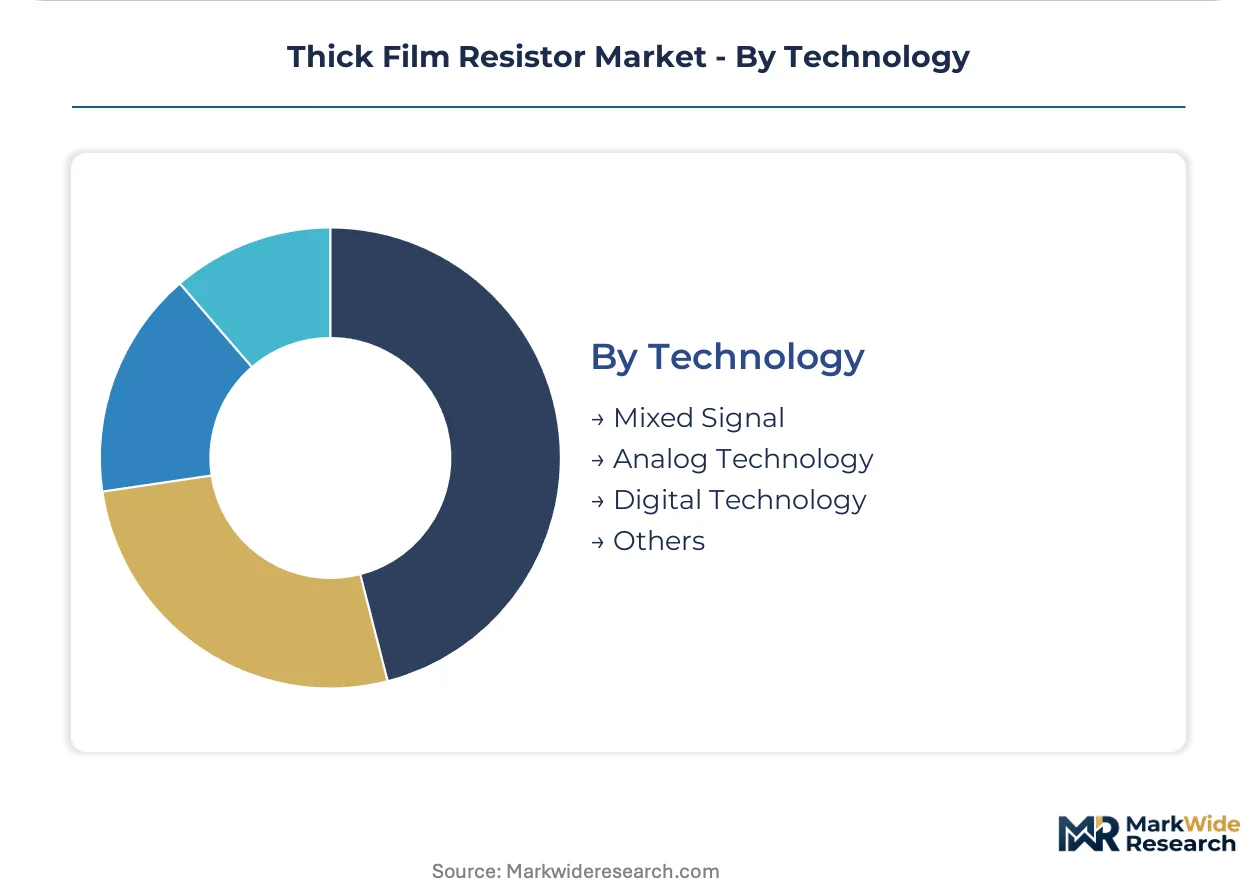
- Mixed Signal:Resistive elements bridging analog and digital domains in data converters and sensor interfaces. Automotive ADAS platforms and industrial IoT nodes in South Korea and Taiwan specify these networks.
- Analog Technology:Traditional voltage division and current limiting in linear circuits. Legacy industrial equipment and audio electronics in Germany and Japan sustain steady replacement demand.
- Digital Technology:Termination resistors and pull-up networks in logic circuits. Consumer electronics and computing equipment in China and Vietnam drive high-volume consumption.
- Others:Specialized RF and microwave applications requiring precise impedance matching. Satellite communications and radar systems in the United States and France specify custom formulations.
Mixed Signal captures the fastest share gain. Analog Technology retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate thick film resistor production, while Western automotive electrification programs drive premium-grade consumption. This geographic asymmetry creates distinct sourcing patterns across major demand centers.
Japan
Automotive OEMs in Toyota City and Yokohama specify AEC-Q200 qualified resistors for hybrid and battery electric platforms. METI enforces JIS standards for passive component reliability in domestic automotive supply chains. Manufacturing concentrates in the Chubu region around Nagoya, where Murata and Panasonic operate automated thick film printing facilities serving tier-1 suppliers.
Germany
BMW and Volkswagen battery management programs in Munich and Wolfsburg require full PPAP documentation and REACH-compliant paste formulations. The KBA mandates material traceability for electrified powertrain components under EU Green Deal protocols. Industrial clusters in Bavaria and Baden-Württemberg host qualification laboratories for automotive-grade resistor certification.
South Korea
Hyundai-Kia EV platforms in Ulsan and Gwangmyeong multiply resistor counts per vehicle for cell monitoring and thermal regulation. The MFDS coordinates with automotive regulators on component reliability standards. Seoul Capital Area facilities supply Samsung SDI and LG Energy Solution with high-power thick film networks for inverter applications.
United States
Tesla and Rivian manufacturing in Austin and Normal, Illinois drive demand for surge-tolerant resistors in DC-DC conversion stages. The EPA oversees hazardous waste protocols from ruthenium mining and paste manufacturing. Defense and aerospace procurement in California and Massachusetts specifies thin film alternatives where TCR requirements exceed thick film capabilities.
China
BYD and CATL battery programs in Shenzhen and Ningbo consume standard thick film volumes for cost-sensitive cell monitoring functions. SAMR enforces GB standards for passive component reliability in domestic automotive and telecommunications equipment. Yangtze River Delta manufacturing clusters in Suzhou and Wuxi produce ceramic substrates and conductive pastes for regional resistor assembly.
Thick Film Resistor Market Vendor Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive ceramic substrate and paste production. Market concentration remains moderate, with Japanese and Taiwanese incumbents holding process expertise advantages while Korean and Chinese challengers expand capacity. Three archetypes dominate: vertically integrated material-to-component manufacturers, specialized high-reliability suppliers, and scale-driven commodity producers. Capacity expansion and long-term supply agreements with automotive OEMs constitute the primary competitive moves reshaping positioning.
Within the diversified conglomerate tier, YAGEO Corporation and Panasonic Holdings Corporation exemplify players with backward integration into ceramic substrate and conductive paste production. Vishay Intertechnology Inc. occupies a position among specialized high-reliability suppliers serving automotive and aerospace qualification programs. These three anchors represent distinct strategic postures—material control, manufacturing scale, and certification depth—that define competitive boundaries in thick film resistor supply.
| Leading Market Players |
|---|
| YAGEO Corporation |
| Vishay Intertechnology Inc. |
| Panasonic Holdings Corporation |
| KOA Corporation |
| Rohm Semiconductor |
| Murata Manufacturing Co. Ltd. |
| TE Connectivity Ltd. |
| Bourns Inc. |
| TT Electronics plc |
| Others |
Supply Flow & Price Mechanics
Automotive-grade AEC-Q200 certification separates premium resistor tiers from commodity consumer electronics supply, embedding this divergence in both pricing power and sourcing geography. REACH compliance costs and ruthenium paste traceability requirements concentrate high-margin production in Japanese and German facilities with established qualification laboratories, while standard-grade volumes flow through Taiwanese and Chinese assembly operations optimized for unit cost.
Pricing Analysis
Margin tightening in standard-grade segments reflects copper-nickel alloy substitution compressing ruthenium-based paste premiums. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels tracks certification burden and material traceability depth. Cost-down pressure on consumer electronics resistors accelerates because smartphone OEMs in Shenzhen and Ho Chi Minh City negotiate aggregate volume discounts. Battery management system suppliers show least price sensitivity, accepting 3-5x unit multiples for zero-failure-tolerance specifications.
Supply Chain Analysis
Ruthenium feedstock rests on South African and Russian mining concentration, exposing paste manufacturers to geopolitical supply disruptions. Ceramic substrate production concentrates in Japan, South Korea, and Taiwan, with alumina and zirconia drawing from specialized Japanese and Chinese refractory suppliers. Single-source vulnerability in noble metal additives threatens high-power resistor allocation during spot price spikes. Distribution runs through tier-1 automotive supplier consignment programs and electronics distributor stocking agreements serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thick film resistor supply constitutes a cost-of-compliance story where REACH substance restrictions and China's SAMR GB standards erect barrier-to-entry moats favoring incumbents with established certification infrastructure and in-country testing capacity.
For Market Incumbents: Lock in long-term ruthenium paste offtake agreements with South Korean and German automotive OEMs to secure allocation during raw material shortages. Deepen backward integration into ceramic substrate production to insulate margin structures from alumina price volatility. Prioritize Suzhou and Shenzhen laboratory accreditation to defend Chinese EV platform access against SAMR documentation requirements. For New Entrants and Emerging Players: Copper-nickel alloy thick film formulations offer a technology-first wedge into mid-precision battery management segments where TCR requirements remain below ±100 ppm/°C. Target India's PLI scheme incentives for passive component assembly, leveraging domestic automotive and telecom equipment demand as captive offtake. Pursue qualification partnerships with established Japanese substrate suppliers to compress 8-12 month certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty high-reliability suppliers with AEC-Q200 and aerospace qualification depth that diversified conglomerates seek for automotive electrification exposure. Five-to-ten-year viability hinges on ruthenium paste reformulation capabilities and East Asian manufacturing footprint scale. Watch copper-nickel alloy adoption rates in German and Japanese automotive tier-1 programs as inflection indicator for ruthenium demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Ruthenium Supply Agreement | Secures paste allocation for Korean and German automotive OEM battery programs during spot market volatility. |
| Backward Integration into Ceramic Substrate Production | Captures alumina and zirconia margin pools while insulating against Japanese substrate supplier pricing power. |
| REACH-Compliant Paste Reformulation | Enables preferential placement in EU automotive supply chains as ECHA restrictions tighten lead-free glass frit requirements. |
| India PLI Scheme Manufacturing Entry | Accesses domestic automotive and telecom demand with government incentive support for passive component assembly. |
| High-Temperature Resistor Development | Addresses silicon carbide power module requirements above 200°C ambient in EV inverter applications. |
Methodological Framework
Multi-period observation of ruthenium spot pricing, automotive platform resistor counts, and regional certification timelines anchored the trend analysis, supplemented by interviews with thick film resistor procurement managers at German and Japanese tier-1 automotive suppliers, ceramic substrate production engineers in Nagoya and Seoul, and regulatory affairs specialists navigating REACH and SAMR compliance. Secondary validation drew from ECHA substance restriction databases, SAMR GB standard filings, SEC 10-K disclosures from diversified electronics conglomerates, and trade flow data for ruthenium oxide and alumina substrates. Bottom-up segment sizing triangulated against top-down automotive electrification content-per-vehicle models.
Input-output matrices structured demand across product type, end user, and application dimensions, with technology and geography completing the segmentation framework. CAGRs derived from fitted growth curves applied to base-year estimates across the projection horizon. Forecast inputs incorporated EV platform rollout schedules, copper-nickel alloy qualification progress at German automotive suppliers, and SAMR enforcement intensity for passive component reliability documentation.
Several conditions sit outside the modeled scope, including abrupt ruthenium supply disruptions from South African mining labor actions or Russian export restrictions, and faster-than-anticipated ASIC integration displacing discrete resistors in consumer electronics. Forecasts reflect documented assumptions about alloy substitution rates and certification timeline stability. A small set of named triggers warrants ongoing watch: copper-nickel sintering process yields, SAMR laboratory accreditation backlogs, and Korean automotive OEM long-term contracting posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market