
 High Voltage Switchboard Market | 2026-2036
High Voltage Switchboard Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Switchboard Market Foresight
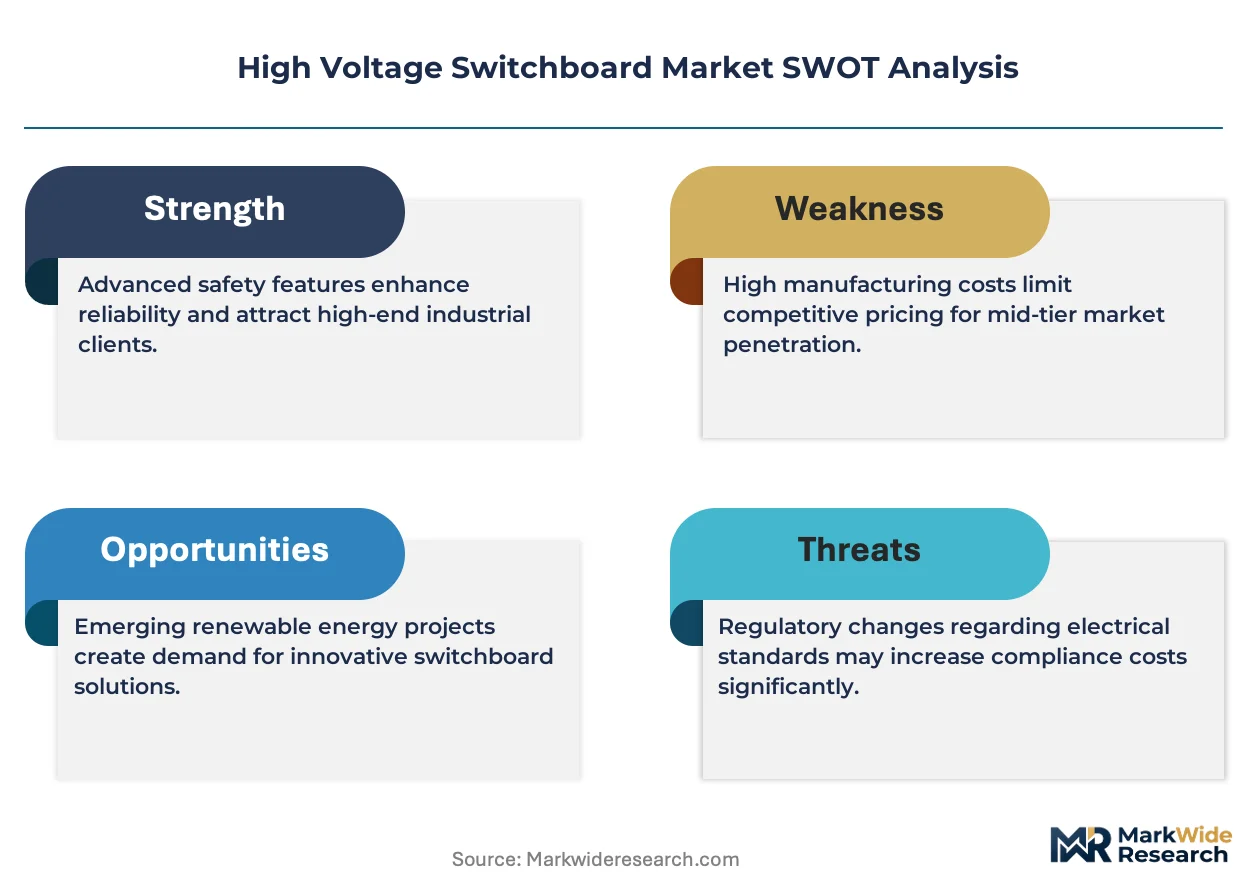
Copper busbar assemblies are pivoting toward aluminum-silver hybrid designs to offset raw material volatility. ABB leverages its European manufacturing base to sustain premium positioning in gas-insulated systems. Siemens AG anchors its competitive stance through deep software integration with switchboard hardware. Schneider Electric differentiates via modular architectures that slash on-site commissioning cycles.
High voltage switchboards are electrical distribution assemblies rated above 1 kV that route power through circuit breakers, busbars, and protective relays housed in metal-enclosed compartments, typically engineered for 12 kV to 36 kV operational ranges with short-circuit withstand ratings up to 50 kA. Their primary purpose is to segment power flows, isolate faults, and enable maintenance access without de-energizing entire grids. Gas-insulated switchgear commands the dominant revenue share due to its compact footprint and reliability in dense urban substations, while modular switchgear represents the fastest-expanding category as utilities prioritize scalable, factory-tested configurations that reduce field labor. Air-insulated variants retain cost advantages in rural and outdoor installations where space constraints are minimal.
The International Electrotechnical Commission sets arc-fault and dielectric withstand benchmarks under IEC 62271, while regional regulators such as the Central Electricity Authority in India mandate seismic qualification and tropical climate ratings for equipment procurement. Compliance with these frameworks shapes vendor qualification lists and directly gates market access for non-certified suppliers. Stakeholders must track evolving grid code harmonization between ASEAN member states and assess localized content rules that could reroute procurement toward domestic assembly partners.
Market Dynamics
Grid modernization across Southeast Asia is compressing procurement cycles as utilities race to interconnect dispersed solar and offshore wind assets before monsoon seasons disrupt construction schedules.
Growth Catalysts
- IEC 62271-200 arc-flash compliance:Southeast Asian regulators are mandating internal arc classification ratings for urban substations, forcing equipment upgrades and creating specification-driven replacement demand.
- Vietnam Power Development Plan 8:The government's transmission corridor buildout requires thousands of new 220 kV and 500 kV substations, concentrating switchboard procurement through state-owned EVN.
- Gas-insulated switchgear densification:Land-scarce cities like Jakarta and Manila are specifying GIS over air-insulated alternatives to halve substation footprints in dense commercial districts.
Market Restraints
- Copper price volatility:Raw material swings exceeding 30 percent annually are eroding fixed-price contract margins for busbar-intensive assemblies.
- European component concentration:Critical vacuum interrupters and cast resin insulators rely on a three-supplier oligopoly centered in Germany and Switzerland.
- SF6 phase-down timelines:The EU F-Gas Regulation and parallel ASEAN draft standards are compressing the operational window for sulfur hexafluoride-dependent GIS designs.
Strategic Opportunities
- Philippines island grids:The archipelago's 7,000-plus islands lack interconnected infrastructure, creating demand for containerized, modular switchboards deployable by barge.
- Digital twin integration:Converging switchboard hardware with asset performance management software enables recurring revenue streams through predictive maintenance subscriptions.
- Indonesia PLN electrification targets:The state utility's 35,000 MW capacity addition program mandates localized assembly partnerships, opening joint venture pathways for foreign technology licensors.
Industry Challenges
- Seismic qualification bottlenecks:IEC 62271-2 shake-table testing requires six-month lead times at accredited Southeast Asian laboratories, delaying project commissioning.
- Legacy air-insulated retrofit complexity:Aging 11 kV outdoor switchyards in rural Vietnam and Laos resist GIS conversion without complete civil works reconstruction.
- Specialized commissioning engineer scarcity:Gas handling certification and partial discharge testing expertise concentrates in Bangkok and Singapore, inflating field service costs for remote Indonesian installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Switchboard Market |
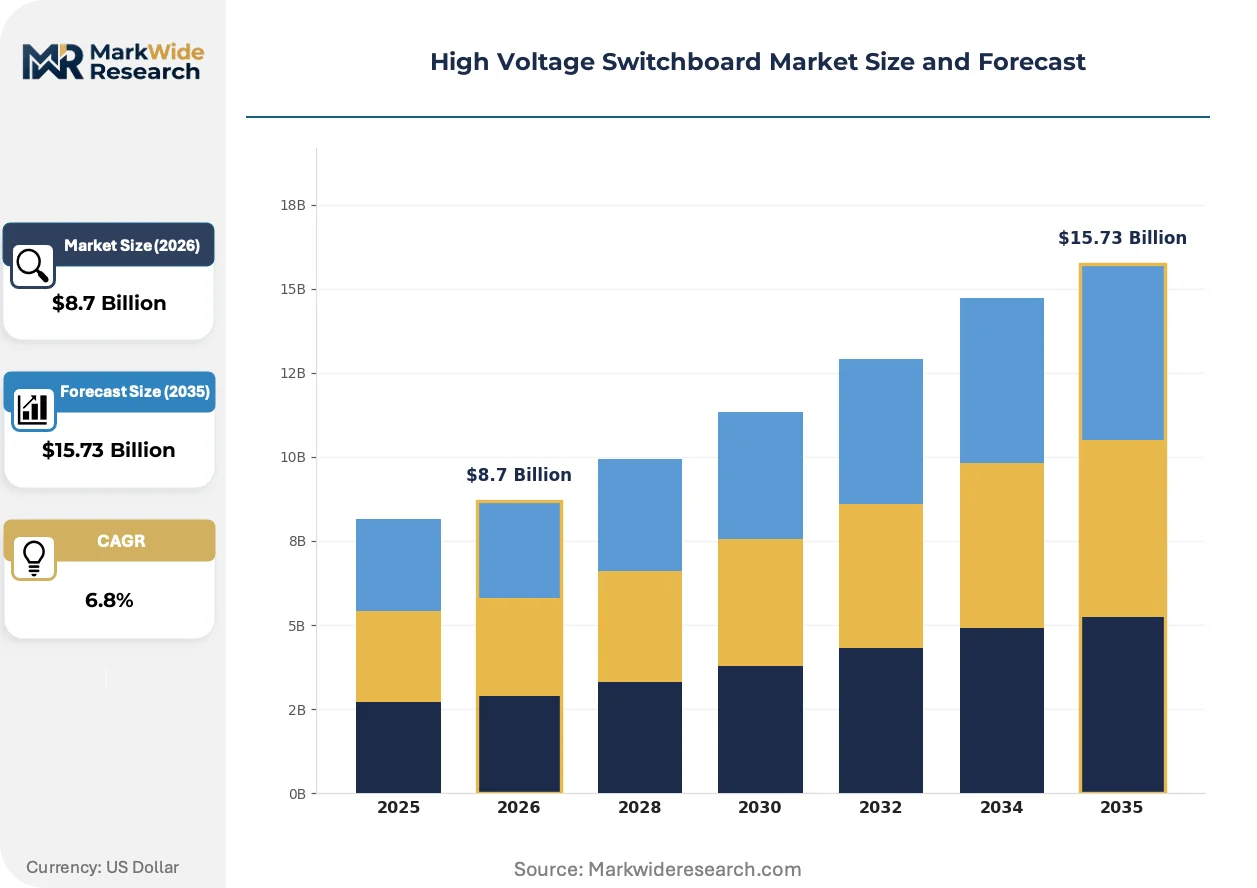
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-insulated Switchgear, Gas-insulated Switchgear, Hybrid Switchgear, Modular Switchgear Installation Type: Indoor, Outdoor, Prefabricated, Containerized End User: Utility, Industrial, Commercial, Renewable Energy Operation Technology: Manual, Automated, Remote-controlled, Intelligent Monitoring |
| Companies Covered | Siemens AG, ABB, Schneider Electric, Eaton Corporation, General Electric, Mitsubishi Electric, Hitachi Energy, Toshiba, LS Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Switchboard Market Shifts & Advancements
Digitalization is penetrating switchboard architecture from protection relays through busbar temperature monitoring, collapsing the traditional separation between primary equipment and control systems into unified intelligent platforms.
Aluminum-silver hybrid busbar designs are integrating composite metallurgy to maintain conductivity while shedding 40 percent of copper mass. Indonesian and Vietnamese utilities are piloting these assemblies in coastal substations where corrosion resistance outweighs pure copper thermal performance. The technology is integrating factory-tested modular segments that slash on-site welding and brazing labor by two-thirds.
Thailand's Provincial Electricity Authority and Malaysia's TNB are tightening procurement specifications around IEC 61850 communication protocols for substation automation. The regulation forces vendors to embed Ethernet-based process bus architectures alongside conventional hardwired tripping circuits. GIS suppliers serving Bangkok's metropolitan ring are responding by pre-configuring dual-protocol protection schemes in factory acceptance testing.
Power utilities are unbundling switchboard supply from installation and commissioning, awarding engineering-procurement-construction contracts to local contractors while retaining direct relationships with OEMs for critical components. This procurement fragmentation is most visible in Vietnam's competitive bidding rounds for 500 kV backbone projects, where foreign manufacturers face margin pressure from domestic EPC consortia bidding below equipment cost to secure civil works packages.
High Voltage Switchboard Market Segmentation
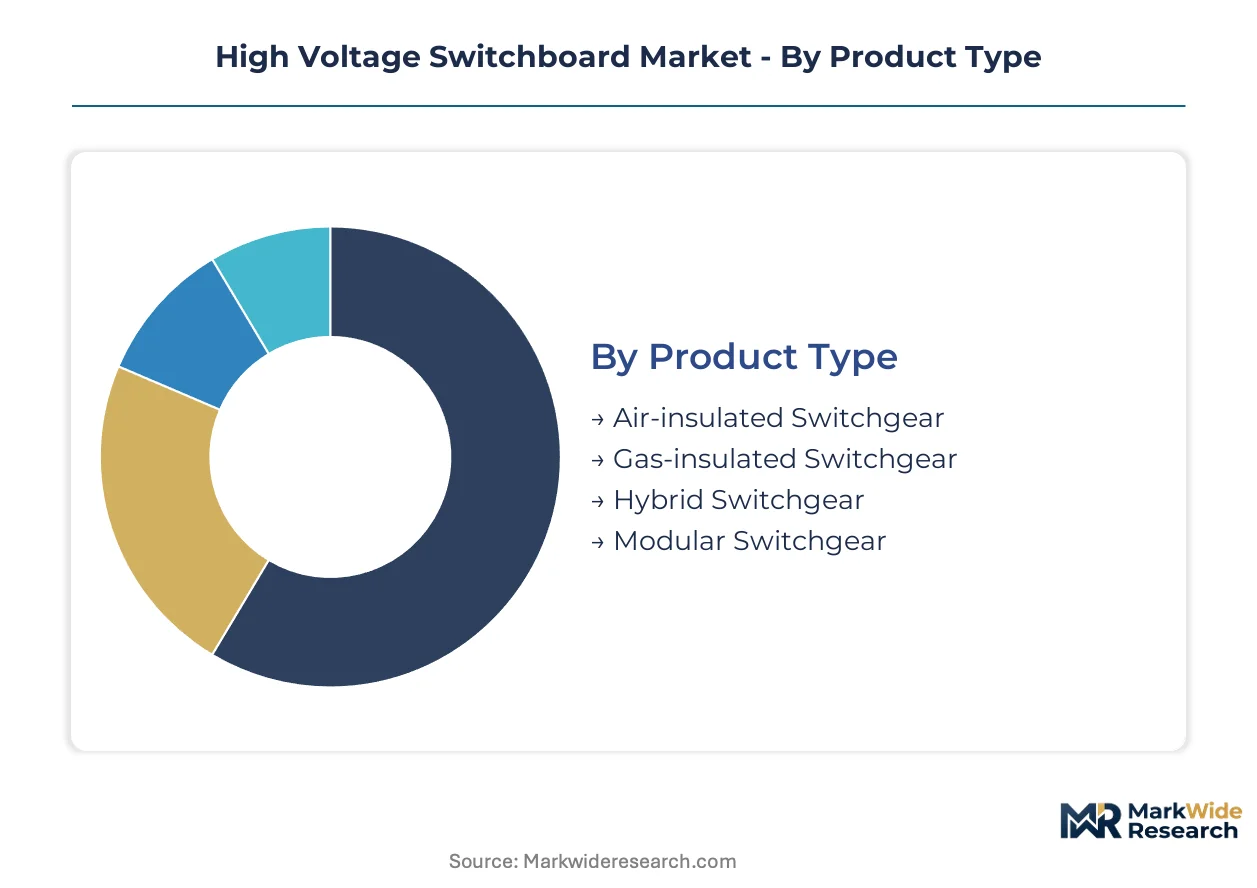
Segmentation in the high voltage switchboard market reveals how procurement priorities diverge between space-constrained urban utilities and cost-sensitive rural operators. Understanding these fault lines helps vendors calibrate product portfolios and pricing architectures to specific buyer archetypes.
Product Type:
Buyers in this category differentiate primarily by footprint constraints versus capital expenditure tolerance.
- Gas-insulated Switchgear:SF6-insulated compartments compress switchboard volume by 70 percent versus air-insulated equivalents, enabling substation placement within dense commercial districts in Jakarta and Manila. EVN in Vietnam specifies GIS for all 220 kV urban ring substations to circumvent land acquisition bottlenecks.
- Modular Switchgear:Factory-tested segments arrive as pre-wired skids that cut field commissioning from weeks to days. Philippine island utilities and Indonesian PLN regional divisions are standardizing on containerized modular units for barge-deployable microgrids.
- Air-insulated Switchgear:Open-frame designs maintain cost leadership for rural 11 kV distribution where land costs remain negligible.
- Hybrid Switchgear:Combines gas-insulated busbars with air-insulated circuit breakers to balance footprint and serviceability in mid-density zones.
Volume sits with Gas-insulated Switchgear; growth tilts toward Modular Switchgear.
Installation Type:
Site preparation requirements and labor mobility constraints shape procurement decisions here.
- Containerized:Standardized shipping-container enclosures enable rapid deployment to remote Indonesian archipelago sites without permanent civil works. PLN's outer island electrification program sources exclusively containerized 20 kV switchboards to bypass concrete foundation delays during monsoon windows.
- Prefabricated:Pre-assembled building-integrated switchrooms arrive with HVAC and fire suppression pre-installed, compressing Bangkok metropolitan project timelines by 40 percent.
- Indoor:Conventional brick-and-mortar substation construction dominates established urban grids with available real estate.
- Outdoor:Open-yard installations persist in Laos and rural Vietnam where weather protection adds unnecessary cost.
Procurement concentrates on Prefabricated solutions; containerized formats are expanding most quickly in archipelago markets.
End User:
Budget cycles and technical staffing depth create divergent buying behaviors across user categories.
- Utility:State-owned transmission operators like EVN, PLN, and the Philippine National Grid Corporation drive bulk procurement through multi-year framework agreements. These buyers prioritize IEC 62271-200 arc-flash certification and seismic qualification to minimize operational liability.
- Renewable Energy:Solar and offshore wind developers require switchboards with rapid fault-clearing capabilities to protect inverter assets. Vietnamese solar IPPs are specifying 36 kV modular units with integrated protection relays to interconnect dispersed ground-mount arrays.
- Industrial:Manufacturing campuses in Thailand's Eastern Economic Corridor demand high-availability configurations with redundant busbar arrangements.
- Commercial:Shopping mall and hospital operators prioritize compact GIS to minimize substation space within premium real estate footprints.
Utility buyers command procurement volume; renewable energy developers are gaining share fastest as grid interconnection queues lengthen.
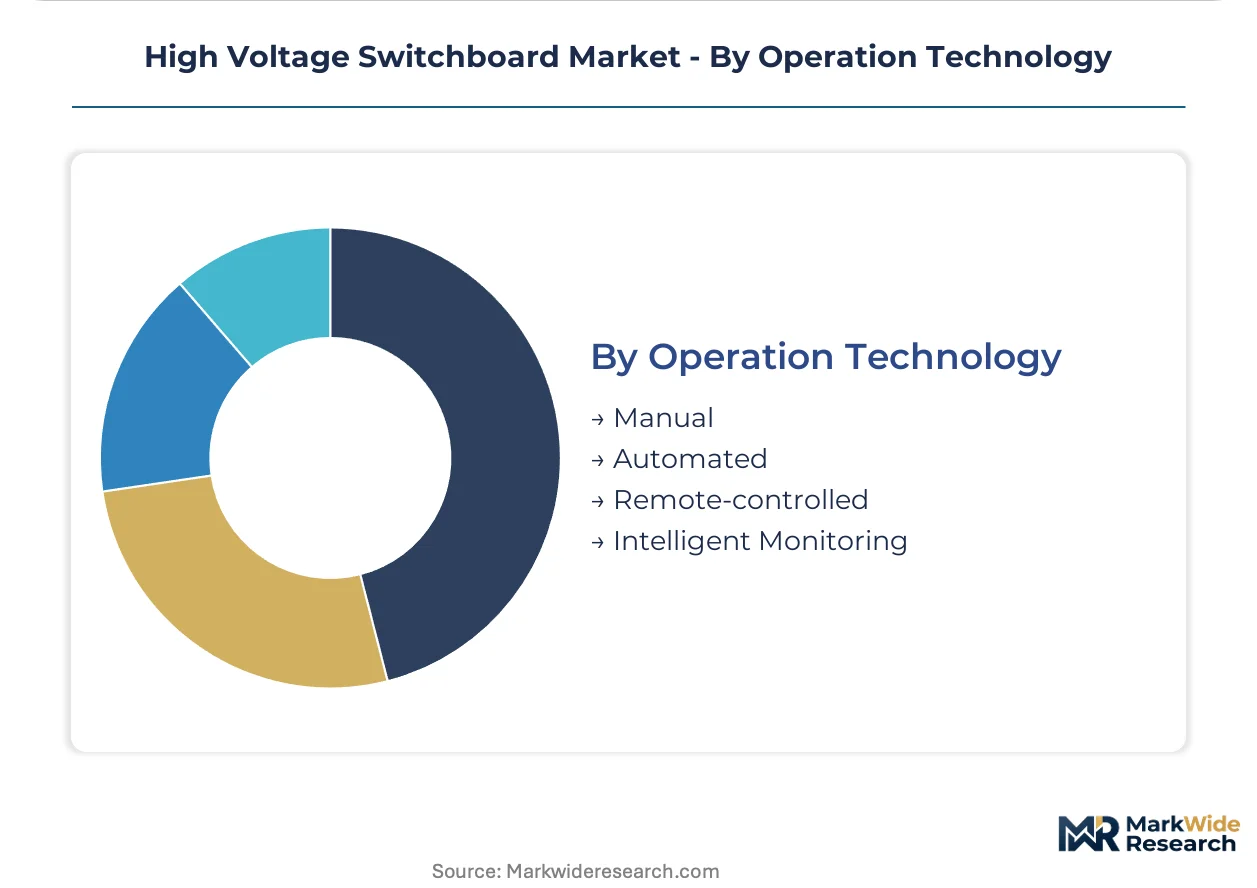
Operation Technology:
Workforce availability and grid reliability targets determine automation investment levels.
- Intelligent Monitoring:Embedded sensors track partial discharge, busbar temperature, and SF6 gas density, feeding predictive maintenance algorithms. Thailand's Provincial Electricity Authority mandates IEC 61850 protocol compliance for all new 115 kV substations, forcing Ethernet-based process bus adoption.
- Remote-controlled:SCADA-integrated switchboards enable centralized operation from regional control centers, reducing staffing requirements for Indonesian outer island installations.
- Automated:Programmable logic controllers execute pre-defined switching sequences without human intervention.
- Manual:Hand-operated mechanisms persist in legacy installations and budget-constrained rural extensions.
Manual systems retain installed base dominance; intelligent monitoring configurations are climbing the fastest as digitalization mandates propagate across ASEAN grid codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for high voltage switchboards concentrates in Southeast Asian utilities racing to interconnect renewable assets before monsoon construction windows close. Vietnam, Indonesia, and the Philippines anchor procurement volume through state-owned transmission operators.
Vietnam
EVN's 500 kV backbone expansion and Power Development Plan 8 transmission corridors drive concentrated procurement of gas-insulated switchgear for urban ring substations. The Central Electricity Authority mandates seismic qualification and tropical climate ratings for all imported equipment. Ho Chi Minh City and Hanoi metropolitan areas specify compact GIS designs to circumvent land acquisition bottlenecks in dense commercial districts.
Indonesia
PLN's 35,000 MW electrification program and outer island microgrid initiatives create dual demand streams for containerized modular switchboards. The state utility's localized content rules reroute procurement toward domestic assembly partnerships for foreign technology licensors. Java-Bali grid interconnection projects concentrate in Surabaya and Jakarta, while eastern archipelago deployments rely on barge-transportable containerized units.
Philippines
The National Grid Corporation's island grid stabilization program and dispersed solar interconnection queues accelerate switchboard procurement across 7,000-plus islands. Philippine grid codes tighten arc-flash performance requirements following IEC 62271-200 adoption. Luzon transmission corridors concentrate demand in Metro Manila, while Visayas and Mindanao deployments favor prefabricated modular configurations for rapid commissioning.
Thailand
The Provincial Electricity Authority's metropolitan ring expansion and IEC 61850 automation mandates reshape procurement specifications for 115 kV substations. Thailand's Board of Investment incentives attract GIS manufacturers establishing regional assembly hubs. Bangkok's land-scarce commercial districts specify gas-insulated switchgear to halve substation footprints, while Eastern Economic Corridor industrial zones demand redundant busbar configurations.
Malaysia
Tenaga Nasional Berhad's grid modernization program and smart substation automation roadmaps concentrate procurement in Peninsular Malaysia's industrial corridors. The Energy Commission's adoption of IEC 61850 communication protocols forces Ethernet-based process bus integration. Selangor and Johor manufacturing clusters drive demand for high-availability switchboard configurations with intelligent monitoring capabilities.
High Voltage Switchboard Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated European conglomerates commanding premium positioning in gas-insulated systems while Asian fabricators capture volume in modular and air-insulated categories. The vendor base organizes around three strategic archetypes: technology licensors leveraging deep software integration, modular architects optimizing factory-tested configurations, and regional assemblers exploiting localized content rules. Competitive intensity manifests through joint venture formations with state utilities and accelerated digital twin development for predictive maintenance revenue streams.
Among European-headquartered industrial conglomerates, Siemens AG and ABB exemplify the technology-licensor archetype through sustained positioning in gas-insulated switchgear and deep software-hardware convergence. Schneider Electric occupies a differentiated position within the modular architecture tier, emphasizing factory-tested configurations that compress on-site commissioning cycles. These three entities anchor the premium segment through compliance with tightening IEC 62271 arc-flash and seismic performance standards across Southeast Asian procurement frameworks.
| Leading Market Players |
|---|
| Siemens AG |
| ABB |
| Schneider Electric |
| Eaton Corporation |
| General Electric |
| Mitsubishi Electric |
| Hitachi Energy |
| Toshiba |
| LS Electric |
| Others |
Supply & Pricing Matrix
EVN's compressed procurement cycles for Vietnam's 500 kV backbone expansion are forcing switchboard OEMs to absorb copper price volatility through fixed-price frameworks rather than pass-through clauses, compressing margins on busbar-intensive assemblies while rewarding suppliers with captive aluminum-silver hybrid metallurgy capabilities.
Pricing Analysis
Volume concentrates in standardized GIS configurations for state utility frameworks, while margins concentrate in intelligent monitoring packages with IEC 61850 protocol integration. Three-tier pricing structure across premium certified, standard compliant, and economy domestic-assembly levels separates vendors by seismic qualification and arc-flash certification tier. Cost compression in economy-tier air-insulated switchgear is intensifying because Indonesian PLN's localized content rules favor domestic assemblers bidding below equipment cost. Renewable energy developers exhibit highest price sensitivity due to interconnection queue economics, while Thailand's Provincial Electricity Authority shows lowest sensitivity given automation mandates and reliability premiums.
Supply Chain Analysis
Dual-sourcing requirements embedded in Philippine National Grid Corporation contracts and EVN competitive bidding rules mandate qualified second sources for vacuum interrupters and cast resin insulators, fragmenting procurement across German, Swiss, and emerging Southeast Asian suppliers. Critical component manufacturing concentrates in Germany, Switzerland, and Japan for vacuum interrupters, while aluminum processing and sheet metal fabrication concentrate in China, Vietnam, and Indonesia. Raw material dependencies span copper cathodes, SF6 gas alternatives, and silver-plated aluminum extrusions. Single-source vulnerability in European vacuum interrupter supply creates qualification bottlenecks during seismic testing backlogs. Distribution runs through state utility framework agreements, EPC contractor consortia, and direct OEM relationships for critical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High voltage switchboard procurement is navigating a technology-transition phase as SF6-dependent GIS designs face compressed operational windows under EU F-Gas Regulation and parallel ASEAN draft standards, displacing legacy sulfur hexafluoride architectures with fluoronitrile and vacuum interrupter alternatives.
For Market Incumbents: Lock in backward integration into aluminum-silver hybrid busbar manufacturing to offset copper volatility exposure and defend margin position against domestic assemblers exploiting Indonesian localized content rules. Prioritize IEC 62271-200 arc-flash certification investment and seismic qualification capacity expansion at accredited Southeast Asian laboratories to capture EVN and PLN framework agreement volume. For New Entrants and Emerging Players: EPC contractor consortia represent the most penetrable channel pathway for technology licensors seeking Indonesian PLN electrification program access without full manufacturing footprint investment. Target Philippine island grid containerized modular switchboard demand where barge-deployable configurations and rapid commissioning capabilities outweigh brand heritage. Pursue joint venture structures with domestic assembly partners to satisfy localized content thresholds. For Investors and Strategic Acquirers: The window for entry favors digital twin software specialists with asset performance management platforms that can layer recurring revenue atop hardware procurement cycles. Long-term viability hinges on predictive maintenance subscription attach rates and SF6-alternative technology licensing positions. Watch for ASEAN grid code harmonization announcements as inflection indicators for qualification barrier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SF6 Alternative Technology Licensing | Fluoronitrile and vacuum interrupter patents determine market access as EU F-Gas Regulation compresses legacy GIS operational windows. |
| Domestic Assembly Joint Venture | Indonesian PLN's 35,000 MW program mandates localized content partnerships, rerouting procurement toward domestic assembly licensors. |
| IEC 61850 Protocol Integration | Thailand's Provincial Electricity Authority mandates Ethernet-based process bus architectures, forcing protection relay hardware-software convergence. |
| Seismic Qualification Capacity Expansion | IEC 62271-2 shake-table testing bottlenecks at accredited Southeast Asian laboratories delay project commissioning and gate market access. |
| Containerized Modular Configuration Development | Philippine archipelago deployments and Indonesian outer island microgrids demand barge-transportable, factory-tested switchboard skids. |
Research Methodology
Regulatory filings with the Central Electricity Authority of India, ASEAN energy ministry procurement databases, and IEC standards documentation formed the secondary backbone, cross-referenced against primary interviews with utility planning officers at EVN, PLN, and the Philippine National Grid Corporation, EPC contractor procurement leads, and switchboard OEM technical directors. Bottom-up triangulation across project pipeline databases and top-down validation through national electrification program targets anchored volume estimates.
Historical trendline analysis of transmission substation commissioning rates, renewable energy interconnection queue lengths, and copper-aluminum price ratio movements informed the analytical framework across the projection horizon. Segmentation dimensions modeled include insulation technology, installation format, end-user category, and automation protocol tier. CAGRs derived from utility capital expenditure forecasts and grid modernization program timelines, with specific inputs from Vietnam Power Development Plan 8 corridor buildout schedules and Indonesian PLN 35,000 MW capacity addition phasing.
Caveats apply where ASEAN grid code harmonization delays, SF6 phase-down timeline acceleration, or copper price volatility spikes exceeding historical bands could materially shift the outlook. Forecasts reflect assumptions around state utility procurement continuity and seismic laboratory capacity expansion. A model refresh is warranted upon material change in IEC 62271-200 adoption timelines or ASEAN F-Gas regulation finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Middle East and Africa Busbar Market