
 Global Precision Resistor Market | 2026-2036
Global Precision Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Resistor Market Outlook
Buyer concentration in automotive electronics is consolidating around tier-one suppliers serving electrified drivetrain programs. Vishay Intertechnology leverages its foil resistor expertise to anchor high-reliability contracts with European and North American OEM qualification systems. Murata Manufacturing sustains dominant surface-mount capacity in Japanese facilities, while Yageo Corporation competes aggressively on thick-film cost structures for consumer-facing volume programs.
A precision resistor maintains exact electrical resistance within tight tolerance bands, typically manufactured through vacuum-deposited thin film, fired thick-film paste, or drawn wirewound construction to serve measurement, calibration, and current-sensing functions in circuits demanding stability across temperature extremes. Thin film variants command premium positioning in aerospace signal conditioning and instrumentation loops where drift specifications below 25 ppm define contract eligibility. Wirewound architectures retain structural importance in power supply and load board applications where thermal dissipation requirements exceed thin-film thermal limits, while thick-film products occupy economy tiers in consumer electronics volume procurement.
RoHS and REACH frameworks in Europe restrict cadmium and lead content in resistor terminations and glaze coatings, compelling reformulation of thick-film paste chemistries across supplier bases. FDA oversight of medical device electronics and FAA airworthiness directives for avionics systems impose traceable calibration protocols that elevate precision resistor specifications in qualified component lists. Stakeholders must monitor evolving automotive functional-safety standards and material-compliance deadlines to preserve qualification status across diverging regional regulatory calendars.
Market Dynamics
Automotive electrification programs in Germany, Japan, and the United States are compressing tolerance specifications for resistive components while consolidating procurement authority around tier-one drivetrain suppliers capable of meeting ISO 26262 functional-safety requirements.
Growth Catalysts
- Battery Management Systems:Electric vehicle platforms require precision current-sensing resistors for cell balancing and state-of-charge algorithms, with automotive OEMs mandating drift specifications below 50 ppm across operating temperature ranges.
- RoHS and REACH:European material-compliance deadlines are accelerating reformulation of thick-film paste chemistries, creating replacement demand for qualified components in industrial and medical equipment refresh cycles.
- Thin Film Deposition:Vacuum sputtering processes now achieve sub-25 ppm temperature coefficients, enabling aerospace signal conditioning applications that wirewound architectures cannot physically satisfy.
Market Restraints
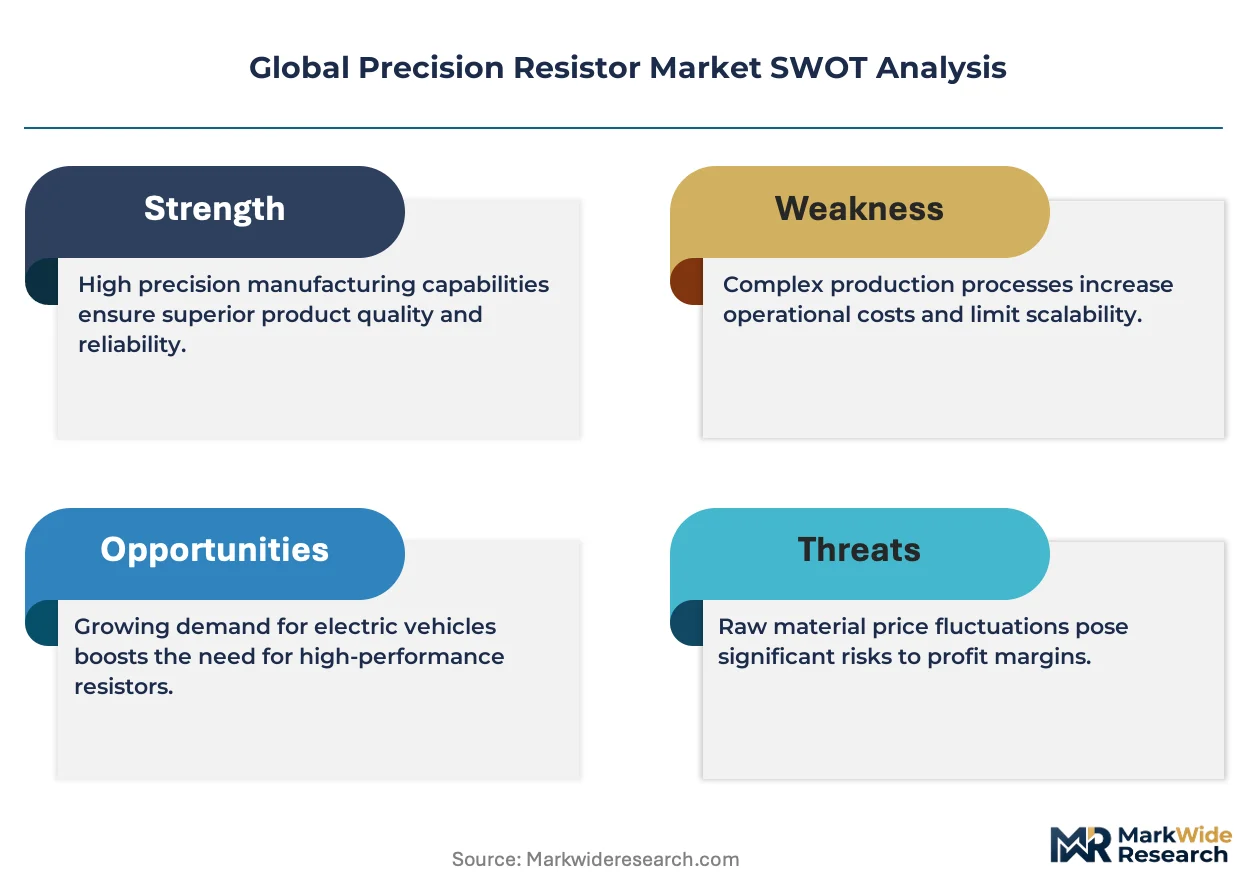
- Palladium Price Volatility:Thick-film termination metallization depends on palladium-silver alloys, with spot price swings above 30% annually compressing margin structures for economy-tier suppliers.
- East Asian Supply Concentration:South Korean and Japanese fabricators control 70% of automotive-qualified thin-film capacity, exposing procurement programs to single-source risk during regional disruption events.
- Thermal Dissipation Ceiling:Thin-film architectures face hard power-handling limits below 2 watts, forcing power supply designers to retain bulkier wirewound alternatives in high-current paths.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting precision resistor assembly investments to serve domestic automotive and telecom equipment demand.
- Onboard Charging Modules:800-volt drivetrain architectures require isolated current-sensing resistors with reinforced insulation ratings, opening premium positioning for foil and metal-strip specialists.
- EU Green Deal:Circular economy mandates for electronics recyclability are favoring designs with lead-free terminations and ceramic substrates that align with existing precision resistor material sets.
Industry Challenges
- ISO 17025 Calibration Traceability:Medical device and avionics contracts require accredited measurement chains extending to national metrology institutes, with audit preparation consuming 12-18 months for new supplier qualification.
- Legacy System Integration:Industrial automation retrofit projects demand pin-compatible replacements for obsolete through-hole resistors, forcing manufacturers to maintain dual-format production lines with divergent automation economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Resistor Market |
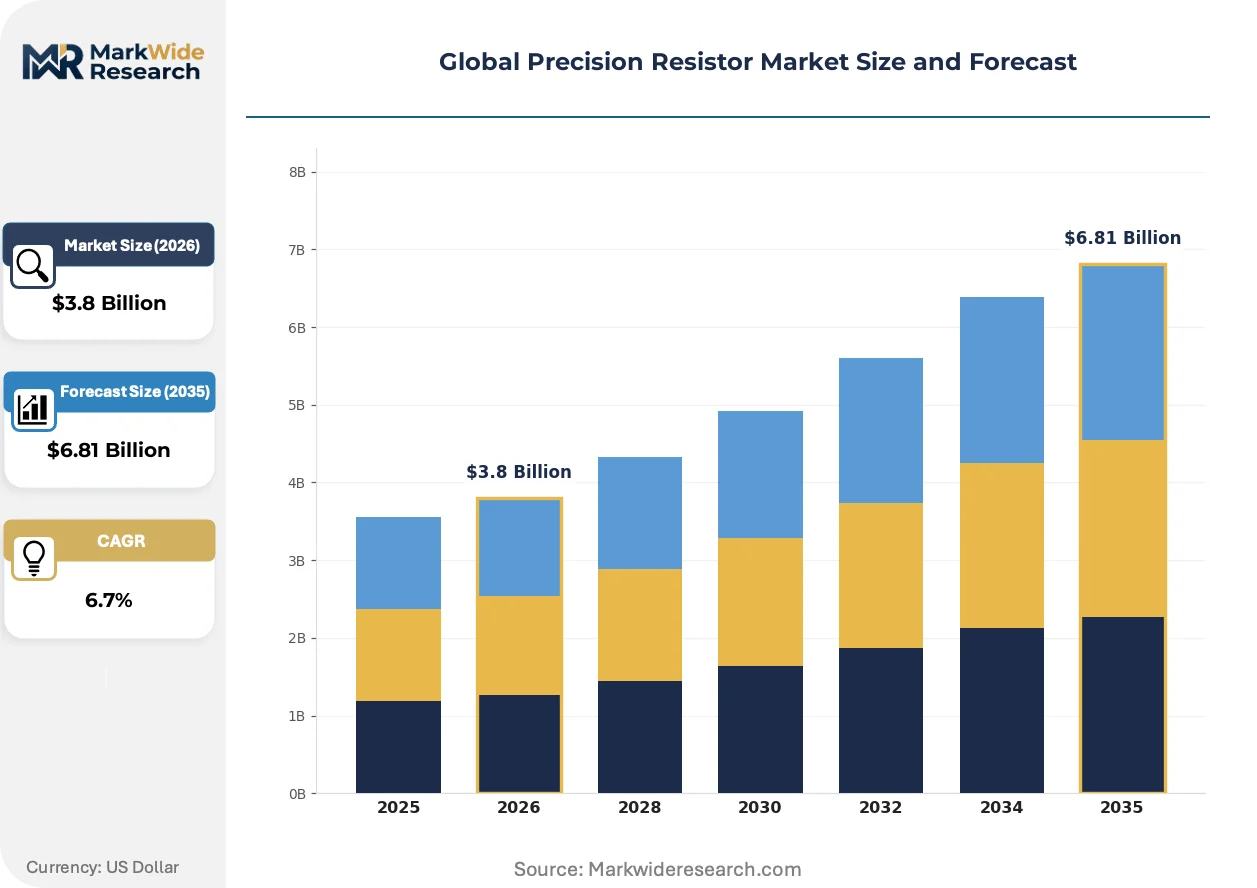
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Thick Film, Wirewound, Foil End User: Consumer Electronics, Automotive, Telecommunications, Aerospace Technology: Surface Mount Technology, Through-Hole Technology, Digital, Analog Application: Data Acquisition, Signal Conditioning, Load Boards, Power Supplies |
| Companies Covered | Vishay Intertechnology, Murata Manufacturing, Yageo Corporation, TDK Corporation, TE Connectivity, Panasonic Corporation, KOA Speer Electronics, Samsung Electro-Mechanics, Bourns Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Resistor Market Strategic Shifts
Material science advances in ceramic substrate formulations and deposition control systems are compressing the performance gap between premium thin-film and economy thick-film architectures. Three developments are restructuring competitive positioning.
Atomic layer deposition of nickel-chromium alloys is rewriting precision resistor manufacturing by enabling sub-10 nanometer film thickness control. Aerospace instrumentation contractors in the United States and Germany are qualifying these components for satellite power distribution units. The technology is compressing lead times for custom resistance values while eliminating wirewound inventory carrying costs.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are compelling reformulation of cleanroom etching chemistries used in thin-film patterning. German and French fabrication facilities are retrofitting abatement systems to capture process emissions. Medical device manufacturers sourcing from European-qualified suppliers face extended certification timelines as suppliers validate alternative chemistries.
Consolidated procurement desks at tier-one automotive electronics contractors are unbundling component supply from module assembly contracts. Korean and Japanese vehicle programs now specify resistor families rather than approved manufacturer lists, forcing suppliers to compete on parametric data rather than historical relationships. This behavior is most visible in battery management system sourcing for platforms launching from 2027.
Global Precision Resistor Market Segmentation
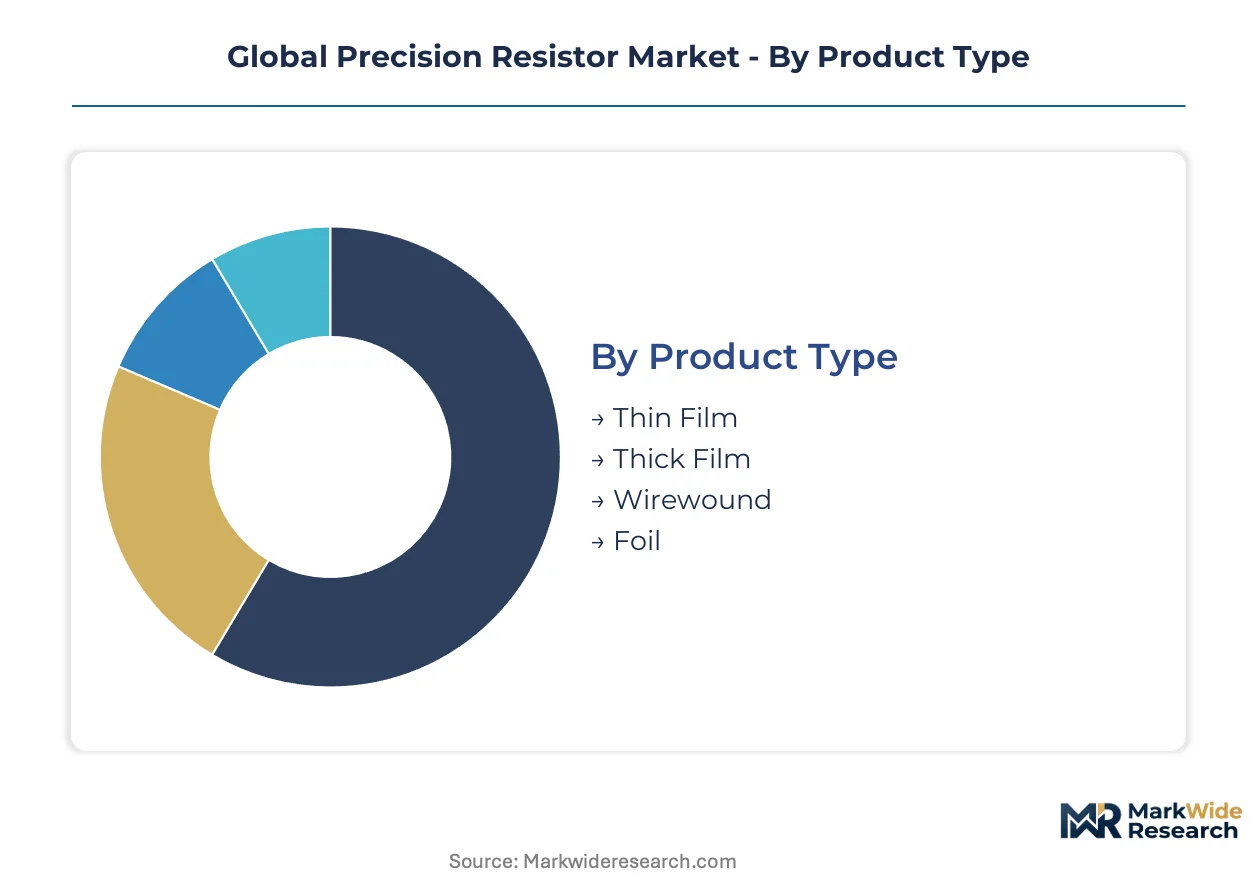
Precision resistor procurement splits sharply between standalone measurement-grade components and embedded systems where resistors serve as sensing elements within larger modules. Understanding these integration patterns reveals why automotive and aerospace buyers maintain parallel qualification tracks for identical resistance values.
Product Type:
Integration depth varies dramatically across construction methods, with foil and wirewound architectures dominating standalone instrumentation while thin film penetrates densely populated circuit boards.
- Thin Film:Vacuum-deposited nickel-chromium or tantalum nitride layers on ceramic substrates achieve temperature coefficients below 25 ppm. Battery management systems in German and Japanese electric vehicle programs specify these for current sensing where drift tolerance is tightest.
- Thick Film:Fired ruthenium oxide pastes on alumina provide economical resistance in consumer volume applications. Palladium-silver termination costs have compressed margins for suppliers serving industrial automation refresh cycles.
- Wirewound:Precision-drawn resistance wire on ceramic cores handles power dissipation above 2 watts in load board and power supply applications where thin film thermal limits fail.
- Foil:Bulk metal foil construction delivers sub-5 ppm stability for met-grade instrumentation in avionics and medical device calibration chains requiring ISO 17025 traceability.
Thick film leads volumes today; thin film is gaining share fastest.
End User:
Cost tier stratification separates qualification-intensive automotive and aerospace procurement from price-sensitive consumer electronics volume programs.
- Automotive:ISO 26262 functional-safety mandates drive 50 ppm drift specifications for battery management and onboard charging modules. Tier-one drivetrain suppliers in South Korea and Japan consolidate procurement authority around qualified thin-film families.
- Aerospace:FAA airworthiness directives and EASA certification protocols impose traceable calibration requirements. Foil resistors anchor signal conditioning loops in satellite power distribution units where atomic layer deposition is displacing wirewound alternatives.
- Consumer Electronics:Thick-film surface-mount devices serve smartphone and wearable volume demand with tolerance bands relaxed to 1% or wider.
- Telecommunications:Base station power amplifiers and optical transceivers require precision current sensing in 5G infrastructure deployments across German and US markets.
Consumer electronics leads volumes today; automotive is climbing the fastest.
Technology:
Manufacturing process selection tracks customer automation economics, with surface mount dominating new designs and through-hole persisting in legacy industrial retrofit obligations.
- Surface Mount Technology:Tape-and-reel packaging enables high-speed pick-and-place assembly in Korean and Japanese automotive electronics facilities. Murata Manufacturing maintains dominant capacity in precision thin-film chip resistor formats.
- Through-Hole Technology:Axial-lead construction persists in industrial automation retrofit projects demanding pin-compatible replacements for obsolete designs. Dual-format production lines strain automation economics for mid-tier suppliers.
- Digital:Integrated resistor networks with digital trimming capabilities serve data acquisition systems requiring in-circuit calibration adjustment.
- Analog:Passive discrete components dominate precision signal paths where digital noise injection is unacceptable.
Surface mount leads volumes today; digital is expanding most quickly.
Application:
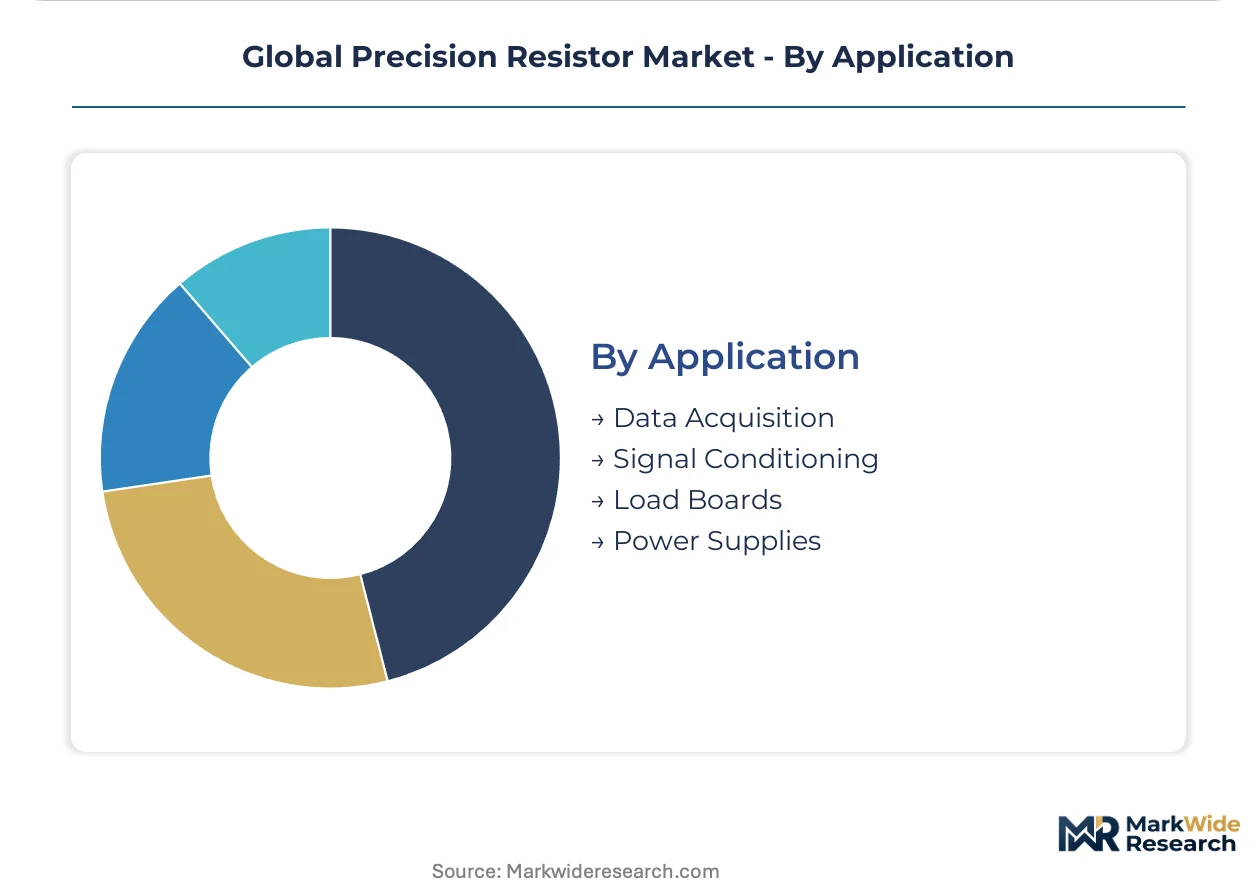
Performance requirements harden progressively from power supply bulk applications through signal conditioning to metrology-grade data acquisition.
- Signal Conditioning:Instrumentation amplifiers and sensor front-ends demand matched resistor pairs with tracking coefficients below 5 ppm. Aerospace contractors in Germany and the United States specify atomic layer deposition components for satellite systems.
- Data Acquisition:Multimeter and calibration equipment reference dividers require foil or metal foil construction with annual drift below 10 ppm. FDA oversight of medical device electronics elevates precision specifications in qualified component lists.
- Power Supplies:Current sensing and voltage feedback loops tolerate wider tolerances in switch-mode designs where thermal dissipation dominates selection criteria.
- Load Boards:Semiconductor test equipment employs wirewound power resistors for burn-in and characterization applications.
Power supplies lead volumes today; signal conditioning shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision resistor engineering talent clusters in German automotive electronics hubs, Japanese ceramic fabrication centers, and South Korean semiconductor packaging corridors. These concentrations anchor qualification-intensive supply chains for electrified drivetrain and aerospace instrumentation programs.
United States
Automotive electrification in Detroit and Silicon Valley accelerates demand for ISO 26262-qualified current-sensing components. FAA airworthiness directives impose traceable calibration protocols on avionics suppliers in Seattle and Wichita. Boston-area medical device manufacturers source foil resistors for FDA-regulated diagnostic equipment.
Germany
Battery management system procurement for BMW and Volkswagen platforms concentrates in Bavaria and Baden-Württemberg. EU F-Gas Regulation restrictions compel Stuttgart-area cleanroom facilities to retrofit abatement systems for thin-film etching processes. Dresden's semiconductor cluster attracts precision resistor assembly investments serving automotive tier-one contractors.
Japan
Murata Manufacturing maintains dominant surface-mount thin-film capacity in Kyoto and Nagaokakyo facilities. METI industrial standards govern precision component specifications for Toyota and Honda electrification programs. Nagoya-area automotive electronics contractors consolidate procurement authority around qualified resistor families.
South Korea
Hyundai and Kia drivetrain electrification drives demand for 50 ppm drift specification resistors in Seoul and Ulsan manufacturing corridors. Samsung Electro-Mechanics anchors domestic precision component supply for 5G base station deployments. Gyeonggi Province packaging facilities serve tier-one automotive electronics contractors with tape-and-reel surface-mount formats.
India
PLI scheme incentives for semiconductor packaging attract precision resistor assembly to Gujarat and Karnataka. Domestic automotive and telecom equipment demand accelerates local procurement of thick-film and wirewound components. Tamil Nadu electronics manufacturing zones develop captive resistor supply for industrial automation retrofit cycles.
Global Precision Resistor Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Premium positioning concentrates among foil and thin-film experts serving aerospace and medical calibration chains. Mid-tier suppliers balance automotive qualification costs against thick-film volume economics. Economy-tier fabricators compete on palladium-silver paste efficiency for consumer electronics procurement. Consolidation pressures favor scale-driven M&A and geographic expansion into Indian PLI-subsidized corridors.
Within the diversified electronics conglomerate tier, Vishay Intertechnology and TDK Corporation occupy positions spanning multiple resistor construction methods. Murata Manufacturing exemplifies the focused pure-play archetype with concentrated surface-mount thin-film expertise. TE Connectivity represents the connectivity-integrated approach, bundling precision resistive sensing with interconnect systems for automotive and industrial automation customers.
| Leading Market Players |
|---|
| Vishay Intertechnology |
| Murata Manufacturing |
| Yageo Corporation |
| TDK Corporation |
| TE Connectivity |
| Panasonic Corporation |
| KOA Speer Electronics |
| Samsung Electro-Mechanics |
| Bourns Inc. |
| Others |
Value Chain & Pricing Dynamics
Atomic layer deposition adoption in aerospace-qualified resistor manufacturing simultaneously compresses unit economics for sub-25 ppm components and concentrates production capacity among German and United States facilities capable of vacuum sputtering at nanometer-scale precision. This process transition rewards scale while penalizing mid-tier suppliers dependent on legacy wirewound inventories, restructuring how procurement desks negotiate long-term supply agreements.
Pricing Analysis
Module assembly unbundling from component supply is restructuring contract structures across automotive electronics procurement. Three-tier pricing structure across ISO 26262-certified premium, industrial-standard, and consumer-economy levels separates drift specification bands. Pricing pressure stems from palladium-silver alloy volatility in thick-film terminations, with Korean and Japanese tier-one contractors least sensitive to unit cost and Indian PLI-scheme entrants most price-responsive.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Kyoto, and Seoul anchor hub-and-spoke patterns for automotive-qualified thin-film components. Manufacturing concentrates in Japan, South Korea, and Germany for deposition-controlled ceramic substrates. Supply chains draw from ruthenium oxide paste, nickel-chromium sputtering targets, and alumina ceramic cores. Single-source vulnerability in South Korean packaging corridors threatens continuity during regional disruption events. Distribution runs through tape-and-reel formats serving high-speed pick-and-place assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision resistor demand functions as a regulatory compounder where EU F-Gas Regulation deadlines and ISO 26262 functional-safety mandates simultaneously tighten specifications and extend qualification timelines, rewarding prepared suppliers with multi-year contract lock-in.
For Market Incumbents: Cement foil resistor expertise in FAA-regulated avionics and FDA-medical device calibration chains against atomic layer deposition substitution threats. Expand captive thin-film capacity in German cleanroom facilities to capture BMW and Volkswagen battery management system procurement. Defend automotive qualification status through ISO 17025 traceability investments that new entrants cannot replicate within audit preparation windows.
For New Entrants and Emerging Players: Tier-two automotive electronics contractors in India offer the most penetrable entry path for thick-film and wirewound volume supply. Target Gujarat and Karnataka PLI-subsidized packaging corridors where domestic automotive and telecom equipment demand outpaces qualified local capacity. Lead with pin-compatible through-hole replacements for industrial automation retrofit cycles that strain legacy suppliers' dual-format production economics.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier thick-film specialists squeezed between palladium cost volatility and automotive qualification barriers. Five-to-ten year viability hinges on successful navigation of material-compliance deadlines and functional-safety certification investments. Monitor EU F-Gas Regulation abatement system deployment timelines as inflection indicator for European-qualified supplier margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Scale-Up | Nickel-chromium sub-10 nanometer control enables satellite power distribution unit contracts with German aerospace contractors. |
| ISO 17025 Accreditation Investment | Traceable calibration chains to national metrology institutes unlock FDA-regulated medical device and FAA-avionics procurement. |
| Backward Integration into Ceramic Substrates | Captive alumina supply insulates margin structures from raw material volatility in thick-film paste formulations. |
| Indian PLI Corridor Expansion | Gujarat and Karnataka assembly investments capture domestic automotive electronics demand from Hyundai and Kia programs. |
| F-Gas Abatement System Retrofit | Etching chemistry capture systems preserve European qualification status under EU regulatory deadlines. |
Study Parameters
Multiple input streams — primary interviews with tier-one automotive procurement managers, precision resistor manufacturing engineers, and aerospace instrumentation contractors; secondary validation through SEC filings, METI industrial standards documentation, and EU regulatory filings; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured qualification timeline dynamics and unbundling procurement behaviors. Secondary sources included RoHS and REACH compliance databases, FAA airworthiness directives, and ISO 26262 certification registries.
Data-stream reconciliation anchored volume and value outputs across construction method, end-use industry, integration technology, and geographic production cluster dimensions. Modeled CAGRs derived from segment-level growth rate synthesis against macroeconomic drivers. Forecast inputs incorporated automotive electrification program timelines, material-compliance deadline schedules, and deposition technology adoption curves without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palladium price volatility, regional disruption events in East Asian manufacturing corridors, and regulatory calendar shifts. Outputs reflect documented assumptions around electrification penetration rates and qualification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market