
 Seamless Stainless Steel Products Market | 2026-2036
Seamless Stainless Steel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Seamless Stainless Steel Products Market Analytics
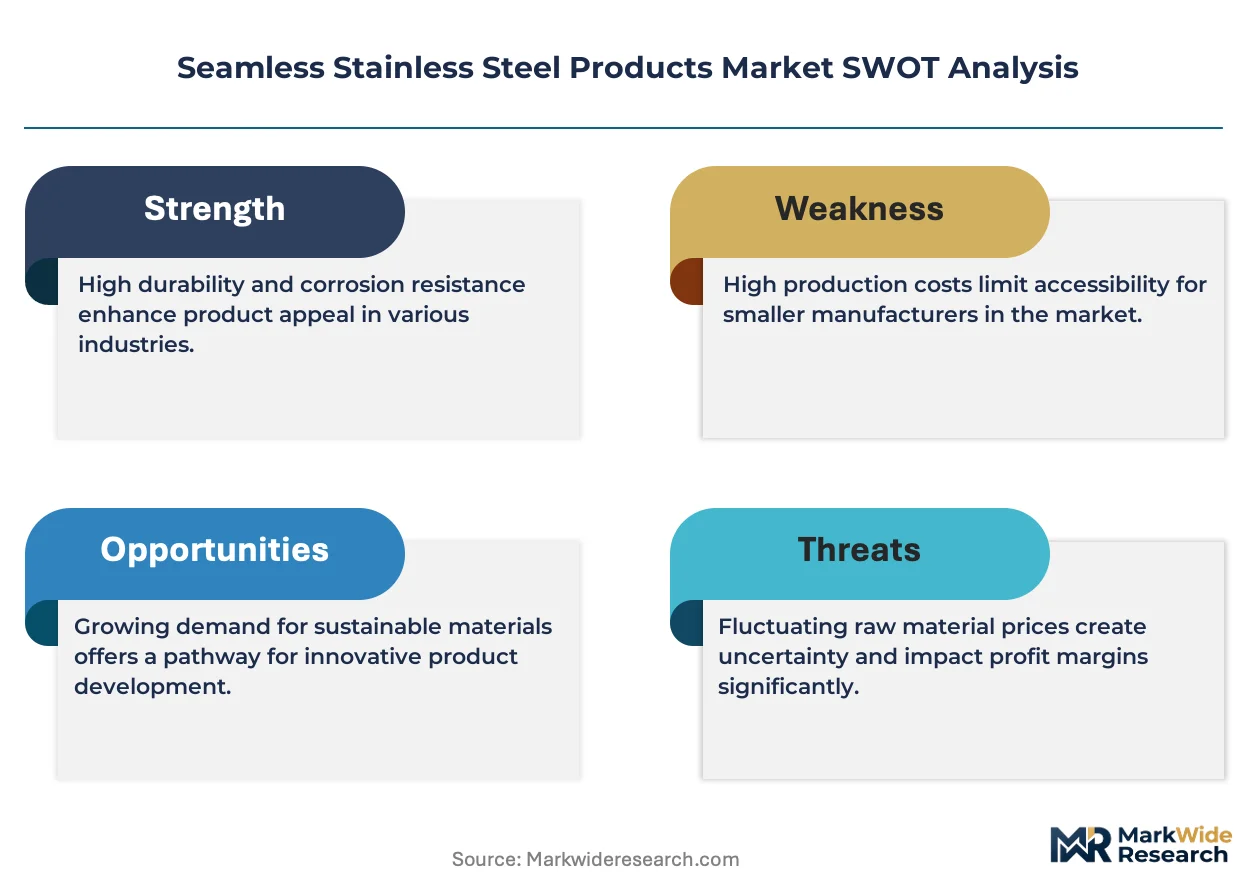
The EU Green Deal is consolidating demand around low-carbon stainless grades across European energy infrastructure. Nippon Steel Corporation leverages integrated blast furnace-to-rolling capabilities to supply nuclear-grade seamless tubing. Alleima specializes in advanced alloy compositions for medical and aerospace applications with exacting purity standards.
Seamless stainless steel products are hollow or solid long products manufactured from billets via hot extrusion or rotary piercing, without longitudinal welds, typically conforming to ASTM A312 or EN 10216 standards for pressure integrity and corrosion resistance. Their primary purpose is to transport aggressive fluids, contain high-pressure gases, or provide structural support in environments where welded joints would compromise fatigue life or hygienic performance. Pipes and tubes dominate volume shipments, while fittings command premium margins due to complex forging requirements and lower production volumes. Aerospace applications represent the fastest-growing end-user segment, driven by jet engine exhaust systems and hydraulic lines requiring thin-wall, high-strength seamless configurations.
The EPA enforces emissions limits that favor durable stainless systems in US refineries, while REACH and the EU F-Gas Regulation restrict hazardous substances in European supply chains, compelling mills to certify full material composition traceability. China's GB standards and MEE environmental inspections similarly tighten production allowances for energy-intensive seamless mills. Stakeholders must track evolving carbon-border adjustment mechanisms and alloy scrap availability before committing to capacity expansion or long-term supply agreements.
Market Dynamics
The EU F-Gas Regulation and China's dual carbon goals are compressing demand into low-leakage, corrosion-resistant seamless systems while simultaneously restricting production allowances at energy-intensive mills.
Growth Catalysts
- EU Green Deal:European energy infrastructure mandates are consolidating procurement around low-carbon stainless grades with full material traceability.
- Petrochemical capacity expansion:China's MEE environmental inspections are accelerating replacement of welded piping in coastal refineries with seamless alternatives.
- Rotary piercing automation:Hot extrusion process refinements are reducing wall-thickness variation, enabling thinner-wall aerospace configurations without yield loss.
Market Restraints
- Nickel price volatility:LME nickel contract swings above $25,000 per tonne are compressing margins at alloy-integrated mills unable to pass through raw material costs.
- Supply concentration in China:GB-certified large-diameter pipe production concentrates in Shandong and Jiangsu provinces, creating single-source risk for nuclear project timelines.
- Technical limitation in ultra-thin walls:Below 0.5mm wall thickness, rotary piercing yields inconsistent grain structure, forcing reliance on cold-drawing with 40% scrap rates.
Strategic Opportunities
- India's nuclear pipeline:CEA licensing of twelve new reactor units creates demand for ASME Section III-certified seamless tubing currently supplied by limited qualified vendors.
- Hydrogen transport infrastructure:High-pressure hydrogen embrittlement resistance requirements are opening specification windows for advanced duplex grades in German pipeline projects.
- Digital alloy certification:Blockchain-anchored mill test certificates are emerging as a procurement differentiator for European medical device OEMs facing MDR traceability mandates.
Industry Challenges
- Non-destructive testing capacity:Eddy current and ultrasonic inspection bottlenecks at third-party facilities are extending lead times for nuclear-grade certification.
- Skilled roller operator shortage:Piercing mill setup expertise concentrated among retiring workforces in Japan and Germany limits greenfield mill commissioning speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seamless Stainless Steel Products Market |
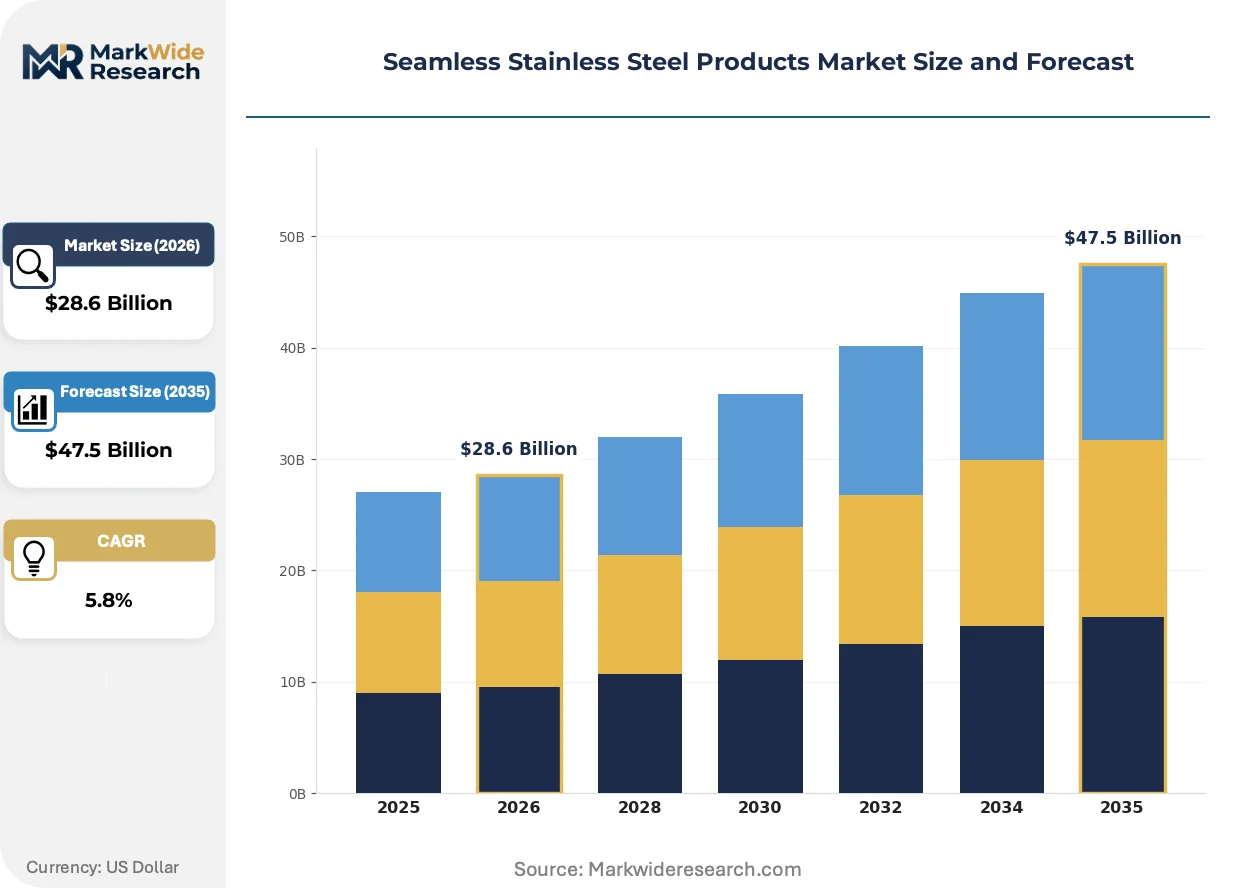
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipes, Tubes, Fittings, Flanges End User: Oil & Gas, Chemical Processing, Food & Beverage, Aerospace Application: Structural, Pressure Vessels, Heat Exchangers, Boilers Form: Round, Square, Rectangular, Oval |
| Companies Covered | Nippon Steel Corporation, Alleima, Vallourec, JFE Steel Corporation, Tubacex, Sandvik, Tenaris, Centravis, Jiuli Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seamless Stainless Steel Products Market Evolving Landscape
Seamless stainless production is bifurcating between commodity scale and precision specialization, with digital quality assurance and alloy innovation reshaping competitive differentiation.
Cold pilgering with in-line laser gauging is modularizing quality control by embedding dimensional verification directly into the forming sequence. Aerospace hydraulic line manufacturers are adopting these integrated systems to eliminate post-process inspection batches. The technology is compressing lead times from melt to ship for thin-wall tubing below 6mm outer diameter.
REACH substance restriction updates are forcing alloy substitution away from hexavalent chromium surface treatments in European medical device supply chains. Mills must now certify passivation chemistries against SVHC candidate lists before shipment. The F-Gas Regulation's service-life extension mandates are amplifying this shift in HVAC-R heat exchanger applications.
Japanese automotive OEMs are unbundling after-sales tubing inventory from original equipment contracts, shifting toward consignment stocking at Tier-1 brake line suppliers. This consumption-pattern change transfers working capital burden downstream while locking in volume commitments. METI supply chain resilience guidelines are accelerating similar arrangements in South Korean shipbuilding.
Seamless Stainless Steel Products Market Segmentation
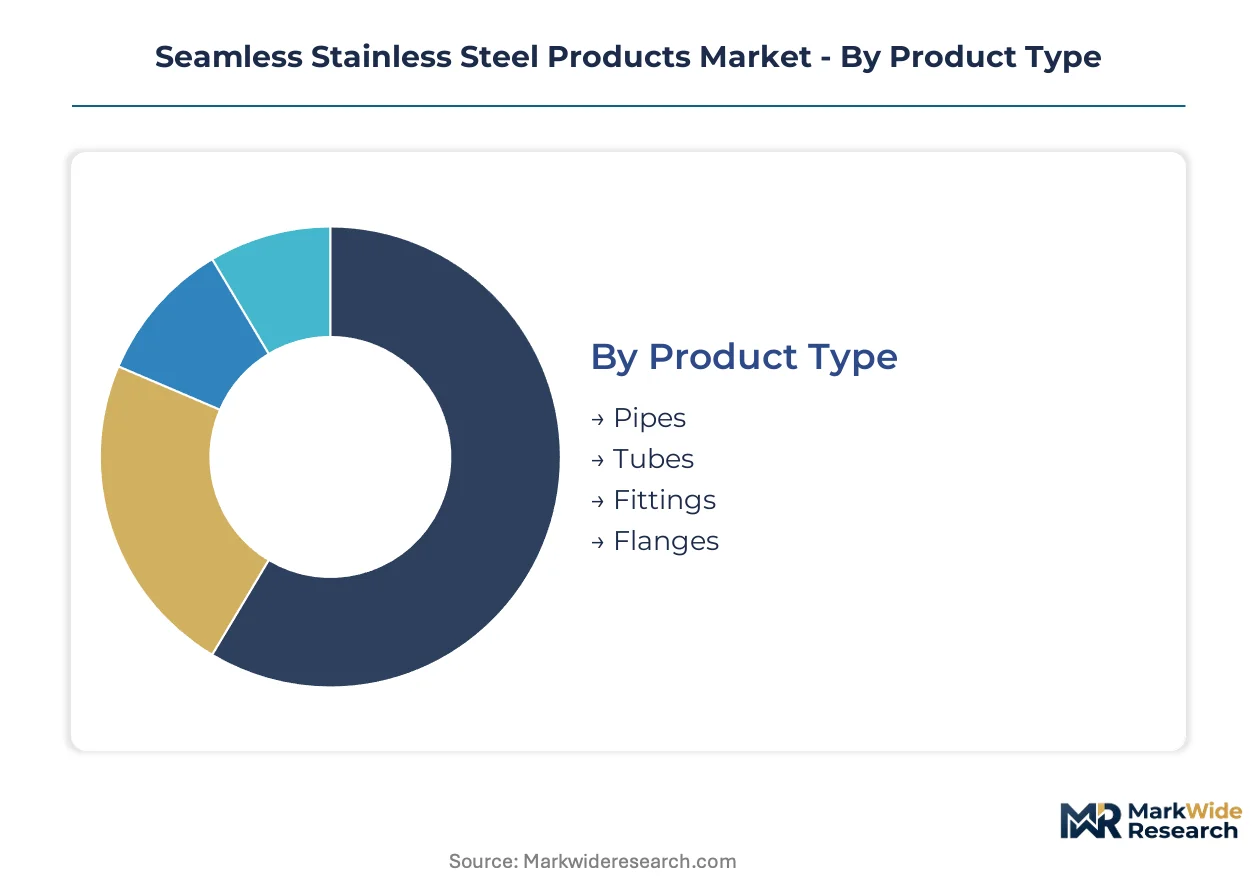
Seamless stainless steel products serve radically different performance requirements across pressure containment, hygienic transport, and structural applications. Certification burdens and alloy specifications fragment procurement patterns, with nuclear and medical end-users imposing traceability standards that commodity segments rarely require.
Product Type:
ASTM A312 and EN 10216 certifications dominate pressure-service segments, while ASME Section III nuclear qualifications restrict qualified supplier pools for specialized tubing.
- Pipes:Large-diameter seamless pipe manufactured via rotary piercing serves petrochemical and nuclear power infrastructure. Demand concentrates in China where MEE environmental inspections are accelerating replacement of welded alternatives in coastal refineries.
- Tubes:Thin-wall configurations produced through cold pilgering with in-line laser gauging meet aerospace hydraulic line specifications. Aerospace OEMs are adopting these integrated quality systems to eliminate post-process inspection batches and compress lead times.
- Fittings:Complex forged geometries command premium margins due to lower production volumes and exacting dimensional tolerances.
- Flanges:Standardized connection components serve pressure vessel and pipeline applications with moderate certification overhead.
Pipes sit at the top of the volume ranking, with tubes climbing the fastest.
End User:
Regulatory intensity varies sharply across end-use segments, with nuclear and aerospace imposing material traceability requirements that oil and gas procurement rarely matches.
- Oil & Gas:Offshore platform risers and subsea flowlines require sour-service resistant grades meeting NACE MR0175 specifications. Gulf Coast chemical processing expansions are driving orders for corrosion-resistant tubing in this segment.
- Chemical Processing:Aggressive fluid transport demands duplex and super-austenitic grades with PREN values above 40. The EU F-Gas Regulation's service-life extension mandates are consolidating procurement around low-leakage seamless systems in European chlor-alkali plants.
- Food & Beverage:Hygienic surface finish requirements per 3A sanitary standards restrict supplier qualification to mills with dedicated bright annealing capacity.
- Aerospace:Jet engine exhaust systems and hydraulic lines require thin-wall, high-strength configurations with full material pedigree documentation. This segment is expanding most quickly as OEMs unbundle after-sales tubing inventory toward consignment stocking arrangements.
Oil & Gas maintains the largest installed base, though aerospace is gaining share fastest on unit value expansion.
Application:
Pressure integrity requirements stratify alloy selection, with boiler and pressure vessel applications demanding full mill test certificate traceability that structural uses often waive.
- Structural:Architectural and mechanical support applications utilize standard austenitic grades with moderate wall thickness tolerances.
- Pressure Vessels:ASME VIII-compliant fabrication requires seamless hollows with documented chemical composition and mechanical testing. German hydrogen transport infrastructure projects are opening specification windows for advanced duplex grades in high-pressure containment roles.
- Heat Exchangers:HVAC-R applications face REACH substance restrictions on hexavalent chromium surface treatments, forcing passivation chemistry certification against SVHC candidate lists.
- Boilers:High-temperature steam service mandates specific grade selections per ASME Section II material specifications.
Pressure vessels command the highest certification burden per ton, with heat exchangers showing the steepest specification tightening trajectory.
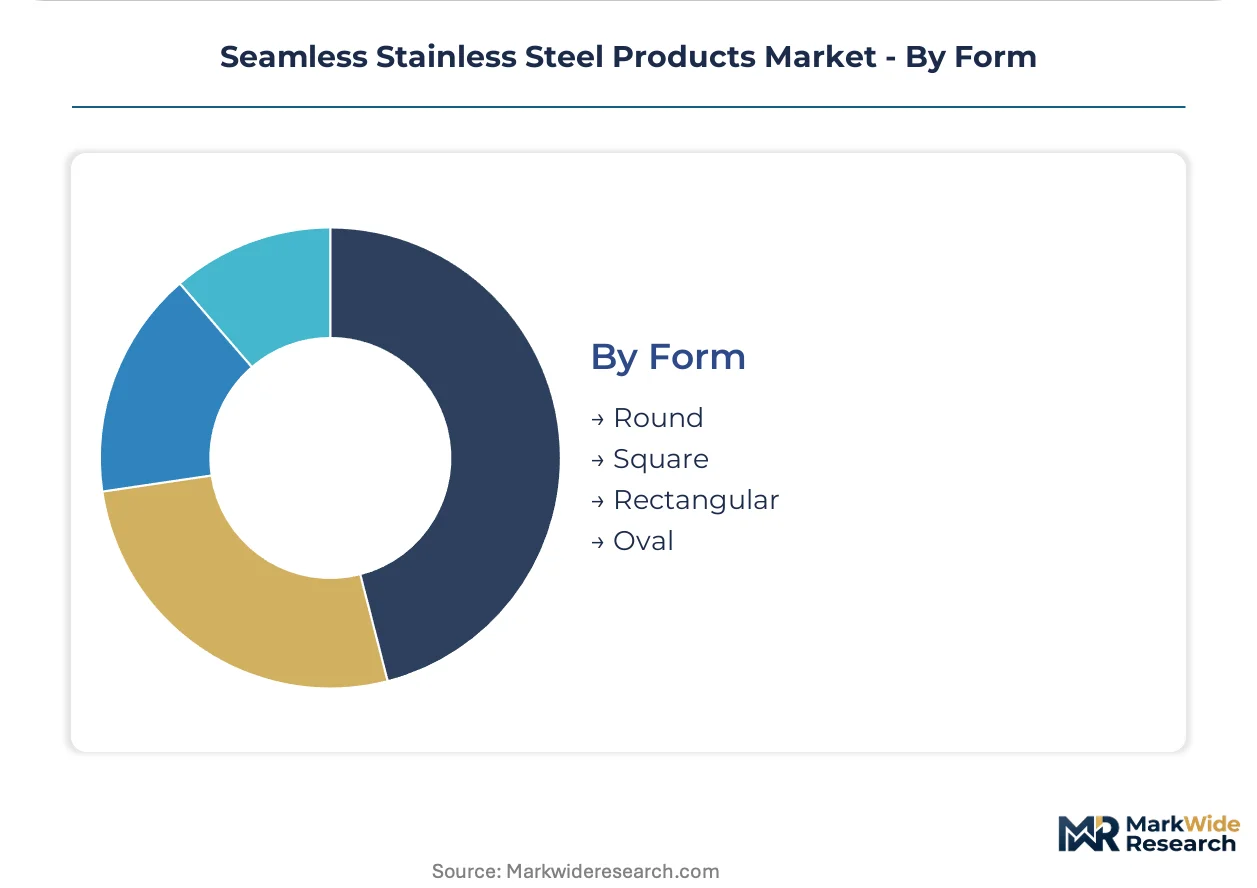
Form:
Geometric complexity drives manufacturing method selection, with non-circular cross-sections requiring specialized die sets that constrain supplier flexibility.
- Round:Dominant geometry serving fluid transport and pressure containment across all end-use segments.
- Square:Architectural and structural framing applications utilize these profiles for aesthetic and assembly efficiency.
- Rectangular:Heat exchanger tube bundles and mechanical housings specify these forms for space-optimized designs.
- Oval:Specialized automotive exhaust and aerospace ducting applications require these low-volume configurations with dedicated tooling investments.
Round forms absorb the majority of melt tonnage, while rectangular profiles are penetrating fastest into compact heat exchange designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized roller operators in Japan and Germany anchor the technical workforce for precision piercing mill operations, while Chinese metallurgical engineers dominate large-diameter pipe production scale.
China
Petrochemical capacity additions and nuclear power projects drive demand for GB-certified large-diameter seamless pipe. MEE environmental inspections tighten production allowances at energy-intensive mills in Shandong and Jiangsu provinces, accelerating replacement of welded piping with seamless alternatives in coastal refineries.
United States
Gulf Coast chemical processing expansions generate orders for corrosion-resistant tubing in sour-service applications. EPA emissions enforcement favors durable stainless systems in refineries, with Houston-area fabricators concentrating NACE MR0175-certified hollow production for offshore platform risers.
Germany
Hydrogen transport infrastructure projects open specification windows for advanced duplex grades in high-pressure containment roles. REACH substance restrictions and the EU F-Gas Regulation compel mills to certify full material composition traceability, with Ruhr Valley producers integrating blockchain-anchored mill test certificates for medical device OEMs.
India
CEA licensing of twelve new reactor units creates demand for ASME Section III-certified seamless tubing. Gujarat and Maharashtra-based fabricators face inspection bottlenecks at third-party eddy current and ultrasonic facilities, extending lead times for nuclear-grade certification.
Japan
Integrated blast furnace-to-rolling capabilities supply nuclear-grade seamless tubing for domestic and export markets. METI supply chain resilience guidelines accelerate consignment stocking arrangements with automotive OEMs unbundling after-sales tubing inventory, with Nagoya-area producers specializing in thin-wall aerospace configurations.
Seamless Stainless Steel Products Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the seamless stainless steel value chain. The market structure concentrates around integrated steelmakers with captive melting capacity and specialized tube mills with precision cold-drawing expertise. Three archetypes dominate: blast furnace-integrated majors controlling raw material flows, precision specialists commanding aerospace and medical premiums, and regional fabricators serving construction and industrial maintenance. Dominant competitive moves include backward integration into nickel alloy scrap sourcing and strategic partnerships for hydrogen-grade certification.
Among the integrated majors, Nippon Steel Corporation and JFE Steel Corporation occupy positions anchored in blast furnace-to-rolling capabilities. Alleima and Sandvik sit within the precision specialist tier, exemplifying advanced alloy composition expertise for exacting purity standards. Vallourec represents the European contingent with integrated seamless pipe production for energy infrastructure. These named entities anchor industry-level commentary without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Alleima |
| Vallourec |
| JFE Steel Corporation |
| Tubacex |
| Sandvik |
| Tenaris |
| Centravis |
| Jiuli Group |
| Others |
Value Network & Pricing Analysis
Nuclear project procurement offices and aerospace OEM material buyers concentrate purchasing power around long-term offtake contracts with embedded nickel price escalators. This buyer archetype dominance locks pricing into volume-commitment frameworks where raw material pass-through clauses determine margin stability more than finished-product differentiation.
Pricing Analysis
Contract-based long-term offtake agreements dominate seamless stainless procurement, with price differentiation resting on ASME Section III certification grade and mill test certificate traceability depth. Premium nuclear-grade tubing commands substantial spreads over standard ASTM A312 commercial pipe due to ultrasonic inspection overhead and qualified supplier scarcity. Cost compression in commodity large-diameter segments is intensifying because Chinese mill capacity expansions in Shandong province are flooding spot markets. Chemical processing plants show the least price sensitivity, prioritizing corrosion resistance and leakage risk reduction over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's nuclear program and Germany's hydrogen infrastructure projects are reshaping sourcing patterns toward local fabrication partnerships. Supply concentrates in China, Japan, and Germany for distinct product tiers: Chinese mills dominate GB-certified large-diameter pipe, Japanese producers anchor nuclear-grade thin-wall tubing, and German fabricators lead advanced duplex grades for hydrogen containment. Raw material flows draw from Indonesian nickel laterite, South African ferrochrome, and Australian iron ore, exposing margins to LME contract volatility. Single-source vulnerability concentrates in rotary piercing mill roller operators, whose retirement wave threatens greenfield commissioning timelines. Distribution runs through mill-direct relationships for nuclear and aerospace tiers, with regional stockists serving maintenance and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seamless stainless steel market functions as a stable compounder where regulatory mandates for extended service life and lower leakage risk perpetuate replacement cycles across energy infrastructure.
For Market Incumbents: Hedge nickel price exposure through backward integration into alloy scrap sourcing or long-term offtake agreements with Indonesian nickel producers. Defend qualified supplier status by accelerating ASME Section III recertification investments before India's CEA reactor licensing wave peaks. Capacity additions in Gujarat and Maharashtra position mills to capture nuclear tubing demand as third-party inspection bottlenecks ease. For New Entrants and Emerging Players: Digital alloy certification platforms offer a technology-first wedge into European medical device supply chains facing MDR traceability mandates. Target blockchain-anchored mill test certificate services as the most penetrable white-space opportunity, with German Ruhr Valley producers as initial anchor customers. Partner with established cold pilgering specialists to bypass the skilled roller operator shortage constraining greenfield mill commissioning. For Investors and Strategic Acquirers: Integrated energy infrastructure conglomerates are the most active acquirer in this space, seeking captive seamless pipe supply for hydrogen transport and carbon capture projects. Five-to-ten year viability hinges on hydrogen-grade duplex certification capabilities and nuclear-qualified production assets. Monitor CEA reactor construction timelines and German hydrogen pipeline award announcements as inflection indicators for capacity utilization and pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Scrap | Captive raw material supply insulates margins from LME volatility at alloy-integrated mills. |
| ASME Section III Certification Investment | Nuclear qualification opens India's CEA-licensed reactor pipeline to qualified tubing vendors. |
| Blockchain-Anchored Mill Test Certificates | Digital traceability satisfies EU MDR mandates for European medical device OEM procurement. |
| Hydrogen-Grade Duplex Development | High-pressure embrittlement resistance positions mills for German pipeline infrastructure awards. |
| Consignment Stocking Partnerships | Inventory transfers to Tier-1 suppliers lock volume commitments from Japanese automotive OEMs. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down mill capacity tracking forms the analytical core of this study. Primary interviews with nuclear procurement officers, chemical plant maintenance directors, aerospace material buyers, and seamless mill technical directors were validated against secondary sources including customs trade data, ASME certification registries, SEC filings from integrated steelmakers, and CEA reactor licensing announcements. This triangulation approach ensures demand estimates from petrochemical expansions and nuclear projects align with verified production capacity across Shandong, Jiangsu, and Nagoya manufacturing clusters.
Historical trendline analysis of rotary piercing output and cold pilgering yield rates established baseline growth patterns across the projection horizon. The forecast framework segments by product type, end-use industry, certification grade, and regional production hub, with CAGRs derived from elasticity modeling against nickel price scenarios and regulatory enforcement intensity. Nuclear capacity additions, hydrogen infrastructure award timelines, and MEE environmental inspection schedules served as industry-specific demand inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel price volatility, skilled roller operator availability, and carbon-border adjustment mechanism implementation timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Titanium Metal Market
Metals
Metal Alloys Market
Metals
Global Tin Market
Metals
Titanium Mill Products Market
Metals
Aluminum Casting Market
Metals
Aluminum Welding Market
Metals
Ferro Aluminum Market
Metals
High Purity Lead Market
Metals
High Purity Base Metals Market
Metals
Weathering Steel Market
Metals
Metal Casting Market
Metals
US Ferrochrome Market
Metals
North America Aluminum Casting Market
Metals
High Carbon Bearing Steel Market
Metals
Rolled Steel Motor Market
Metals
Lightweight Aluminium Pistons Market