
 Shipbuilding Steel Plate Market | 2026-2036
Shipbuilding Steel Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Shipbuilding Steel Plate Market Insights
Aftermarket hull plate refurbishment and life-extension services is rewriting margin distribution across the value chain. POSCO Holdings leverages captive blast furnace capacity to dominate premium marine-grade output for Korean shipbuilders. JFE Steel anchors Japanese supply through specialized thermo-mechanical control process lines at its West Japan Works. China Baowu Group extends geographic reach via integrated mill complexes serving both civilian and naval construction programs.
Shipbuilding steel plate denotes hot-rolled flat carbon or alloy steel exceeding 6 mm thickness, typically supplied in AH36-DH40 grades with minimum yield strengths of 355 MPa, engineered to withstand cyclic wave loading and saltwater corrosion across welded hull structures. Carbon steel grades still occupy the highest volume share in bulk carrier and tanker construction, though high strength low alloy plate is gaining share in containership superstructures where weight reduction directly improves fuel efficiency. Quenched and tempered processing commands premium positioning for ice-class vessels and submarine casing applications requiring through-thickness toughness below minus 40 degrees Celsius.
Classification societies including Lloyd's Register, DNV, and the Korean Register enforce harmonized rules on chemical composition limits, Charpy impact testing protocols, and weldability certification that determine mill qualification and shipyard procurement eligibility. The European Union's Carbon Border Adjustment Mechanism and the International Maritime Organization's revised Energy Efficiency Existing Ship Index together redirect demand toward lower-emission steel production routes and documented lifecycle carbon accounting. Stakeholders must monitor evolving green steel premiums and classification society rules on recycled content thresholds to secure long-term supply contracts.
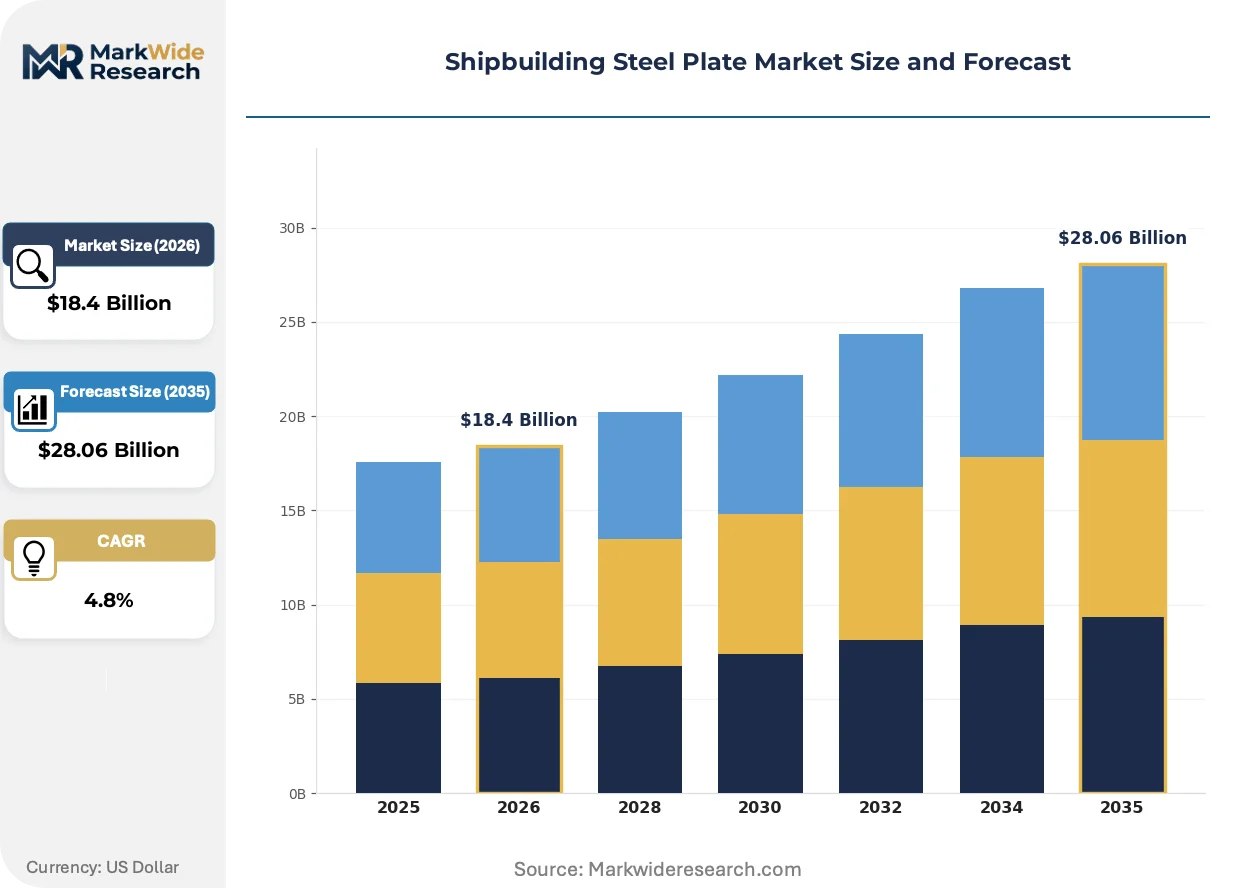
Market Dynamics
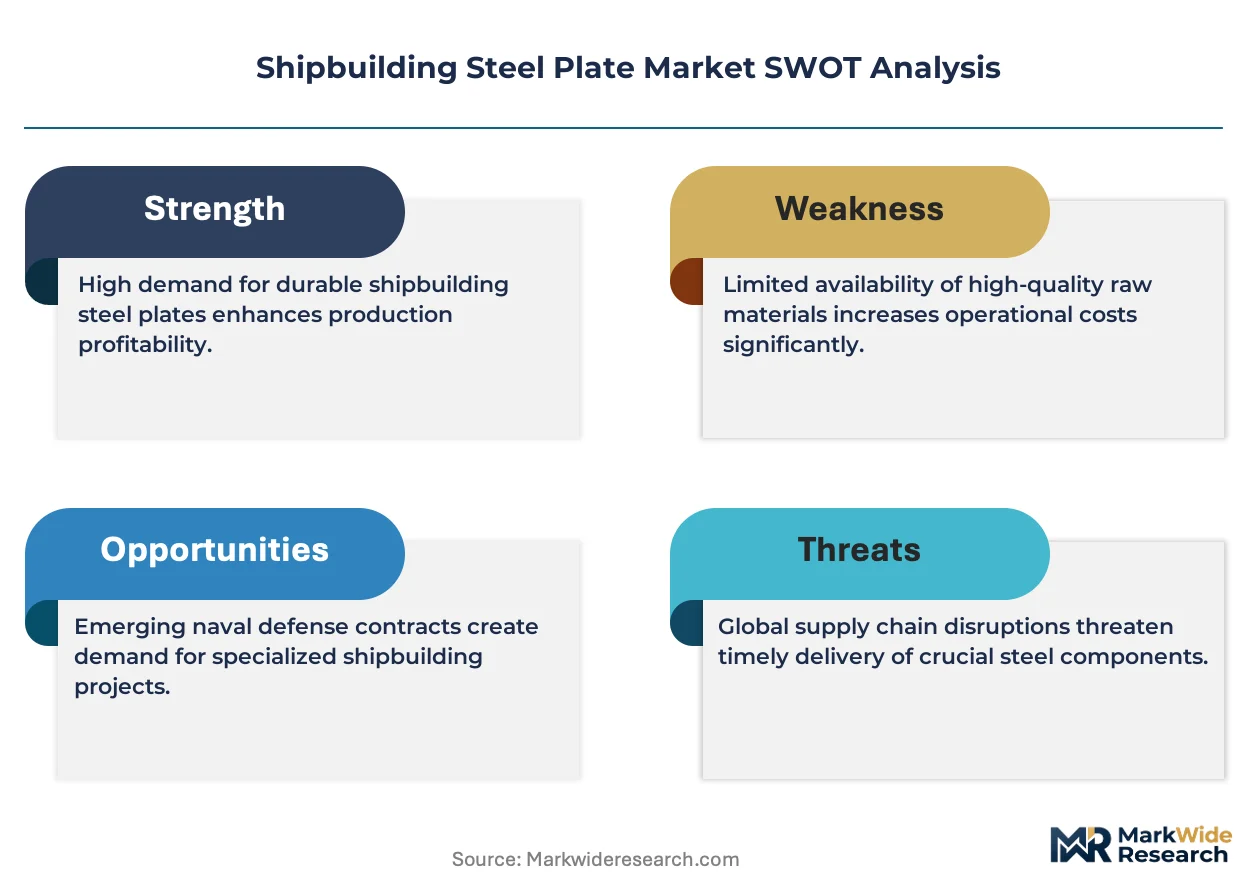
The International Maritime Organization's revised carbon intensity regulations are compressing hull fabrication timelines and forcing shipyards to source lower-emission steel grades with documented lifecycle carbon accounting.
Growth Catalysts
- IMO CII Compliance Deadlines:The Energy Efficiency Existing Ship Index mandates retrofits and newbuilds with lighter superstructures, pulling high-strength low alloy plate into containership programs.
- LNG Carrier Order Surge:Cryogenic containment systems require specialized nickel-alloy clad plate with through-thickness toughness below minus 196 degrees Celsius.
- South Korean Yard Clustering:Dense shipbuilder concentration near Busan and Ulsan creates localized demand density that justifies dedicated mill capacity investments.
Market Restraints
- Iron Ore Price Volatility:Blast furnace operators face margin compression when raw material costs spike unpredictably.
- Mill Qualification Concentration:Only a handful of integrated steelworks hold Lloyd's Register and DNV certification for submarine-grade quenched and tempered plate.
- Scrap Availability Constraints:Electric arc furnace routes struggle to source prime scrap with sufficiently low copper content for marine-grade specifications.
Strategic Opportunities
- EU Carbon Border Adjustment Mechanism:Documented green steel premiums create first-mover advantage for mills with hydrogen-reduction pilot lines.
- Aftermarket Hull Refurbishment:Life-extension services for aging bulk carriers open margin pools beyond original equipment supply.
- Ice-Class Vessel Expansion:Arctic shipping routes drive demand for EH36-FH40 grades with guaranteed Charpy impact values at minus 60 degrees Celsius.
Industry Challenges
- Welder Certification Bottlenecks:Classification societies require specialized welder qualification for high-strength plate that extends yard labor timelines.
- Integrated Mill Capex Requirements:Thermo-mechanical control process lines demand nine-figure investments with decade-long payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipbuilding Steel Plate Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, High Strength Low Alloy, Weathering Steel, Stainless Steel, Marine Grade Steel Application: Hull Construction, Deck Sections, Bulkheads, Offshore Platforms, Submarine Casing Manufacturing Stage: Hot Rolled, Cold Rolled, Quenched & Tempered, Annealed, Normalized End User: Shipyards, Defense Contractors, Offshore Service Providers, Cargo Fleet Operators |
| Companies Covered | POSCO Holdings, JFE Steel, China Baowu Group, ThyssenKrupp, Hyundai Steel, ArcelorMittal, Ansteel Group, Nucor Corporation, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipbuilding Steel Plate Market Trends and Innovations
Digital twin modeling of hull stress distributions is compressing plate specification cycles from months to weeks. Shipyards now simulate fatigue performance before placing mill orders.
High-strength low alloy plate with thermo-mechanical control processing is rendering obsolete conventional normalized carbon grades in containership deck structures. Korean and Chinese yards specify TMCP plate for 80% of new superstructure tonnage. The shift compresses steel weight by 15-20% while maintaining equivalent buckling resistance.
The European Union's Carbon Border Adjustment Mechanism phases in full carbon accounting requirements for imported steel by 2026. Mill qualification now requires third-party verified emissions disclosures alongside traditional mechanical testing. Korean shipbuilders are pre-qualifying European blast furnace operators to secure supply continuity.
Buyer consolidation among top-ten container lines concentrates procurement leverage against fragmented mill supply. Long-term offtake agreements with fixed-volume, floating-price mechanisms displace spot market purchases for premium grades. This concentration is most visible in South Korea, where Hyundai Heavy Industries and Samsung Heavy Industries negotiate directly with POSCO Holdings for dedicated slab allocations.
Shipbuilding Steel Plate Market Segmentation
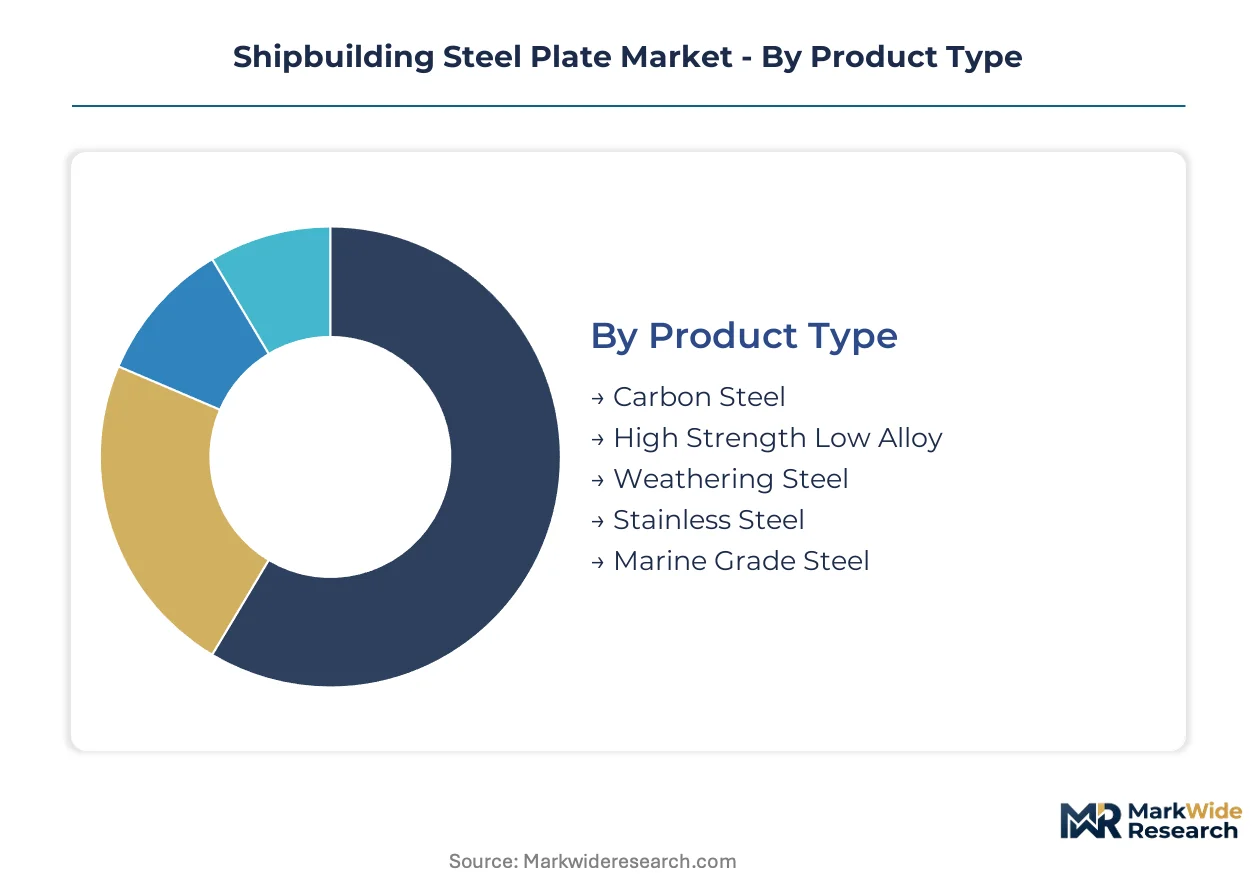
Shipbuilding steel plate procurement varies sharply by application severity and certification requirements. Classification society rules create rigid segment boundaries that determine mill qualification and pricing tiers. Understanding these divisions reveals where margin pools concentrate and where commoditization pressures bite hardest.
Product Type:
Aftermarket service intensity climbs with alloy complexity, as specialized grades demand ongoing inspection, welding repair protocols, and life-extension engineering.
- Carbon Steel:Conventional hot-rolled grades in AH32-AH36 specifications serve bulk carrier and tanker hulls where cost minimization dominates procurement. South Korean yards near Ulsan consume the highest volumes for standard merchant vessel programs, though IMO carbon intensity regulations are compressing margins on these lower-grade specifications.
- High Strength Low Alloy:Thermo-mechanical control process plate delivers 355-460 MPa yield strength with reduced weight for containership superstructures. Hyundai Heavy Industries and Samsung Heavy Industries specify TMCP-HSLA for deck structures to improve vessel fuel efficiency under Energy Efficiency Existing Ship Index compliance deadlines.
- Weathering Steel:Corrosion-resistant grades with copper-chromium additions suit coastal patrol craft and harbor infrastructure where protective coating maintenance is impractical.
- Stainless Steel:Austenitic and duplex grades serve chemical tanker cargo containment areas requiring resistance to aggressive cargoes.
- Marine Grade Steel:Unified designation covering Lloyd's Register and DNV-certified output across all alloy categories, with documentation requirements tightening under EU Carbon Border Adjustment Mechanism phase-in.
By volume, Carbon Steel leads. By growth pace, High Strength Low Alloy is expanding most quickly.
Application:
Structural function determines plate thickness, toughness requirements, and welding complexity, which in turn dictate supply chain configuration and procurement leverage.
- Hull Construction:Bottom shell and side shell plating in 20-80mm thicknesses withstands hydrostatic pressure and wave impact. POSCO Holdings supplies pre-primed hull plate to Hyundai Heavy Industries under long-term offtake agreements with floating-price mechanisms.
- Deck Sections:Upper deck and hatch coaming structures prioritize weight reduction over ultimate strength. Chinese yards specify Q345-Q390 grade TMCP plate for 80% of new containership deck tonnage, compressing steel weight by 15-20% versus normalized alternatives.
- Bulkheads:Transverse and longitudinal watertight divisions require through-thickness ductility to prevent lamellar tearing at welded intersections.
- Offshore Platforms:Jack-up leg and hull integration modules demand Z-direction tested plate with sulfide inclusion control for fatigue resistance in North Sea environments.
- Submarine Casing:HY-80 and HY-100 quenched and tempered grades with guaranteed Charpy values below minus 40 degrees Celsius serve naval pressure hull applications. Only three integrated mills worldwide hold certification for this segment.
By tonnage, Hull Construction dominates. By contract value concentration, Submarine Casing sits at the apex.
Manufacturing Stage:
Process route selection locks in mechanical properties, delivery lead times, and carbon intensity credentials that increasingly determine mill qualification.
- Hot Rolled:As-rolled plate from continuous casting serves non-critical structural applications where as-welded strength suffices. Chinese integrated mills at Ningbo and Shanghai supply hot-rolled AH36 for domestic bulk carrier programs at volume-driven price points.
- Quenched & Tempered:Reheating and controlled cooling delivers 500-690 MPa yield strength with exceptional toughness for ice-class vessels and submarine applications. JFE Steel's West Japan Works specializes in Q&T plate for Arctic LNG carriers requiring EH36-FH40 grades with minus 60 degrees Celsius Charpy guarantees.
- Cold Rolled:Thickness reduction below 6mm serves interior joinery and non-structural marine fittings with tight dimensional tolerances.
- Annealed:Softening heat treatment enables complex forming of bulb flats and stiffener sections without cracking.
- Normalized:Air-cooled refinement of grain structure maintains weldability in thicker sections, though TMCP routes are displacing normalized plate in most new specifications.
By output volume, Hot Rolled leads. By margin per ton, Quenched & Tempered commands the steepest premium trajectory.
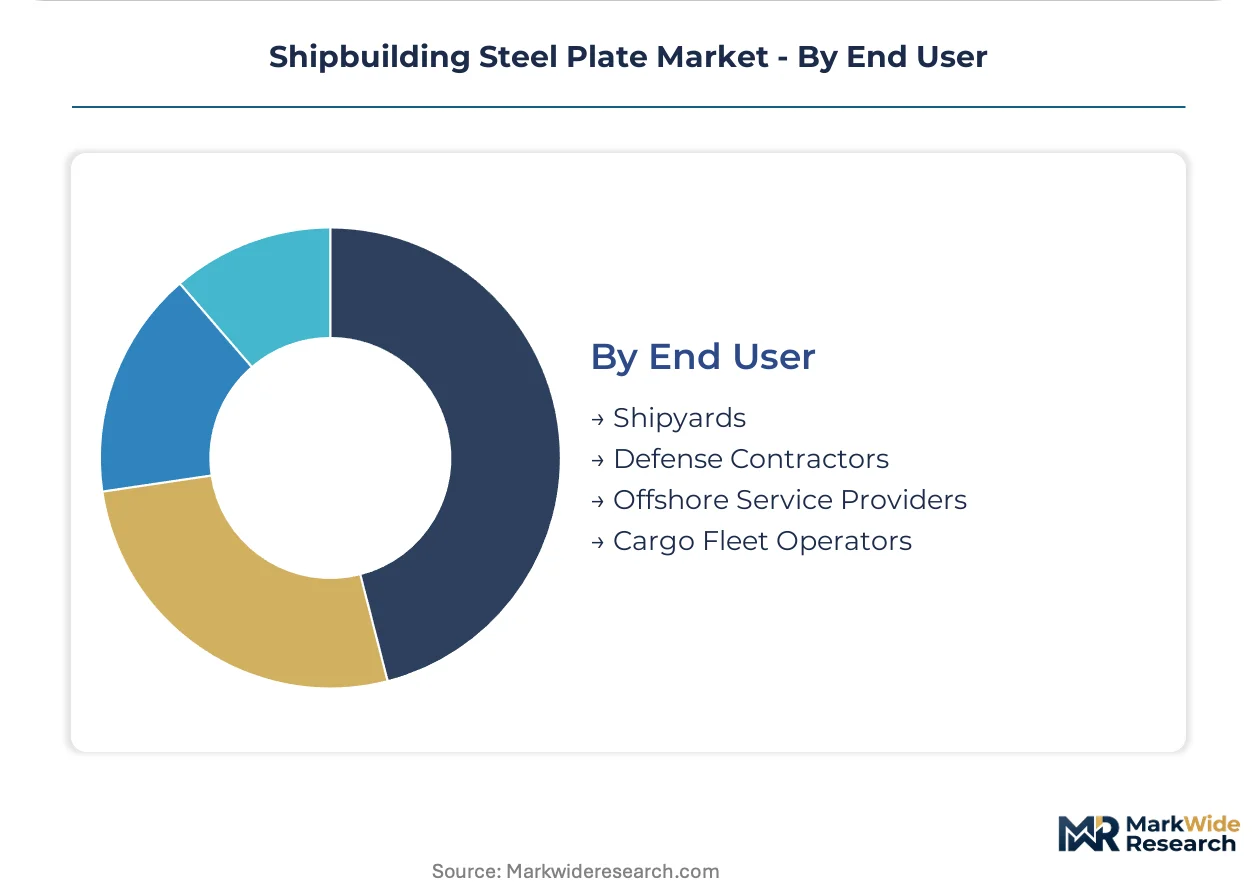
End User:
Buyer scale and technical capability create stark segmentation in procurement sophistication and contract structuring.
- Shipyards:Hyundai Heavy Industries, Samsung Heavy Industries, and Daewoo Shipbuilding & Marine Engineering concentrate demand for premium grades through direct mill negotiations. Korean yard clustering near Busan enables dedicated slab allocations from POSCO Holdings with 3-5 year offtake terms.
- Defense Contractors:Naval shipbuilders in France, the United Kingdom, and the United States require traceability documentation and security-cleared mill personnel for submarine-grade output. Procurement runs through national defense procurement agencies with decade-long program horizons.
- Offshore Service Providers:Jack-up rig owners and floating production system operators source plate through engineering-procurement-construction contractors with performance guarantees on fatigue life.
- Cargo Fleet Operators:Container lines and bulk carrier owners influence newbuild specifications through design approvals but rarely procure plate directly, instead capturing value through life-extension retrofit decisions.
By annual tonnage, Shipyards absorb the majority. By contract duration and qualification barriers, Defense Contractors lock in the longest supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilders in South Korea absorb premium grades with minimal price elasticity, while Chinese bulk carrier programs drive volume through cost-optimized procurement. Indian yards and Southeast Asian fabricators sit between these poles, trading specification flexibility for delivery speed.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor demand for thermo-mechanical control process plate in containership superstructures. The Korean Register enforces harmonized weldability certification that determines mill qualification eligibility. Dense shipbuilder clustering near Busan and Ulsan justifies dedicated slab allocations from captive steelworks with multi-year offtake terms.
China
China Baowu Group and Ansteel Group feed domestic bulk carrier and tanker construction through integrated mill complexes at Ningbo and Shanghai. The Ministry of Ecology and Environment's dual carbon goals redirect new capacity approvals toward lower-emission production routes. Yangtze River Delta shipyards specify Q345-Q390 grade plate for 80% of new containership deck tonnage, compressing steel weight versus normalized alternatives.
Japan
JFE Steel's West Japan Works specializes in quenched and tempered output for Arctic LNG carriers requiring EH36-FH40 grades with minus 60 degrees Celsius Charpy guarantees. METI industrial policy supports thermo-mechanical control process line investments with decade-long payback horizons. Chubu region mills concentrate on ice-class vessel specifications as Japanese yards pivot toward premium niche segments.
United States
Nucor Corporation and domestic electric arc furnace operators struggle to source prime scrap with sufficiently low copper content for submarine-grade specifications. The Department of Defense runs procurement through Naval Sea Systems Command with traceability documentation and security-cleared mill personnel requirements. Gulf Coast repair yards drive aftermarket hull refurbishment demand as Jones Act fleet aging accelerates life-extension programs.
Germany
ThyssenKrupp and ArcelorMittal European operations face Carbon Border Adjustment Mechanism phase-in requirements for third-party verified emissions disclosures by 2026. The EU Green Deal redirects steel procurement toward hydrogen-reduction pilot lines with documented green steel premiums. Northern German shipyards along the Elbe and Weser rivers concentrate on offshore wind installation vessel construction requiring Z-direction tested plate.
Shipbuilding Steel Plate Market Competitive Landscape
Capability concentration sits with integrated blast furnace operators holding Lloyd's Register and DNV certification for submarine-grade quenched and tempered plate; scale advantage sits with Chinese and Korean mills serving high-volume merchant vessel programs. The vendor base stratifies across three archetypes: captive steelworks aligned to national shipbuilder clusters, independent premium-grade specialists, and volume-driven integrated operators. Dominant competitive moves include backward integration into iron ore and metallurgical coal sourcing, plus strategic partnerships between yards and mills for dedicated slab allocations.
Among Korean and Japanese integrated operators, POSCO Holdings, JFE Steel, and Nippon Steel Corporation exemplify the captive-capability archetype, anchoring supply relationships with shipbuilders through long-term offtake structures. These entities occupy positions where mill qualification barriers and classification society weldability certification create defensive moats around premium-grade output.
| Leading Market Players |
|---|
| POSCO Holdings |
| JFE Steel |
| China Baowu Group |
| ThyssenKrupp |
| Hyundai Steel |
| ArcelorMittal |
| Ansteel Group |
| Nucor Corporation |
| Nippon Steel Corporation |
| Others |
Pricing and Supply Chain Analysis
Iron ore cost volatility determines both the spread between carbon steel and quenched-and-tempered grades and the geographic clustering of integrated mill capacity. When raw material spikes compress blast furnace margins, Korean and Japanese operators prioritize long-term offtake structures over spot market exposure, reshaping procurement leverage across the hull fabrication value chain.
Pricing Analysis
Aftermarket hull refurbishment and life-extension services capture lifetime value beyond original equipment supply. Contract-based long-term offtake agreements with floating-price mechanisms dominate premium grade procurement, while spot markets handle carbon steel bulk orders. Price differentiation rests on Lloyd's Register certification tier and volume scale, with Hyundai Heavy Industries and Samsung Heavy Industries locking dedicated slab allocations. Cost compression in AH32-AH36 carbon grades is intensifying because Chinese integrated mills compete on volume-driven price points. Container lines and bulk carrier owners show highest price sensitivity; defense contractors and ice-class vessel operators show least.
Supply Chain Analysis
Metallurgical coal and iron ore feedstock dependency anchors production in South Korea, China, and Japan. The supply chain draws from Australian iron ore, Mongolian coking coal, and domestic scrap pools with copper-content constraints. Single-source vulnerability concentrates in submarine-grade quenched-and-tempered plate, where only three integrated mills worldwide hold DNV certification. Distribution runs through direct mill-shipyard partnerships for premium grades and spot market intermediaries for standard merchant vessel tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shipbuilding steel plate procurement is shifting toward platform-economics logic as digital twin hull modeling and lifecycle carbon accounting create interoperability requirements between classification societies, mills, and shipyards.
For Market Incumbents: Insulate premium-grade positioning through captive thermo-mechanical control process capacity and backward integration into iron ore sourcing. POSCO Holdings and JFE Steel defend against Chinese volume competition by deepening Lloyd's Register certification moats and securing multi-year slab allocations with Korean yard clusters. Classification society weldability bottlenecks and EU Carbon Border Adjustment Mechanism disclosure requirements extend defensive timelines. For New Entrants and Emerging Players: Mid-tier shipyards in Vietnam and Indonesia represent the most penetrable entry point for non-certified carbon steel supply. Aftermarket hull refurbishment services for aging bulk carriers offer margin pools beyond original equipment with lower qualification barriers. Green steel pilot lines with hydrogen-reduction credentials provide differentiation angle for European procurement pre-qualification. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with captive blast furnace capacity and submarine-grade certification. Long-term viability across the analysis window hinges on carbon intensity disclosure capabilities and classification society relationship depth. Watch for EU Carbon Border Adjustment Mechanism enforcement intensity as inflection signal for green steel premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Ore | POSCO Holdings secures captive feedstock against Australian price volatility. |
| Long-term Supply Agreement | Hyundai Heavy Industries locks dedicated slab allocations with floating-price mechanisms. |
| Green Manufacturing Transition | Hydrogen-reduction pilot lines qualify mills for EU Carbon Border Adjustment Mechanism compliance. |
| Capacity Expansion | Chinese integrated mills at Ningbo add volume for domestic bulk carrier programs. |
| Joint Venture | Korean shipbuilder clustering near Busan enables shared logistics infrastructure with POSCO Holdings. |
Research Methodology
The analysis maps carbon steel, high-strength low alloy, and quenched-and-tempered plate sub-sectors, each validated through procurement directors at major shipyards, classification society technical auditors, and blast furnace operations managers. Primary interviews with POSCO Holdings supply chain executives, Lloyd's Register marine surveyors, and Hyundai Heavy Industries material planners combined with secondary validation from Korean Register rule filings, DNV technical standards, customs trade data, and SEC 10-K disclosures from listed steel producers. Bottom-up tonnage estimates and top-down value projections underwent cross-referencing triangulation.
Assumptions held fixed include IMO Energy Efficiency Existing Ship Index compliance deadlines and EU Carbon Border Adjustment Mechanism phase-in timelines, while iron ore price trajectories and scrap copper-content availability were varied across scenarios. Segmentation dimensions modeled encompass product grade tier, manufacturing process route, hull structural application, and end-user procurement sophistication. CAGRs were derived from production capacity utilization trends and orderbook-to-delivery ratios across the projection horizon. Classification society rule evolution and green steel premium elasticity served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction steel demand and Baltic Dry Index volatility would shift the trajectory. Forecasts reflect documented assumptions on scrap pool quality and hydrogen-reduction technology maturation. Cross-checking against Lloyd's Register and DNV mill qualification registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Coil Lamination Market
Metals
Global Mercury Market
Metals
Seamless Stainless Steel Products Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
High-End Copper Foil Market
Metals
Expanded Metal Foils Market
Metals
Global Aluminum Extruded Products Market
Metals
Copper Wire Market
Metals
Pump Casing Materials Market
Metals
Bearing Steel Market
Metals
Copper and Brass Flat Products Market
Metals
Battery Metals Market
Metals
Copper Smelting Market
Metals
Magnesium Metal Market
Metals
Titanium Mill Products Market
Metals
Electrolytic Iron Market