
 GCC Aluminium Powder Market | 2026-2036
GCC Aluminium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Aluminium Powder Market Intelligence
Distributor networks serving Saudi Arabia and the UAE is rewriting how aluminium powder reaches Gulf manufacturers. Eckart GmbH leverages its European production base to sustain premium supply lines into Dubai's coatings cluster. Rusal anchors volume availability through its smelter relationships and regional logistics partnerships. AMG Aluminum competes on specialty alloy formulations tailored to aerospace specifications across the Emirates.
Aluminium powder consists of finely divided metallic aluminium particles, typically produced through atomization or milling processes with particle sizes ranging from 1 to 200 microns, serving primarily as functional fillers, pigments, and feedstock for additive manufacturing and chemical reactions. Flake aluminium powder dominates decorative coatings demand across Gulf construction projects, while spherical atomized grades command higher margins in additive manufacturing feedstock for aerospace end users. Powder and granule categories occupy distinct procurement channels, with bulk packaging for industrial chemical applications and drum formats for precision coating operations.
SASO standards in Saudi Arabia and ESMA regulations in the UAE govern product purity, particle size distribution, and hazardous material handling protocols for aluminium powder imports and domestic blending operations. The Gulf Standardization Organization coordinates cross-border technical requirements, while individual member states enforce country-specific industrial safety inspections at port of entry. Stakeholders must monitor evolving national industrial strategies linking aluminium downstream processing to domestic value-add targets rather than raw material re-export models.
Market Dynamics
Atomization technology upgrades across GCC smelter complexes are compressing particle size tolerances and forcing procurement criteria toward SAMR-aligned purity standards, concentrating supply relationships around technically verified producers.
Growth Catalysts
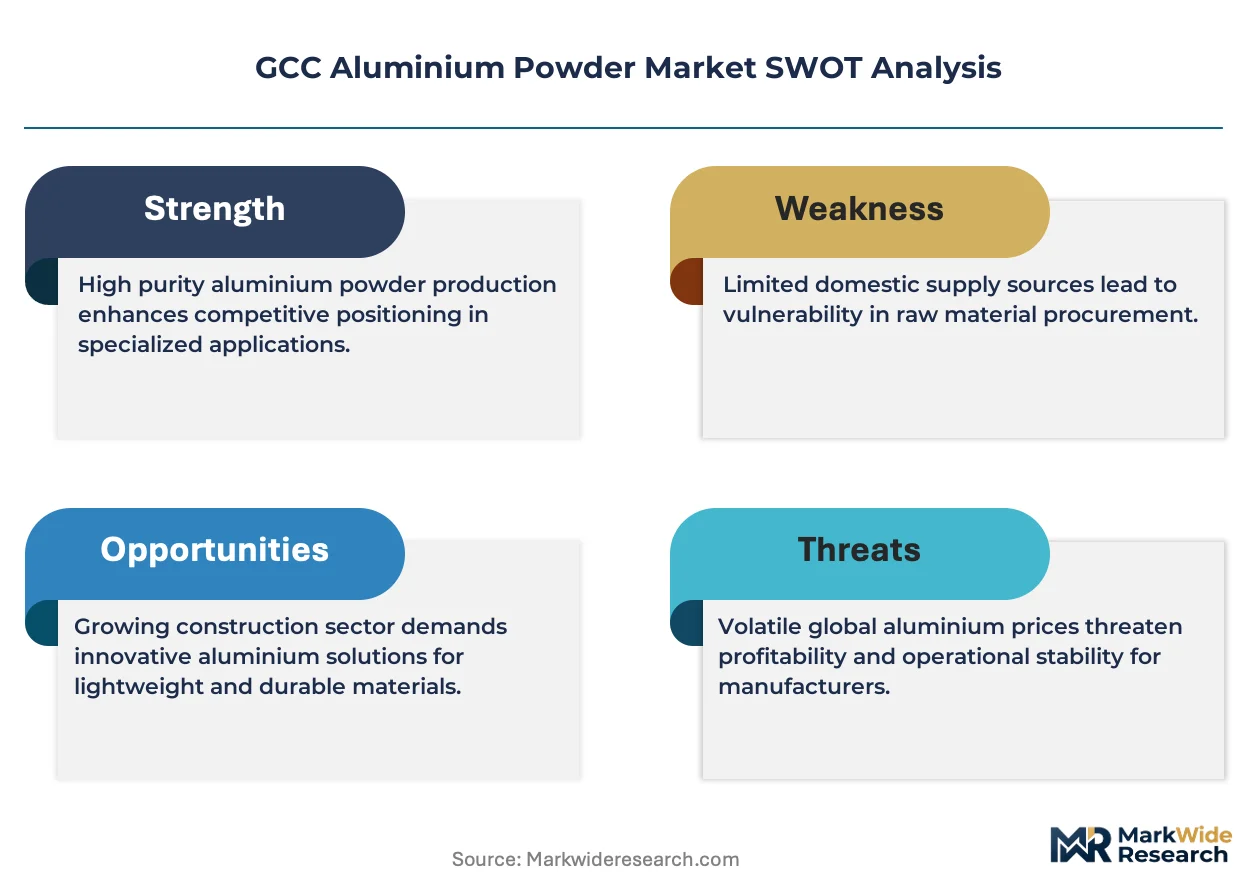
- Automotive Lightweighting Mandates:Saudi Arabia's industrial corridor between Jubail and Yanbu is absorbing atomized aluminium powder for electric vehicle chassis and powertrain components as domestic assembly targets tighten.
- ESMA Hazardous Material Protocols:UAE regulatory harmonization is eliminating substandard imports and consolidating demand around certified regional blenders with documented handling capabilities.
- Additive Manufacturing Feedstock Expansion:Spherical powder grades are penetrating aerospace maintenance operations across the Emirates as tier-one suppliers qualify local sources for printed replacement parts.
Market Restraints
- Feedstock Cost Volatility:Primary aluminium ingot price swings transmit directly into atomized powder production economics, compressing blender margins during LME spikes.
- Smelter Concentration Risk:Volume availability depends on Rusal's regional logistics partnerships and Emirates Global Aluminium's tolling arrangements, creating single-source vulnerability for large coating accounts.
- Flake Powder Substitution Pressure:Pearlescent pigments and coated mica alternatives are displacing decorative aluminium flake in mid-tier Gulf construction finishes.
Strategic Opportunities
- Kuwait Underpenetration:Industrial chemical applications remain underserved relative to Saudi Arabia and the UAE, offering first-mover positioning for bulk packaging suppliers.
- Gulf Standardization Organization Coordination:Cross-border technical requirements harmonization is creating pan-GCC certification pathways that reduce per-country compliance overhead.
- Digital Procurement Platforms:B2B marketplaces are emerging as alternative channels to traditional distributor networks for mid-volume coating manufacturers seeking price transparency.
Industry Challenges
- Atomization Specialist Scarcity:Gas atomization process engineers with GCC industrial gas safety certification remain concentrated in European and East Asian talent pools.
- SASO Certification Timelines:Saudi product registration cycles for new particle size distributions extend 8-14 months, delaying commercialization of customized alloy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Aluminium Powder Market |
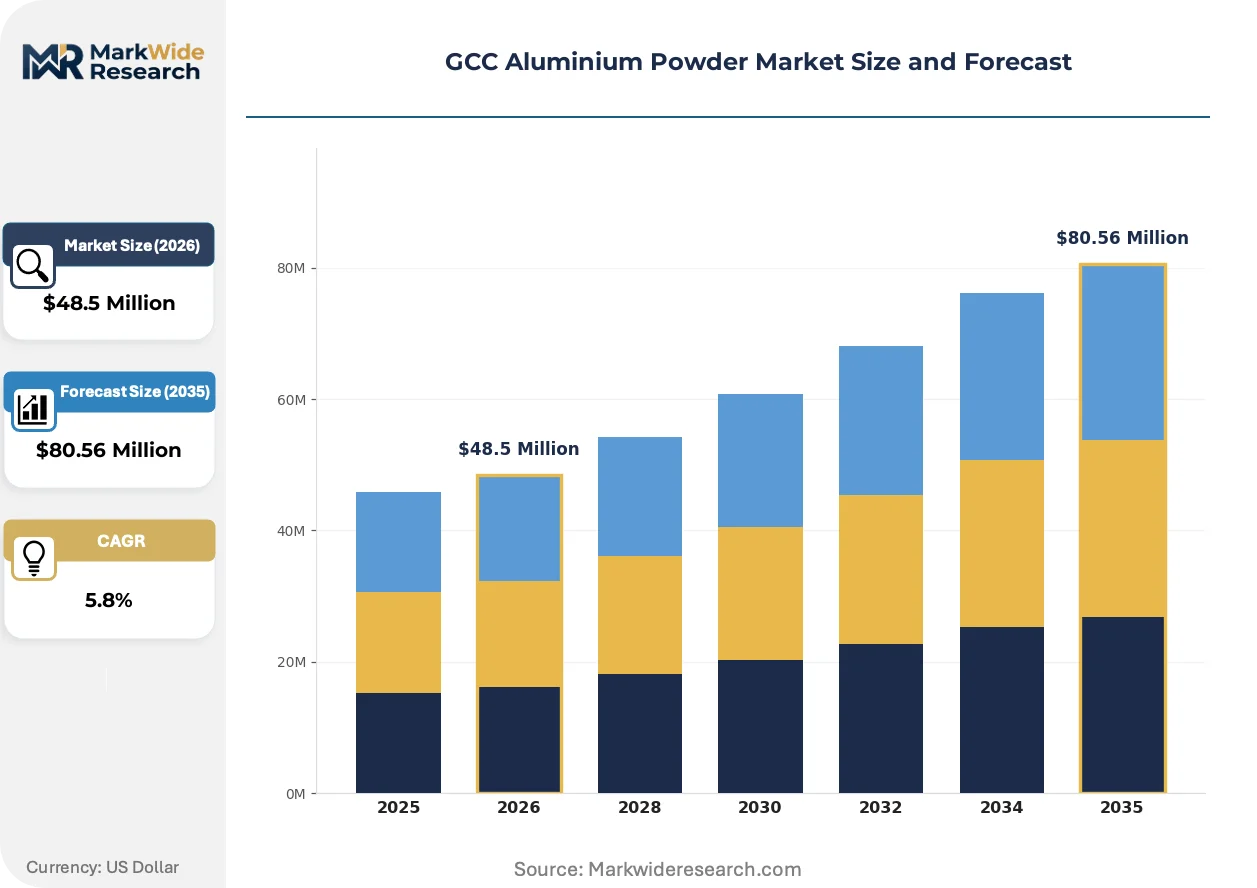
| Market Size in 2026 | $48.5 Million |
| Market Size in 2035 | $80.56 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Granule, Powder, Pellets Application: Coating, Additive, Fillers, Additives End User: Aerospace, Automotive, Construction, Electronics Packaging Type: Bag, Drum, Bulk, Canister |
| Companies Covered | Eckart GmbH, Valimet Inc., Rusal, Sun Chemical Corporation, Silberline Manufacturing Co., Inc., Toyo Aluminium K.K., AMG Aluminum, Metal Powder Company Ltd., Showa Denko K.K., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Aluminium Powder Market Strategic Shifts & Innovations
Computational approaches to particle morphology prediction are compressing R&D cycles for specialty alloy powders, while regulatory alignment pressures and procurement centralization are restructuring how Gulf manufacturers source feedstock.
Plasma atomization systems are virtualizing traditional gas atomization for titanium-aluminium intermetallic powders in aerospace applications. Emirates-based maintenance, repair, and overhaul facilities are adopting these systems at pilot scale. The technology is virtualizing established qualification pathways by enabling direct digital certification of powder lot characteristics.
Gulf Standardization Organization technical committees are finalizing unified particle size distribution testing protocols across member states. Industrial safety inspections at Saudi and UAE ports of entry are converging toward common hazardous material handling documentation. Specialty alloy blenders serving aerospace specifications are most affected, accelerating investment in dual-certified laboratory capacity.
Consolidated procurement desks at major Gulf construction groups are unbundling coating formulation from powder supply, forcing distributors to compete on technical service rather than sole-source relationships. Drum-format precision packaging is displacing bulk tote arrangements for mid-tier decorative applications. This pattern is most visible in Dubai's coatings cluster, where project-scale purchasing has centralized around three specified buyers.
GCC Aluminium Powder Market Segmentation
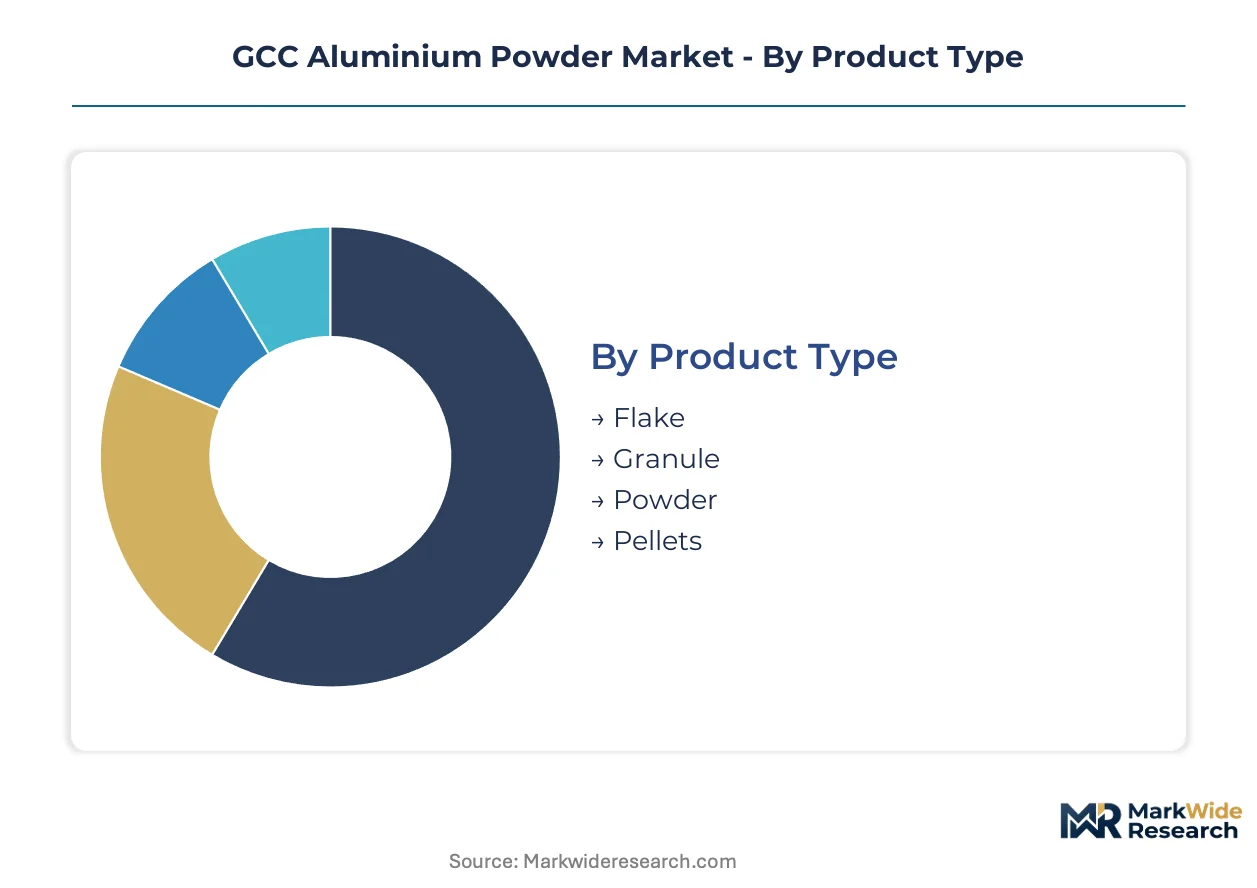
Aluminium powder procurement in the Gulf Cooperation Council follows distinct technical and commercial pathways. Each segmentation dimension shapes supplier relationships, certification requirements, and margin structures differently across Saudi Arabia and the Emirates.
Product Type:
Particle morphology determines application suitability and pricing tiers across GCC industrial buyers.
- Powder:Spherical atomized grades with particle sizes from 1 to 200 microns serve as feedstock for additive manufacturing and chemical reactions. Demand concentrates in Dubai's aerospace maintenance facilities as tier-one suppliers qualify local sources for printed replacement parts under ESMA hazardous material protocols.
- Flake:Lamellar particles produced through milling processes dominate decorative coatings demand across Gulf construction projects. Procurement concentrates in Saudi Arabia's industrial corridor between Jubail and Yanbu, though pearlescent pigment alternatives are displacing mid-tier decorative applications.
- Granule:Coarser agglomerated forms suit bulk industrial chemical applications with less stringent particle size distribution requirements.
- Pellets:Compacted forms for controlled-feed manufacturing processes in specialty alloy blending operations.
Powder commands the established base. The steepest expansion runs through Flake as construction activity accelerates across the Emirates.
Application:
Functional roles in manufacturing processes separate high-margin specialty grades from commodity filler volumes.
- Coating:Pigment and protective layer applications span automotive refinishing, architectural finishes, and industrial corrosion protection. Drum-format precision packaging is displacing bulk tote arrangements for mid-tier decorative applications in Dubai's coatings cluster.
- Additive:Feedstock for metal additive manufacturing requires spherical morphology and tight particle size distribution. Emirates-based maintenance, repair, and overhaul facilities are adopting plasma atomization systems at pilot scale for titanium-aluminium intermetallic powders.
- Fillers:Functional loading in composites and polymers for automotive lightweighting applications across Saudi assembly operations.
- Additives:Chemical process catalysts and pyrotechnic formulations serving industrial chemical applications.
Coating retains volume leadership. The fastest climb occurs in Additive as aerospace qualification pathways compress.
End User:
Industry-specific certification requirements and performance specifications fragment procurement channels.
- Automotive:Electric vehicle chassis and powertrain components absorb atomized aluminium powder as Saudi domestic assembly targets tighten. SAMR-aligned purity standards are reshaping procurement criteria for regional buyers.
- Aerospace:Maintenance, repair, and overhaul operations across the Emirates demand specialty alloy formulations with documented handling capabilities under Gulf Standardization Organization protocols.
- Construction:Decorative and protective coatings for Gulf building projects, subject to SASO standards in Saudi Arabia and ESMA regulations in the UAE.
- Electronics:Conductive fillers and thermal management applications in semiconductor packaging and LED thermal interfaces.
Construction anchors current demand. Automotive is gaining share fastest as Saudi industrial corridor capacity expands.
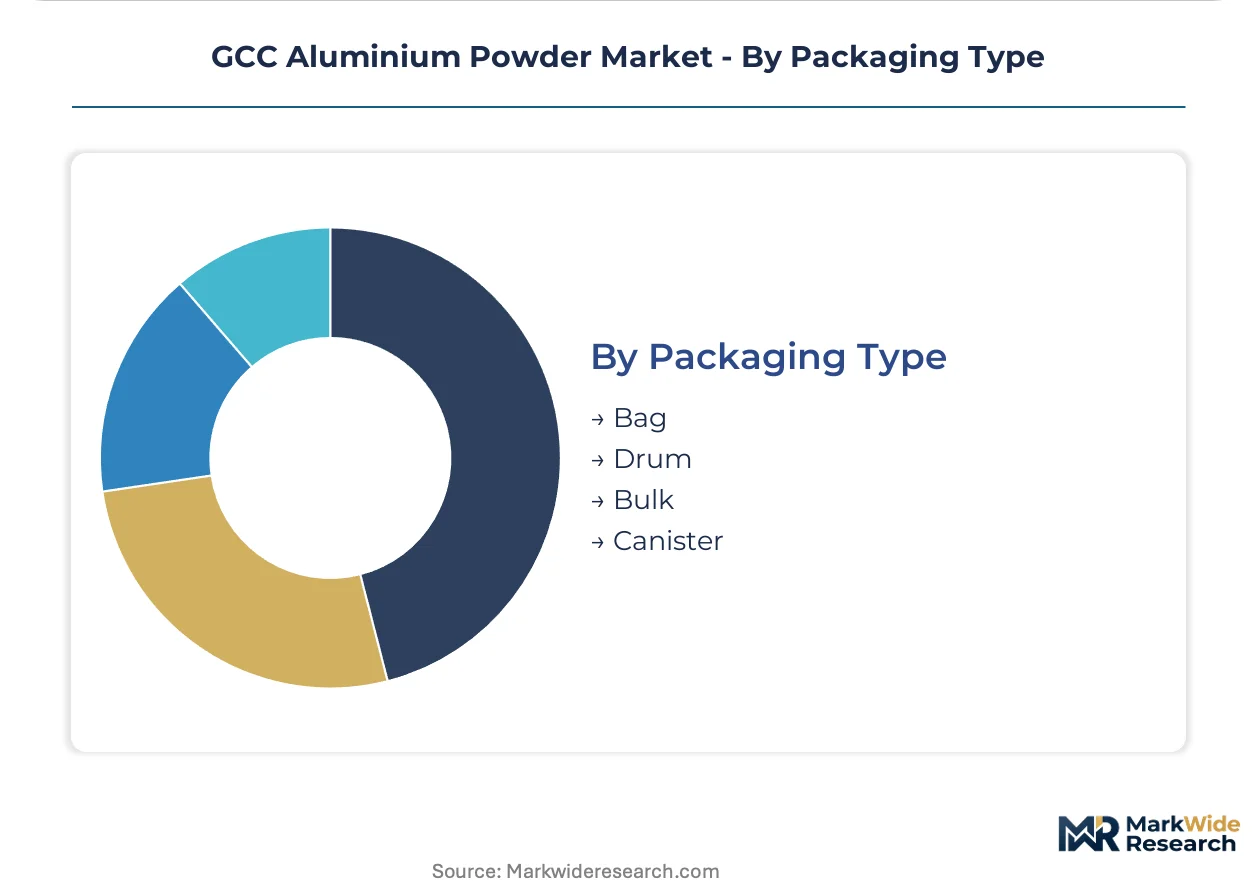
Packaging Type:
Format selection reflects handling safety requirements, volume scale, and precision dosing needs.
- Drum:Steel containers with sealed lids for precision coating operations requiring contamination control. Consolidated procurement desks at major Gulf construction groups are unbundling coating formulation from powder supply, forcing distributors to compete on technical service.
- Bulk:Tote and silo formats for high-volume industrial chemical applications with dedicated handling infrastructure.
- Bag:Flexible intermediate bulk containers for mid-scale manufacturing with standard material handling equipment.
- Canister:Small-format containment for laboratory, R&D, and specialty alloy sampling requirements.
Bulk formats dominate tonnage shipments. Drum packaging is climbing fastest as project-scale purchasing centralizes around specified buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Fahd Industrial Port in Jubail anchors aluminium powder throughput for the GCC, with dedicated bulk handling infrastructure serving smelter-adjacent atomization facilities and downstream coating operations.
Saudi Arabia
Electric vehicle chassis production and powertrain lightweighting absorb atomized grades across the Jubail-Yanbu industrial corridor. SASO purity standards and extended certification timelines for new particle size distributions shape procurement patterns. Riyadh-based construction groups consolidate drum-format purchasing, unbundling formulation services from raw material supply.
United Arab Emirates
Dubai's aerospace maintenance facilities pilot plasma atomization systems for titanium-aluminium intermetallic feedstock. ESMA hazardous material protocols eliminate substandard imports, concentrating demand around certified regional blenders. The Jebel Ali coatings cluster centralizes project-scale procurement for decorative flake applications.
Kuwait
Industrial chemical applications remain underpenetrated relative to Saudi Arabia and the UAE, with limited domestic blending capacity. The country's national industrial safety regulator enforces port-of-entry inspections that favor established suppliers with documented handling capabilities. Shuaiba Industrial Area hosts nascent bulk packaging demand for pyrotechnic and catalyst formulations.
Qatar
Specialty alloy procurement for LNG infrastructure maintenance drives spherical powder demand with tight particle size tolerances. The national standardization body coordinates with Gulf Standardization Organization technical committees on unified testing protocols. Ras Laffan Industrial City concentrates chemical-grade consumption for offshore platform coating systems.
Oman
Sohar Port's free zone status attracts tolling arrangements for regional smelter output, positioning the sultanate as a logistics intermediary rather than terminal demand center. The Ministry of Commerce, Industry and Investment Promotion oversees industrial safety alignment with neighboring ESMA frameworks. Duqm Special Economic Zone offers first-mover positioning for bulk chemical applications serving underpenetrated Yemen and East African markets.
GCC Aluminium Powder Market Key Industry Players
On the supply side, the industry is bifurcated between integrated smelter-affiliated producers and independent specialty blenders. Three archetypes dominate: European pigment specialists with established Gulf distributor networks, Russian aluminium majors leveraging tolling partnerships, and regional aerospace-focused formulators. Competitive moves concentrate on dual-certification laboratory investment and unbundling of technical service from commodity supply.
Among European-based pigment specialists, Eckart GmbH and AMG Aluminum occupy positions anchored by premium supply lines into Dubai's coatings cluster and aerospace specification work across the Emirates. Rusal exemplifies the smelter-affiliated archetype, with volume availability tied to regional logistics partnerships. These three represent distinct competitive vectors: formulation expertise, alloy specialization, and upstream integration.
| Leading Market Players |
|---|
| Eckart GmbH |
| Valimet Inc. |
| Rusal |
| Sun Chemical Corporation |
| Silberline Manufacturing Co., Inc. |
| Toyo Aluminium K.K. |
| AMG Aluminum |
| Metal Powder Company Ltd. |
| Showa Denko K.K. |
| Others |
Cost & Logistics Intelligence
Russia's smelter-affiliated producers anchor upstream volume availability, concentrating margin capture in Dubai's coatings cluster where drum-format precision packaging commands technical service premiums over commodity flake supply.
Pricing Analysis
Volume-discount tiering structures separate aerospace-qualified spherical grades from construction-grade flake, with SAMR-aligned purity certification and ESMA hazardous material documentation driving premium-mid-economy pricing differentiation. Price differentiation hinges on atomization technology generation and dual-certified laboratory capacity. Margins are tightening in decorative flake as pearlescent pigment substitution accelerates across mid-tier Gulf finishes. Construction procurement desks exhibit highest price sensitivity; aerospace MRO facilities show lowest due to qualification lock-in costs.
Supply Chain Analysis
Export-control regimes limiting plasma atomization technology flows constrain Emirates-based additive manufacturing feedstock autonomy, forcing tolling arrangements with European and East Asian equipment holders. Geographic supply concentrates in Russia, the UAE, and Germany for spherical grades; China and India for milled flake alternatives. Raw material dependencies center on primary aluminium ingot, industrial gas supply, and specialty alloy element feedstock. Single-source vulnerability runs through Rusal's regional logistics partnerships. Distribution runs through certified regional blenders with documented SASO and ESMA handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC aluminium powder procurement is approaching a platform-economics inflection as digital B2B marketplaces unbundle formulation services from raw material supply, creating interoperability standards around Gulf Standardization Organization certification data.
For Market Incumbents: Harden dual-certified laboratory capacity across Saudi Arabia and the UAE to defend against plasma atomization technology diffusion that threatens gas atomization incumbency. Deepen backward integration into captive industrial gas supply to offset feedstock cost volatility. Lock in long-term tolling arrangements with Emirates Global Aluminium before atomization specialist scarcity intensifies.
For New Entrants and Emerging Players: Build out bulk packaging infrastructure in Kuwait's Shuaiba Industrial Area, where industrial chemical applications remain underpenetrated relative to Saudi and UAE markets. Target pyrotechnic and catalyst formulations as the most penetrable segment given limited domestic blending capacity. Pursue direct digital certification partnerships with Gulf Standardization Organization technical committees to bypass traditional distributor gatekeeping.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European pigment specialists holding established Gulf distributor networks but lacking additive manufacturing feedstock positioning. Five-to-ten year viability favors aerospace-focused formulators with plasma atomization pilot scale operations. Watch Emirates-based MRO facility qualification timelines as the inflection signal—local source certification compression would accelerate regional captive supply investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Laboratory Investment | Accelerates SASO and ESMA alignment for specialty alloy blenders serving aerospace MRO facilities. |
| Plasma Atomization Pilot Scale Deployment | Virtualizes gas atomization qualification pathways for titanium-aluminium intermetallic powders in Dubai. |
| Digital Procurement Platform Integration | Unbundles coating formulation from powder supply for mid-volume manufacturers seeking price transparency. |
| Backward Integration into Industrial Gas Supply | Captures margin compression from LME-linked primary aluminium ingot price volatility. |
| Kuwait Bulk Packaging Infrastructure Buildout | Positions first-mover advantage in underpenetrated industrial chemical applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across the GCC aluminium powder value chain, including atomization facility engineers, procurement leads at Dubai coatings manufacturers, Saudi construction group purchasing directors, and ESMA hazardous material compliance officers. Secondary validation drew from Gulf Standardization Organization technical committee documentation, SASO product registration filings, customs trade data for aluminium powder imports, and SEC disclosures from listed smelter operators. Bottom-up volume estimates triangulated against top-down consumption models across the analysis window.
Calibration approaches anchored forward projections to observed atomization capacity expansion timelines and qualification pathway compression rates. Segmentation dimensions modeled include particle morphology tier, application function, end-use industry certification requirements, packaging format, and regional industrial corridor concentration. CAGRs derived from slope-consistency checks against historical consumption elasticity to primary aluminium price movements and construction activity indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plasma atomization technology licensors or Gulf Standardization Organization protocol acceleration would shift outcomes. Material shifts in SAMR-aligned purity standard enforcement timelines or Emirates Global Aluminium tolling arrangement restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lanthanum Market
Metals
Galvanized Steel Coil Market
Metals
Rhodium Market
Metals
US Ferrochrome Market
Metals
Aluminum Tubes Market
Metals
Global Aluminum Market
Metals
Global Oxygen-Free Copper Market
Metals
Copper Azoles Market
Metals
Global Copper Sputtering Target Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Global Titanium Metal Market
Metals
Steel Casting Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Refined Nickel Market
Metals
Global Aluminium Wire Rod Market