
 Global Built and Natural Environment Consulting Market | 2026-2036
Global Built and Natural Environment Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Built and Natural Environment Consulting Market Analysis
The shift from single-source engineering contracts to multi-disciplinary consortium arrangements is pivoting how infrastructure owners procure advisory services. WSP Global Inc. leverages its integrated design and environment capabilities to anchor large-scale transit projects across North America and Europe. AECOM competes through its combined construction management and sustainability consulting platform, while Jacobs Engineering Group Inc. differentiates via deep specialization in water resource and environmental remediation advisory.
Built and natural environment consulting encompasses technical advisory services for the planning, design compliance, and ecological stewardship of constructed assets and surrounding ecosystems, typically delivered through multidisciplinary teams combining civil engineering, environmental science, and spatial analytics. Its primary commercial purpose is to reduce regulatory risk, optimize resource efficiency, and ensure infrastructure projects meet permitting requirements across jurisdictions. Sustainability Consulting commands premium pricing as building performance regulations tighten, while GIS Solutions within the Technology segment represents the fastest-expanding capability layer as clients demand real-time geospatial intelligence for land-use decisions. Project Management services remain the most mature revenue pool, though margin compression there pushes firms toward higher-value Planning Consultations.
The EPA enforces National Environmental Policy Act compliance for federally funded projects in the United States, directly shaping consultant procurement scopes and staffing requirements. EMA and ECHA frameworks under the EU Green Deal mandate embodied carbon disclosure for new construction, creating standardized demand for lifecycle assessment expertise across member states. Stakeholders must monitor how emerging digital twin mandates from regulators in China and South Korea reshape technology investment priorities and service delivery models.
Market Dynamics
The transition from fragmented, discipline-specific consulting contracts to integrated multi-disciplinary consortiums is compressing traditional procurement timelines and elevating firms with combined engineering-environmental-technology capabilities. This structural pivot rewards scale and cross-functional coordination while marginalizing single-service specialists.
Growth Catalysts
- EU Green Deal building performance mandates:ECHA embodied carbon disclosure requirements for new construction across member states are standardizing demand for lifecycle assessment advisory services.
- India's smart city corridor:Urbanization pressure along the Mumbai-Delhi axis is generating concentrated procurement for integrated planning and sustainability expertise from government agencies.
- Digital twin technology integration:Real-time geospatial intelligence capabilities are expanding consultant scopes from static compliance reporting to continuous environmental monitoring systems.
Market Restraints
- Specialized talent scarcity:The shallow pool of professionals combining civil engineering, environmental science, and spatial analytics expertise constrains service expansion velocity.
- Regulatory fragmentation:Divergent NEPA compliance requirements in the United States versus EMA frameworks in Europe force consultants to maintain jurisdiction-specific staffing duplications.
- Technology integration costs:Capital requirements for GIS platform investments and digital twin infrastructure create barriers for mid-sized advisory practices.
Strategic Opportunities
- Southeast Asia climate resilience procurement:Government agencies across Indonesia, Vietnam, and Thailand are expanding advisory service tenders for flood-resistant infrastructure design.
- Sustainability certification premium tier:Tightened building performance standards are creating price-insensitive demand segments for third-party environmental validation services.
- AI-enhanced spatial analytics convergence:Machine learning integration with traditional GIS Solutions is opening new service lines for predictive land-use modeling.
Industry Challenges
- Multi-disciplinary coordination complexity:Consortium arrangements require consultants to harmonize civil engineering, environmental science, and technology teams under unified project governance.
- Certification timeline compression:Accelerated permitting schedules for transit and water infrastructure projects strain traditional environmental review workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Built and Natural Environment Consulting Market |
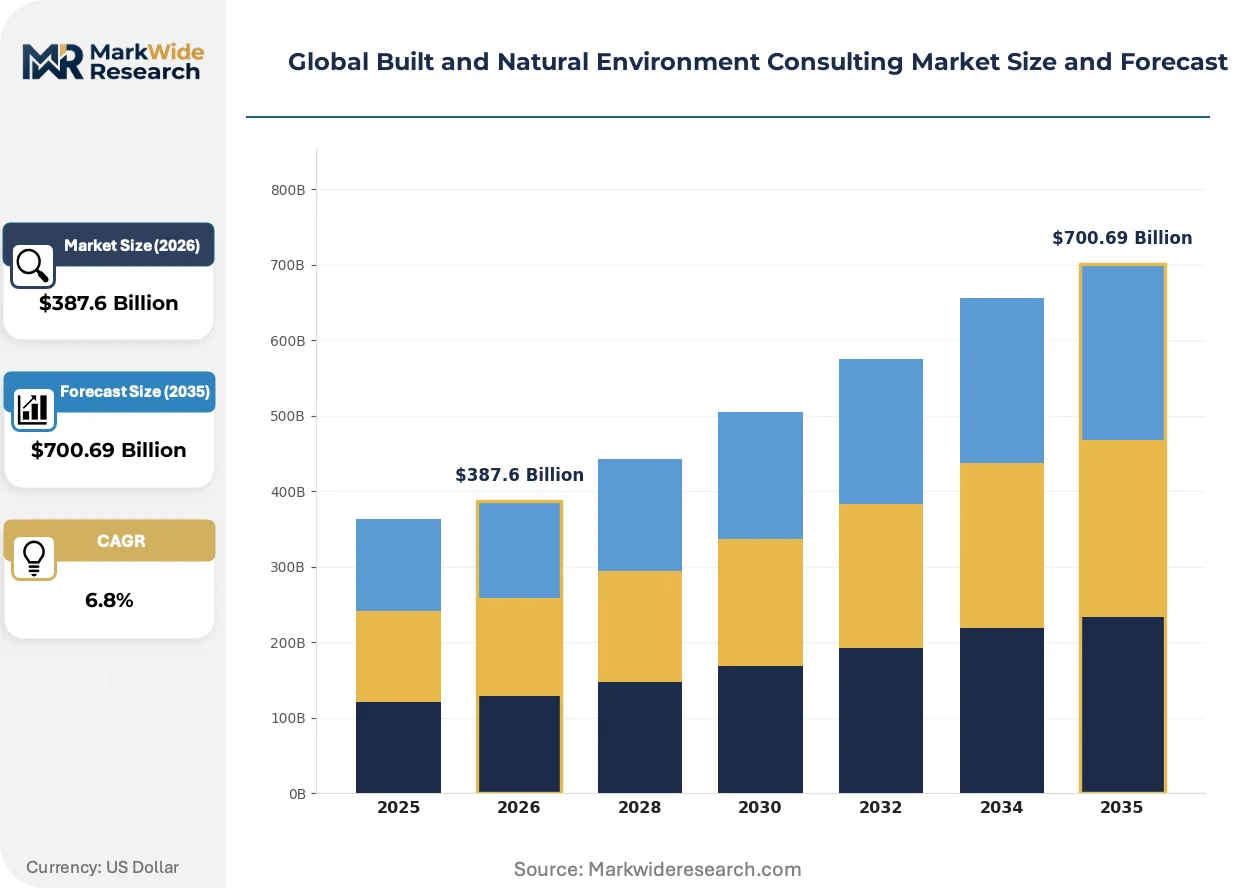
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Environmental Impact Assessments, Planning Consultations, Sustainability Consulting, Project Management End User: Government Agencies, Private Sector, Non-Profit Organizations, Academic Institutions Application: Urban Planning, Natural Resource Management, Infrastructure Development, Conservation Projects Technology: GIS Solutions, Data Analytics, Modeling Software, Simulation Tools |
| Companies Covered | Bechtel Corporation, SNC-Lavalin Group Inc., AECOM, Stantec Inc., Wood plc, WSP Global Inc., Worley, Jacobs Engineering Group Inc., Arup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Built and Natural Environment Consulting Market Emerging Trajectories
Advisory service delivery is pivoting from episodic project-based engagements toward continuous environmental intelligence partnerships. This evolution compresses the traditional design-permit-construct sequence while embedding consultants deeper into asset lifecycle management.
Digital twin technology is decentralizing environmental monitoring responsibilities from centralized regulatory agencies to distributed project stakeholders. Engineering firms are deploying sensor-integrated virtual replicas for real-time infrastructure performance tracking. Asset owners in North American transit and European water sectors are adopting these platforms to compress compliance reporting cycles from quarterly to continuous.
REACH regulation amendments under the EU Green Deal are mandating embodied carbon disclosure thresholds for construction materials imported into member states. This policy shift forces real estate developers to engage lifecycle assessment consultants earlier in design phases. German and French commercial property markets are responding fastest, integrating carbon accounting into standard procurement specifications.
Multi-year master service agreements are displacing single-project contracts for large infrastructure owners seeking integrated planning and compliance support. Engineering consultancies are restructuring fee models around outcome metrics rather than hourly billing. This pattern concentrates most visibly among North American transit authorities and Australian state infrastructure agencies managing pipeline portfolios exceeding ten-year horizons.
Global Built and Natural Environment Consulting Market Segmentation
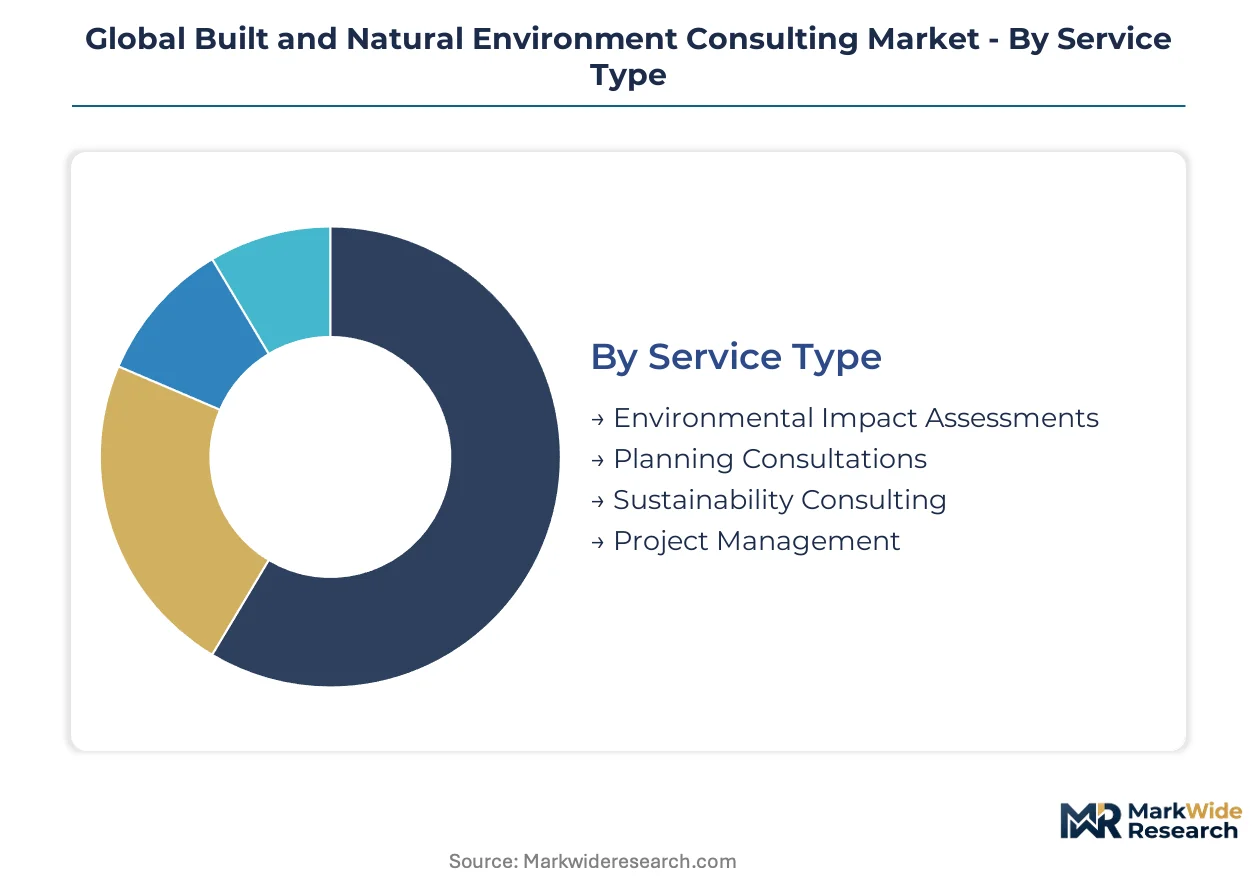
Segmentation in built and natural environment consulting reveals how procurement patterns split between standardized compliance services and customized advisory engagements. Understanding these divides helps vendors align capability investments with where margins concentrate and where volume scales.
Service Type:
Customization intensity varies sharply across this category, from templated regulatory filings to bespoke multi-year sustainability partnerships.
- Environmental Impact Assessments:Standardized documentation packages for permitting compliance, delivered through repeatable methodologies. Demand concentrates in US federally funded infrastructure where EPA NEPA enforcement mandates third-party review, though margin pressure from template commoditization pushes firms toward bundled offerings.
- Sustainability Consulting:Highly customized advisory spanning embodied carbon accounting, lifecycle assessment, and third-party certification support. EU Green Deal ECHA disclosure requirements for new construction in Germany and France are generating price-insensitive procurement as real estate developers front-load compliance into design phases.
- Planning Consultations:Integrated urban and regional strategy advisory combining spatial analytics with stakeholder engagement protocols.
- Project Management:Mature service line with established fee structures, facing compression as owners shift toward outcome-based contracting.
Leading the category by volume: Project Management. Expanding most quickly: Sustainability Consulting.
End User:
Procurement sophistication separates this category, from rigid public tender processes to flexible private sector negotiations.
- Government Agencies:Public infrastructure owners across India's Mumbai-Delhi smart city corridor and Southeast Asian climate resilience programs. India's urbanization mandates concentrate procurement for integrated planning expertise, while Indonesian, Vietnamese, and Thai agencies expand flood-resistant infrastructure advisory tenders.
- Private Sector:Real estate developers and industrial asset owners purchasing compliance and optimization services. REACH regulation amendments under EU Green Deal force earlier consultant engagement in German and French commercial property markets.
- Non-Profit Organizations:Conservation-focused entities procuring ecological stewardship advisory for protected area management.
- Academic Institutions:Research-driven contracting for environmental monitoring and longitudinal ecosystem studies.
Climbing the fastest: Government Agencies. Dominating revenue share: Private Sector.
Application:
Project duration and stakeholder complexity create distinct service delivery economics across this category.
- Urban Planning:Long-horizon engagements requiring continuous regulatory navigation and community interface. Smart city mandates in India compress traditional design-permit sequences while embedding consultants deeper into asset lifecycle management.
- Infrastructure Development:Large-scale transit and water projects across North America and Europe where digital twin mandates from regulators in China and South Korea reshape technology investment priorities.
- Natural Resource Management:Water resource and environmental remediation advisory requiring specialized scientific expertise.
- Conservation Projects:Biodiversity protection and habitat restoration programming with non-standard funding cycles.
Steepest expansion trajectory: Infrastructure Development. Highest margin concentration: Urban Planning.
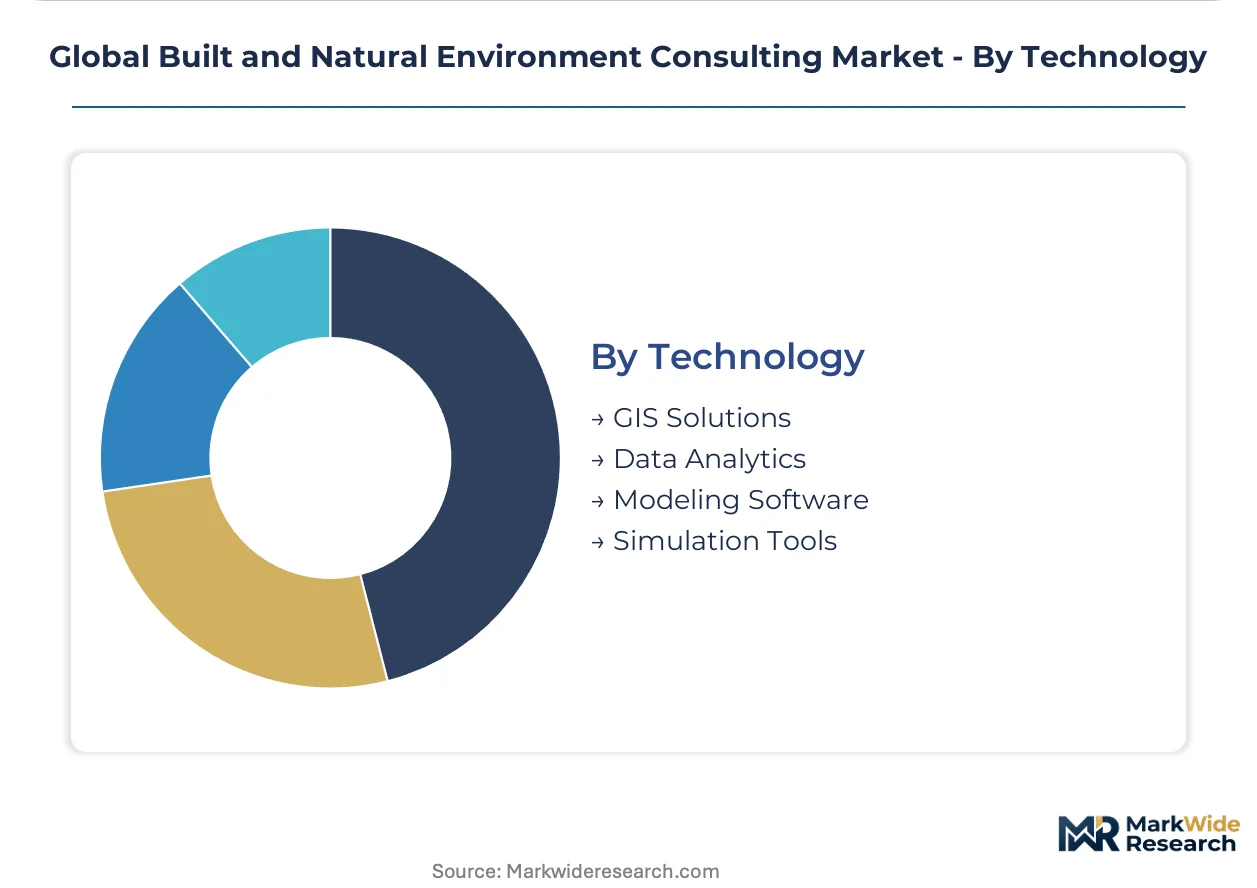
Technology:
Capital intensity and integration complexity segment this category from lightweight software subscriptions to sensor-embedded platform investments.
- GIS Solutions:Real-time geospatial intelligence capabilities expanding consultant scopes from static compliance reporting to continuous environmental monitoring. Asset owners in North American transit and European water sectors adopt sensor-integrated virtual replicas to compress reporting cycles from quarterly to continuous.
- Data Analytics:Machine learning integration opening predictive land-use modeling service lines as AI-enhanced spatial analytics converge with traditional advisory.
- Modeling Software:Simulation platforms for infrastructure performance prediction and scenario planning.
- Simulation Tools:Virtual prototyping environments for environmental impact projection and design optimization.
Gaining share fastest: GIS Solutions. Representing the largest deployment base: Modeling Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's limestone-rich western corridor anchors procurement for cement-intensive infrastructure advisory, while Germany's engineering density concentrates lifecycle assessment expertise demand. China's coastal manufacturing belt and the United States' federal infrastructure pipeline complete the primary geography set.
United States
Transit authorities in California and New York are compressing environmental review timelines for rail expansion projects. EPA NEPA enforcement mandates third-party review for all federally funded construction, expanding consultant procurement scopes. The Pacific Northwest corridor concentrates flood-resilient infrastructure advisory as FERC updates dam safety protocols.
Germany
Commercial real estate developers in Frankfurt and Munich are front-loading embodied carbon accounting into design phases. ECHA disclosure requirements under REACH amendments standardize demand for lifecycle assessment services. The Ruhr industrial cluster drives brownfield remediation advisory as state agencies accelerate coal transition site rehabilitation.
India
Government agencies along the Mumbai-Delhi smart city corridor are tendering integrated planning contracts spanning urban design and sustainability compliance. Bureau of Indian Standards building code updates mandate energy performance certification for new construction. Karnataka's Bengaluru Tech Hub concentrates demand for GIS-enabled spatial analytics in municipal master planning.
China
Provincial infrastructure commissions in Guangdong and Jiangsu are mandating digital twin integration for water resource management projects. Ministry of Ecology and Environment standards tighten environmental impact documentation for coastal development. The Yangtze River Delta manufacturing belt generates concentrated procurement for industrial site remediation advisory.
United Kingdom
Transport for London and Network Rail are adopting continuous environmental monitoring through sensor-integrated asset management platforms. Environment Agency flood defense procurement is expanding climate resilience advisory for Thames Estuary upgrades. The Cambridge-Oxford growth corridor concentrates biodiversity offset planning as housing development accelerates.
Global Built and Natural Environment Consulting Market Vendor Landscape
Strategic partnerships dominate the current landscape as engineering-environmental-technology capability integration accelerates procurement consolidation. The market structure tilts toward scale-driven multi-disciplinary platforms, with mid-sized specialists facing margin compression on single-service contracts. Three archetypes define positioning: integrated engineering-environmental conglomerates, technology-forward analytics platforms, and deep-specialist boutique practices. M&A activity and digital capability licensing represent the primary competitive vectors reshaping vendor rankings.
Within the integrated conglomerate tier, WSP Global Inc. and AECOM exemplify firms anchoring large-scale transit and water infrastructure advisory across North American and European markets. Jacobs Engineering Group Inc. occupies a position representing deep-specialist positioning in water resource and environmental remediation segments. These three entities collectively illustrate how cross-functional coordination capabilities determine consortium leadership in multi-disciplinary procurement environments.
| Leading Market Players |
|---|
| Bechtel Corporation |
| SNC-Lavalin Group Inc. |
| AECOM |
| Stantec Inc. |
| Wood plc |
| WSP Global Inc. |
| Worley |
| Jacobs Engineering Group Inc. |
| Arup |
| Others |
Supply Flow & Price Mechanics
North American transit authorities and Australian state infrastructure agencies purchasing multi-year master service agreements dominate procurement volume, anchoring a shift from hourly billing toward outcome-based fee structures that compress margins for single-service specialists while rewarding integrated platform capabilities.
Pricing Analysis
Service bundling separates lifecycle assessment and carbon accounting packages from unbundled environmental impact documentation, with EU Green Deal ECHA disclosure mandates in Germany and France generating price-insensitive demand for premium sustainability certification support. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization intensity. Pricing pressure stems from template commoditization in standardized NEPA compliance filings, squeezing margins on Environmental Impact Assessments. Government agencies exhibit highest price sensitivity due to rigid tender processes, while private real estate developers in Frankfurt and Munich show lowest sensitivity as they front-load embodied carbon accounting into design phases.
Supply Chain Analysis
Direct-to-agency channels handle government procurement demand across India's Mumbai-Delhi smart city corridor and Southeast Asian climate resilience programs, while consortium-led engagements serve private sector infrastructure owners. Geographic supply concentration centers on the United States, Germany, and India, where engineering talent pools and regulatory enforcement density cluster. The supply chain draws from specialized civil engineering labor, environmental science expertise, and GIS platform licensing as core inputs. Single-source vulnerability in multi-disciplinary talent combining engineering, environmental science, and spatial analytics constrains service expansion velocity. Distribution runs through multi-year master service agreements displacing single-project contracts for large infrastructure owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward control over digital twin infrastructure and AI-enhanced spatial analytics capabilities determines consortium leadership in multi-disciplinary procurement environments.
For Market Incumbents: Anticipate margin compression from technology-forward analytics platforms by deepening captive supply of GIS Solutions and digital twin infrastructure, while accelerating certification investment in lifecycle assessment expertise to defend against emerging AI-enhanced spatial analytics entrants. Anchor consortium leadership through cross-functional coordination capabilities spanning civil engineering, environmental science, and real-time geospatial intelligence. For New Entrants and Emerging Players: EU Green Deal ECHA disclosure requirements in Germany and France open a window for boutique lifecycle assessment specialists to penetrate price-insensitive real estate developer segments. Target India's Mumbai-Delhi smart city corridor for integrated planning and sustainability expertise tenders, where government agency procurement concentrates. Pursue technology licensing partnerships with established GIS platform providers as the primary go-to-market angle to bypass capital barriers. For Investors and Strategic Acquirers: The window for entry favors mid-sized specialists with deep vertical expertise in water resource advisory or environmental remediation segments. Long-term viability hinges on acquisition targets possessing multi-disciplinary talent pipelines and existing government agency relationships. Monitor digital twin mandates from regulators in China and South Korea as the signal for technology investment priority inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GIS Platform Integration | Real-time geospatial intelligence capabilities expand consultant scopes from static compliance to continuous environmental monitoring systems. |
| Lifecycle Assessment Certification | ECHA embodied carbon disclosure mandates under EU Green Deal standardize demand for third-party environmental validation services. |
| Multi-Disciplinary Consortium Formation | Integrated engineering-environmental-technology capabilities determine leadership in compressed procurement timelines for transit and water infrastructure. |
| Digital Twin Infrastructure Investment | Sensor-integrated virtual replicas compress compliance reporting cycles from quarterly to continuous for North American transit authorities. |
| AI-Enhanced Spatial Analytics Development | Machine learning integration opens predictive land-use modeling service lines as asset owners demand forward-looking environmental intelligence. |
Methodological Framework
Regulatory filings from EPA, ECHA, and India's Bureau of Indian Standards, trade data from engineering consultancy associations, and infrastructure procurement databases formed the secondary backbone, validated through primary interviews with transit authority planning officers, real estate development sustainability directors, environmental compliance managers at industrial asset owners, and GIS platform procurement leads at municipal agencies. Bottom-up service line revenue estimates triangulated against top-down market sizing from government infrastructure spending disclosures.
Historical trendline analysis of procurement contract values tracked the shift from single-project engagements toward multi-year master service agreements across the analysis window. Segmentation modeling incorporated service type customization intensity, end-user procurement sophistication, application project duration, and technology capital requirements as core dimensions. CAGRs derived from regression analysis of disclosed contract values and stated government infrastructure pipeline commitments, with digital twin adoption curves and smart city mandate implementation timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for digital twin integration; alternative pathways for AI-enhanced spatial analytics convergence would alter the outlook for GIS Solutions growth trajectories. Forecasts reflect assumptions regarding regulatory enforcement continuity for NEPA, ECHA, and BIS building code mandates, with tariff exposure on cross-border engineering talent mobility and commodity price volatility in sensor hardware representing specific revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Fume Hoods Market