
 Early Production Facility Market | 2026-2036
Early Production Facility Market Size, Share, and Industry Trends Forecast 2026-2036
Early Production Facility Market Analysis
Engineering-procurement-construction contracting is reshaping how early production capabilities reach field operators. Technip Energies leverages its modular fabrication yards to compress delivery schedules for offshore clients. SLB anchors its position through integrated project management spanning design through commissioning. Halliburton competes with portable separation and treatment packages sized for marginal fields.
Early production facilities are temporary or semi-permanent hydrocarbon processing installations engineered for rapid deployment, typically handling 5,000 to 50,000 barrels per day through skid-mounted separation, gas compression, and water treatment trains designed for 3-7 year operational lifespans before permanent infrastructure replacement. Modular Facilities command the dominant share due to repeatability and yard-based quality control, while Skid-Mounted Units represent the fastest-expanding category as independents seek asset-light entry into proven basins. Gas Processing technology leads the technology dimension because associated gas handling requirements have intensified under flaring restrictions.
EPA regulations in the United States and REACH compliance obligations in Europe constrain material selection and emissions profiles for temporary processing equipment, directly elevating engineering complexity and vendor qualification thresholds. Brazil's ANVISA and environmental licensing frameworks add another layer of local content and safety verification for deployed units. Stakeholders must weigh modular standardization against field-specific regulatory bundles when selecting deployment partners.
Market Dynamics
Modular fabrication standardization is compressing early production facility deployment timelines while EU F-Gas Regulation and EPA methane rules simultaneously elevate engineering complexity for temporary processing equipment. This structural tension between speed and compliance defines current competitive positioning.
Growth Catalysts
- Flaring restrictions:Associated gas handling mandates from the EPA and Brazil's ANP are forcing operators toward rapid gas processing deployment. Independent producers in the Permian Basin now prioritize skid-mounted compression trains to avoid production curtailments.
- Deepwater pre-salt economics:Brazil's layered local content requirements create captive demand for modular yards with ANVISA certification. Petrobras-linked contractors source standardized separation packages to accelerate first-oil at marginal subsalt discoveries.
- Unconventional well productivity:Extended lateral lengths in US shale basins generate front-loaded production profiles that favor temporary processing over permanent infrastructure commitments. Operators defer full-field development capital through 3-7 year EPF leases.
Market Restraints
- Specialized steel alloy costs:NACE-compliant materials for sour service applications command 40-60% premiums over standard carbon steel. Yards in Singapore and the US Gulf Coast face margin compression when nickel and molybdenum prices spike.
- Fabrication capacity concentration:Heavy modular construction clusters in South Korea, China, and the US Gulf Coast. Geopolitical friction or shipping bottlenecks through the Panama Canal disrupt delivery schedules for Atlantic basin projects.
- Electrification substitution:Grid-tied permanent facilities and renewable-powered subsea tiebacks reduce the addressable market for diesel-generator-dependent temporary installations. Norwegian operators increasingly bypass EPF stages for direct electrification.
Strategic Opportunities
- Carbon capture retrofit modules:EU Green Deal carbon border adjustments create demand for bolt-on CO2 separation skids. Modular amine units sized for 10,000-30,000 bpd flows enable compliance without permanent facility overhaul.
- Argentina Vaca Muerta entry:International independents lacking established Argentine operations require asset-light processing solutions. Skid-mounted units bypass the 18-24 month permitting timelines for permanent plant construction.
- Digital twin integration:Convergence of IoT sensors and cloud-based performance modeling allows remote optimization of distributed EPF fleets. Operators in the North Sea deploy predictive maintenance to extend temporary facility lifespans beyond original design limits.
Industry Challenges
- Welding inspector certification scarcity:ASME Section IX and API 1104 qualified radiographic interpreters command premium wages across US and Middle East fabrication yards. Project delays accumulate when third-party inspection capacity saturates during offshore construction peaks.
- Legacy SCADA integration:Temporary facilities must interface with operator-specific control architectures without permanent infrastructure investment. Commissioning teams face protocol mismatches between skid-mounted PLCs and host facility DCS systems.
Report Scope
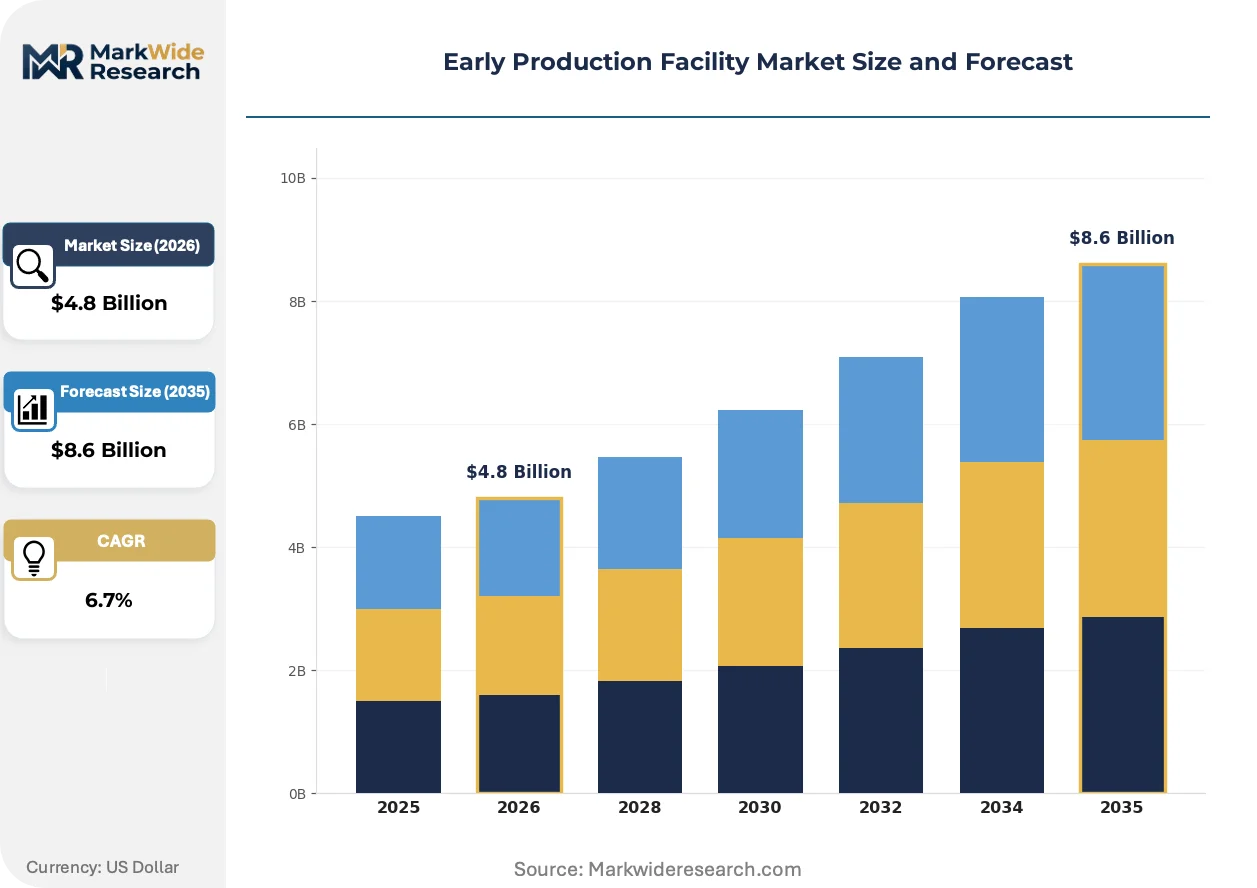
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Early Production Facility Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Facilities, Skid-Mounted Units, Standardized Equipment, Onshore Installations Technology: Gas Processing, Oil Separation, Water Treatment, Compression Solutions End User: Oil & Gas Companies, Independent Producers, Energy Investment Firms, Utilities Service Type: Design Services, Engineering Support, Modular Assembly, Maintenance Solutions |
| Companies Covered | Technip Energies, Expro Group, SLB, Wood Group, TETRA Technologies, Halliburton, Petrofac, Fluor Corporation, Weatherford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Early Production Facility Market Emerging Trajectories
Equipment miniaturization and process intensification are redefining throughput-density ratios for temporary hydrocarbon processing. Vendors now compete on footprint reduction and automated operation rather than raw capacity scaling.
High-pressure compact separation technology is migrating from subsea processing applications to surface-mounted early production facilities. Operators in the Norwegian Continental Shelf deploy these units to eliminate bulky three-phase separators and reduce platform weight by 30-40%. The technology is migrating from permanent offshore installations to temporary onshore shale applications where pad space constraints mirror topside limitations.
REACH compliance and EU F-Gas Regulation are banning hydrofluorocarbon refrigerants in gas dehydration and NGL recovery units. Equipment suppliers reformulate cooling circuits using ammonia or CO2-based alternatives that require redesigned pressure envelopes and safety systems. Modular fabricators in the Netherlands and Germany now pre-certify climate-neutral refrigeration packages for pan-European deployment.
Leasing structures are displacing traditional EPC contracting for marginal field development. Independents in the US Mid-Continent and West Africa now procure processing capacity as operational expenditure rather than capital commitment. This preference shift concentrates vendor risk on equipment lessors and rewards standardized, redeployable designs over field-optimized one-off installations.
Early Production Facility Market Segmentation
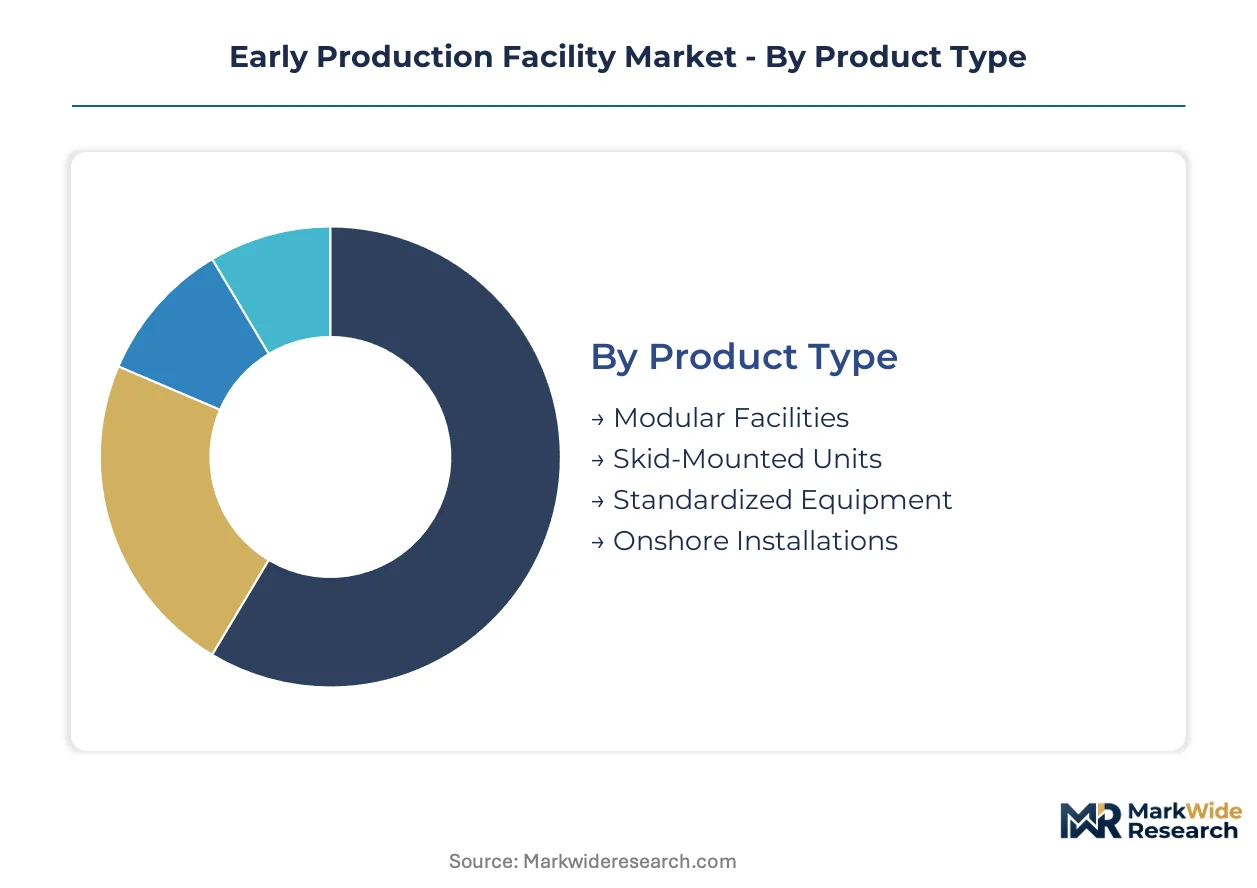
Early production facility procurement hinges on matching deployment speed with field-specific processing requirements. Operators select product architectures and technology bundles based on reservoir characteristics, regulatory exposure, and capital cycle positioning.
Product Type:
Cost tier differentiation separates permanent-equipment buyers from operators seeking operational expenditure flexibility.
- Modular Facilities:Yard-fabricated process trains with integrated separation, compression, and utilities housed in repeatable structural frames. Petrobras contractors in Brazil source these from ANVISA-certified yards to compress local content compliance timelines. Demand concentrates where project finance requires predictable delivery schedules and quality documentation.
- Skid-Mounted Units:Compact single-process packages mounted on structural steel bases for rapid field installation without permanent foundations. Permian Basin independents deploy these to avoid EPA flaring penalties while deferring full-field infrastructure capital. The segment is expanding most quickly among asset-light entrants.
- Standardized Equipment:Catalog-specified vessels and rotating machinery with minimal customization. Operators in mature North Sea fields procure these for predictable spare parts availability.
- Onshore Installations:Semi-permanent processing plants engineered for 5-10 year lifespans with modular expansion capability. Vaca Muerta developers in Argentina favor these to bypass extended permitting for permanent facilities.
Modular Facilities hold installed capacity. Skid-Mounted Units are rotating up the share rankings.
Technology:
Application intensity varies with reservoir fluid composition and regulatory flaring constraints.
- Gas Processing:Associated gas handling systems including dehydration, compression, and NGL recovery trains. EPA methane rules and Brazil ANP flaring restrictions are forcing deployment across US shale and pre-salt developments. The segment commands priority budget allocation where gas export infrastructure lags oil production ramp.
- Oil Separation:Three-phase and high-pressure compact separators removing water and solids from produced fluids. Norwegian Continental Shelf operators specify these to reduce platform weight and defer permanent topside investment. Demand tracks deepwater discovery rates and subsea tieback economics.
- Water Treatment:Produced water polishing and injection systems managing reservoir pressure maintenance. Middle East heavy oil projects require these for sustained production rates.
- Compression Solutions:Gas lift and export compression packages sized for declining field pressure profiles. US Gulf Coast fabricators specialize in API 618-compliant reciprocating units for sour service.
Gas Processing anchors technology investment. Compression Solutions is gaining share fastest as field pressures decline.
End User:
Customer type determines contracting structure and equipment ownership models.
- Oil & Gas Companies:Integrated operators with internal engineering capabilities and established vendor relationships. These buyers specify integrated EPF scopes linking to permanent facility handover protocols.
- Independent Producers:Capital-constrained operators prioritizing lease-based processing over ownership. US Mid-Continent and West African independents drive demand for redeployable skid-mounted units.
- Energy Investment Firms:Private equity-backed entities acquiring mature fields with deferred maintenance. These buyers favor operational expenditure structures and rapid production restoration.
- Utilities:Power generators and gas distributors seeking temporary supply security during infrastructure transitions.
Oil & Gas Companies dominate committed capital. Independent Producers are climbing the fastest in active project count.
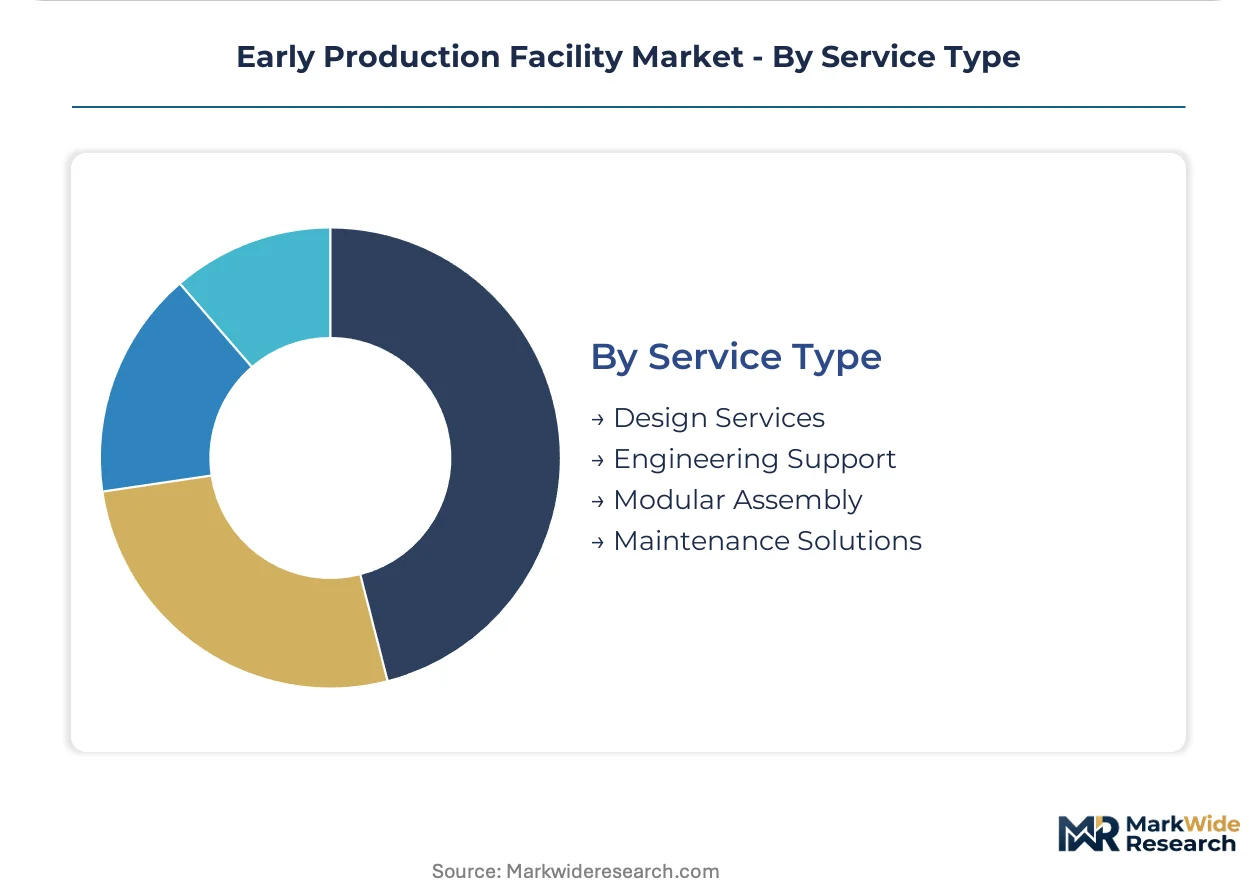
Service Type:
Margin capture shifts downstream from fabrication toward lifecycle support and digital integration.
- Design Services:Front-end engineering and process simulation defining equipment specifications and regulatory compliance pathways. EU F-Gas Regulation and REACH constraints elevate demand for climate-neutral refrigeration design.
- Engineering Support:Field supervision, commissioning, and performance optimization during operational phases. North Sea operators extend these contracts to maximize temporary facility utilization.
- Modular Assembly:Yard-based fabrication, integration, and pre-commissioning of process skids. Singapore and US Gulf Coast yards compete on welding inspector certification availability.
- Maintenance Solutions:Spare parts management, predictive maintenance, and end-of-life decommissioning. Digital twin integration is expanding contract value in remote deployments.
Modular Assembly captures fabrication value. Engineering Support is rotating up the share rankings as fleet complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal throughput constraints and US Gulf Coast liquefaction terminal buildouts concentrate early production facility demand across Atlantic and Pacific basin shipping lanes. Deepwater pre-salt discoveries and Permian Basin flaring enforcement anchor procurement volumes in the Americas.
United States
Permian Basin independents deploy skid-mounted gas compression to avoid EPA methane curtailment orders. FERC interstate pipeline approvals lag behind production growth, forcing temporary processing deployment. Houston-Galveston fabrication yards specialize in API-certified packages for shale operators.
Brazil
Petrobras contractors source ANVISA-certified modular separation trains for marginal pre-salt tiebacks. ANP flaring restrictions mandate associated gas handling before first-oil certification. Rio de Janeiro metropolitan yards dominate local content-compliant fabrication for subsalt developments.
Norway
Equinor-linked suppliers deliver compact separation units for electrified platform tiebacks. REACH and EU F-Gas Regulation constrain refrigerant selection for temporary NGL recovery. Stavanger-Bergen engineering clusters specialize in subsea-to-surface integration for declining North Sea fields.
Singapore
Jurong Island fabricators export skid-mounted water treatment packages to Southeast Asian marginal fields. The country's national environmental regulator enforces emissions standards for offshore equipment export. Singapore yards compete on welding inspector certification availability during regional construction peaks.
United Arab Emirates
ADNOC contractors lease modular gas processing for offshore sour gas developments. The country's national oil company mandates in-country value requirements for temporary facility deployment. Abu Dhabi industrial zones host assembly operations linking Asian fabrication to Middle East field schedules.
Early Production Facility Market Vendor Landscape
On the supply side, the industry is tiered between integrated EPC contractors and specialized modular fabricators. French and American engineering groups anchor the premium tier through project management capabilities. Mid-tier independents compete on lease-based pricing and redeployment speed. Consolidation pressure favors acquisition of regional yards with regulator pre-certification.
Within the integrated contractor tier, Technip Energies and SLB exemplify full-scope positioning spanning design through commissioning. Halliburton occupies a position among portable equipment specialists serving marginal field operators. These three anchors represent divergent strategic bets: yard-based standardization versus field-service integration versus asset-light leasing structures.
| Leading Market Players |
|---|
| Technip Energies |
| Expro Group |
| SLB |
| Wood Group |
| TETRA Technologies |
| Halliburton |
| Petrofac |
| Fluor Corporation |
| Weatherford |
| Others |
Supply Flow & Price Mechanics
Overcapacity at Singapore and US Gulf Coast fabrication yards is compressing contractor margins while simultaneously elevating buyer negotiating leverage for standardized modular packages. This utilization dynamic forces suppliers toward lease-based revenue models and accelerates consolidation among mid-tier fabricators lacking ANVISA or API certification premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified Brazilian yards from API-compliant US fabricators and uncertified Asian independents. Price differentiation hinges on welding inspector certification density and local content compliance documentation. Cost compression in the economy tier is intensifying because nickel and molybdenum alloy premiums erode fabricator margins. Independent producers in the Permian Basin exhibit highest price sensitivity, while Petrobras-linked contractors absorb certification premiums for schedule certainty.
Supply Chain Analysis
Contract manufacturing concentrates at Jurong Island Singapore yards, US Gulf Coast fabricators near Houston-Galveston, and Rio de Janeiro metropolitan facilities serving pre-salt developments. Raw material sourcing draws from South Korean steel mills for pressure vessels, German refrigeration component suppliers for F-Gas-compliant cooling circuits, and domestic Brazilian yards for local content mandates. Single-source vulnerability concentrates in ASME-certified welding inspector pools across US and Middle East construction peaks. Distribution runs through EPC contractor integration rather than direct operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation and EPA methane enforcement are disrupting established equipment specifications faster than incumbent certification cycles can adapt, creating asymmetric opportunity for modular fabricators with pre-certified climate-neutral refrigeration packages.
For Market Incumbents: Insulate margin position through captive welding inspector certification programs and backward integration into NACE-compliant alloy sourcing. Electrification substitution for diesel-generator-dependent installations threatens lease-based revenue streams; anchor defensibility through digital twin integration contracts that extend facility lifespans beyond original design limits.
For New Entrants and Emerging Players: Pursue Argentina Vaca Muerta deployment opportunities where 18-24 month permitting timelines for permanent facilities create captive demand for skid-mounted gas processing units. The most penetrable segment lies with international independents lacking established Argentine operations; differentiate through ANVISA certification partnerships that compress local content compliance timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across skid-mounted unit manufacturing as leasing structures displace traditional EPC contracting. Long-term viability favors equipment lessors with standardized, redeployable designs over field-optimized one-off installations. Target acquisition archetype: regional yards with regulator pre-certification and established welding inspector pipelines. The signal to watch is FERC interstate pipeline approval velocity in the Permian Basin, which dictates flaring-driven EPF demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Module Development | EU Green Deal carbon border adjustments create compliance-driven demand for bolt-on CO2 separation skids at 10,000-30,000 bpd scale. |
| Digital Twin Platform Integration | IoT sensor convergence with cloud-based performance modeling enables predictive maintenance contracts extending temporary facility utilization. |
| ANVISA Certification Acquisition | Brazilian regulatory pre-approval compresses local content timelines for Petrobras-linked marginal pre-salt tieback awards. |
| Refrigeration Circuit Redesign | REACH and F-Gas Regulation bans on hydrofluorocarbon refrigerants mandate ammonia or CO2-based alternatives with redesigned pressure envelopes. |
| Lease-Based Revenue Model Expansion | Operational expenditure structures concentrate vendor risk on equipment lessors and reward standardized, redeployable designs. |
Methodological Framework
A standing panel of EPC contract managers, modular fabrication yard supervisors, and upstream project development engineers provided ongoing calibration against field deployment realities. Primary interviews with these stakeholders combined with secondary validation from SEC filings of publicly traded contractors, ANP regulatory bulletins, and EPA methane enforcement records. Bottom-up project tracking across Brazil, the United States, Norway, and Argentina triangulated against top-down market sizing from equipment procurement databases.
Scenario-bracketing framed demand projections across low, base, and high cases reflecting Permian Basin flaring enforcement intensity and Petrobras pre-salt capital allocation shifts. Segmentation dimensions modeled include product architecture, processing technology bundle, end-user contracting structure, and regional regulatory cluster. CAGRs derived from equipment lease commencement records and EPC award announcements, with cross-reference to fabrication yard capacity utilization surveys and alloy price index movements.
Sensitivities concentrate around FERC pipeline approval velocity, nickel and molybdenum commodity spikes, and ANVISA certification backlog fluctuations. Forecasts reflect assumptions regarding electrification substitution rates and EU carbon border adjustment implementation scope. Cross-checking against IEA upstream investment outlooks and OPEC marginal field development announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Cold Storage Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Scandinavia Construction Market
Building Construction
Honduras Construction Market
Building Construction
Japan Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Spain Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Tunnels Design and Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Latin America Construction Market
Building Construction
Prefabricated Construction Market
Building Construction
Spain Prefabricated Buildings Market