
 Global HVAC Packaged Unit Market | 2026-2036
Global HVAC Packaged Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global HVAC Packaged Unit Market Outlook
Refrigerant technician shortages across North America and Europe is bifurcating the competitive landscape into those with captive training pipelines and those dependent on subcontractor networks. Carrier Global Corporation sustains its market position through extensive distributor certification programs that lock in installation capacity. Daikin Industries Ltd. leverages its captive refrigerant handling academies in Texas and Georgia to secure project timelines that competitors cannot match. Midea Group competes aggressively on manufacturing scale, though its reliance on third-party service networks creates vulnerability in markets where technician density lags equipment deployment.
Global HVAC packaged units are self-contained climate control systems integrating compressors, condensers, evaporators, and air handlers within factory-sealed enclosures, typically rated between 3 and 150 tons cooling capacity, designed for single-point electrical and ducted distribution connections in commercial and light industrial buildings. Rooftop units dominate installed base economics in North American strip retail and warehouse segments, where standardized curb mounting reduces field labor and permits rapid swap-out during tenant turnovers. Variable refrigerant flow technology is displacing conventional chiller-fed architectures in mid-rise commercial spaces across Asia-Pacific, driven by zoning flexibility and reduced refrigerant charge volumes per floor plate. Heat pumps represent the fastest-growing product configuration in European retrofit installations, where regulatory bans on fossil fuel heating in new construction are redirecting specification decisions toward electric-only systems.
The US Department of Energy enforces minimum efficiency standards under 10 CFR Part 431, while the EPA regulates refrigerant phase-down through its Section 608 program and AIM Act implementation timelines, collectively forcing manufacturers to redesign coil geometries and compressor architectures ahead of compliance deadlines. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive create parallel certification burdens that filter non-compliant suppliers from European procurement channels. Stakeholders must monitor refrigerant transition roadmaps and workforce development investments as tightly as they track equipment cost curves, since installation capacity constraints will determine which manufacturers can convert specification wins into revenue realization.
Market Dynamics
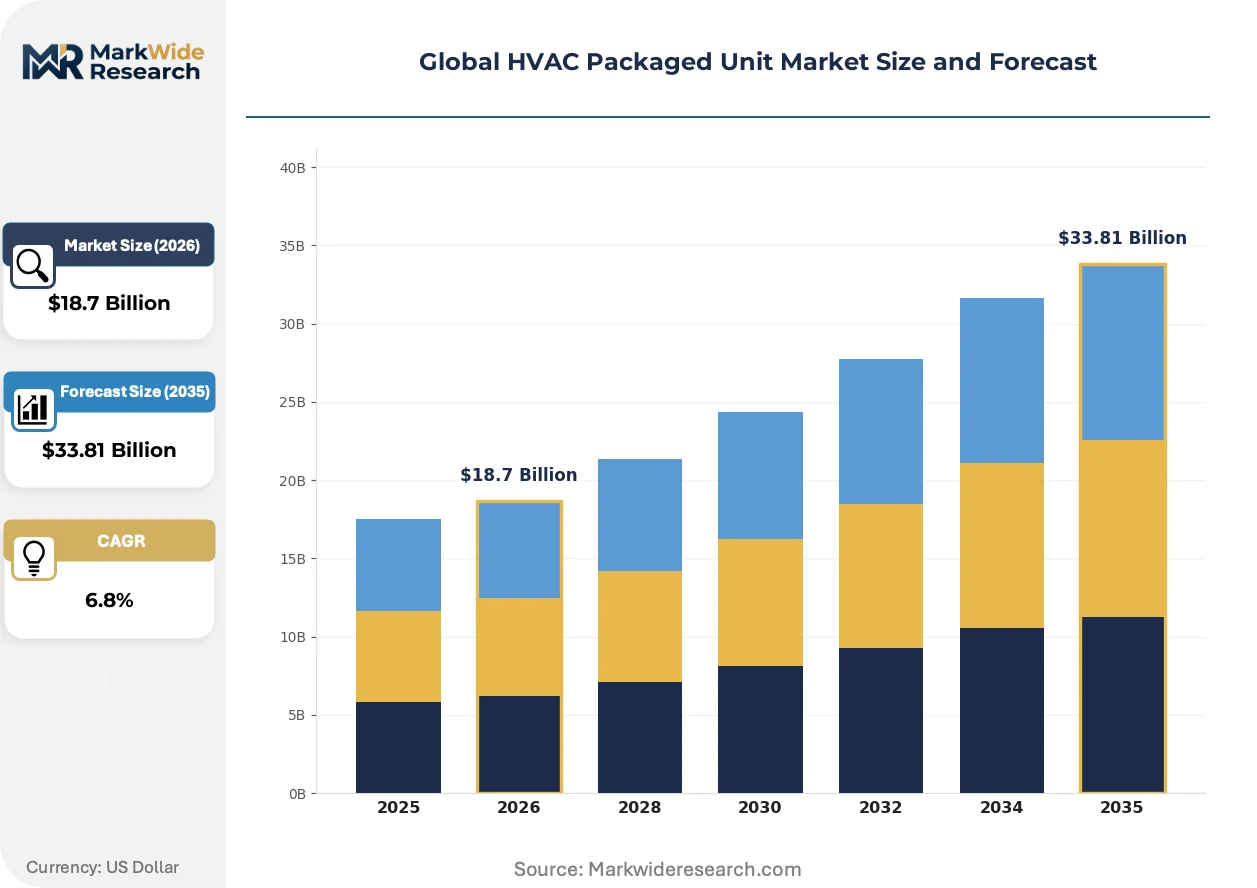
Variable refrigerant flow architectures are forcing coil geometry redesigns across the supply base as refrigerant charge volumes per floor plate compress installation footprints and labor requirements in mid-rise commercial construction.
Growth Catalysts
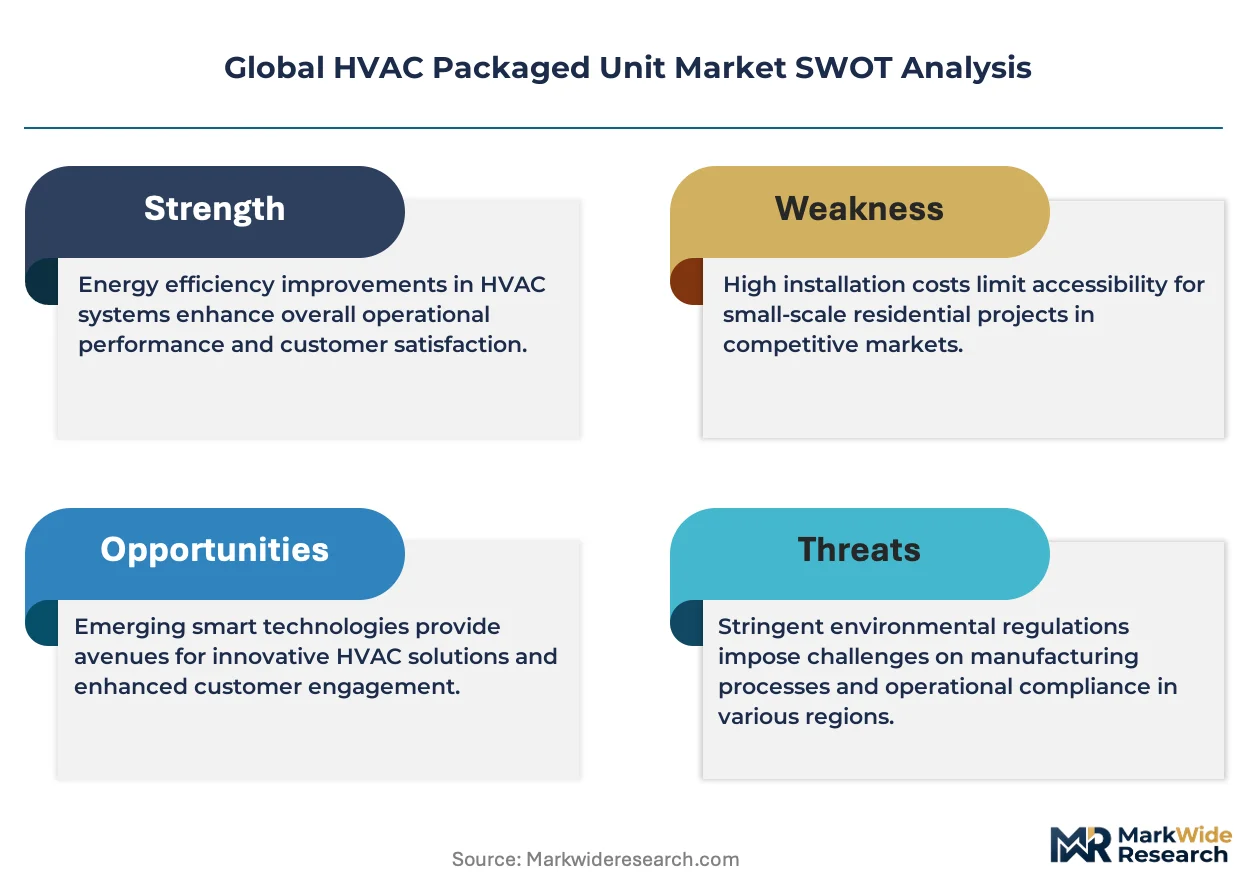
- US DOE 10 CFR Part 431 mandates:Minimum efficiency standards are accelerating equipment replacement cycles in existing commercial building stock across the United States.
- Urban rooftop deployment:Southeast Asian commercial real estate developers are expanding curb-mounted unit installations as tenant turnover velocity increases in retail and warehouse segments.
- R-454B refrigerant transition:Lower global warming potential formulations are opening specification pathways for manufacturers with certified handling protocols and captive technician pipelines.
Market Restraints
- Copper and aluminum input volatility:Coil material costs fluctuate with commodity markets, compressing margin buffers for manufacturers without long-term supply agreements.
- Refrigerant technician scarcity:North America and Europe face acute shortages in EPA Section 608-certified installers, capping revenue conversion for brands dependent on third-party service networks.
- Legacy chiller infrastructure:Central plant architectures in existing commercial buildings create switching friction against packaged unit retrofits despite efficiency advantages.
Strategic Opportunities
- India replacement acceleration:Bureau of Indian Energy Efficiency mandates are shortening equipment lifecycles and creating upgrade demand across existing building stock.
- Heat pump configuration expansion:European fossil fuel heating bans in new construction are redirecting specification decisions toward electric-only packaged systems.
- Connected diagnostics integration:IoT-enabled predictive maintenance modules are creating recurring revenue streams and locking in aftermarket relationships with facility managers.
Industry Challenges
- AIM Act compliance timelines:EPA refrigerant phase-down schedules require simultaneous redesign of compressor architectures and coil geometries ahead of fixed deadlines.
- EU F-Gas certification burdens:CE marking requirements under the Machinery Directive filter non-compliant suppliers from European procurement channels.
- Subcontractor network reliability:Installation capacity constraints in technician-scarce markets prevent manufacturers from converting specification wins into realized revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HVAC Packaged Unit Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rooftop Units, Split Systems, Heat Pumps, Portable Units Technology: Variable Refrigerant Flow, Chiller Systems, Evaporative Cooling, Air-Cooled End User: Residential Buildings, Commercial Spaces, Industrial Facilities, Educational Institutions Installation: On-Site, Prefabricated, Retrofit, New Construction |
| Companies Covered | Daikin Industries Ltd., Carrier Global Corporation, Trane Technologies plc, Johnson Controls International plc, Midea Group, LG Electronics, Mitsubishi Electric Corporation, Lennox International Inc., Bosch Thermotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HVAC Packaged Unit Market Strategic Shifts
Refrigerant chemistry transitions, efficiency mandate compressions, and workforce capability gaps are simultaneously reshaping product architectures and go-to-market structures across the supply base.
Variable refrigerant flow technology is supplanting conventional chiller-fed architectures in mid-rise commercial spaces across Asia-Pacific. Property developers in Singapore and Bangkok are specifying zoned VRF systems for floor plates under 50,000 square feet. The technology is supplanting centralized plant rooms and reducing field refrigerant handling requirements per installation.
The EPA's AIM Act implementation timelines are forcing compressor redesigns ahead of R-410A phase-down milestones. Manufacturers must certify new coil geometries and lower-charge architectures under Section 608 protocols. European suppliers face parallel pressure from EU F-Gas Regulation quotas, with the tightest compliance windows hitting rooftop unit configurations first.
Facility managers are unbundling after-sales service from equipment procurement, creating direct relationships with certified technician networks. Third-party service aggregators in Germany and France are capturing maintenance contracts that manufacturers previously held through distributor channels. This shift is most visible in retail and warehouse verticals where tenant turnover accelerates equipment swap-out frequency.
Global HVAC Packaged Unit Market Segmentation
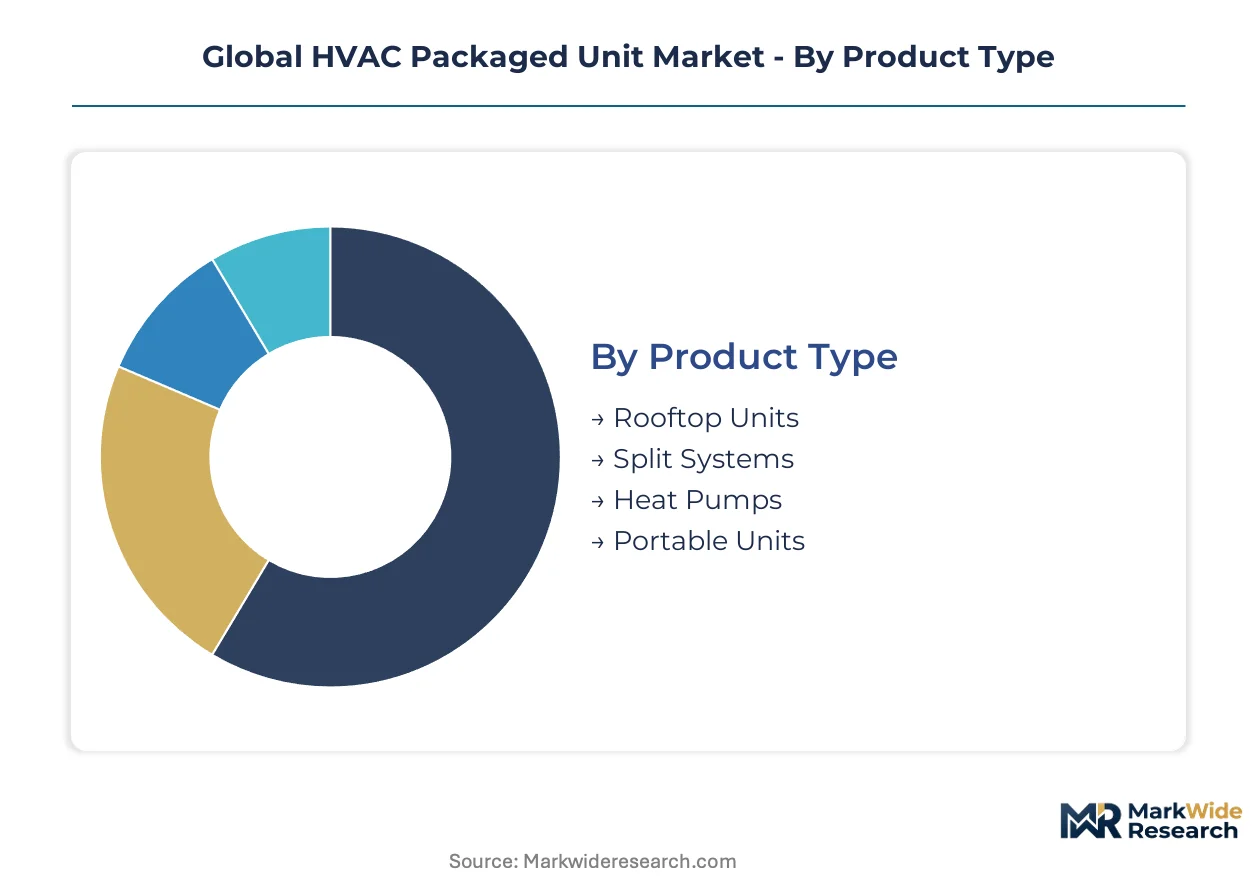
Segmentation in the Global HVAC Packaged Unit Market reveals how substitution pressures from adjacent technologies reshape competitive boundaries across product architectures. Each dimension exposes distinct vulnerability surfaces where manufacturers defend installed base positions or cede ground to alternative climate control approaches.
Product Type:
Rooftop units face the most acute substitution threat from VRF architectures in mid-rise commercial construction, while portable units compete against permanent split system retrofits in tenant improvement cycles.
- Rooftop Units:Factory-sealed enclosures integrate compressors, condensers, and air handlers within 3-150 ton cooling capacity ratings. Curb-mounted deployments dominate North American strip retail and warehouse segments where standardized electrical and ducted connections reduce field labor during tenant turnovers.
- Heat Pumps:Electric-only systems capture specification wins in European new construction where fossil fuel heating bans redirect procurement decisions toward packaged electric configurations. Regulatory mandates in Germany and France accelerate displacement of gas-fired alternatives in commercial retrofits.
- Split Systems:Separate indoor and outdoor units serve residential and light commercial applications with flexible installation footprints.
- Portable Units:Self-contained mobile configurations address temporary cooling requirements in event spaces and construction site offices.
Rooftop units anchor the volume base across North American commercial stock while heat pumps gain share at the steepest rate under European decarbonization mandates.
Technology:
Cost tier stratification separates premium VRF architectures from standardized air-cooled units, with chiller systems defending position only in largest floor plate applications.
- Variable Refrigerant Flow:Zoned refrigerant distribution reduces charge volumes per floor plate and compresses installation footprints in Singapore and Bangkok mid-rise developments. Property developers specify VRF for floor plates under 50,000 square feet where centralized plant rooms prove economically unviable.
- Air-Cooled:Condenser heat rejection through ambient airflow eliminates cooling tower infrastructure and water treatment costs. Standardized configurations dominate budget-constrained procurement in Indian commercial construction where first-cost sensitivity outweighs lifecycle efficiency considerations.
- Chiller Systems:Centralized chilled water distribution serves large floor plates and campus-style developments with high simultaneous cooling loads.
- Evaporative Cooling:Water-based heat rejection achieves efficiency advantages in arid climate zones with low wet-bulb temperatures.
Air-cooled systems maintain volume leadership in cost-sensitive procurement channels while variable refrigerant flow climbs the fastest in premium mid-rise specifications.
End User:
Application maturity varies sharply, with educational institutions representing the most penetrated vertical and industrial facilities showing the strongest retrofit acceleration.
- Commercial Spaces:Retail, office, and hospitality deployments constitute the core revenue base with highest equipment density per square meter. Tenant turnover velocity in Southeast Asian urban centers drives replacement cycle compression and rooftop unit swap-out frequency.
- Industrial Facilities:Process cooling and warehouse climate control applications demand ruggedized configurations with extended operating envelopes. Manufacturing clusters in Vietnam and Indonesia expand deployment as foreign direct investment flows into export-oriented production capacity.
- Residential Buildings:Multi-family and single-family applications favor split system architectures over packaged units due to installation flexibility constraints.
- Educational Institutions:School and university campuses represent mature installed base with standardized procurement through public sector tender processes.
Commercial spaces anchor the volume base through recurring tenant-driven replacement cycles while industrial facilities expand most quickly under manufacturing relocation trends.
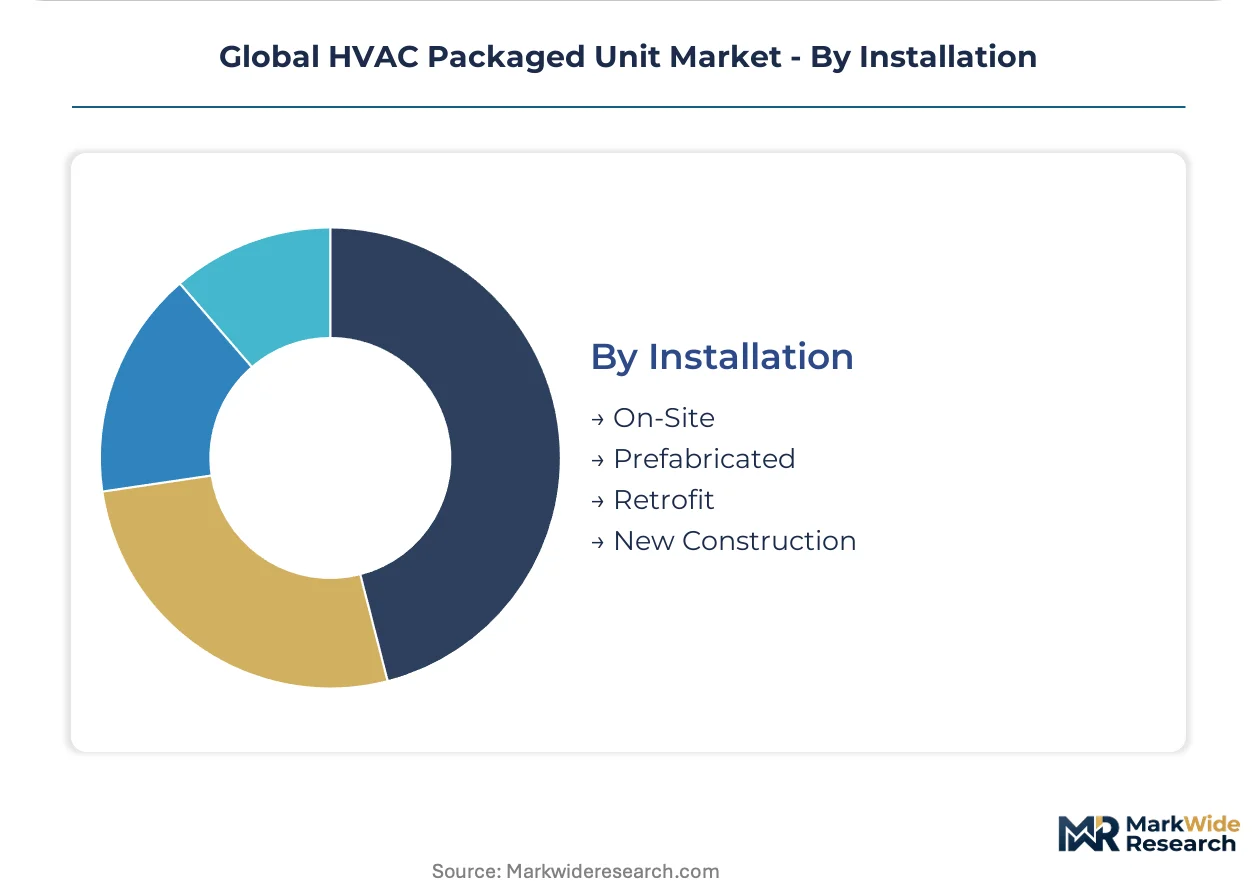
Installation:
Customer type bifurcation separates new construction specification from retrofit replacement, with prefabricated modules emerging as the margin-accretive hybrid.
- New Construction:Integrated design-build workflows allow optimized equipment sizing and ducted distribution routing before structural closure. Indian urban commercial developments accelerate specification as Bureau of Energy Efficiency mandates shorten allowable equipment lifecycles in building code compliance.
- Retrofit:Existing building stock replacement confronts spatial constraints and legacy distribution infrastructure limitations. US commercial real estate owners face DOE efficiency standard compliance deadlines that force accelerated swap-out of pre-standard equipment.
- On-Site:Traditional field assembly and commissioning maintains dominance in custom architectural configurations.
- Prefabricated:Factory-integrated modules reduce field labor and accelerate project timelines in standardized building typologies.
New construction anchors the volume base through integrated project delivery workflows while retrofit applications expand most quickly under regulatory replacement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency anchors the dominant geography through its AIM Act implementation timelines and Section 608 refrigerant handling protocols. These regulations cascade into equipment redesign requirements that reshape procurement patterns across North American commercial building stock. Distinct national regulatory environments now determine where manufacturers can convert specification advantages into installed revenue.
United States
Commercial real estate developers in Texas and Florida accelerate rooftop unit deployments as tenant turnover velocity increases in warehouse and retail segments. The Department of Energy's 10 CFR Part 431 mandates force equipment replacement cycles in existing building stock ahead of efficiency compliance deadlines. Atlanta and Dallas-Fort Worth industrial clusters concentrate specification decisions for mid-rise commercial developments under 50,000 square feet.
Germany
Facility managers unbundle after-sales service from equipment procurement as third-party service aggregators capture maintenance contracts in retail and warehouse verticals. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive filter non-compliant suppliers from European procurement channels. The Rhine-Ruhr metropolitan region drives heat pump specification in commercial retrofits where fossil fuel heating bans redirect decisions toward electric-only systems.
India
The Bureau of Indian Energy Efficiency mandates shorten allowable equipment lifecycles in building code compliance for new urban commercial developments. Central Electricity Authority regulations intersect with state-level energy conservation codes to accelerate replacement demand across existing building stock. Mumbai and Bangalore construction clusters specify air-cooled configurations where first-cost sensitivity outweighs lifecycle efficiency considerations in budget-constrained procurement.
Singapore
Property developers specify zoned variable refrigerant flow systems for floor plates under 50,000 square feet where centralized plant rooms prove economically unviable. The country's national energy regulator enforces green building standards that compress installation footprints and labor requirements in mid-rise commercial construction. The Marina Bay and Jurong Lake District development corridors anchor VRF adoption rates in Southeast Asian urbanization patterns.
Japan
Manufacturing clusters in Osaka and Nagoya expand deployment of ruggedized configurations with extended operating envelopes for process cooling applications. The Ministry of Economy, Trade and Industry oversees JIS standards compliance that shapes coil geometry redesigns across the supply base. Industrial facility retrofits in the Chubu region demonstrate the fastest acceleration under manufacturing relocation trends and foreign direct investment flows.
Global HVAC Packaged Unit Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the supply base. The market structure concentrates around diversified industrial conglomerates with captive refrigerant handling capabilities and scale-driven manufacturers dependent on third-party service networks. Three archetypes dominate: integrated technology specialists with proprietary training pipelines, volume manufacturers competing on production scale, and regional system integrators with localized installation capacity. Competitive moves center on workforce development investments and refrigerant transition readiness ahead of fixed compliance deadlines.
Within the integrated technology tier, Daikin Industries Ltd. and Carrier Global Corporation exemplify archetypes that secure project timelines through captive technician pipelines. Daikin anchors positioning through refrigerant handling academies in Texas and Georgia. Carrier sustains market presence through distributor certification programs that lock in installation capacity. Midea Group occupies a position at the scale-driven end, competing aggressively on manufacturing output though its reliance on third-party service networks creates vulnerability in technician-scarce markets. These three represent the structural fault lines determining which manufacturers convert specification wins into realized revenue.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Carrier Global Corporation |
| Trane Technologies plc |
| Johnson Controls International plc |
| Midea Group |
| LG Electronics |
| Mitsubishi Electric Corporation |
| Lennox International Inc. |
| Bosch Thermotechnology |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85 percent in Chinese compressor manufacturing compress cost floors across the supply base while simultaneously concentrating bargaining power among tier-one OEMs. This scale concentration shapes price formation through volume-commitment contracts that lock in coil and compressor supply ahead of refrigerant transition deadlines.
Pricing Analysis
Price spreads between German and Indian procurement markets exceed 40 percent for equivalent tonnage ratings, reflecting certification tier stratification and logistics cost differentials. Three-tier pricing structure across premium certified, standard efficiency, and economy air-cooled configurations dominates transactional patterns. Cost compression in economy tiers is intensifying because Indian developers prioritize first-cost outlays over lifecycle efficiency. Small commercial contractors in Southeast Asia exhibit highest price sensitivity, while European facility managers accept premium tiers for F-Gas compliance certainty.
Supply Chain Analysis
Inventory cycles stretching 16-20 weeks for copper tube-and-fin coils expose manufacturers to commodity price volatility ahead of seasonal demand peaks. Manufacturing concentrates in China, Mexico, and Thailand for final assembly, while Japan and Germany anchor precision compressor and control component production. Raw material dependencies center on copper cathode, aluminum coil stock, and rare-earth magnet feedstocks for high-efficiency motors. Single-source vulnerability in semiconductor-based inverter controls threatens production continuity. Distribution runs through authorized dealer networks with captive installation capacity in North America and Europe, shifting toward direct procurement by project developers in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected diagnostics platforms are redefining competitive boundaries by unbundling equipment from recurring service revenue, creating interoperability standards that favor first-movers with API-open architectures.
For Market Incumbents: Shield installed base positions by deepening captive technician pipelines ahead of R-454B certification deadlines. Accelerate backward integration into coil manufacturing to offset copper volatility exposure. VRF substitution in mid-rise commercial segments threatens rooftop unit margins most acutely in Singapore and Bangkok development corridors. For New Entrants and Emerging Players: Anchor in India's retrofit replacement acceleration where Bureau of Energy Efficiency mandates compress equipment lifecycles and dislodge incumbent relationships. Target industrial facility verticals in Vietnam and Indonesia where foreign direct investment flows exceed local service capacity. Pursue OEM-private-label partnerships with Midea-scale manufacturers to bypass distributor certification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated technology specialists with proprietary refrigerant handling academies over scale-dependent assemblers. Long-term viability hinges on conversion of specification wins into realized revenue through installation capacity control rather than manufacturing throughput alone. Watch technician certification velocity by EPA Section 608 and EU F-Gas pathways as the inflection signal distinguishing revenue converters from specification also-rans.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Technician Academy Expansion | Locks in installation capacity ahead of R-454B handling certification deadlines under EPA Section 608 protocols. |
| Backward Integration into Coil Manufacturing | Insulates margin buffers from copper and aluminum commodity volatility through in-house tube-and-fin production. |
| Connected Diagnostics Platform Launch | Creates recurring revenue streams through IoT-enabled predictive maintenance modules tied to facility management contracts. |
| VRF Architecture Certification Investment | Secures specification pathways in Singapore and Bangkok mid-rise developments under 50,000 square feet. |
| Heat Pump Configuration Scale-Up | Captures European new construction demand redirected by fossil fuel heating bans in Germany and France. |
Study Parameters
A spread of perspectives from HVAC equipment procurement managers, refrigerant handling technicians, commercial real estate developers, and facility management directors converged on the working assumptions governing replacement cycle timing and specification criteria. Primary fieldwork combined structured interviews with distributor network heads and aftermarket service aggregators across North America, Europe, and Asia-Pacific. Secondary validation drew from EPA Section 608 enforcement data, EU F-Gas Regulation quota filings, Bureau of Indian Energy Efficiency compliance schedules, and customs records tracking compressor and coil trade flows. Bottom-up equipment shipment tallies by tonnage rating and top-down construction spend attribution were triangulated against regulatory mandate calendars.
Segmentation dimensions modeled span product architecture, refrigerant technology type, end-use vertical, installation context, and regional regulatory cluster. Volume and value outputs across the projection horizon reflect equipment replacement cycles triggered by efficiency mandate deadlines, new construction specifications, and tenant turnover velocity. CAGRs were derived from regression against historical shipment patterns and forward-projected regulatory compliance windows. Industry-specific forecast inputs include technician certification pipeline capacity by geography and refrigerant chemistry transition timelines under AIM Act and F-Gas Regulation schedules.
Material uncertainties — commodity price spikes, refrigerant supply disruptions, and workforce development shortfalls — sit outside the modeled envelope and could compress or extend replacement cycles independently of regulatory calendars. Forecasts reflect documented assumptions regarding compliance deadline adherence and installation capacity scaling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Global Heat Exchangers Market