
 Italy Commercial HVAC Market | 2026-2036
Italy Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Commercial HVAC Market Insights
Italy is reconfiguring its commercial HVAC supply base through expanded manufacturing footprints in northern industrial zones. Daikin Industries Ltd. anchors premium variable refrigerant flow production from its Italian facilities, while Carrier Corporation leverages extensive service networks across the peninsula. Johnson Controls International PLC competes on building automation integration, and Danfoss A/S specializes in compressor and controls technology for hydronic applications.
Italy Commercial HVAC comprises centralized and decentralized climate systems engineered to regulate temperature, humidity, and air quality across non-residential built environments, typically operating within coefficient of performance ranges of three to six for heat pump configurations. These systems serve commercial structures through mechanical ventilation, refrigeration cycles, and thermal distribution networks designed for continuous occupancy loads. Chillers retain the largest installed base among product types, though heat pumps are capturing disproportionate investment as electrification mandates intensify. Variable Refrigerant Flow technology leads technology segmentation in new office construction, while retrofit installations dominate the installation type mix as aging building stock requires efficiency upgrades.
EU F-Gas Regulation and Ecodesign directives enforced by Italian environmental agencies are accelerating refrigerant transitions and minimum efficiency thresholds. CE marking requirements under the Machinery Directive govern market access for imported equipment assemblies. Stakeholders must monitor refrigerant quota allocations and local incentive structures for building energy renovation to align procurement timelines with compliance deadlines.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant availability and forcing premature equipment replacement across Italy's aging commercial building stock. This regulatory pressure intersects with electrification mandates to reshape capital allocation and vendor selection criteria.
Growth Catalysts
- Hospital Infrastructure Modernization:Italian healthcare facilities are replacing legacy climate systems with high-efficiency heat pumps to meet energy renovation targets and infection control standards.
- F-Gas Phase-Down Schedules:The EU F-Gas Regulation is accelerating equipment turnover as quota restrictions tighten refrigerant supply for service and replacement.
- Lombard Industrial Corridors:Manufacturing concentration around Milan generates sustained demand for process cooling and precision climate control in pharmaceutical and food processing facilities.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and coil manufacturing faces margin pressure from commodity price swings in base metals essential to thermal transfer equipment.
- Refrigerant Supply Concentration:European quota allocation mechanisms create bottleneck risk for HFO and natural refrigerant alternatives during peak replacement seasons.
- Grid Capacity Constraints:Electrified HVAC loads strain distribution infrastructure in dense urban cores, limiting simultaneous adoption rates across multiple buildings.
Strategic Opportunities
- Southern Italy Building Stock:Underpenetrated commercial real estate in Sicily and Calabria offers first-mover positioning as energy efficiency incentives expand beyond northern industrial zones.
- Building Automation Convergence:Integration of HVAC controls with IoT sensors and predictive analytics creates service revenue streams beyond equipment sales.
- Superbonus 110% Incentive Extensions:Italian tax deduction structures for building energy renovation sustain demand acceleration for qualifying high-efficiency system upgrades.
Industry Challenges
- Natural Refrigerant Technician Scarcity:CO2 and ammonia system installation and service requires specialized certification pathways that training institutions have not scaled to match equipment deployment rates.
- Legacy Control Integration Complexity:Retrofit projects face commissioning delays when connecting modern variable-speed equipment to existing pneumatic or early digital building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Commercial HVAC Market |
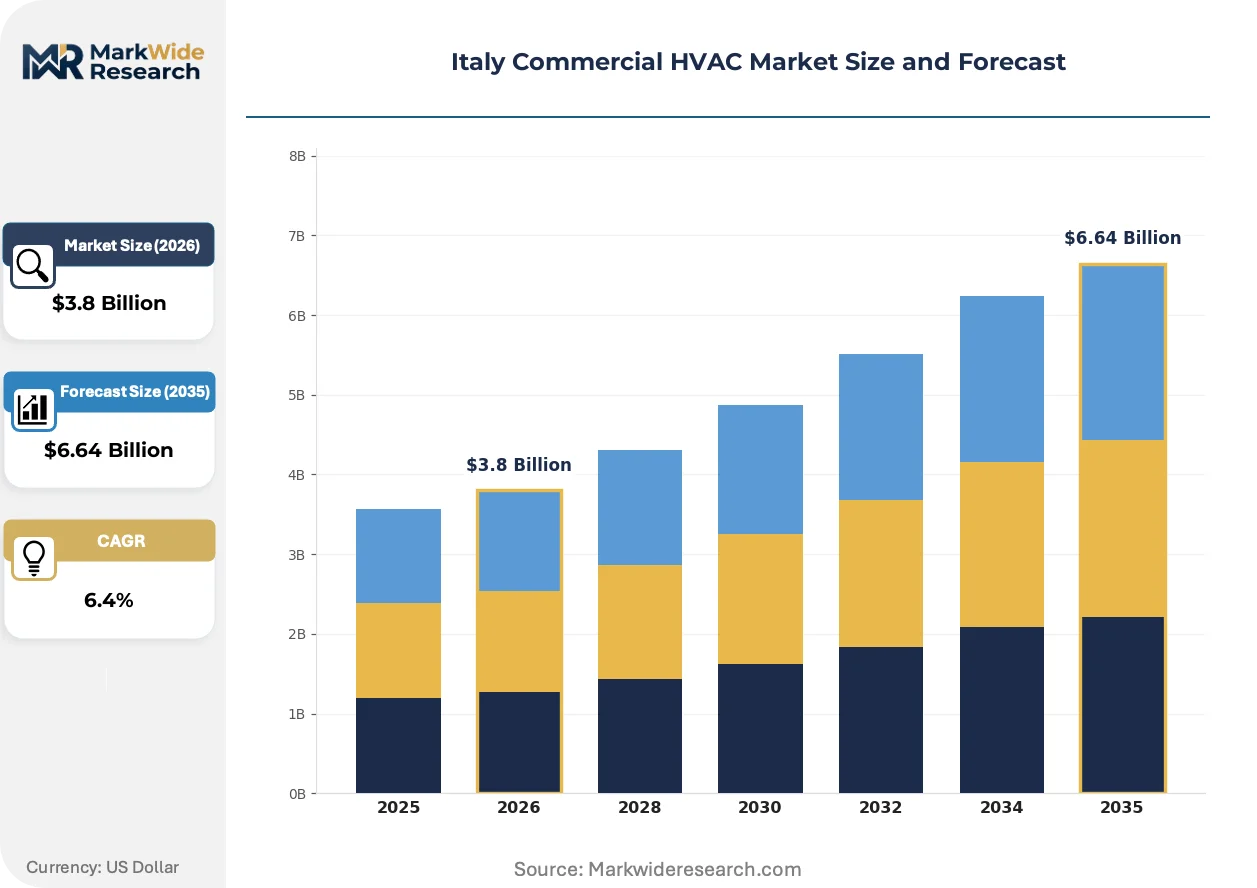
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Heat Pumps, Rooftop Units, AHUs Technology: Variable Refrigerant Flow, Hydronic Systems, Ductless Solutions, Natural Ventilation End User: Office Buildings, Retail Spaces, Hospitals, Educational Institutions Installation Type: New Construction, Retrofit, Expansion, Replacement |
| Companies Covered | Robert Bosch GmbH, Danfoss A/S, Daikin Industries Ltd., LG Electronics Inc., Lennox International Inc., Johnson Controls International PLC, Mitsubishi Electric Europe BV, Midea Group Co. Ltd, Carrier Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Commercial HVAC Market Trends and Innovations
Electrification mandates and refrigerant chemistry constraints are forcing simultaneous evolution across equipment design, service delivery models, and procurement structures. Italian commercial HVAC is experiencing compressed technology cycles that favor adaptive supply chains.
Heat pump technology is hybridizing with thermal storage and solar photovoltaic integration to create dispatchable heating and cooling systems. Large retail and logistics operators in northern Italy are piloting these configurations to manage demand charges and grid interaction costs. This convergence is compressing the standalone chiller market while expanding the addressable scope for integrated energy service providers.
The EU F-Gas Regulation is tightening quota enforcement through 2030, forcing refrigerant transitions toward lower-GWP alternatives. Equipment manufacturers must redesign compressors and heat exchangers for flammable or high-pressure working fluids. The chiller segment faces the steepest compliance curve, with natural refrigerant adoption accelerating in food retail and industrial process applications.
Facility managers are unbundling equipment purchase from long-term service contracts, creating competitive pressure on OEM captive service networks. Independent service providers in Milan and Turin are capturing maintenance relationships through predictive diagnostics and faster response commitments. This shift is most pronounced in multi-site retail and hospitality portfolios where centralized procurement favors specialized service aggregators over manufacturer-direct arrangements.
Italy Commercial HVAC Market Segmentation
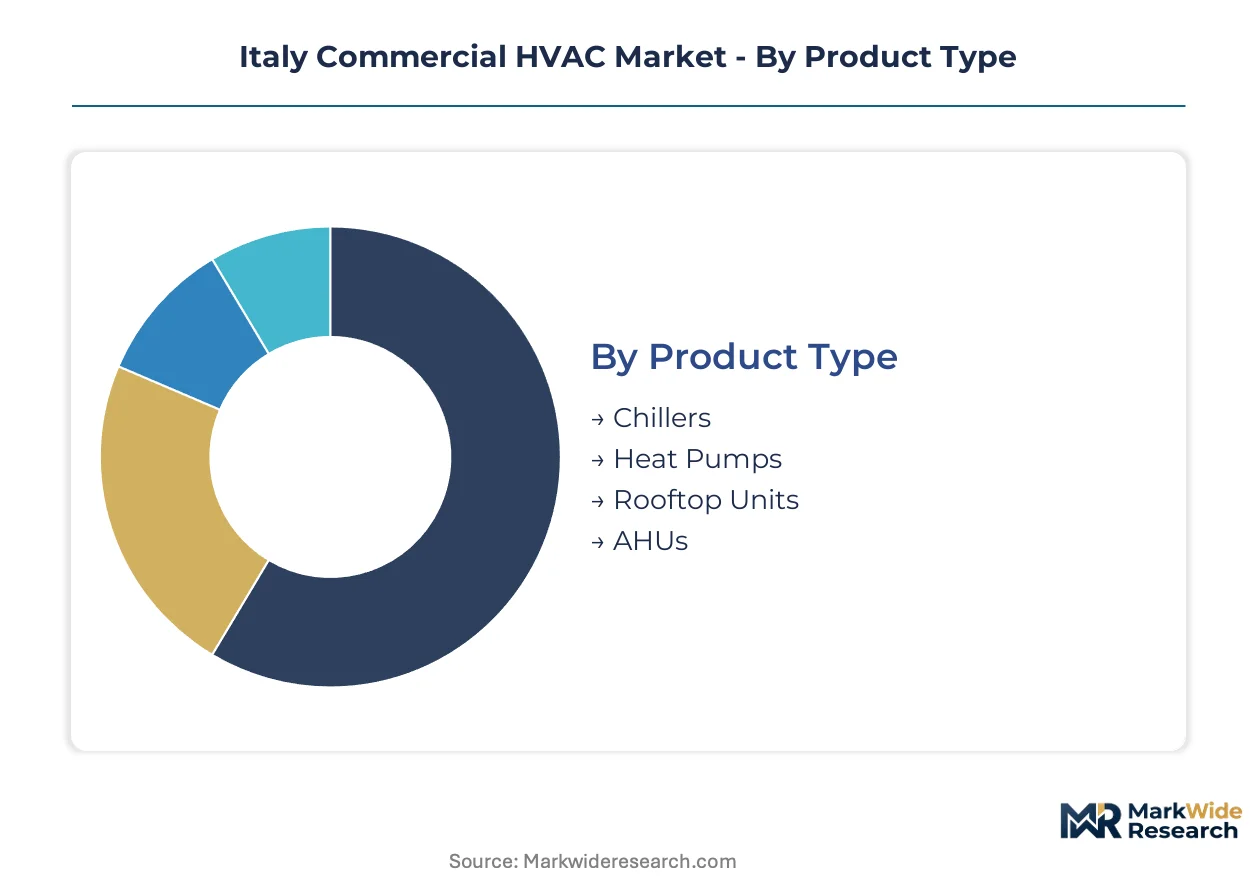
Italy's commercial HVAC segmentation reflects divergent service lifecycle economics across equipment categories. After-sales intensity varies dramatically between chiller overhaul contracts and heat pump maintenance, reshaping vendor profitability profiles and customer retention strategies throughout the peninsula.
Product Type:
After-sales-service intensity peaks with chillers requiring specialized technician deployment and refrigerant handling protocols.
- Chillers:Centrifugal and screw-compressor systems dominate large commercial and industrial thermal loads. Milan's financial district and Lombard pharmaceutical corridors sustain concentrated demand for process-critical cooling capacity. Water-cooled configurations retain preference where cooling tower infrastructure exists.
- Heat Pumps:Air-source and geothermal configurations are displacing fossil-fired heating across renovated building stock. Northern Italy's Superbonus 110% incentive pipeline accelerates electrification retrofits in multi-tenant office buildings. Coefficient of performance thresholds now exceed regulatory minimums as efficiency tiers stratify procurement.
- Rooftop Units:Packaged systems serve single-story retail and logistics facilities with standardized maintenance intervals.
- AHUs:Air handling units integrate filtration and humidity control for healthcare and cleanroom specifications.
By volume, chillers lead. By growth pace, heat pumps are climbing the fastest.
Technology:
Cost tier stratification separates premium VRF deployments from standardized hydronic infrastructure.
- Variable Refrigerant Flow:Multi-zone refrigerant distribution enables independent temperature control across building zones. Turin and Bologna office developments specify VRF for tenant flexibility and metered energy allocation. Heat recovery capabilities between simultaneous heating and cooling zones drive specification in mixed-use developments.
- Hydronic Systems:Chilled water and hot water distribution networks serve campus-scale facilities and district heating connections. Rome's historic building stock limits hydronic retrofit feasibility due to spatial constraints on piping distribution. Four-pipe configurations retain preference where simultaneous loads justify capital investment.
- Ductless Solutions:Mini-split and multi-split configurations penetrate small commercial retrofits where central distribution is impractical.
- Natural Ventilation:Mixed-mode systems reduce mechanical cooling loads in temperate climate zones and heritage structures.
By installed base, hydronic systems dominate. By specification momentum, VRF is gaining share fastest.
End User:
Application-specific performance requirements create divergent procurement timelines and technical specifications.
- Office Buildings:Tenant comfort standards and energy certification targets drive variable-speed equipment adoption. Milan's commercial core generates sustained replacement demand as Class A stock ages past 15-year equipment lifecycles. Demand-controlled ventilation with CO2 sensing is becoming baseline specification.
- Hospitals:Infection control mandates and 24/7 reliability requirements specify redundant capacity and specialized filtration. Italian healthcare infrastructure modernization programs are accelerating chiller and AHU replacements in acute care facilities. Operating room pressure cascade systems require precision control beyond standard commercial applications.
- Retail Spaces:Open-plan sales floors and food service integration create mixed thermal loads requiring flexible zoning.
- Educational Institutions:Seasonal occupancy patterns and capital budget constraints favor standardized equipment with extended service intervals.
By project value, hospitals command premium positioning. By transaction frequency, office buildings generate the steepest expansion trajectory.
Installation Type:
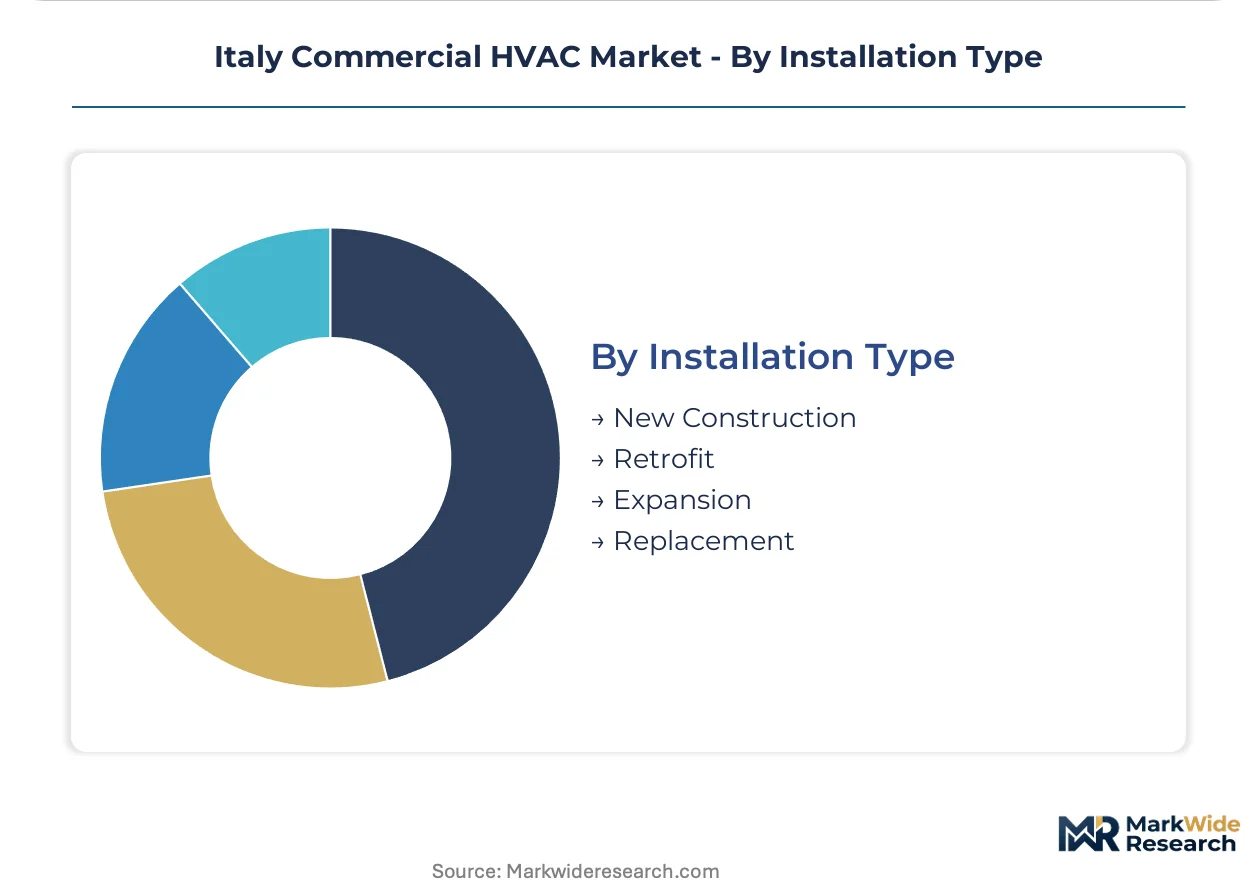
Customer type segmentation separates developer-driven new construction from owner-occupied retrofit decisions.
- New Construction:Integrated design enables optimized equipment sizing and building automation convergence. Northern Italy's logistics warehouse development corridor specifies heat pump-centered systems to meet nearly zero-energy building standards. Commissioning protocols ensure performance verification before occupancy handover.
- Retrofit:Equipment replacement within constrained mechanical spaces demands adaptive engineering and phased installation. Aging chiller plants in Rome and Naples commercial stock face F-Gas Regulation-driven refrigerant transition deadlines. Thermal storage integration is emerging as a strategy to downsize replacement equipment capacity.
- Expansion:Capacity additions to existing systems require compatibility verification with legacy controls and distribution infrastructure.
- Replacement:Like-for-like equipment swaps under emergency failure timelines prioritize availability over optimization.
By project count, retrofit dominates. By system performance potential, new construction offers the most favorable technical outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian HVAC manufacturing clusters heavily in northern industrial zones, with component supply chains radiating from established machinery corridors. This geographic concentration shapes procurement patterns and service response capabilities across the peninsula.
Lombardy
Milan's financial district drives premium chiller replacements as Class A office stock ages past operational lifecycles. The EU F-Gas Regulation compresses refrigerant availability for legacy equipment servicing. Bergamo and Brescia host precision metalworking clusters supplying heat exchanger components to OEM assembly plants.
Piedmont
Turin's automotive heritage translates into advanced manufacturing demand for process cooling and cleanroom climate systems. The Superbonus 110% incentive structure accelerates heat pump retrofits in multi-tenant commercial buildings. The Ivrea industrial zone sustains specialized compressor testing and calibration facilities serving peninsula-wide distribution.
Veneto
Padua and Verona pharmaceutical corridors specify redundant cooling capacity for GMP-compliant production environments. CE marking enforcement under the Machinery Directive governs equipment imports through Venice port logistics. Vicenza's engineering services cluster supports commissioning protocols for complex hydronic installations.
Emilia-Romagna
Bologna's food processing machinery sector generates sustained demand for ammonia-based industrial refrigeration. The Ecodesign directive tightens minimum efficiency thresholds for equipment procurement in publicly tendered projects. Modena and Parma packaging equipment manufacturers integrate precision humidity control into automated production lines.
Lazio
Rome's constrained historic building stock limits hydronic retrofit feasibility due to spatial restrictions on piping distribution. Italian environmental agencies enforce refrigerant quota allocations that bottleneck HFO alternatives during peak replacement seasons. Fiumicino logistics hubs pilot thermal storage integration to manage electrified HVAC demand charges.
Italy Commercial HVAC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The Italian commercial HVAC structure tiers across multinational OEMs with captive distribution, regional assemblers serving retrofit markets, and specialized component fabricators. Three archetypes dominate: full-system providers bundling equipment and long-term service contracts, technology licensors enabling regional manufacturing partnerships, and controls-integrated platform vendors converging HVAC with building automation. Competitive moves concentrate on strategic partnerships for refrigerant transition compliance and geographic expansion into underpenetrated southern markets.
Among the full-system provider archetype, Carrier Corporation and Daikin Industries Ltd. occupy positions defined by manufacturing footprints and service network density. Johnson Controls International PLC exemplifies the building automation convergence strategy. These three anchors represent distinct competitive vectors: captive service infrastructure, variable refrigerant flow specialization, and integrated controls platforms respectively.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Danfoss A/S |
| Daikin Industries Ltd. |
| LG Electronics Inc. |
| Lennox International Inc. |
| Johnson Controls International PLC |
| Mitsubishi Electric Europe BV |
| Midea Group Co. Ltd |
| Carrier Corporation |
| Others |
Pricing and Supply Chain Analysis
Genoa-Milan freight corridors transmit copper and aluminum cost volatility directly into equipment pricing tiers, amplifying the margin squeeze on standardized heat pump configurations while preserving premium positioning for VRF systems with captive service bundling.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across Italian commercial HVAC procurement, separating premium variable refrigerant flow systems with integrated controls from standard heat pump configurations and economy-grade rooftop units lacking after-sales coverage. Price differentiation rests on CE marking compliance tiers and Superbonus 110% incentive eligibility, with northern Italian healthcare and pharmaceutical buyers showing lowest price sensitivity due to infection control mandates. Cost compression in mid-tier hydronic equipment is intensifying because Bergamo metalworking clusters face margin pressure from commodity input swings.
Supply Chain Analysis
Export control regimes on compressor technology and precision controls limit flows from German and Japanese manufacturing bases into Italian assembly operations. Geographic supply concentration centers on China for heat exchanger coils, Germany for scroll and screw compressors, and Denmark for electronic expansion valves and drives. Raw material dependencies draw from Chilean copper cathode, Russian aluminum ingot, and fluorinated gas precursors subject to quota allocation. Single-source vulnerability concentrates in HFO refrigerant supply during peak replacement seasons. Distribution runs through Milan-based OEM captive networks and Turin-independent service aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
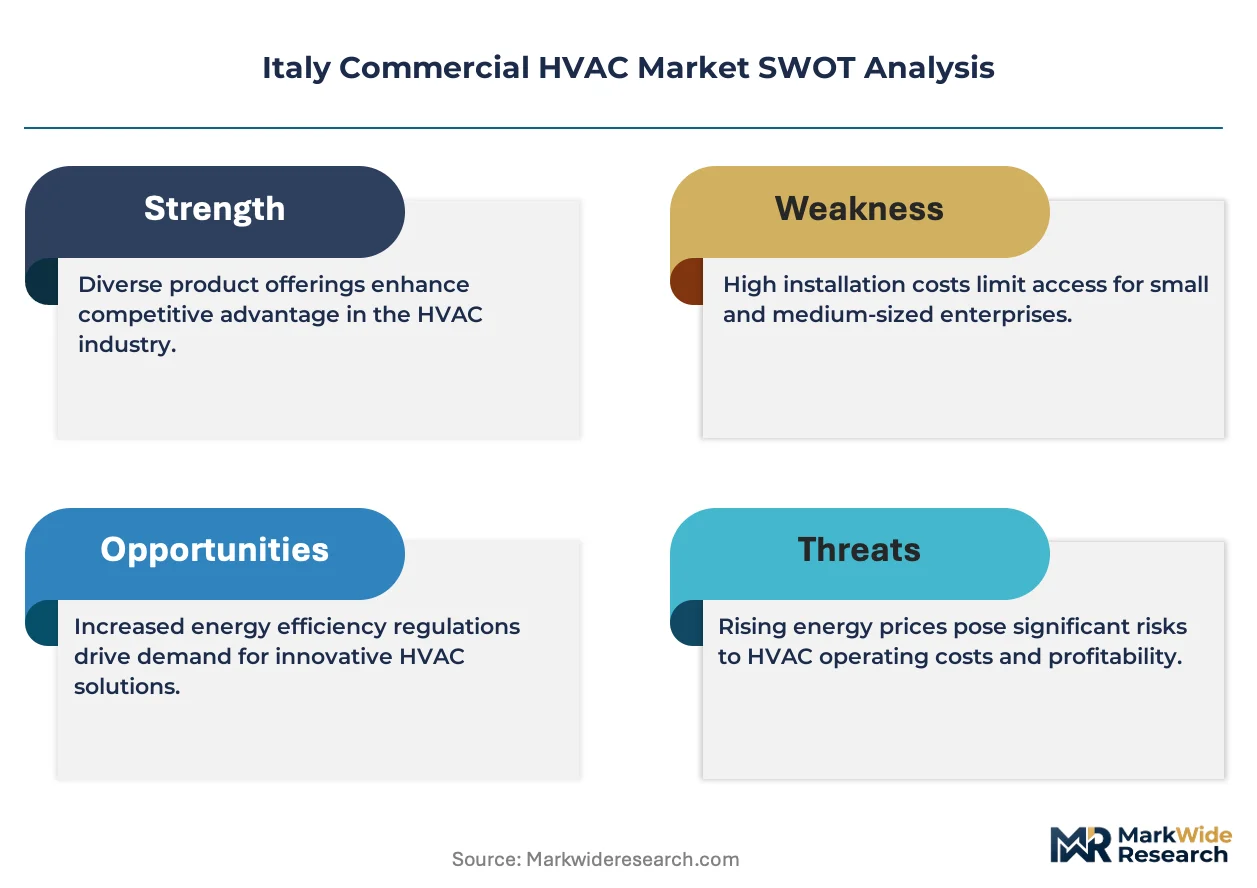
Italian commercial HVAC fragmentation creates positioning openings as F-Gas Regulation compliance deadlines splinter procurement timelines across retrofit-heavy building stock.
For Market Incumbents: Insulate service revenue streams from equipment margin erosion by deepening backward integration into compressor remanufacturing and refrigerant reclamation. Capture Lombard hospital infrastructure modernization through long-term performance contracting that bundles equipment, installation, and compliance management. Threat substitution from independent service aggregators with predictive analytics capabilities demands channel control investment in IoT-enabled diagnostics platforms. For New Entrants and Emerging Players: Southern Italy's underpenetrated commercial real estate in Sicily and Calabria offers first-mover positioning as energy efficiency incentives expand beyond northern industrial corridors. Target small-format retail and hospitality portfolios with standardized heat pump configurations and fast-response maintenance commitments. Go-to-market leverage concentrates on Superbonus 110% tax deduction facilitation for owner-occupied properties. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational OEMs seeking to divest non-core regional distribution assets. Long-term viability frames around electrification mandate acceleration and natural refrigerant technician scarcity creating captive service value. Acquisition archetypes include independent Milan-Turin service aggregators with multi-site retail relationships. Signal to watch: HFO refrigerant quota auction pricing as inflection indicator for equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Capability Buildout | CO2 and ammonia system expertise captures food retail and industrial process cooling demand under F-Gas phase-down schedules. |
| Backward Integration into Compressor Remanufacturing | Captive refurbishment capacity secures refrigerant handling margins and accelerates retrofit project turnaround times. |
| Building Automation Platform Integration | Johnson Controls and similar convergence strategies capture recurring software revenue beyond equipment sales cycles. |
| Southern Italy Geographic Expansion | Sicily and Calabria first-mover positioning exploits incentive program extension into underpenetrated commercial stock. |
| Superbonus 110% Facilitation Partnership | Tax deduction navigation services differentiate procurement offerings for owner-occupied retrofit decisions. |
Research Methodology
The analysis maps chiller, heat pump, rooftop unit, and air handling unit sub-sectors, each validated through facility managers, HVAC contractor procurement leads, and OEM regional sales directors. Primary interviews with hospital biomedical engineers, pharmaceutical plant maintenance heads, and retail portfolio energy managers combined with secondary validation from EEA refrigerant quota filings, Italian Revenue Agency Superbonus transaction data, and CE marking compliance databases. Bottom-up equipment shipment analysis and top-down construction spending triangulation anchored volume estimates.
Assumption sets held EU F-Gas Regulation phase-down schedules and Superbonus incentive structures fixed while varying copper-aluminum price scenarios and grid capacity expansion timelines across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user vertical, and installation category. CAGRs derived from equipment replacement cycle analysis and electrification mandate penetration curves. Forecast inputs incorporated Lombard pharmaceutical corridor expansion plans and Rome-Naples chiller plant aging profiles.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by independent service aggregators would shift outcomes. Material shifts in refrigerant quota allocation mechanisms or Superbonus program cancellation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Swing Compressor Market