
 South America Screw Compressor Market | 2026-2036
South America Screw Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
South America Screw Compressor Market Analytics
Modular compressor packages that integrate dryers, filters, and controllers into single skid-mounted units is consolidating buyer preference across South American industrial procurement. Atlas Copco AB leverages its aftermarket service network to sustain recurring revenue from installed bases in Chilean mining operations. Kaeser Compressor Inc. anchors its regional position through dedicated assembly capacity in Brazil. Ingersoll Rand Inc. competes aggressively on oil-free technology leadership for pharmaceutical and food-grade applications.
South America screw compressors are positive displacement machines utilizing intermeshing helical rotors to compress air or gas, typically achieving discharge pressures between 100 and 200 psig with continuous duty cycles designed for industrial process reliability. Oil-injected configurations dominate current installed capacity due to lower capital outlay and mature service infrastructure, while oil-free systems capture expanding margin pools in food and beverage and pharmaceutical end uses where ISO 8573 Class 0 air quality is mandatory. Variable speed drive technology is displacing fixed-speed units across energy-intensive manufacturing segments as electricity costs escalate in Argentina and Brazil.
Brazil's PROCEL labeling program and Argentina's energy efficiency regulations under the national electric power secretariat shape equipment specification requirements and import compliance pathways for compressor suppliers. ANVISA sanitary standards for food-contact compressed air systems in Brazil further constrain product configuration options for oil-free segment participants. Stakeholders must monitor evolving energy tariff structures and local content requirements as governments across the region recalibrate industrial policy to protect domestic manufacturing employment.
Market Dynamics
Brazil's PROCEL energy efficiency certification is compressing replacement cycles for fixed-speed screw compressors across the southeastern manufacturing corridor, forcing industrial buyers toward variable speed drive configurations despite higher capital requirements.
Growth Catalysts
- ANVISA Sanitary Standards:Brazil's food-contact compressed air regulations mandate ISO 8573 Class 0 quality for beverage bottling lines, accelerating oil-free compressor deployment in São Paulo state processing facilities.
- Food and Beverage Processing:Packaging automation investments across Argentina's wine export sector and Brazil's dairy industry are expanding baseline compressed air capacity requirements.
- Variable Speed Drive Technology:Electricity tariff volatility in Buenos Aires industrial zones is concentrating buyer preference toward load-matching compressor architectures that reduce peak demand charges.
Market Restraints
- Import Duty Structure:Brazil's industrial equipment import tariffs elevate landed costs for European and Asian compressor manufacturers, protecting local assembly operations but limiting technology transfer velocity.
- Service Infrastructure Gaps:Remote mining operations in Chile's Atacama Desert face extended mean-time-to-repair intervals due to sparse authorized technician coverage.
- Copper and Steel Volatility:Rotor machining and pressure vessel fabrication costs fluctuate with regional metal commodity pricing, compressing margin predictability for equipment suppliers.
Strategic Opportunities
- Colombia's Emerging Manufacturing Base:Medellín's automotive component cluster currently operates aging piston compressor fleets, creating replacement white space for screw technology penetration.
- Pharmaceutical Sterile Air Systems:ANVISA's expanded GMP enforcement for antibiotic manufacturing is opening specification windows for oil-free two-stage screw configurations.
- Remote Monitoring Convergence:Integration of compressor controllers with facility energy management systems is enabling predictive maintenance revenue streams for service providers.
Industry Challenges
- Rotor Profile Machining Expertise:Precision grinding of helical screw profiles requires specialized CNC programming skills that remain scarce in regional technical institutes.
- Legacy Pneumatic System Integration:Brownfield manufacturing plants in Argentina's Pampas industrial belt operate mixed-vintage air networks that resist seamless VFD retrofit without full distribution redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Screw Compressor Market |
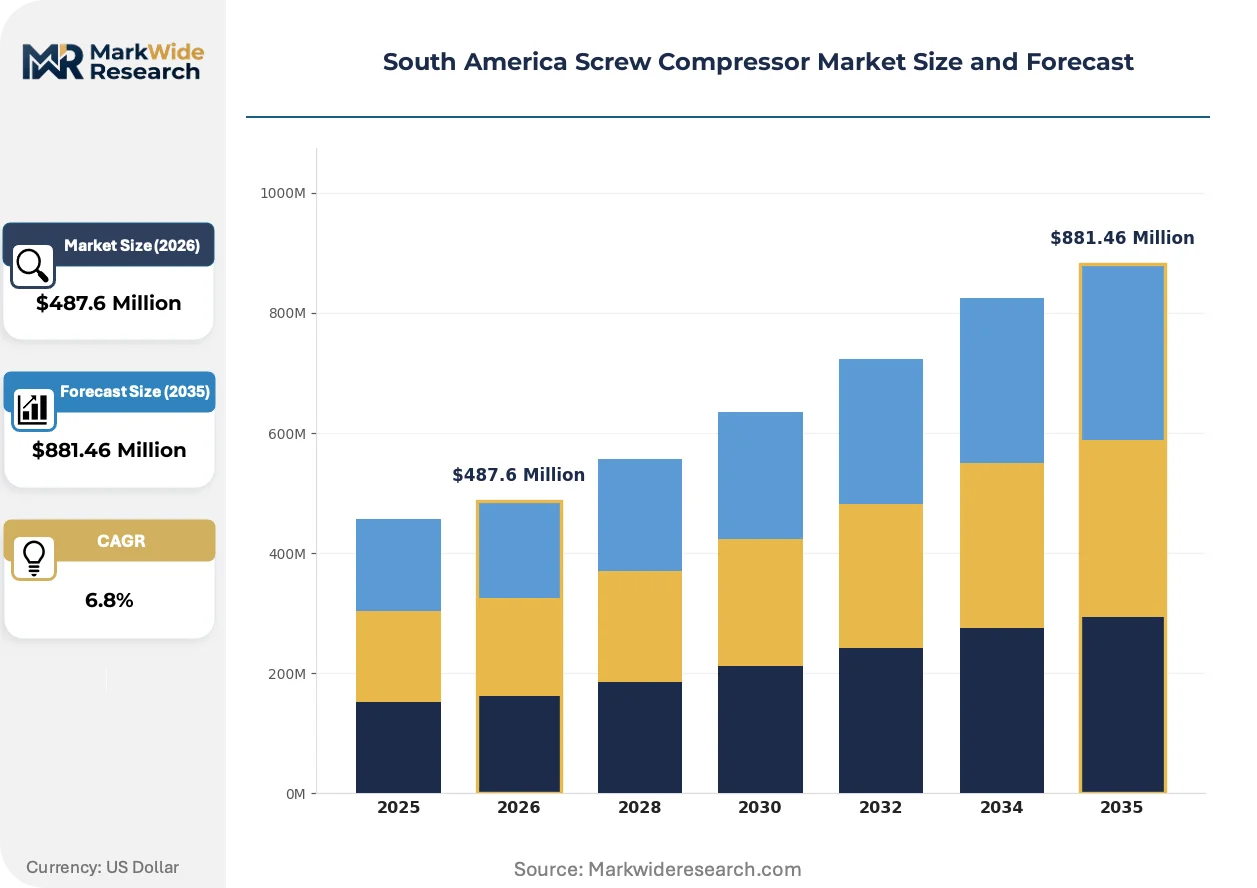
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-injected, Oil-free, Portable, Industrial End User: Manufacturing, Construction, Energy, Food & Beverage Distribution Channel: Direct Sales, Online, Retail, Distributors Technology: Rotary, Variable Speed Drive, Centrifugal, Piston |
| Companies Covered | Kobe Steel Ltd., Atlas Copco AB, Ingersoll Rand Inc., General Electric Company, Kaeser Compressor Inc., Man Energy Solutions, Burckhardt Compression AG, Zhejiang Kaishan Compressor Co., Ltd., Quincy Compressor LLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Screw Compressor Market Evolving Landscape
Digital compressor controls and integrated air treatment packages are compressing the traditional boundaries between equipment supply and energy service provision across South American industrial procurement.
Permanent magnet motor technology paired with advanced rotor profiling is automating load-responsive compression in Brazilian automotive assembly plants. Tier-one suppliers in São Paulo's ABC industrial region are specifying these configurations to meet PROCEL certification thresholds. The technology is automating demand-side energy management by eliminating unload cycles and reducing kilowatt-hour intensity per cubic meter of compressed air delivered.
Argentina's Secretariat of Electric Energy efficiency regulations are mandating minimum performance coefficients for industrial motors above 75 kilowatts, directly affecting screw compressor drive specifications. Food processing exporters in Buenos Aires province must document compliance to maintain refrigerated logistics subsidies. Oil-free compressor segments face accelerated certification timelines as provincial energy auditors tighten enforcement.
Compressed air-as-a-utility contracting is displacing traditional capital purchase models among multinational manufacturers operating in Brazil. Argentine chemical processors and Chilean copper concentrators now specify availability-based service agreements with guaranteed pressure and dew point performance. This shift concentrates vendor selection criteria on regional service network density rather than unit capital cost.
South America Screw Compressor Market Segmentation
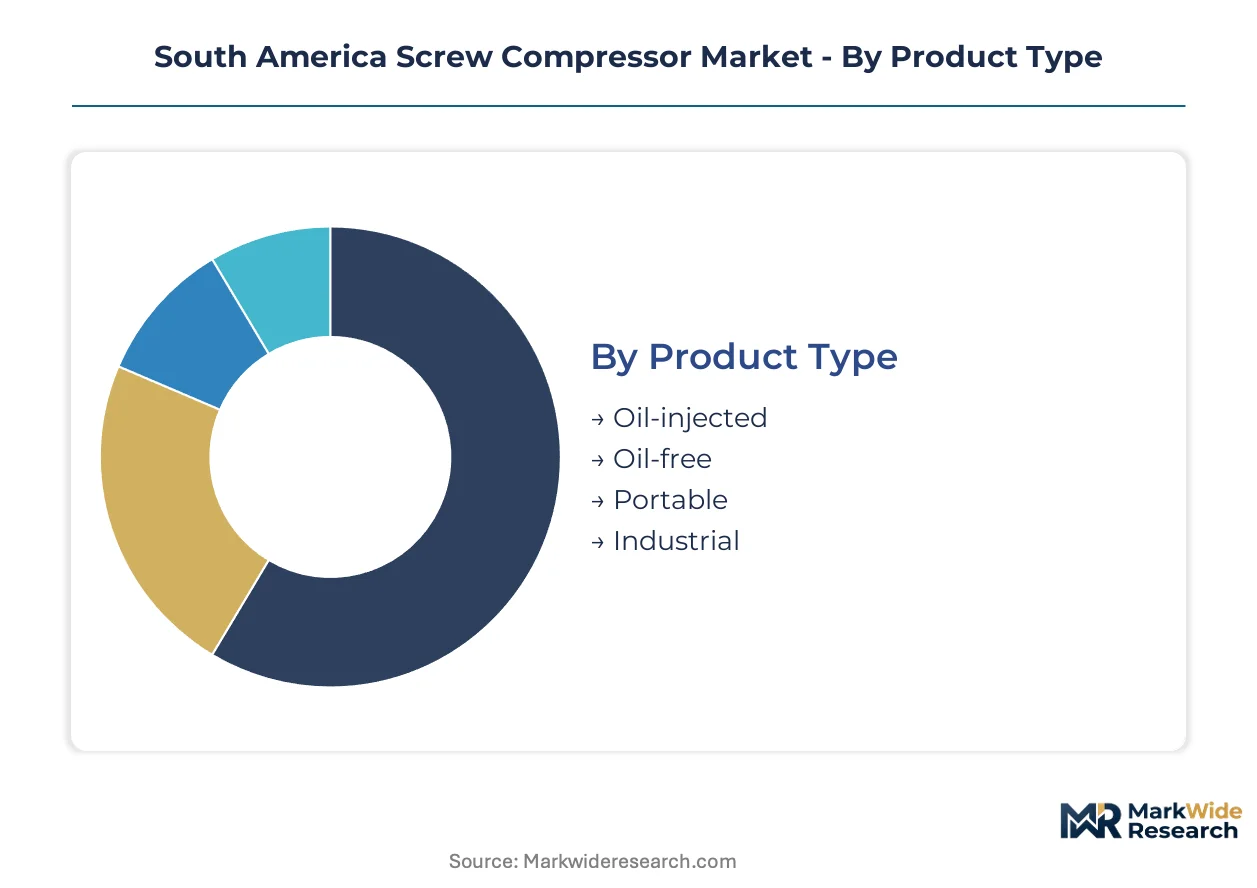
Screw compressor procurement in South America fragments across multiple technical and commercial dimensions. Equipment specification varies sharply between food-grade oil-free mandates and cost-driven industrial applications, while distribution channels reflect the regional imbalance between direct manufacturer relationships and third-party service networks.
Product Type:
Replacement cycles across South American facilities are compressing as energy regulations force premature retirement of legacy fixed-speed units.
- Oil-injected:These configurations utilize lubricant flooding between intermeshing rotors to seal clearances and dissipate compression heat, achieving discharge pressures up to 200 psig with simpler maintenance protocols. Brazilian automotive stamping plants in São Paulo's ABC region specify these units for general pneumatic power, driven by lower capital outlay and mature local service infrastructure despite higher energy intensity.
- Oil-free:Two-stage dry compression architectures eliminate hydrocarbon contamination through precision-timed rotor profiles and specialized coating systems, delivering ISO 8573 Class 0 air quality. ANVISA's food-contact compressed air standards are accelerating deployment across Rio Grande do Sul dairy processing facilities and Mendoza wine bottling operations where product contamination liability exceeds equipment cost premiums.
- Portable:Skid-mounted or trailer-housed diesel-driven units serve remote construction and mining applications with rapid relocation capability.
- Industrial:Stationary base-mounted packages integrate dryers, filters, and receivers for permanent manufacturing installations.
Volume placements concentrate in Oil-injected configurations; the faster expansion belongs to Oil-free as sanitary enforcement tightens across food export sectors.
End User:
Customer procurement sophistication varies dramatically across South American industrial sectors, with energy-intensive segments demanding lifecycle cost analysis while smaller operators prioritize upfront capital containment.
- Manufacturing:Automotive assembly plants, metal fabrication shops, and textile operations constitute the core installed base, with PROCEL-certified variable speed units displacing fixed-speed legacy equipment across Minas Gerais industrial parks.
- Construction:Infrastructure projects and commercial building activity drive rental and short-term deployment of portable diesel-driven screw compressors.
- Energy:Oil and gas field operations, plus power generation maintenance, require high-reliability configurations with extended mean-time-between-overhauls.
- Food & Beverage:Argentina's wine export sector and Brazil's protein processing industry are expanding compressed air capacity for automated packaging lines, with ANVISA compliance mandating oil-free specifications for beverage bottling and aseptic dairy operations.
Manufacturing captures the dominant share of unit placements; Food & Beverage demonstrates the steepest expansion trajectory as export-oriented processing capacity expands.
Distribution Channel:
Channel selection in South America reflects the tension between manufacturer control and local market access, with import duty structures and service response requirements shaping procurement patterns.
- Direct Sales:Large multinational manufacturers and mining conglomerates negotiate frame agreements with compressor OEMs, specifying availability-based service contracts and guaranteed spare parts provisioning across Brazilian southeastern manufacturing corridors.
- Online:E-procurement platforms are gaining traction among mid-sized maintenance departments for standard spare parts and consumables, though complete unit purchases remain relationship-driven.
- Retail:Local equipment dealers serve small contractor and workshop segments with limited technical specification requirements.
- Distributors:Authorized regional networks provide installation, commissioning, and aftermarket service coverage, with density concentrated around São Paulo and Buenos Aires industrial zones while remaining sparse in Chilean mining hinterlands.
Direct Sales anchor high-value transactions; Distributors mediate the broadest geographic reach.
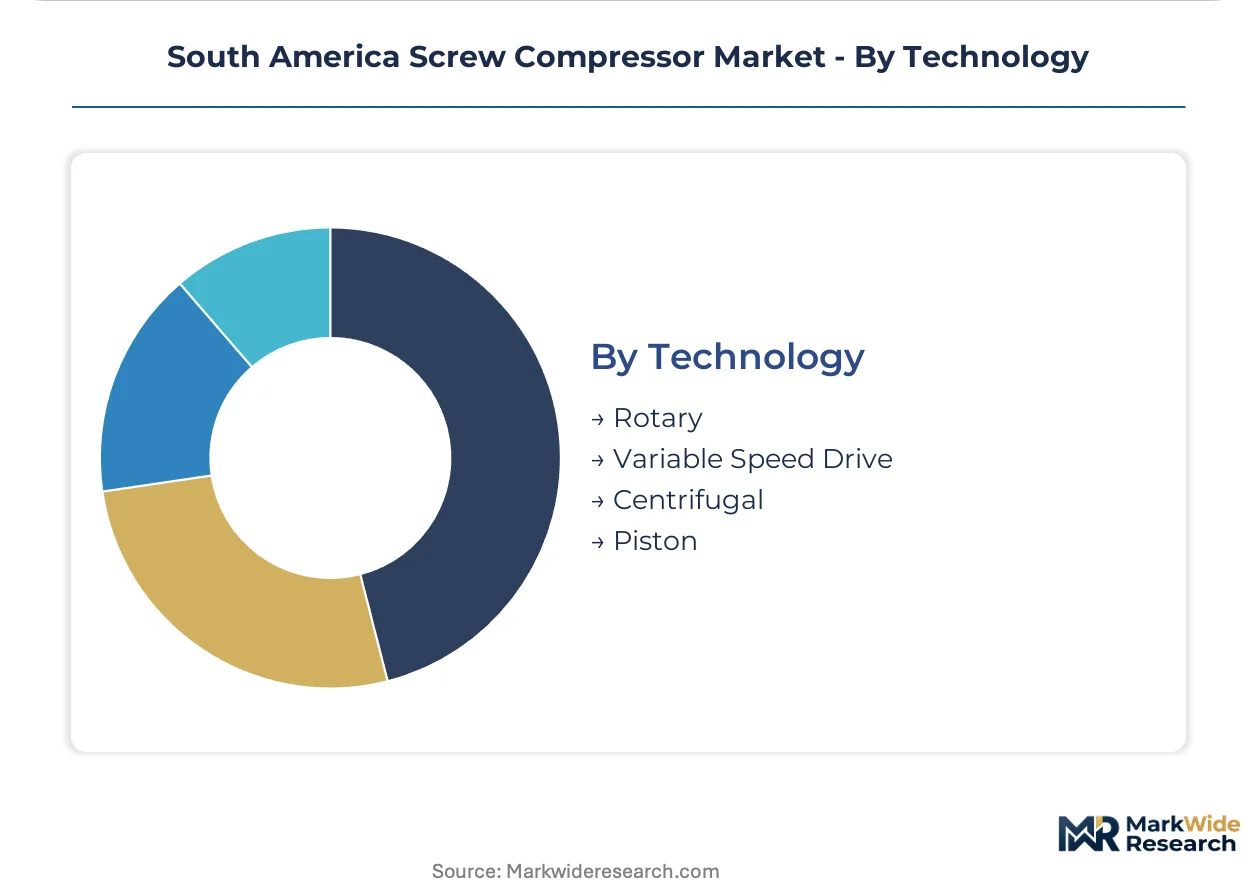
Technology:
Technology adoption curves diverge between efficiency-mandated upgrades in regulated jurisdictions and capital-constrained retention of legacy architectures elsewhere.
- Rotary:Conventional fixed-speed helical screw designs dominate installed capacity but face accelerated replacement under Brazil's PROCEL efficiency thresholds and Argentina's Secretariat of Electric Energy motor performance regulations.
- Variable Speed Drive:Permanent magnet motor configurations with load-matching frequency control eliminate unload cycles and reduce kilowatt-hour intensity per cubic meter delivered, concentrating demand in electricity-intensive Brazilian automotive and textile operations facing volatile tariff structures.
- Centrifugal:Dynamic compression technology serves very high flow rate applications above 500 horsepower, primarily in petrochemical and large-scale mining air separation.
- Piston:Reciprocating technology persists in legacy installations and ultra-small capacity points below 10 horsepower, with screw technology penetrating this residual base as total cost of ownership advantages become recognized.
Rotary technology retains the largest installed base; Variable Speed Drive configurations are gaining share fastest as energy regulations tighten and electricity costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone and Argentina's Tierra del Fuego industrial park concentrate assembly capacity through tax-advantaged import regimes. These special economic zones anchor regional supply chains for energy-intensive manufacturing equipment.
Brazil
Automotive stamping plants and dairy processing facilities drive replacement demand for variable speed drive units. ANVISA's sanitary standards mandate ISO 8573 Class 0 air quality for beverage bottling lines. São Paulo's ABC industrial region and Minas Gerais manufacturing corridor anchor oil-free compressor deployment.
Argentina
Wine export bottling operations and pharmaceutical antibiotic manufacturing expand compressed air capacity requirements. The Secretariat of Electric Energy enforces minimum performance coefficients for industrial motors above 75 kilowatts. Buenos Aires province processing clusters face accelerated energy audit compliance timelines.
Chile
Copper concentrator operations and remote mining maintenance sustain demand for high-reliability configurations. Sparse authorized technician coverage in the Atacama Desert extends mean-time-to-repair intervals. Santiago metropolitan area service networks concentrate aftermarket revenue capture.
Colombia
Medellín's automotive component cluster operates aging piston compressor fleets ripe for screw technology penetration. The national productivity program incentivizes energy efficiency upgrades across manufacturing sub-sectors. Bogotá industrial zones show accelerating specification sophistication for integrated air treatment packages.
South America Screw Compressor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South American screw compressor procurement. The market structure concentrates around three to four dominant multinational OEMs with established regional assembly footprints, while mid-tier specialists capture niche sanitary applications. Strategic archetypes include full-lifecycle service integrators, oil-free technology specialists, and cost-optimized volume manufacturers. Competitive intensity manifests through aftermarket service network density expansion and energy performance guarantee contracting.
Among the established multinational OEMs, Atlas Copco AB exemplifies the full-service integration archetype through its regional aftermarket infrastructure. Kaeser Compressor Inc. occupies a position as the dedicated regional assembler with Brazilian production capacity. Ingersoll Rand Inc. anchors the oil-free technology premium tier for pharmaceutical and food-grade specifications.
| Leading Market Players |
|---|
| Kobe Steel Ltd. |
| Atlas Copco AB |
| Ingersoll Rand Inc. |
| General Electric Company |
| Kaeser Compressor Inc. |
| Man Energy Solutions |
| Burckhardt Compression AG |
| Zhejiang Kaishan Compressor Co., Ltd. |
| Quincy Compressor LLC |
| Others |
Value Network & Pricing Analysis
Brazil's PROCEL energy efficiency certification gates qualified supply and premium-tier pricing access, as only variable speed drive configurations from certified assembly operations command full margin realization while fixed-speed legacy units face accelerated depreciation.
Pricing Analysis
Margin tightening in oil-free configurations reflects ANVISA sanitary enforcement and specialized rotor machining requirements. Three-tier pricing structure across premium, standard, and economy levels separates ISO 8573 Class 0 certified units from PROCEL-compliant oil-injected systems and uncertified legacy equipment. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in economy-tier fixed-speed units intensifies as electricity tariff volatility concentrates buyer preference toward load-matching architectures. Small workshop operators in Brazil's retail channel exhibit highest price sensitivity; multinational food processors in São Paulo state demonstrate lowest.
Supply Chain Analysis
Refurbishment flows from Chilean mining operations and Argentine industrial parks feed secondary markets with remanufactured rotor assemblies and reconditioned airends. Geographic supply concentrates in Brazil, Germany, and China, with Brazilian assembly operations drawing from German precision machining and Chinese steel forging. Raw material dependencies center on high-grade steel for pressure vessels, copper for motor windings, and specialized coatings for oil-free rotor profiles. Single-source vulnerability in precision helical grinding equipment creates supply chain risk. Distribution runs through authorized service networks anchored in São Paulo and Buenos Aires industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where precision rotor profile machining expertise bottlenecks qualified manufacturing capacity and props pricing for certified equipment.
For Market Incumbents: Extend aftermarket service network density into Chile's Atacama Desert mining hinterlands to capture predictive maintenance revenue streams and defend against emerging compressed air-as-a-utility contractors. Deepen backward integration into permanent magnet motor production to secure PROCEL certification compliance and reduce exposure to copper price volatility.
For New Entrants and Emerging Players: Mid-sized automotive component manufacturers in Medellín's aging piston compressor fleet represent an underserved buyer archetype with replacement white space and limited incumbent service coverage. Target this segment with portable-to-stationary upgrade programs and localized Portuguese-language technical support to bypass established distributor relationships in São Paulo.
For Investors and Strategic Acquirers: ANVISA's expanded GMP enforcement timeline for antibiotic manufacturing is the leading indicator that oil-free two-stage screw specialists will command acquisition premiums. Long-term viability over the analysis window favors targets with captive rotor machining capability and existing PROCEL certification infrastructure. Monitor provincial energy auditor staffing levels in Buenos Aires province for enforcement velocity signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive motor production secures PROCEL certification thresholds and insulates margin from copper tariff exposure. |
| Remote Monitoring Platform Deployment | Predictive maintenance integration with facility energy management systems converts equipment sales to recurring revenue. |
| Oil-Free Two-Stage Configuration Certification | ANVISA GMP compliance for pharmaceutical sterile air opens specification windows in antibiotic manufacturing. |
| Authorized Service Network Expansion | Technician density in Chilean mining hinterlands compresses mean-time-to-repair and captures aftermarket share. |
| Compressed Air-as-a-Utility Contracting | Availability-based service agreements displace capital purchase models among multinational manufacturers. |
Research Methodology
Independent corroboration across maintenance directors at Brazilian automotive stamping plants, aftermarket service heads at Chilean copper concentrators, OEM procurement teams in São Paulo's ABC region, and plant engineers at Argentine wine bottling facilities underwrites the qualitative findings. Secondary validation draws from PROCEL certification databases, ANVISA regulatory filings, SEC equipment manufacturer disclosures, and Brazilian customs import records. Bottom-up unit placement estimates triangulate against top-down energy consumption projections for industrial compressed air.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product architecture (oil-injected versus oil-free), drive technology (fixed-speed versus variable speed), and end-use intensity (continuous process versus intermittent duty). Modeled CAGRs derive from replacement cycle compression under efficiency regulations, electricity tariff elasticity estimates, and food export capacity expansion timelines. Forecast inputs incorporate PROCEL certification adoption curves and ANVISA enforcement staffing projections.
Revisions become necessary when copper and steel commodity volatility exceeds historical bands, when ANVISA accelerates sanitary standard timelines, or when Brazil's industrial equipment import duty structure shifts. Practitioners should monitor provincial energy auditor hiring in Buenos Aires, PROCEL certification renewal rates, and Chilean mining maintenance outsourcing decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Blowers Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Warm Air Heater Market