
 Material Handling Automation Market | 2026-2036
Material Handling Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Material Handling Automation Market Insights
System integrator networks is reconfiguring how material handling automation reaches end users across fragmented warehouse and manufacturing sectors. Daifuku Co. Ltd leverages its captive software stack to control commissioning timelines for large distribution center deployments. KION Group AG anchors European supply through vertically integrated forklift-to-robotics portfolios. Dematic competes on dense shuttle-system density for cold-chain grocery clients.
Material handling automation encompasses electromechanical systems, sensor arrays, and control software that transport, sort, orient, and store goods through programmed or adaptive workflows, typically operating at throughput rates exceeding manual equivalents by an order of magnitude while integrating with WMS and ERP layers. Conveyor systems retain the largest installed base but generate thinner margins as commoditized belt-and-roller configurations dominate mature facilities. Automated guided vehicles capture expanding capital allocation as lithium-ion powertrains and fleet management software extend operating windows across multi-shift warehouses. AI-based systems sit at the fastest-growth intersection where predictive maintenance algorithms reduce unplanned downtime in high-velocity sortation environments.
FDA facility standards for pharmaceutical warehousing, OSHA powered industrial truck regulations, and EU machinery directives with CE marking requirements collectively shape equipment certification, operator training mandates, and retrofit timelines for legacy installations. ISO 3691-4 safety standards for driverless trucks further constrain design freedom while creating compliance barriers for unproven entrants. Stakeholders must weigh the capital efficiency of modular, interoperable automation architectures against the operational risk of single-vendor ecosystem lock-in as facility footprints expand and contract with demand volatility.
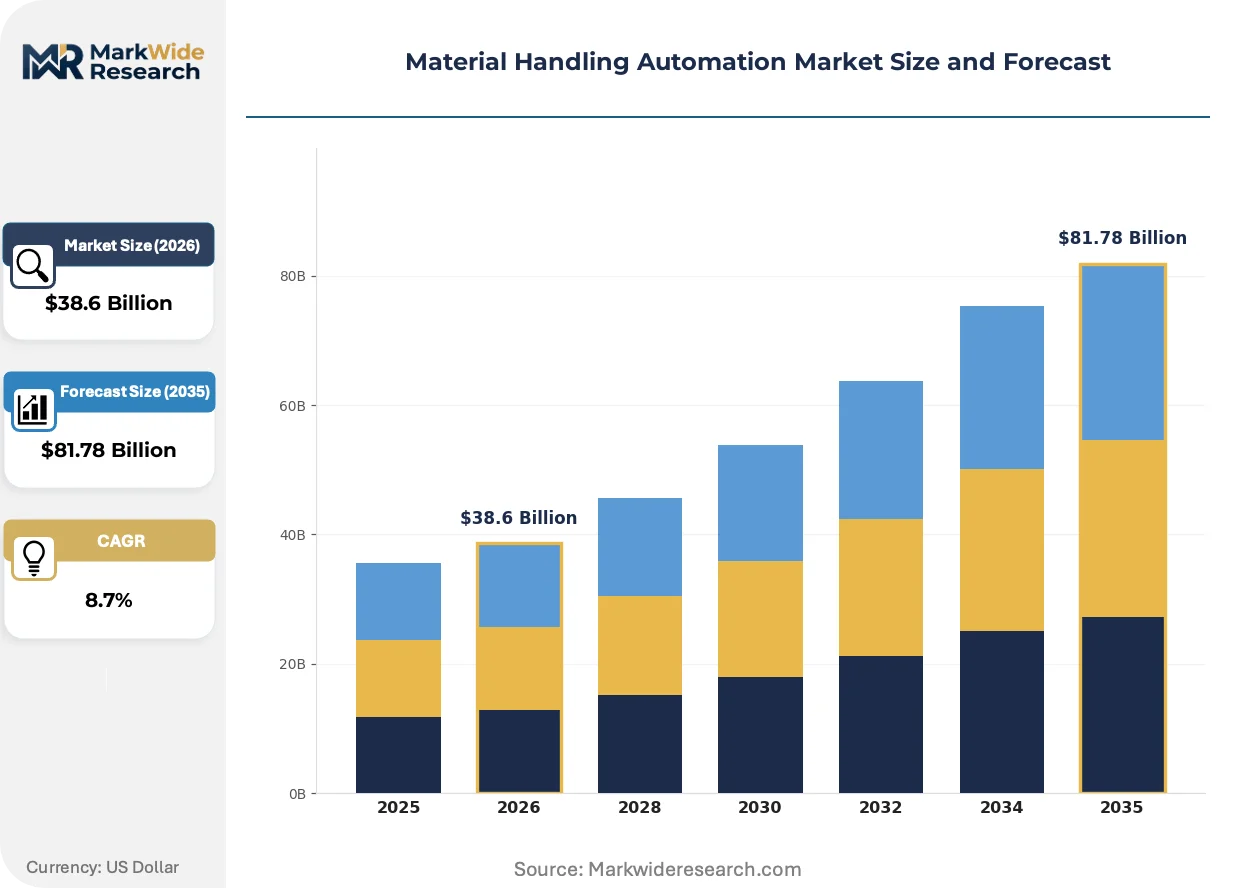
Market Dynamics
Capital allocation patterns across warehouse operators are concentrating procurement power into integrated system bundles, compressing standalone component vendors into niche retrofit specialists serving legacy facilities.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day delivery mandates from retail platforms force warehouse operators to automate picking workflows. Robotics integration now spans inbound receiving through last-mile sortation.
- EU machinery directives:CE marking requirements for sensor-guarded equipment accelerate replacement cycles for unguarded legacy conveyor installations across German automotive plants.
- Lithium-ion powertrains:Extended operating windows across multi-shift warehouses eliminate battery swap downtime. Fleet management software synchronizes AGV charging with WMS order waves.
Market Restraints
- Steel and rare-earth input volatility:Permanent magnet costs for AGV drive motors fluctuate with Chinese export quotas. Equipment manufacturers absorb margin compression or pass through via index-linked contracts.
- Single-source sensor dependency:Safety-rated LiDAR modules concentrate among three German and Japanese suppliers. Qualification timelines for alternative vendors extend 18-24 months.
- ISO 3691-4 compliance barriers:Driverless truck certification requires documented safety case submissions. Unproven entrants face capital lockup during extended validation periods.
Strategic Opportunities
- Indian pharmaceutical warehousing:CDSCO facility standards and cold-chain integrity mandates create specification-driven demand for automated storage and retrieval systems in Mumbai and Hyderabad clusters.
- Predictive maintenance convergence:AI algorithms processing vibration and thermal data from sortation equipment reduce unplanned downtime. Integration with existing SCADA layers avoids greenfield infrastructure.
- US Inflation Reduction Act incentives:Domestic content requirements for clean energy supply chains subsidize automated material handling investments in battery gigafactories across Michigan and Tennessee.
Industry Challenges
- Controls engineering scarcity:PLC programming and safety system integration expertise concentrates among aging specialists. Vocational pipelines fail to replenish technical depth for commissioning complex installations.
- WMS-ERP interoperability:Proprietary middleware from automation vendors fragments data architecture. Multi-site operators struggle to normalize telemetry across heterogeneous equipment generations.
- Pharmaceutical validation timelines:FDA 21 CFR Part 11 documentation requirements for automated warehousing extend deployment schedules. Equipment suppliers absorb project risk through fixed-price validation milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Handling Automation Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Conveyor Systems, Sortation Systems End User: Warehouses, Manufacturing Plants, Distribution Centers, Retail Facilities Technology: AI-Based Systems, RFID Technology, IoT Solutions, Machine Learning Application: Order Fulfillment, Inventory Management, Loading & Unloading, Packing |
| Companies Covered | Daifuku Co. Ltd, KION Group AG, Jungheinrich AG, SSI Schaefer, Toyota Industries Corporation, Honeywell International Inc., Dematic, BEUMER Group, Murata Machinery Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Handling Automation Market Trends and Innovations
Software-defined orchestration layers are decoupling hardware procurement from operational control, enabling warehouse operators to swap mechanical subsystems without rewiring management logic.
Collaborative robot arms equipped with vision-guided grippers are collapsing the throughput gap between human pickers and traditional fixed automation. Grocery and apparel fulfillment centers deploy these systems for variable-SKU environments where product dimensions resist hard-tooling. Capital deployment cycles compress from 24-month conveyor installations to 8-week cobot cell deployments.
OSHA powered industrial truck regulations are mandating operator-assist technologies on new forklift purchases. Fleet managers must retrofit existing equipment with proximity sensors and speed governors or accelerate replacement schedules. Third-party logistics providers in California and Texas face compressed compliance windows as state inspectors align enforcement with federal rulemaking.
Consumption-pattern shifts toward micro-fulfillment are fragmenting warehouse footprints into urban edge locations. Retailers contract automated locker and dark-store operators rather than building captive distribution infrastructure. This channel disintermediation concentrates specification influence among real estate developers who bundle automation as lease incentives in Dutch and South Korean logistics parks.
Material Handling Automation Market Segmentation
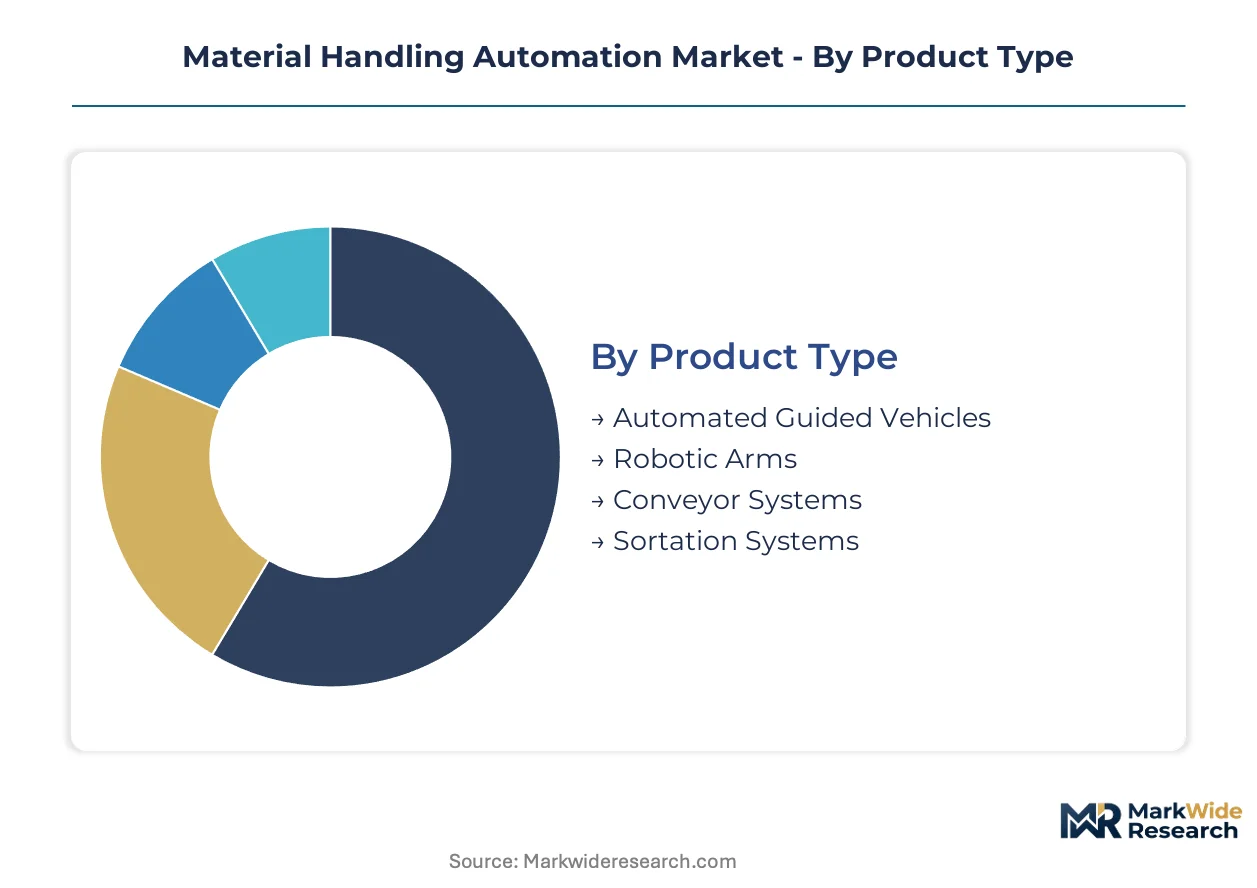
Segmentation in material handling automation exposes divergent technology maturity curves and capital deployment patterns. Equipment categories span commoditized mechanical systems through AI-enabled adaptive platforms. End-use concentration in e-commerce fulfillment centers reshapes specification priorities across product tiers.
Product Type:
Cost tier stratification separates mature mechanical equipment from emerging robotics platforms requiring specialized integration services.
- Automated Guided Vehicles:Lithium-ion powered mobile robots navigate warehouse floors via magnetic tape, laser guidance, or vision-based pathfinding. Demand concentrates in German automotive plants and US third-party logistics hubs where multi-shift operations justify fleet-scale deployments. Fleet management software integration with WMS layers drives procurement decisions.
- Robotic Arms:Articulated manipulators with six or more degrees of freedom execute pick-and-place operations in variable-SKU environments. Grocery and apparel fulfillment centers in the Netherlands and South Korea deploy these systems where product dimensions resist hard-tooling. Vision-guided grippers collapse deployment timelines from months to weeks.
- Conveyor Systems:Belt-and-roller configurations dominate mature facilities with thinner margins and standardized throughput requirements.
- Sortation Systems:High-velocity diverters and cross-belt sorters handle peak e-commerce volumes in regional distribution hubs.
Conveyor systems command the established base. The steepest expansion runs through automated guided vehicles.
End User:
Application context determines specification rigor, with pharmaceutical and cold-chain facilities imposing validation requirements absent in general merchandise operations.
- Warehouses:Multi-tenant fulfillment centers serving retail platforms drive procurement of modular automation architectures. Same-day delivery mandates from e-commerce operators in California and Texas compress deployment timelines. OSHA powered industrial truck regulations accelerate retrofit schedules for legacy forklift fleets.
- Distribution Centers:Dedicated facilities for grocery and apparel brands deploy dense shuttle systems and robotic arms. Cold-chain integrity mandates from FDA facility standards shape equipment selection for pharmaceutical clients in Mumbai and Hyderabad clusters. Capital allocation concentrates in automated storage and retrieval systems.
- Manufacturing Plants:Automotive assembly lines in Germany integrate AGV fleets with just-in-time component delivery. EU machinery directives with CE marking requirements compel sensor-guarded equipment retrofits.
- Retail Facilities:Micro-fulfillment dark stores in urban edge locations contract automated locker operators rather than building captive infrastructure.
Warehouses capture the dominant share of current deployment. Distribution centers are climbing the fastest as cold-chain specifications proliferate.
Technology:
Maturity gradients separate proven identification and connectivity layers from predictive algorithms still navigating qualification timelines.
- AI-Based Systems:Predictive maintenance algorithms process vibration and thermal telemetry from sortation equipment to reduce unplanned downtime. Integration with existing SCADA layers avoids greenfield infrastructure investments. High-velocity fulfillment environments in Tennessee battery gigafactories subsidized by US Inflation Reduction Act incentives drive adoption.
- RFID Technology:Passive and active radio-frequency identification tags enable real-time inventory tracking without line-of-sight constraints. Pharmaceutical warehousing under FDA 21 CFR Part 11 documentation requirements deploys these systems for lot-level traceability. Validation timelines extend deployment schedules.
- IoT Solutions:Sensor networks connecting mechanical subsystems to cloud orchestration layers enable remote monitoring and firmware updates.
- Machine Learning:Adaptive algorithms optimize pick-path routing and fleet charging schedules based on historical order patterns.
RFID technology holds the installed base advantage. AI-based systems are gaining share fastest at the predictive maintenance convergence point.
Application:
Workflow position determines throughput specifications, with inbound receiving and last-mile sortation presenting divergent mechanical and software requirements.
- Order Fulfillment:Picking workflows span goods-to-person shuttle systems through collaborative robot arms with vision-guided grippers. E-commerce velocity mandates from retail platforms force automation of previously manual operations. Variable-SKU environments in apparel and grocery resist fixed automation tooling.
- Inventory Management:Automated storage and retrieval systems with double-deep rack configurations maximize cubic utilization in constrained urban footprints. CDSCO facility standards for Indian pharmaceutical warehousing create specification-driven demand in Mumbai clusters.
- Loading & Unloading:Mobile manipulators and extendable conveyors bridge the gap between dock doors and storage systems.
- Packing:Automated cartonization and void-fill systems adapt to variable order dimensions in direct-to-consumer fulfillment.
Inventory management anchors current automation investment. Order fulfillment shows the steepest trajectory as same-day delivery mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates anchor the United States as the dominant geography, where warehouse operators automate picking and sorting workflows under federal compliance pressure. E-commerce fulfillment velocity and lithium-ion powertrain adoption concentrate capital allocation across specific industrial clusters.
United States
Third-party logistics providers in California and Texas deploy AGV fleets at scale to meet same-day delivery mandates from retail platforms. OSHA powered industrial truck regulations accelerate retrofit schedules for legacy forklift fleets. The Inland Empire logistics corridor east of Los Angeles hosts dense automation deployments serving West Coast e-commerce distribution.
Germany
Automotive assembly lines and third-party logistics providers integrate robotic arms and AGV fleets under just-in-time component delivery models. EU machinery directives with CE marking requirements compel sensor-guarded equipment retrofits across Baden-Württemberg and Bavaria manufacturing belts. Stuttgart's automotive cluster drives specification demand for integrated shuttle systems.
China
Battery gigafactories and e-commerce fulfillment centers absorb automated storage and retrieval systems at scale. MIIT industrial upgrading programs subsidize smart factory investments in the Yangtze River Delta. Shenzhen and Dongguan electronics manufacturing hubs deploy vision-guided robotic arms for variable-SKU assembly workflows.
India
Pharmaceutical warehousing under CDSCO facility standards creates specification-driven demand for cold-chain automation. The PLI scheme for manufacturing incentivizes capital investment in automated material handling across Maharashtra and Gujarat industrial zones. Mumbai and Hyderabad clusters anchor automated storage and retrieval system deployments for export-oriented pharma operations.
Japan
Automotive and electronics manufacturers deploy predictive maintenance algorithms on sortation equipment to reduce unplanned downtime. METI productivity enhancement programs support SME automation adoption in Aichi Prefecture's industrial corridor. Nagoya-based automotive suppliers integrate AI-based fleet management software with existing SCADA layers.
Material Handling Automation Market Competitive Landscape
Vertically integrated conglomerates and specialized system integrators split the market into distinct capability tiers. Tier-one players control captive software stacks that compress commissioning timelines for large distribution center deployments. Mid-tier fabricators compete on dense shuttle-system configurations for cold-chain grocery clients. Dominant competitive moves include backward integration into lithium-ion powertrain production and strategic partnerships with WMS vendors to secure interoperability advantages.
Within the integrated-system tier, Daifuku Co. Ltd and KION Group AG exemplify divergent geographic anchoring strategies. Daifuku represents the Asia-Pacific conglomerate archetype with software-defined control architectures. KION Group AG occupies a position as the European vertically integrated player spanning forklift-to-robotics portfolios. Dematic sits within the North American system integration specialist tier, competing on deployment velocity for multi-site warehouse operators.
| Leading Market Players |
|---|
| Daifuku Co. Ltd |
| KION Group AG |
| Jungheinrich AG |
| SSI Schaefer |
| Toyota Industries Corporation |
| Honeywell International Inc. |
| Dematic |
| BEUMER Group |
| Murata Machinery Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese lithium-ion cell production is compressing powertrain margins for AGV manufacturers while simultaneously extending supplier payment terms to 180 days. This utilization imbalance forces European system integrators to absorb cost pressure or renegotiate index-linked contracts with warehouse operators.
Pricing Analysis
German automotive plants pay 15-25% premiums for CE-certified sensor-guarded equipment compared to unguarded legacy configurations in Eastern European facilities. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive maintenance bundles from basic mechanical conveyors. Cost compression in standard AGV tiers is intensifying because Chinese battery gigafactories are subsidizing domestic automation procurement. Third-party logistics providers in Texas and California exhibit the highest price sensitivity due to compressed same-day delivery margins, while pharmaceutical cold-chain operators in Mumbai clusters prioritize validation documentation over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese automotive OEMs are cascading through the safety-rated LiDAR module supply chain, straining cash conversion cycles for German and Japanese component suppliers. Permanent magnet production draws from China, Japan, and Germany, with rare-earth processing concentrated in Chinese refining facilities. Steel conveyor components rest on Turkish and Indian mill supply subject to EU carbon border adjustment exposure. Distribution runs through system integrator networks rather than direct OEM channels, fragmenting specification influence across Daifuku, KION Group AG, and Dematic deployment teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-site third-party logistics providers who bundle automation procurement across California, Texas, and German automotive corridors. This consolidation is compressing standalone component vendors into retrofit specialists serving fragmented legacy facilities.
For Market Incumbents: Entrench software-defined control architectures that lock warehouse operators into recurring fleet management subscriptions. Backward integration into lithium-ion powertrain production secures margin control against Chinese cell price volatility. ISO 3691-4 safety certification investment creates compliance barriers for unproven entrants attempting AGV qualification.
For New Entrants and Emerging Players: Indian pharmaceutical warehousing under CDSCO facility standards offers specification-driven entry with validation documentation requirements that favor specialized system integrators over vertically integrated conglomerates. Predictive maintenance algorithm development for existing SCADA layers avoids greenfield infrastructure competition with incumbents. Partner with Mumbai-based cold-chain real estate developers who bundle automation as lease incentives.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across collaborative robot arm sub-segments as vision-guided gripper commoditization accelerates deployment velocity. Long-term viability favors mid-tier fabricators with dense shuttle-system expertise for grocery cold-chain clients. Watch for lithium-ion input price stabilization as the signal for AGV fleet-scale deployment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Management Software Integration | WMS-ERP interoperability partnerships with Dematic and KION Group AG secure multi-site operator lock-in. |
| Predictive Maintenance Algorithm Development | AI-based systems processing vibration telemetry from Tennessee battery gigafactories reduce unplanned downtime. |
| Lithium-Ion Powertrain Backward Integration | In-house cell production insulates AGV margins from Chinese rare-earth export quota volatility. |
| CE Marking Certification Investment | EU machinery directive compliance creates 18-24 month qualification barriers for unguarded equipment competitors. |
| Indian Pharmaceutical Cold-Chain Partnership | CDSCO facility standard validation capabilities capture specification-driven demand in Mumbai clusters. |
Research Methodology
The analysis maps AGV fleet deployments, robotic arm installations, conveyor retrofits, and AI-based predictive maintenance systems, each validated through plant engineers, warehouse operations directors, system integrator project managers, and OEM procurement teams. Primary interviews with maintenance directors at German automotive plants and third-party logistics operators in California and Texas combined with secondary validation against SEC 10-K filings, EU machinery directive certification databases, OSHA enforcement records, and customs trade data. Bottom-up equipment shipment tallies triangulate against top-down capital expenditure surveys from warehouse operators.
Assumptions held fixed include OSHA powered industrial truck regulation enforcement timelines, EU CE marking requirements, and lithium-ion powertrain adoption curves, while e-commerce fulfillment velocity and pharmaceutical cold-chain integrity mandates were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, end user, technology, and application, with geographic regulatory clusters treated as distinct adoption environments. CAGRs were derived from equipment shipment trajectories normalized against warehouse construction permits and manufacturing capital expenditure disclosures across the analysis window.
Practitioners should monitor Chinese rare-earth export quota announcements, FDA facility standard revisions for pharmaceutical warehousing, and OSHA enforcement alignment with state-level industrial truck regulations for early signals of forecast deviation. Macroeconomic contraction in e-commerce fulfillment, regulatory relaxation of EU machinery directives, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Can Racks Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Hydraulic Hose Market