
 HVAC System Analyzer Market | 2026-2036
HVAC System Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC System Analyzer Market Foresight
Wi-Fi-enabled diagnostic-grade analyzer specifications are redrawing competitive expectations across the HVAC service sector. Testo SE & Co. KGaA leverages its combustion analyzer specialization to anchor premium positioning in European markets. Fluke Corporation dominates North American distribution through channel control and brand recognition among electrical and HVAC technicians. TSI Incorporated differentiates via air quality monitoring integration, extending its reach into indoor environmental health applications.
An HVAC system analyzer is a portable or fixed diagnostic instrument that measures combustion efficiency, refrigerant pressure, airflow velocity, and indoor air quality parameters to verify system performance and identify mechanical faults. These devices typically incorporate electrochemical gas sensors, differential pressure transducers, and infrared thermography modules to deliver simultaneous multi-parameter readouts for field technicians. Portable analyzers currently occupy the largest revenue pool due to technician mobility requirements, while multi-parameter analyzers represent the fastest-expanding category as consolidation of diagnostic tools reduces truck inventory costs. Commercial buildings generate the dominant application demand because facility managers prioritize predictive maintenance to avoid tenant disruption and energy penalty exposure.
EPA refrigerant management regulations and OSHA confined-space monitoring standards shape product certification requirements and channel compliance burdens across the United States. The EU F-Gas Regulation and CE marking under the Machinery Directive constrain market access for non-compliant imports while elevating replacement cycle frequency in member states. Stakeholders must monitor evolving refrigerant chemistries and corresponding sensor calibration protocols to preserve instrument relevance and service contract renewability.
Market Dynamics
Refrigerant chemistry transitions under EPA's phasedown mandates are forcing analyzer manufacturers to recalibrate sensor arrays and firmware architectures, compressing product development cycles while expanding the addressable installed base of legacy equipment requiring retrofit diagnostics.
Growth Catalysts
- Commercial building energy mandates:Facility managers in Germany deploy multi-parameter analyzers to comply with the national building energy efficiency ordinance, triggering instrumentation refresh cycles across aging HVAC infrastructure.
- OSHA confined-space standards:US service contractors upgrade to diagnostic-grade analyzers with integrated gas detection to satisfy workplace safety monitoring requirements during ductwork and mechanical room interventions.
- Electrochemical sensor miniaturization:Advances in solid-state gas sensing enable handheld devices to match benchtop accuracy, expanding field technician adoption of portable combustion analysis platforms.
Market Restraints
- Sensor calibration drift:Electrochemical cells require 6-12 month recalibration intervals, creating recurring service costs that deter small contractor adoption of premium analyzer portfolios.
- Refrigerant sensor obsolescence:Rapid refrigerant chemistry evolution under F-Gas and AIM Act protocols renders fixed-sensor analyzers technically obsolete before depreciation cycles complete.
- Supply concentration in infrared thermography modules:Three specialized optics suppliers control core thermal imaging components, exposing analyzer assemblers to allocation risk during demand surges.
Strategic Opportunities
- Indoor air quality convergence:Analyzer manufacturers integrating particulate and VOC sensing capture facility manager budgets previously allocated to standalone IAQ monitors.
- Utility rebate programs:State-level energy efficiency incentives in California and New York subsidize diagnostic equipment purchases, lowering effective price barriers for mid-market contractors.
- Predictive maintenance SaaS bundling:Hardware vendors embedding cellular connectivity enable recurring revenue streams through cloud-based performance analytics and automated fault alerting.
Industry Challenges
- Cross-trained technician scarcity:Field service firms struggle to recruit personnel proficient in both combustion analysis and refrigerant system diagnostics, constraining analyzer utilization rates.
- Multi-protocol certification complexity:Devices must simultaneously satisfy CE marking under the Machinery Directive, EPA refrigerant handling credentials, and OSHA calibration traceability standards, elongating time-to-market.
- Legacy BAS integration friction:Analyzer data formats often lack native compatibility with building automation system architectures, requiring custom middleware development for enterprise facility deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC System Analyzer Market |
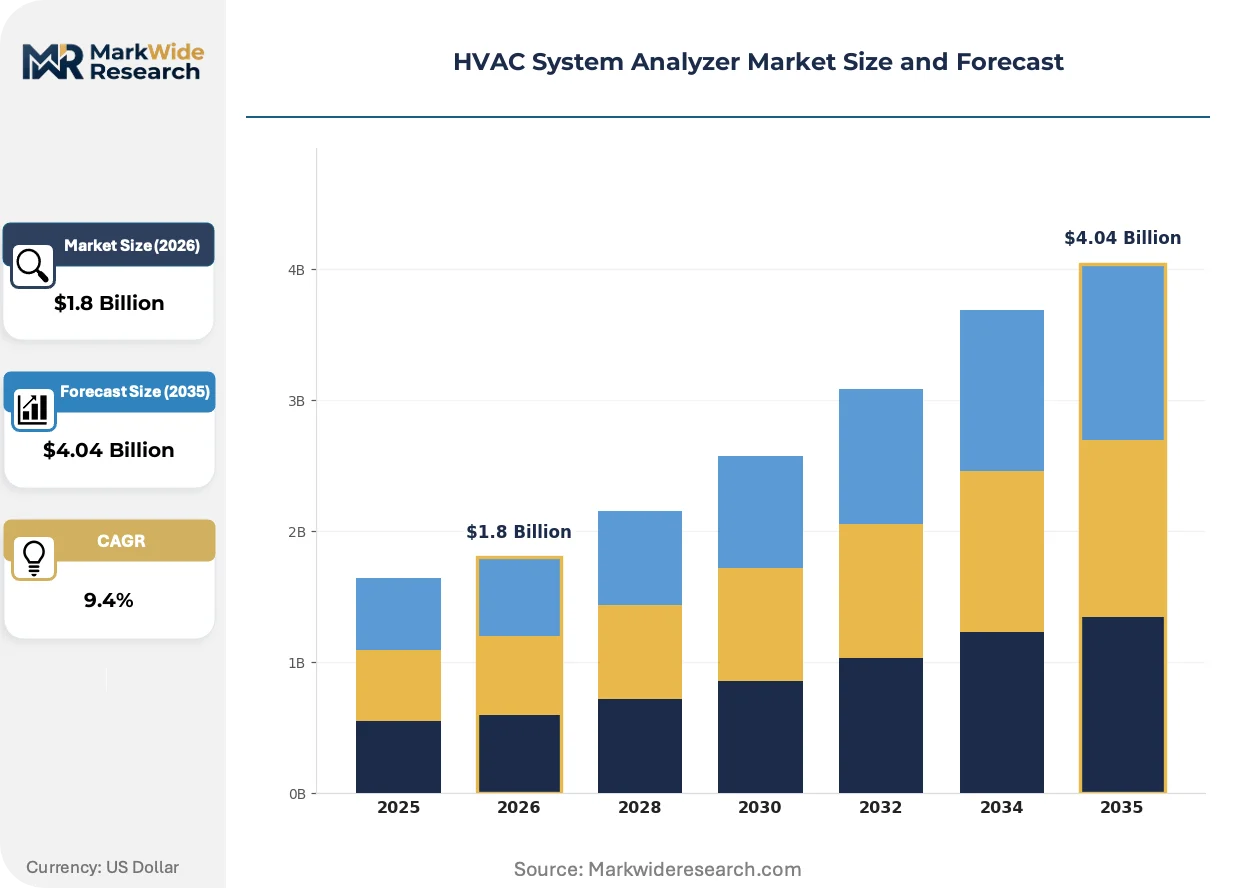
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Fixed Analyzers, Multi-Parameter Analyzers, Combustion Analyzers Application: Residential Settings, Commercial Buildings, Industrial Facilities, Automotive Maintenance Technology: Infrared Thermography, Gas Detection, Pressure Measurement, Air Quality Monitoring End User: HVAC Contractors, Building Inspectors, Facility Managers, Homeowners |
| Companies Covered | Bacharach Inc., TSI Incorporated, Testo SE & Co. KGaA, Sauermann Group, Kane International Limited, Fluke Corporation, UEi Test Instruments, PCE Instruments, Fieldpiece Instruments Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC System Analyzer Market Shifts & Advancements
Diagnostic instrumentation is converging with wireless telemetry and cloud analytics, transforming standalone analyzers into networked sensor nodes that feed continuous performance data to centralized maintenance platforms.
Cloud-connected analyzer architectures are displacing manual data logging workflows across commercial service fleets. Large mechanical contractors in Texas and Florida now mandate Wi-Fi-enabled devices that auto-upload combustion efficiency readings, eliminating handwritten field reports. This connectivity layer compresses service documentation time while enabling real-time escalation of critical fault codes to remote engineering support.
EPA's refrigerant management regulations under the AIM Act are compelling analyzer firmware updates to recognize low-GWP alternative chemistries. Equipment manufacturers must validate sensor response curves for R-454B and R-1234yf blends, retooling production lines for modular sensor cartridge designs. US-based service distributors report inventory bifurcation between legacy HFC-compatible and next-generation refrigerant-ready analyzer SKUs.
Facility management procurement teams now bundle analyzer purchases with multi-year calibration service contracts, unbundling hardware from aftermarket support. This consumption pattern concentrates vendor selection authority among national service integrators rather than individual technician preferences. The shift is most pronounced in Class A office buildings across Chicago and Atlanta, where centralized procurement functions negotiate enterprise-wide diagnostic equipment standards.
HVAC System Analyzer Market Segmentation
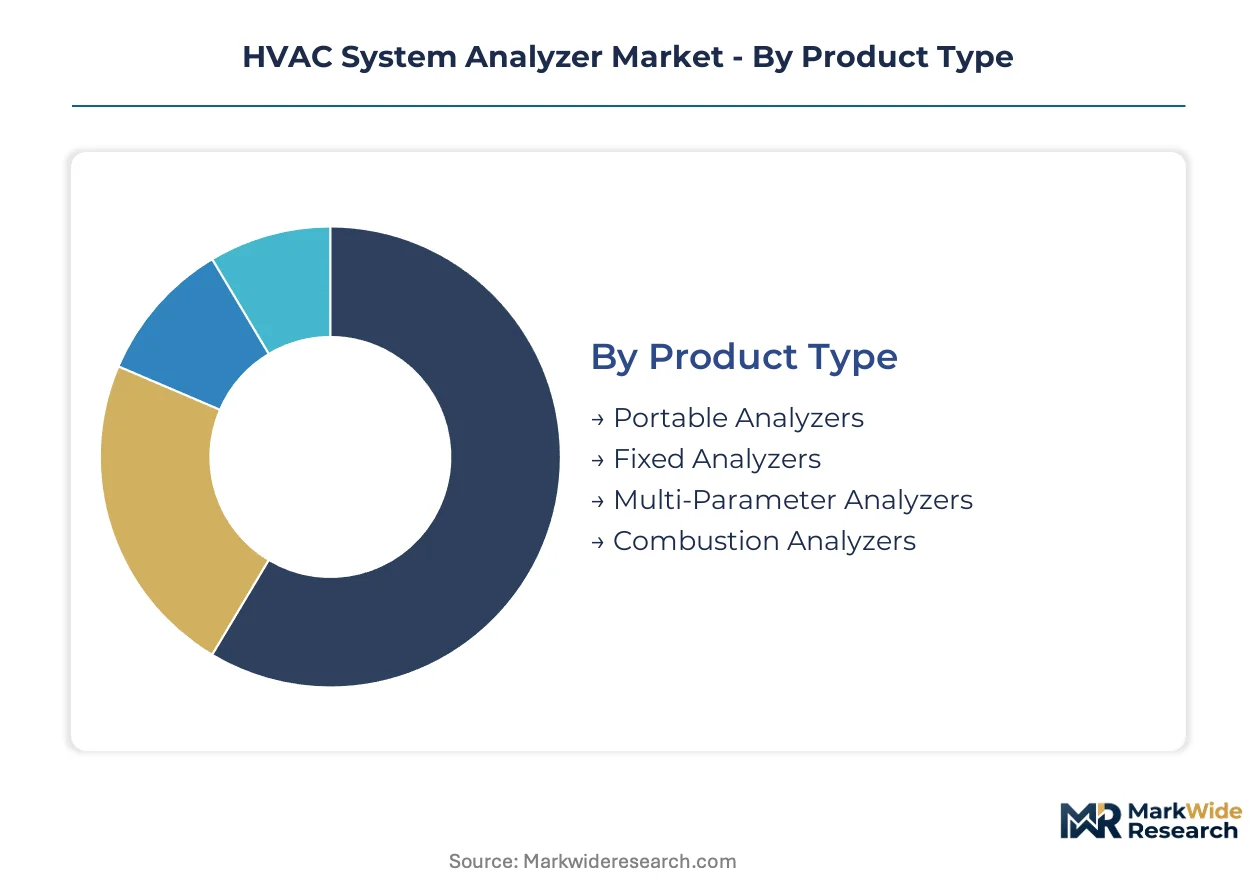
Analyzer manufacturers optimize product portfolios around distinct technical specifications and buyer economics. Segment boundaries determine calibration service attach rates, sensor replacement revenue, and channel partnership structures across service contractor networks.
Product Type:
Margin pools concentrate in devices that consolidate multiple diagnostic functions into single field-deployable units, reducing technician truck inventory while commanding premium positioning.
- Portable Analyzers:Battery-powered handheld units integrate electrochemical gas sensors and differential pressure transducers for combustion efficiency and refrigerant diagnostics. Field service fleets in Germany prioritize these for building energy ordinance compliance inspections across dispersed commercial properties. Sensor drift issues create recurring calibration revenue streams that extend customer lifetime value.
- Multi-Parameter Analyzers:Consolidated platforms simultaneously measure combustion gases, refrigerant pressure, airflow velocity, and particulate counts. Facility managers in Chicago and Atlanta procurement offices specify these for predictive maintenance programs that minimize tenant disruption penalties. Firmware modularity enables refrigerant chemistry updates without hardware replacement.
- Fixed Analyzers:Permanently installed monitoring stations feed continuous data to building automation systems.
- Combustion Analyzers:Specialized units measure flue gas composition and excess air ratios for boiler and furnace tuning.
The dominant share belongs to Portable Analyzers, while Multi-Parameter Analyzers are expanding most quickly as consolidation economics reshape contractor equipment standards.
Application:
Revenue velocity diverges sharply between price-sensitive residential replacement cycles and mandate-driven commercial retrofit instrumentation.
- Commercial Buildings:Class A office towers, healthcare facilities, and educational institutions deploy diagnostic-grade analyzers to satisfy energy performance mandates and avoid lease penalty exposure. Germany's national building energy efficiency ordinance triggers instrumentation refresh cycles across aging infrastructure. Procurement centralization concentrates vendor selection authority with national service integrators.
- Residential Settings:Single-family and multi-family dwellings generate analyzer demand through HVAC replacement and warranty service calls.
- Industrial Facilities:Manufacturing plants and process operations require ruggedized analyzers for continuous monitoring of combustion systems and refrigeration loops.
- Automotive Maintenance:Vehicle service bays utilize compact analyzers for mobile air conditioning system diagnostics and refrigerant recovery verification.
Commercial Buildings command the largest revenue pool, while Residential Settings show the steepest expansion trajectory as smart home integration extends diagnostic capabilities to homeowner segments.
Technology:
Component sourcing economics favor analyzer architectures that leverage commoditized sensor platforms rather than specialized optical subsystems.
- Gas Detection:Electrochemical and infrared absorption sensors identify refrigerant leaks and combustion byproducts including carbon monoxide and nitrogen oxides. EPA refrigerant management regulations under the AIM Act force firmware updates to recognize low-GWP alternative chemistries. Solid-state sensing advances enable handheld accuracy matching benchtop laboratory equipment.
- Infrared Thermography:Thermal imaging modules visualize heat exchanger performance and insulation defects through non-contact surface temperature mapping.
- Pressure Measurement:Differential pressure transducers quantify airflow velocity and refrigerant system operating pressures.
- Air Quality Monitoring:Particulate and VOC sensing extends analyzer utility into indoor environmental health applications.
Gas Detection anchors the technology mix by revenue, while Air Quality Monitoring is gaining share fastest as facility manager budgets converge with standalone IAQ monitor displacement.
End User:
Buyer sophistication determines specification intensity, calibration contract attach rates, and replacement cycle frequency across the installed base.
- HVAC Contractors:Independent and franchise service technicians prioritize portable durability and multi-parameter consolidation to minimize truck inventory. OSHA confined-space standards compel upgrades to diagnostic-grade units with integrated gas detection for ductwork interventions. Wi-Fi connectivity eliminates handwritten documentation and enables real-time engineering escalation.
- Facility Managers:Corporate and institutional building operations teams specify enterprise-wide equipment standards and bundle multi-year calibration service contracts.
- Building Inspectors:Regulatory compliance officers require certified calibration traceability for code enforcement documentation.
- Homeowners:DIY maintenance segments purchase entry-level combustion analyzers for furnace filter and thermostat troubleshooting.
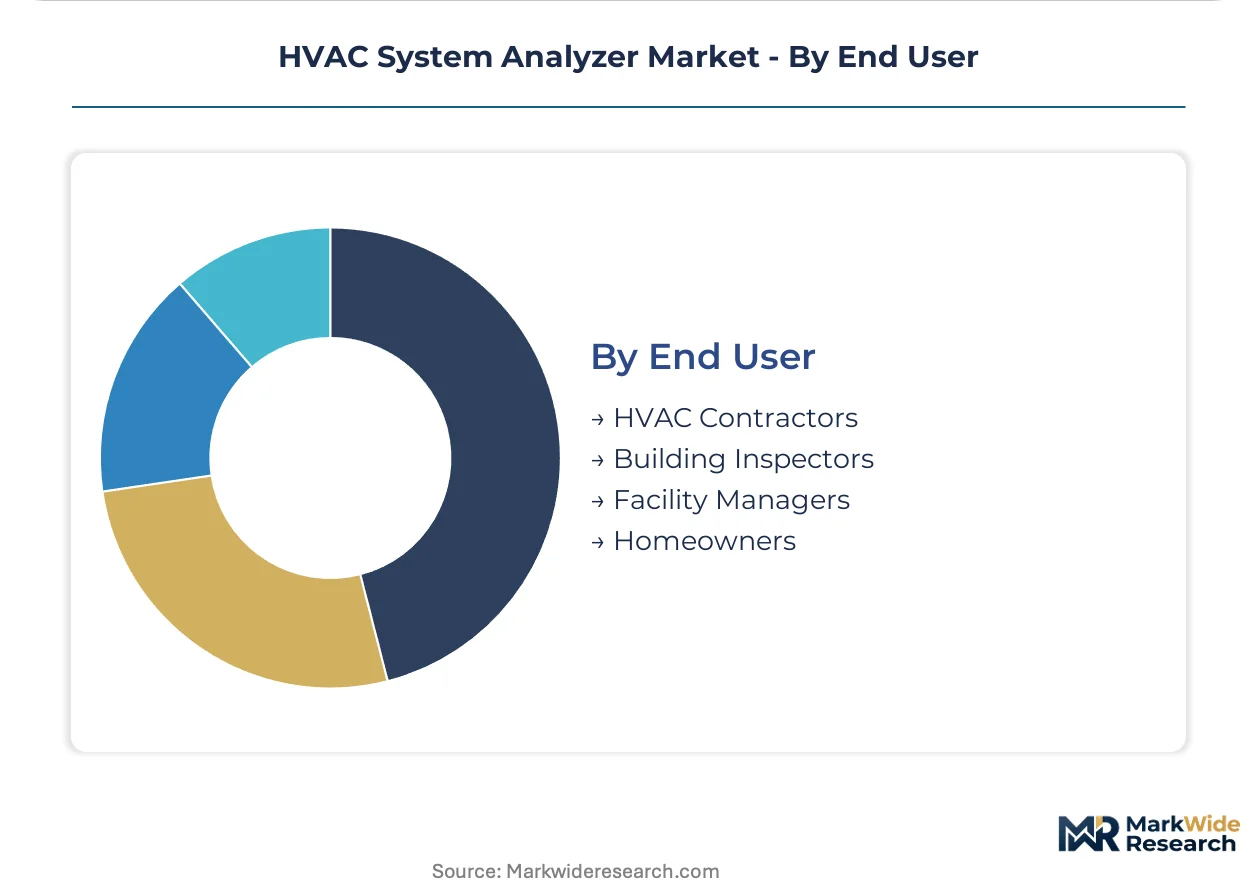
HVAC Contractors represent the largest addressable population, while Facility Managers are climbing the fastest as procurement centralization concentrates specification authority in enterprise accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analyzer manufacturing concentrates in Germany, the United States, and Japan, with sensor module sourcing extending into South Korea and Taiwan. Distribution networks radiate from these production hubs into regional service markets.
United States
Commercial building operators in Chicago and Atlanta drive multi-parameter analyzer procurement for predictive maintenance programs. EPA refrigerant management regulations under the AIM Act force firmware updates to recognize low-GWP alternative chemistries. Texas and Florida mechanical contractors now mandate Wi-Fi-enabled devices that auto-upload combustion efficiency readings.
Germany
The national building energy efficiency ordinance triggers instrumentation refresh cycles across aging HVAC infrastructure. EU F-Gas Regulation and CE marking under the Machinery Directive constrain market access for non-compliant imports. Bavarian and North Rhine-Westphalian facility managers deploy multi-parameter analyzers to satisfy energy performance mandates.
Japan
Industrial facility operators in the Kanto and Kansai regions require ruggedized analyzers for continuous monitoring of combustion systems. METI efficiency standards and JIS certification protocols elevate replacement cycle frequency. Osaka-based mechanical contractors prioritize portable durability for field service fleets.
China
Manufacturing plants in the Yangtze River Delta and Pearl River Delta drive demand for fixed analyzer installations feeding building automation systems. MEE environmental monitoring requirements and GB standards shape product certification requirements. Shanghai procurement offices specify enterprise-wide equipment standards with bundled calibration contracts.
India
Commercial building retrofits in Maharashtra and Karnataka generate analyzer demand as facility managers adopt predictive maintenance protocols. BIS certification requirements and state-level energy efficiency incentives subsidize diagnostic equipment purchases. Mumbai and Bangalore HVAC contractors upgrade to diagnostic-grade units with integrated gas detection.
HVAC System Analyzer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium positioning concentrates among German and Japanese specialists with combustion analyzer heritage, while North American distributors compete on channel density and technician brand recognition. Three archetypes dominate: precision instrumentation specialists, broad-line electrical test suppliers, and air quality convergence players. Consolidation activity centers on sensor technology licensing agreements and regional distribution partnerships.
Within the precision instrumentation tier, Testo SE & Co. KGaA and Sauermann Group anchor European market positioning through electrochemical sensor specialization. Fluke Corporation exemplifies the broad-line electrical test archetype with North American channel control. TSI Incorporated occupies the air quality convergence position, extending analyzer utility into indoor environmental health applications previously served by standalone monitors.
| Leading Market Players |
|---|
| Bacharach Inc. |
| TSI Incorporated |
| Testo SE & Co. KGaA |
| Sauermann Group |
| Kane International Limited |
| Fluke Corporation |
| UEi Test Instruments |
| PCE Instruments |
| Fieldpiece Instruments Inc. |
| Others |
Supply & Pricing Matrix
Multi-year calibration service contracts lock in both supply access and price visibility for analyzer manufacturers serving commercial building operators in Germany and the United States. These bundled arrangements concentrate procurement authority with national service integrators while insulating vendors from spot-price volatility in sensor module markets.
Pricing Analysis
EPA refrigerant management regulations under the AIM Act dictate the pricing tier structure across the HVAC analyzer market. Three-tier pricing structure across premium, standard, and economy levels separates firmware-modular multi-parameter units from fixed-sensor legacy designs and entry-level combustion-only devices. Certification grade under CE marking and OSHA calibration traceability standards commands measurable premiums. Cost compression in economy-tier portable units is intensifying because electrochemical sensor commoditization erodes hardware differentiation. Small independent contractors in residential settings exhibit highest price sensitivity, while facility managers in Class A office buildings prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Germany and Japan anchor precision electrochemical sensor fabrication for combustion gas detection, while Taiwan and South Korea supply infrared thermography modules and solid-state pressure transducers. Analyzer assemblers in the United States and China draw from these concentrated upstream nodes for core sensing subsystems. Single-source vulnerability in specialized thermal imaging optics exposes production schedules to allocation risk during demand surges. Distribution runs through authorized service distributors and direct enterprise sales teams to mechanical contractors and facility management procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC analyzer market is recovering from a cyclical trough as commercial building retrofit mandates accelerate replacement cycles. Equipment refresh driven by refrigerant chemistry transitions under EPA and EU protocols is restoring pricing power to vendors with modular firmware architectures.
For Market Incumbents: Fortify sensor calibration service attach rates through predictive maintenance SaaS bundling, converting one-time hardware sales into recurring revenue streams. Deepen backward integration into electrochemical cell production to defend margins against commodity sensor price erosion. Prioritize firmware modularity investments that extend product lifespans across refrigerant protocol transitions, neutralizing obsolescence risk from rapid chemistry evolution under F-Gas and AIM Act mandates. For New Entrants and Emerging Players: Lead with indoor air quality convergence as the most penetrable white-space target, displacing standalone particulate and VOC monitors in facility manager budgets. Target mid-market HVAC contractors in India and China where state-level energy efficiency incentives subsidize diagnostic equipment purchases but premium incumbents lack localized service infrastructure. Pursue utility rebate program certification as the primary go-to-market angle, leveraging subsidized procurement channels to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among analyzer manufacturers with embedded cellular connectivity and cloud-based performance analytics platforms. Long-term viability over the coming decade hinges on refrigerant chemistry adaptability and calibration service network density. Prioritize acquisition targets with modular sensor cartridge designs and established enterprise calibration contracts. Monitor EPA refrigerant phasedown implementation velocity as the critical inflection indicator for hardware refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Modularity Investment | Modular cartridge designs extend product relevance across R-454B and R-1234yf refrigerant transitions mandated by EPA. |
| Predictive Maintenance SaaS Launch | Cellular-enabled fault alerting captures facility manager budgets previously allocated to standalone building automation systems. |
| Calibration Service Network Expansion | Dense service infrastructure in Germany and the United States locks in multi-year contracts with national mechanical contractors. |
| Indoor Air Quality Sensor Integration | Particulate and VOC sensing displaces standalone IAQ monitor procurement in Class A office buildings across Chicago and Atlanta. |
| Utility Rebate Program Certification | State-level incentive eligibility in California and New York lowers effective price barriers for mid-market contractor segments. |
Research Methodology
The analysis maps portable analyzers, multi-parameter platforms, fixed installations, and combustion-specific units, each validated through facility managers, HVAC service contractors, calibration service technicians, and building automation system integrators. Primary interviews with these stakeholders combined with secondary validation from EPA refrigerant management filings, EU F-Gas Regulation compliance databases, OSHA confined-space standard documentation, and SEC filings from listed instrumentation manufacturers. Bottom-up unit economics triangulated against top-down market sizing from trade association shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application, technology, and end-user dimensions alongside refrigerant chemistry compatibility tiers. CAGRs were derived from segmented growth trajectory analysis. Forecast inputs incorporated commercial building energy ordinance implementation schedules and electrochemical sensor miniaturization adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of refrigerant phasedown timelines or accelerated refrigerant chemistry transitions would require recalibration. Forecasts reflect documented assumptions regarding calibration service contract renewal rates and Wi-Fi-enabled device penetration in mechanical contractor fleets. Recalibration cycles align with material shifts in EPA AIM Act implementation velocity and EU F-Gas Regulation amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Global Air Conditioner Market