
 Kuwait Construction Market | 2026-2036
Kuwait Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Construction Market Outlook
Multi-source procurement is shifting toward consolidated design-build arrangements among Kuwaiti contractors. Combined Group Contracting Company leverages its integrated project delivery capability across infrastructure and industrial assignments. Hyundai Engineering & Construction anchors large-scale developments through its established presence in the Gulf region. Gulf Dredging & General Contracting Company specializes in marine and land reclamation works that sustain its niche dominance.
Kuwait construction encompasses the planning, engineering, procurement, and assembly of built structures using reinforced concrete, structural steel, curtain-wall glass, and engineered timber systems, with concrete formulations typically achieving 30-50 MPa compressive strength for high-rise applications. The sector serves housing provision, commercial facility operation, industrial production, and transport connectivity for government and private clients. Infrastructure project types currently absorb the largest share of public capital allocation, while residential segments face accelerated demand pressure from Kuwait's housing welfare backlog. Design-build service types are capturing margin pools by compressing project timelines and reducing interface risk between designers and builders.
Kuwait Municipality building codes, the Public Authority for Housing Welfare technical standards, and Ministry of Public Works procurement regulations collectively govern material specifications, contractor qualification, and project handover protocols. These frameworks elevate compliance costs for entrants while privileging established firms with demonstrated local delivery records. Stakeholders must monitor how Kuwait's national development plan revisions redirect contract awards between government direct commissioning and public-private structures.
Market Dynamics
Kuwait's construction sector is reconfiguring around the Public Authority for Housing Welfare's accelerated project mandates, which compress procurement cycles and favor contractors with pre-qualified design-build capabilities.
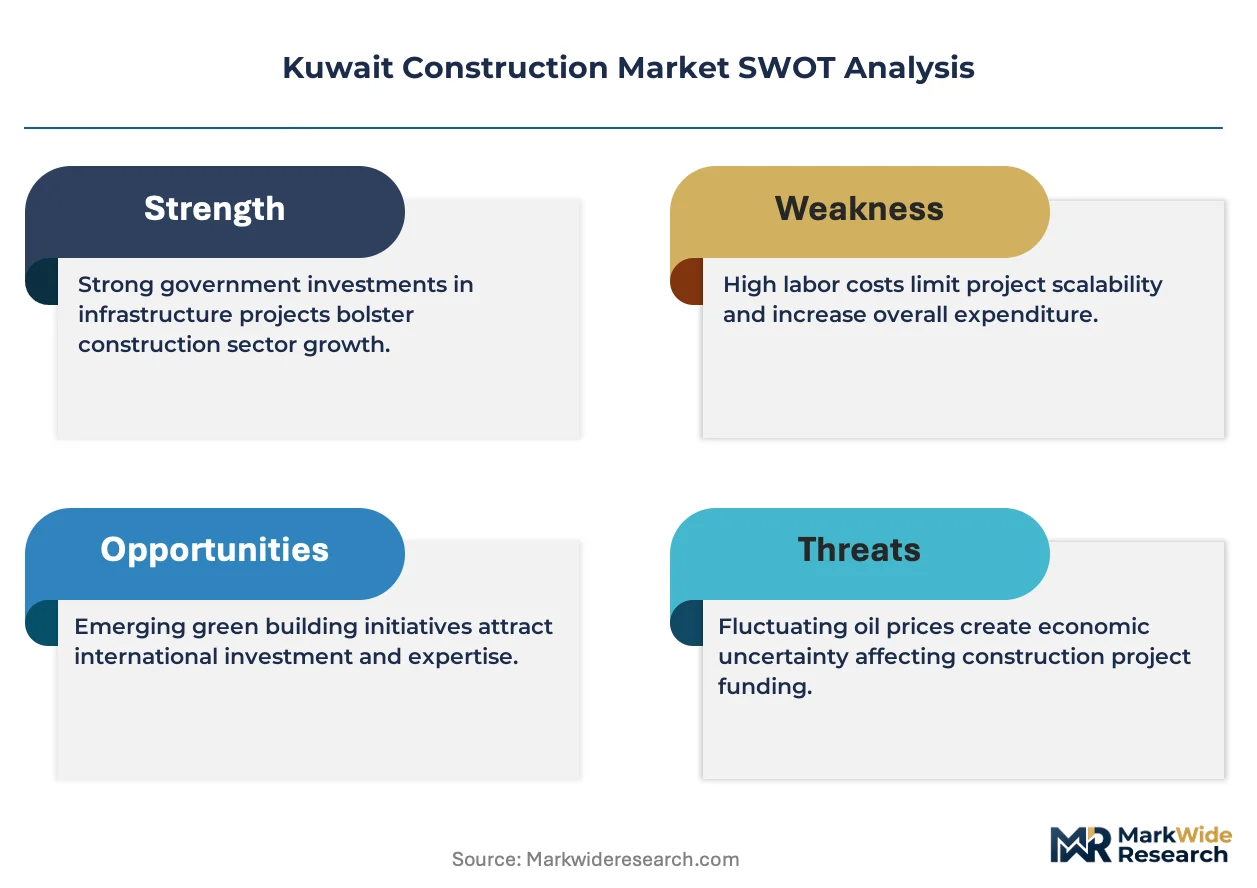
Growth Catalysts
- South Al-Mutlaa City Development:Government-backed new city construction channels contractor resources into integrated residential infrastructure, creating sustained demand for earthworks, utilities, and building envelope systems.
- Public Authority for Housing Welfare Technical Standards:Standardized material specifications and contractor pre-qualification reduce bid preparation friction for established firms while streamlining project handover protocols.
- Design-Build Consolidation:Single-source contracting arrangements compress project timelines and eliminate interface risk between architectural designers and construction execution teams.
Market Restraints
- Reinforcement Steel Price Volatility:Global scrap metal and billet supply fluctuations transmit directly into Kuwaiti reinforced concrete cost structures, compressing fixed-price contract margins.
- Specialized Marine Equipment Concentration:Land reclamation and dredging capacity concentrates among a limited pool of regional contractors with heavy fleet ownership, constraining entry for new participants.
- Kuwait Municipality Building Code Compliance Burden:Evolving fire safety and seismic resistance standards require recurrent engineering redesigns, extending pre-construction phases.
Strategic Opportunities
- Jahra Governorate Residential Undersupply:Peripheral governorate housing stock deficits present white space for developers willing to operate outside South Al-Mutlaa's saturated contractor landscape.
- Engineered Timber Hybrid Systems:Cross-laminated timber and glulam integration with concrete cores offers carbon footprint reduction for government clients with sustainability procurement criteria.
- Ministry of Public Works Public-Private Partnership Models:Emerging availability payment and revenue-sharing structures transfer construction risk to private operators while securing long-term maintenance revenue streams.
Industry Challenges
- Project Management Professional Scarcity:Shortage of locally certified construction managers fluent in FIDIC contract administration delays site mobilization and claims resolution.
- Curtain-Wall Installation Skill Gaps:Limited pool of technicians qualified for unitized facade system waterproofing and thermal break installation extends high-rise enclosure schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Construction Market |
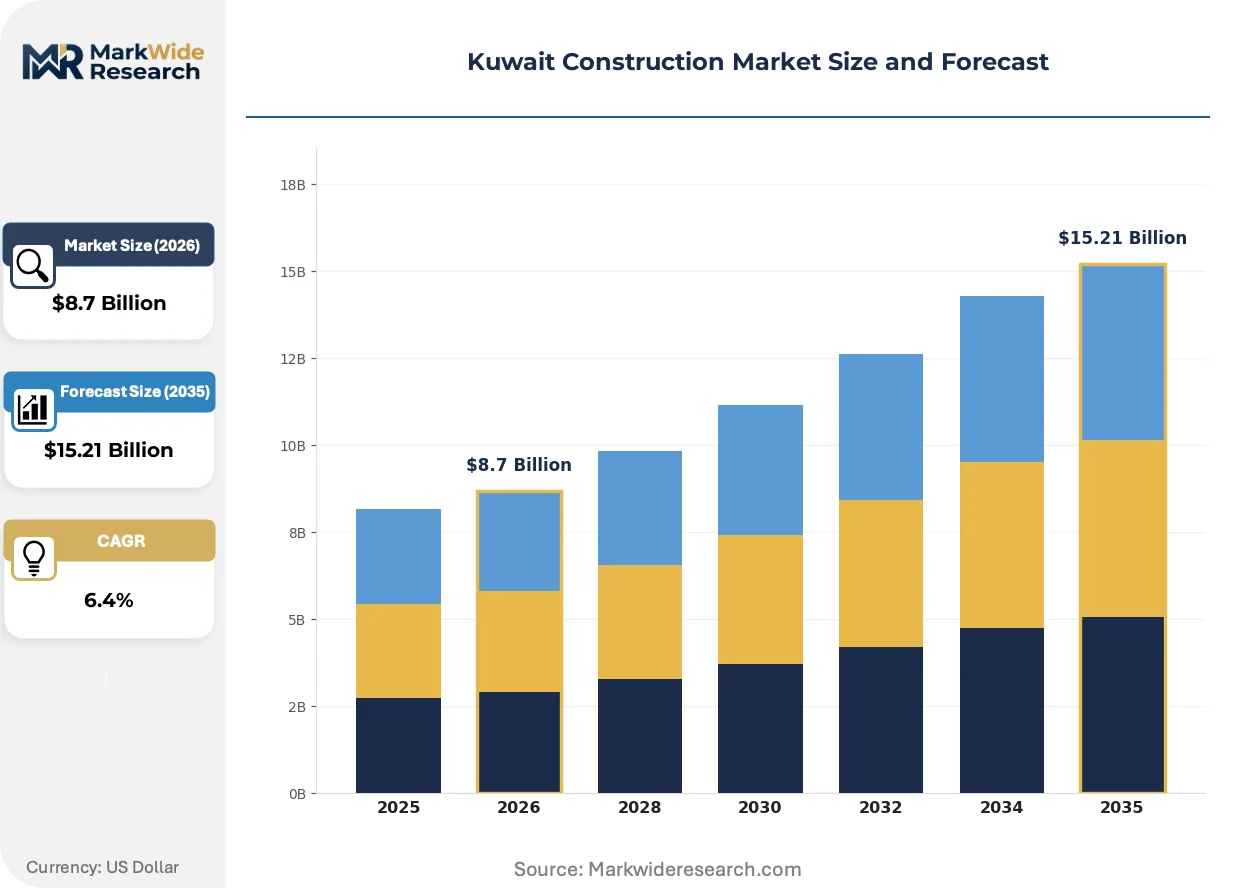
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Glass, Wood Service Type: Construction Management, Design-Build, General Contracting, Renovation End User: Government, Private Sector, Real Estate Developers, Non-Profit Organizations |
| Companies Covered | Mushrif Trading and Contracting Company, Kuwait Company for Process Plant Construction & Contracting (KCPC), Combined Group Contracting Company, Gulf Dredging & General Contracting Company, Hyundai Engineering & Construction, Heavy Engineering Industries & Shipbuilding Company (HEISCO), ACICO Group, Mohammed Abdulmohsin Al-Kharafi & Sons (MAK), Alghanim Engineering Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Construction Market Strategic Shifts
Prefabrication and digital coordination tools are compressing traditional construction sequences in Kuwait, while regulatory pressure on housing delivery timelines accelerates adoption of non-conventional delivery models.
Modular bathroom pods and precast concrete wall panels are modularizing high-rise residential construction in Kuwait. Major real estate developers now specify factory-cast volumetric units for repetitive tower typologies, cutting on-site wet trades by half. This shift compresses critical path schedules and reduces labor camp population pressure on project sites.
Kuwait Municipality has tightened enforcement of post-occupancy energy performance verification for commercial buildings above 10,000 square meters. Developers must now submit actual consumption data within two years of handover, with penalties for deviation from design-stage modeling. Large-scale mixed-use projects in Kuwait City are responding by integrating building management system commissioning into construction contracts rather than treating it as owner handover.
Integrated project delivery contracts with shared risk-reward pools are displacing traditional lump-sum tendering for complex infrastructure assignments. Kuwait's Ministry of Public Works now pilots collaborative contracting on arterial road upgrades, with designers and builders co-locating during schematic phases. This behavioral shift is most visible on the Fifth Ring Road expansion, where early contractor involvement has reduced change order incidence.
Kuwait Construction Market Segmentation
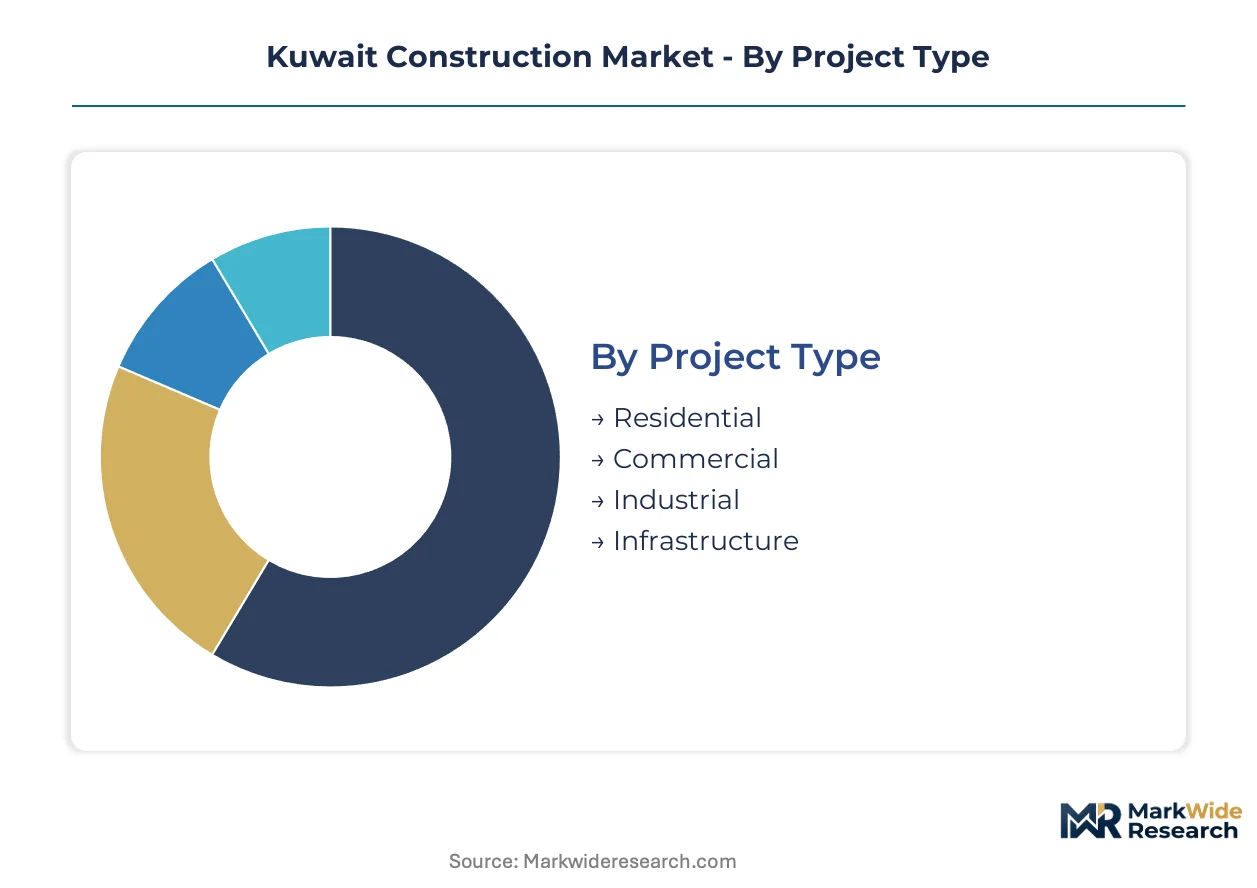
Construction demand in Kuwait fragments across project scale, material specification, procurement method, and client risk appetite. Each segmentation axis reveals distinct margin profiles and capability requirements that shape contractor positioning.
Project Type:
Scale and procurement complexity separate buyers across residential, commercial, industrial, and infrastructure categories.
- Infrastructure:Arterial roads, utilities, and transport nodes absorb the largest share of Ministry of Public Works capital allocation. South Al-Mutlaa city development channels earthworks and utility contractors into integrated delivery packages with compressed timelines.
- Residential:High-rise towers and villa compounds dominate output, with Public Authority for Housing Welfare mandates accelerating project cycles. Prefabricated bathroom pods and precast wall panels are modularizing repetitive typologies to meet backlog reduction targets.
- Commercial:Mixed-use developments in Kuwait City face tightened post-occupancy energy verification requirements above 10,000 square meters.
- Industrial:Refinery adjacent construction and logistics facilities demand specialized structural steel and fire-resistant envelope systems.
Volume sits with Infrastructure; growth tilts toward Residential.
Material Type:
Performance specifications and supply chain exposure differentiate material selection across project portfolios.
- Concrete:Formulations achieving 30-50 MPa compressive strength anchor high-rise structural cores. South Al-Mutlaa's residential towers specify precast concrete wall panels to compress critical path schedules and reduce on-site labor camp pressure.
- Steel:Reinforcement bar and structural sections face margin compression from global scrap metal and billet price volatility.
- Glass:Unitized curtain-wall systems with thermal break specifications dominate commercial facade procurement.
- Wood:Cross-laminated timber and glulam hybrid systems are penetrating government sustainability procurement criteria.
Concrete commands current volume; engineered timber climbs the fastest on carbon reduction mandates.
Service Type:
Risk allocation and timeline compression drive procurement method selection.
- Design-Build:Single-source contracting eliminates interface risk between designers and builders while compressing handover schedules. Ministry of Public Works pilots collaborative contracting with shared risk-reward pools on arterial road upgrades.
- Construction Management:Agency-style delivery persists for complex industrial assignments where owner-retained risk is preferred.
- General Contracting:Lump-sum tendering faces displacement on complex infrastructure as integrated project delivery gains traction.
- Renovation:Existing building energy retrofits expand with Municipality enforcement of consumption verification deadlines.
General Contracting retains legacy volume; design-build captures expanding share through risk-transfer preference.
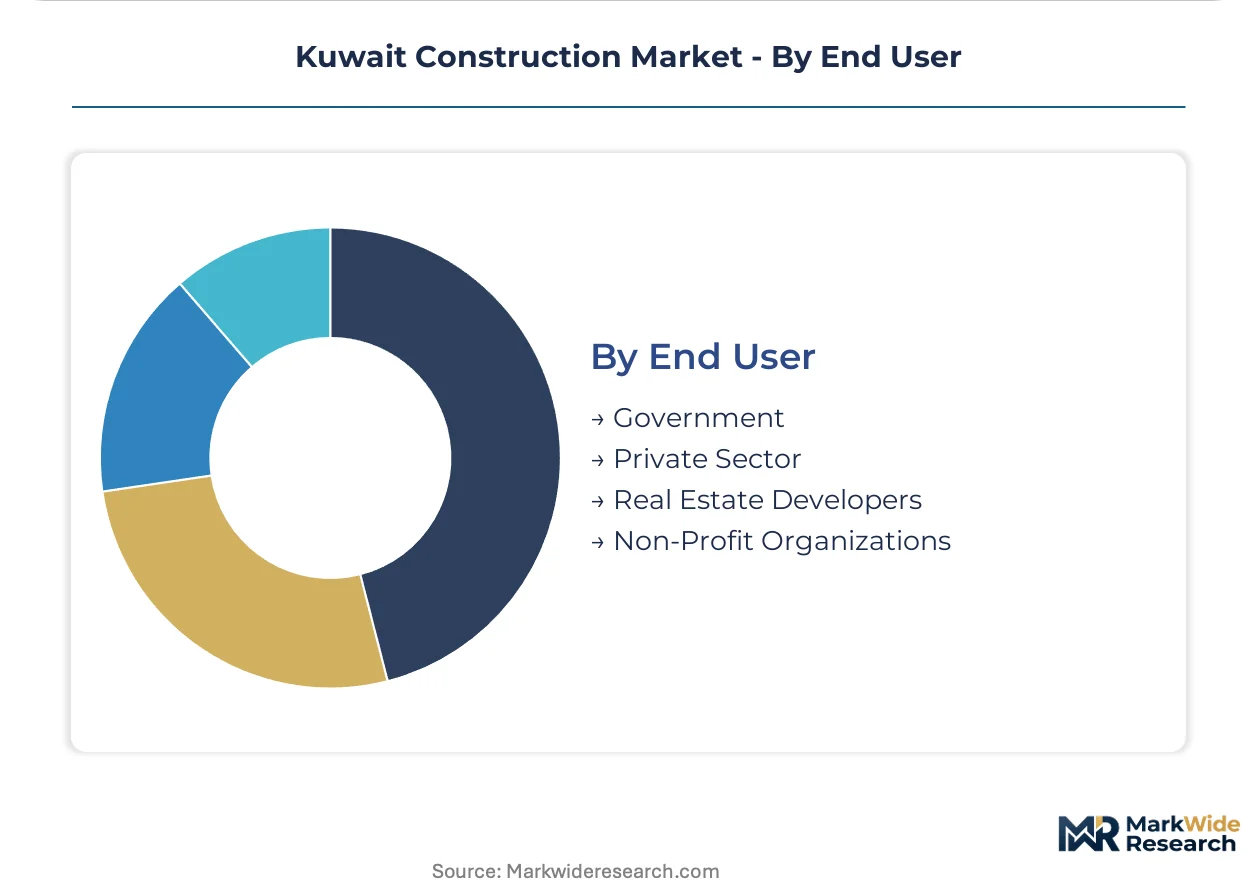
End User:
Budget certainty and procurement flexibility separate public commissioning from private development.
- Government:Ministry of Public Works and Public Authority for Housing Welfare dominate capital allocation with standardized technical specifications and pre-qualification requirements that privilege established delivery records.
- Real Estate Developers:Private towers in Kuwait City integrate building management system commissioning into construction contracts to meet post-occupancy verification mandates.
- Private Sector:Industrial clients and commercial owner-occupiers specify performance-based procurement with extended maintenance obligations.
- Non-Profit Organizations:Limited project scale concentrates in social housing and community facility assignments.
Government contracts anchor volume; real estate developers show steepest expansion trajectory on housing welfare backlog reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone quarries in the Jahra Governorate supply the aggregate base for Kuwait's concrete production, anchoring material flows to South Al-Mutlaa's residential tower clusters.
Kuwait City Metropolitan Area
High-rise commercial towers and mixed-use developments concentrate demand for unitized curtain-wall systems and building management system integration. Kuwait Municipality enforces post-occupancy energy verification mandates above 10,000 square meters. The Sharq and Kuwait City districts host the densest contractor bidding activity for government-backed infrastructure.
South Al-Mutlaa Development Zone
Integrated residential city construction channels earthworks, utilities, and precast concrete panel demand into consolidated design-build packages. Public Authority for Housing Welfare technical standards compress procurement cycles and privilege pre-qualified contractors. The new city site absorbs the largest share of Ministry of Public Works capital allocation for residential backlog reduction.
Jahra Governorate
Peripheral housing stock deficits present undeveloped territory for residential contractors outside South Al-Mutlaa's saturated bidding landscape. The governorate's limestone quarries anchor regional concrete supply chains. Jahra's industrial zones host precast manufacturing facilities serving tower construction across northern Kuwait.
Ahmadi Governorate
Refinery-adjacent industrial construction and logistics facilities demand specialized structural steel and fire-resistant envelope systems. The country's petroleum regulator mandates safety specifications for hydrocarbon-proximate builds. Mina Al-Ahmadi and surrounding industrial clusters concentrate heavy engineering contractor presence.
Hawalli Governorate
Dense residential redevelopment and commercial retrofit activity drives renovation sector growth. Existing building energy retrofits expand with Municipality enforcement of consumption verification deadlines. The Salmiya and Hawalli districts concentrate mid-rise residential tower replacement cycles.
Kuwait Construction Market Competitive Environment
Consolidated design-build capability expansion dominates the current landscape, with established contractors capturing margin pools through timeline compression. The vendor base clusters around three archetypes: integrated infrastructure specialists with heavy fleet ownership, design-build consolidators with pre-qualification advantages, and marine reclamation niche players with dredging capacity concentration. M&A activity and strategic pre-qualification positioning represent the dominant competitive moves as contractors defend access to Public Authority for Housing Welfare procurement channels.
Among Kuwait-based integrated contractors, Combined Group Contracting Company and Gulf Dredging & General Contracting Company exemplify the design-build and marine specialization archetypes respectively. Hyundai Engineering & Construction anchors the Gulf-experienced foreign contractor tier. Mushrif Trading and Contracting Company occupies a position within the established local delivery network, while Heavy Engineering Industries & Shipbuilding Company represents the industrial-heavy engineering crossover segment.
| Leading Market Players |
|---|
| Mushrif Trading and Contracting Company |
| Kuwait Company for Process Plant Construction & Contracting (KCPC) |
| Combined Group Contracting Company |
| Gulf Dredging & General Contracting Company |
| Hyundai Engineering & Construction |
| Heavy Engineering Industries & Shipbuilding Company (HEISCO) |
| ACICO Group |
| Mohammed Abdulmohsin Al-Kharafi & Sons (MAK) |
| Alghanim Engineering Group |
| Others |
Value Chain & Pricing Dynamics
Reinforcement steel billet indices transmit volatility directly into Kuwaiti contractor bidding strategies, cascading from global scrap metal markets through precast concrete cost structures and into project-specific pricing tiers that separate design-build integrators from lump-sum tenderers.
Pricing Analysis
Extended warranty and post-handover maintenance bundling now separates premium design-build proposals from unbundled general contracting bids. Three-tier pricing structure across integrated delivery, construction management, and traditional lump-sum levels reflects contractor qualification status and risk retention. Cost compression in fixed-price residential segments is intensifying because Public Authority for Housing Welfare procurement cycles compress margin buffers. Real estate developers show highest price sensitivity on high-rise envelope systems, while government clients prioritize timeline certainty over unit cost.
Supply Chain Analysis
Freight costs from UAE and Saudi Arabia precast manufacturing hubs to South Al-Mutlaa development sites anchor regional logistics expenditure. Material flows draw from Omani limestone aggregates, Turkish reinforcement steel, and Chinese curtain-wall components. Single-source vulnerability concentrates in specialized marine dredging equipment held by Gulf Dredging & General Contracting Company. Distribution runs through Ministry of Public Works pre-qualified contractor networks with direct commissioning authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait Municipality building code evolution operates as a cost-of-compliance story, where escalating fire safety and seismic resistance standards erect barrier-to-entry moats that privilege established contractors with demonstrated local delivery records.
For Market Incumbents: Deepen design-build capability consolidation to defend against emerging regional entrants from Saudi Arabia and UAE. Invest in precast concrete manufacturing capacity within Jahra Governorate to shorten material lead times. Secure Public Authority for Housing Welfare pre-qualification renewals ahead of South Al-Mutlaa package releases.
For New Entrants and Emerging Players: Local engineering consultancies represent the most accessible channel partnership for bypassing direct contractor pre-qualification barriers. Target Jahra Governorate peripheral housing deficits where established contractor saturation is lowest. Pursue specialty subcontractor positioning in curtain-wall installation or building management system commissioning rather than prime contracting.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap design-build specialists with dormant heavy equipment fleets in Ahmadi Governorate. Long-term viability hinges on exposure to Ministry of Public Works public-private partnership pipeline expansion. Monitor Public Authority for Housing Welfare procurement channel access as the decisive inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Capability Expansion | Compresses project timelines and eliminates designer-builder interface risk for Public Authority for Housing Welfare mandates. |
| Precast Manufacturing Capacity Addition | Reduces on-site labor camp pressure while meeting South Al-Mutlaa residential tower delivery schedules. |
| Curtain-Wall Installation Certification Investment | Addresses technician scarcity for unitized facade waterproofing and thermal break installation. |
| Public-Private Partnership Positioning | Secures long-term maintenance revenue streams under Ministry of Public Works collaborative contracting pilots. |
| Engineered Timber Hybrid System Development | Aligns contractor portfolios with government sustainability procurement criteria for carbon footprint reduction. |
Study Parameters
Kuwait Central Statistical Bureau construction permits, Ministry of Public Works procurement disclosures, and Public Authority for Housing Welfare project announcements formed the secondary backbone. Primary interviews with project directors at integrated contractors, procurement officers at real estate developers, and technical standards engineers at Kuwait Municipality validated segment assumptions. Bottom-up project pipeline aggregation and top-down GDP-investment-ratio calibration enabled cross-verification.
Bottom-up modeling anchored volume estimates to named project capacities across the analysis window, while top-down expenditure ratios tested plausibility against national accounts. Segmentation dimensions covered project type, material specification, service delivery model, and end-user procurement channel. CAGRs derived from slope analysis of investment trajectory curves, with reinforcement steel price volatility and contractor pre-qualification velocity as construction-specific sensitivity inputs.
Caveats apply where Public Authority for Housing Welfare mandate revisions or Kuwait Municipality code amendments could materially shift the outlook. Forecasts reflect documented assumptions about procurement channel access and material cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Thailand Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Indonesia Infrastructure Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
Egypt Construction Market
Building Construction
Construction Market
Building Construction
Malaysia Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
South Africa Prefabricated Buildings Market