
 Thermo Ventilators Market | 2026-2036
Thermo Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Thermo Ventilators Market Analysis
Healthcare infrastructure spending is decoupling from traditional commercial construction cycles as hospitals prioritize climate-controlled isolation environments. Johnson Controls International plc leverages its building automation portfolio to integrate thermo ventilators with centralized energy management platforms. Siemens AG anchors European demand through its dominance in smart HVAC retrofit contracts for hospital networks. Daikin Industries, Ltd. competes on refrigerant technology leadership and manufacturing scale across Asian supply chains.
Thermo ventilators are electromechanical devices that combine temperature modulation with forced air exchange, typically operating across flow rates from 50 to 500 cubic meters per hour and incorporating heat recovery exchangers to capture thermal energy from exhaust streams. Their primary commercial purpose centers on maintaining indoor air quality while minimizing energy loss in enclosed environments with high occupancy or contamination sensitivity. Fixed installations lead the product type category due to permanent infrastructure integration in healthcare and industrial facilities, while smart technology represents the fastest-expanding segment as IoT-enabled units enable predictive maintenance and real-time air quality monitoring. Exhaust-type thermo ventilators occupy mature margin pools in residential retrofits where simpler specifications dominate procurement criteria.
The U.S. Department of Energy efficiency standards, EU Ecodesign regulations under the EU Green Deal framework, and Japan's METI Top Runner program collectively mandate minimum heat recovery efficiency thresholds that filter non-compliant products from market access. China's GB standards and NMPA-linked healthcare facility codes further constrain import eligibility for thermo ventilators deployed in medical settings. Stakeholders must monitor regulatory divergence between energy-efficiency mandates and healthcare-specific air purity certifications when configuring product portfolios for cross-border deployment.
Market Dynamics
Healthcare infrastructure spending is decoupling from traditional commercial construction cycles as hospitals prioritize climate-controlled isolation environments. Johnson Controls International plc leverages its building automation portfolio to integrate thermo ventilators with centralized energy management platforms. Siemens AG anchors European demand through its dominance in smart HVAC retrofit contracts for hospital networks. Daikin Industries, Ltd. competes on refrigerant technology leadership and manufacturing scale across Asian supply chains.
Growth Catalysts
- EU Ecodesign regulations:Minimum heat recovery efficiency thresholds under the EU Green Deal framework are accelerating replacement cycles in Germany and France. Healthcare facilities must upgrade exhaust-type units to comply with 2024 efficiency mandates.
- Japan's METI Top Runner program:Energy performance labeling is compressing product lifecycles in commercial buildings. Building operators in Tokyo and Osaka face procurement pressure to exceed baseline efficiency standards.
- Heat pump integration:Hybrid thermo ventilator-heat pump systems are capturing specification share in Nordic retrofit markets. The technology reduces auxiliary heating loads in sub-zero climates.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger manufacturing faces input cost pressure from base metal commodity swings. Procurement teams struggle to hedge exposure across 12-18 month project timelines.
- Refrigerant supply concentration:Low-GWP refrigerant production clusters in China and Japan, creating import dependency for European and North American OEMs. F-Gas quota allocations constrain volume planning.
- Retrofit compatibility limits:Legacy ductwork dimensions in 1970s-era commercial buildings restrict airflow capacity upgrades. Mechanical contractors encounter structural modification costs that stall project approvals.
Strategic Opportunities
- India hospital construction:Greenfield healthcare infrastructure under the Ayushman Bharat expansion lacks installed HVAC base, creating specification windows for integrated thermo ventilator systems. Tier-2 and Tier-3 cities present first-mover positioning.
- IoT-enabled predictive maintenance:Sensor-embedded units are opening recurring revenue streams through remote diagnostics contracts. Equipment-as-a-service models reduce upfront capital barriers for mid-sized facility operators.
- US Inflation Reduction Act efficiency credits:Tax incentives for building electrification are redirecting commercial retrofit budgets toward heat-recovery ventilation. Property developers in California and New York are bundling thermo ventilators into net-zero certification pathways.
Industry Challenges
- Cross-certification complexity:Healthcare deployment requires simultaneous compliance with ASHRAE ventilation standards and Joint Commission infection control protocols. Documentation timelines extend bid-to-award cycles by 4-6 months.
- Controls integration friction:BACnet and Modbus protocol mismatches between legacy building management systems and new smart ventilator units demand custom middleware development. Commissioning engineers report 15-20% of projects require post-installation software remediation.
- Specialized technician scarcity:Heat recovery exchanger maintenance and refrigerant handling certifications are concentrated among aging workforce cohorts in Germany and Japan. Training pipeline gaps threaten service response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermo Ventilators Market |
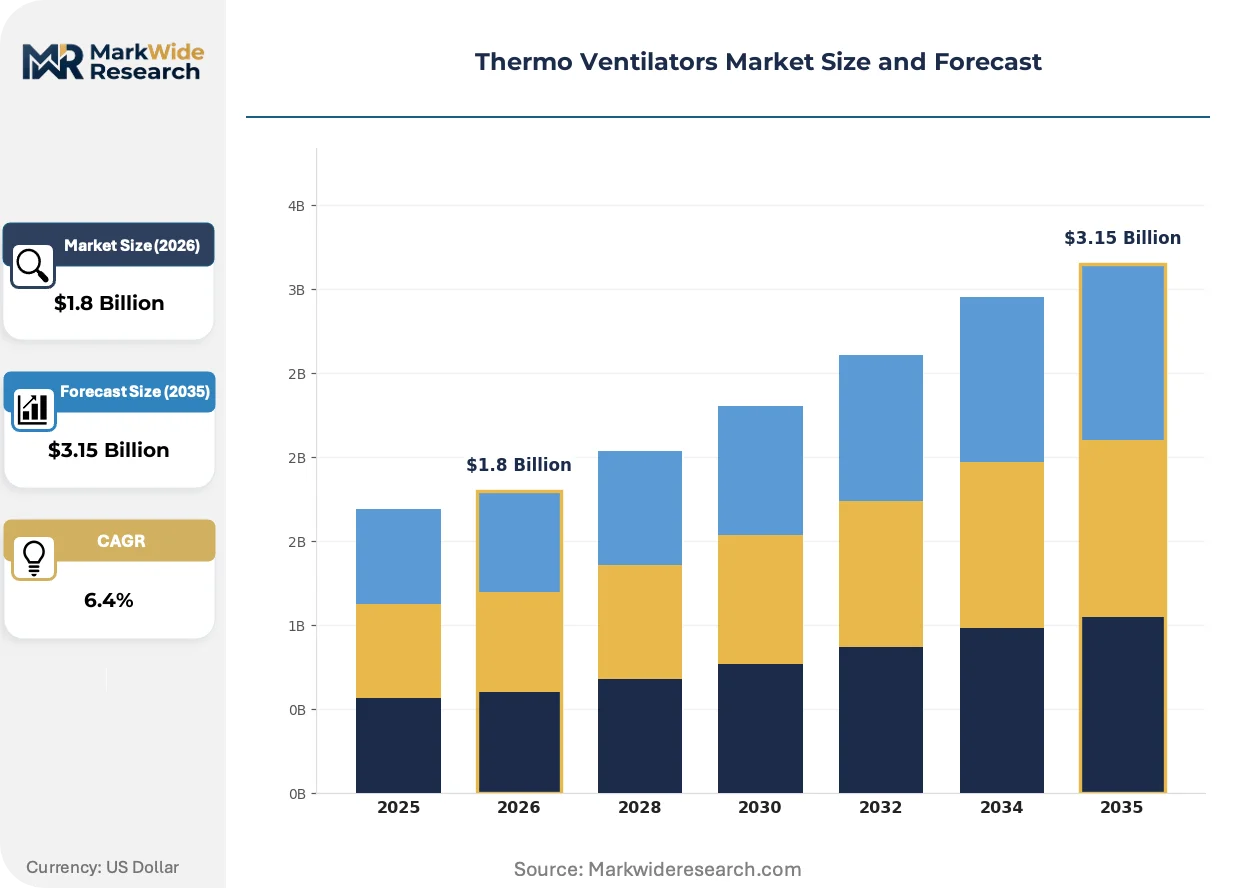
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Exhaust, Hybrid Technology: Solar Powered, Electric, Mechanical, Smart End User: Commercial Buildings, Industrial Facilities, Residential Homes, Healthcare Institutions Application: Air Quality Control, Temperature Regulation, Ventilation Systems, Environment Management |
| Companies Covered | Johnson Controls International plc, Siemens AG, Honeywell International Inc, Daikin Industries, Ltd., Mitsubishi Electric Corporation, Panasonic Corporation, Carrier Global Corporation, Trane Technologies plc, Lennox International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermo Ventilators Market Emerging Trajectories
Smart technology represents the fastest-expanding segment as IoT-enabled units enable predictive maintenance and real-time air quality monitoring. Fixed installations lead the product type category due to permanent infrastructure integration in healthcare and industrial facilities.
Desiccant-enhanced enthalpy recovery wheels are unifying humidity control with sensible heat exchange in a single rotating component. Hospital networks in the Netherlands and Belgium are specifying these units for operating theater applications. The technology is unifying previously separate dehumidification and ventilation capital expenditures into consolidated procurement packages.
REACH restrictions on per- and polyfluoroalkyl substances are forcing refrigerant formulation changes across European supply chains. OEMs face reformulation costs and retesting cycles for compressor lubricant compatibility. Medical-grade thermo ventilators with ultra-low leakage specifications encounter the tightest compliance timelines under the 2025 enforcement window.
Facility managers are consolidating vendor relationships around full-HVAC-system contractors rather than component specialists. Independent thermo ventilator distributors in the United States are losing specification influence to integrated mechanical contractors. The pattern is most visible in the Southeast, where design-build firms now control 60% of commercial healthcare ventilation procurement decisions.
Thermo Ventilators Market Segmentation
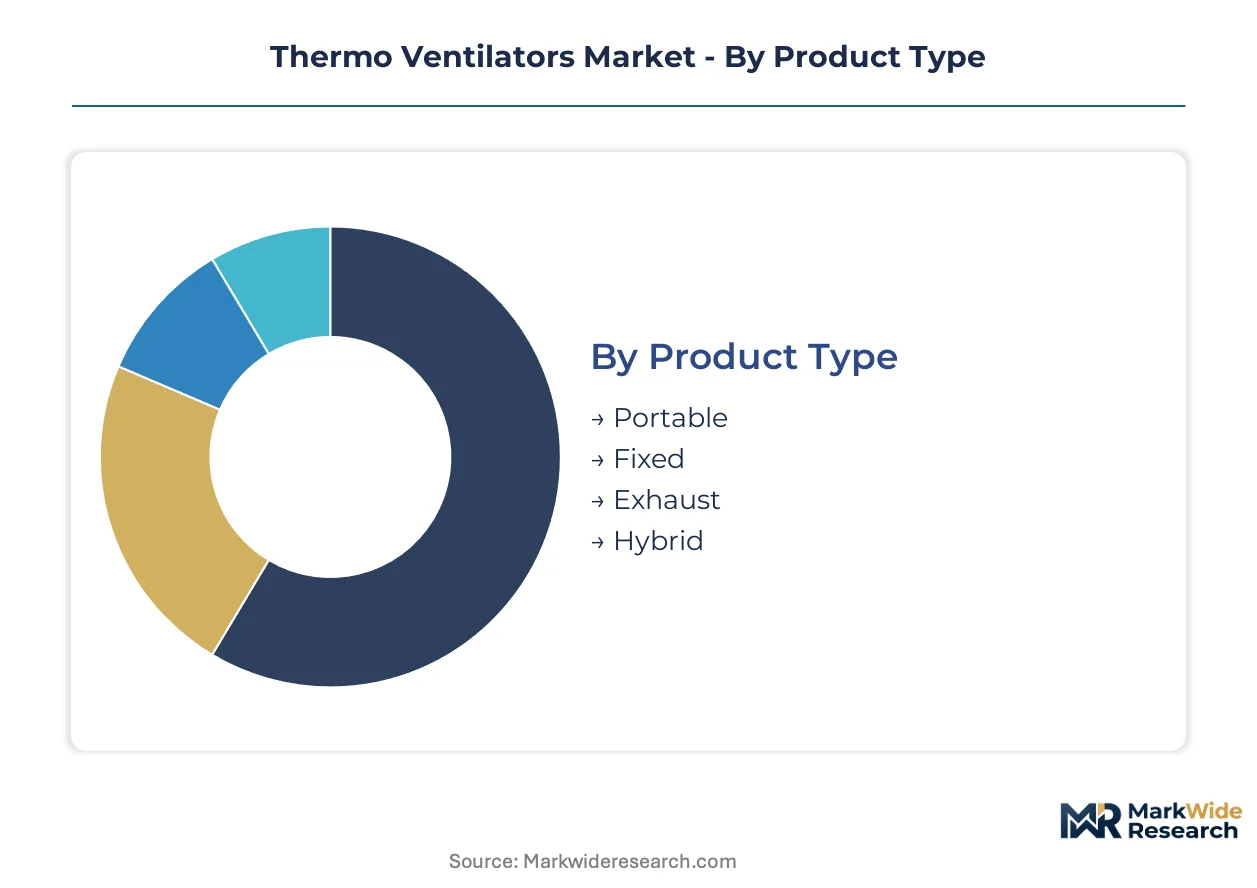
Thermo ventilator procurement patterns diverge sharply across installation permanence, power source, and regulatory environment. Segmentation reveals where specification power concentrates and which technology trajectories command capital allocation priority.
Product Type:
Supply concentration in heat exchanger fabrication favors permanent infrastructure solutions over mobile alternatives, with OEM capacity clustering around fixed-mount production lines in Germany and Japan.
- Fixed:Permanent wall or ceiling-mounted units integrate with building HVAC infrastructure and typically incorporate enthalpy recovery wheels rated for 10-15 year service intervals. Demand concentrates in German hospital retrofit contracts where EU Ecodesign mandates require minimum 73% heat recovery efficiency. Siemens AG and Johnson Controls dominate specification channels through bundled building automation contracts.
- Portable:Self-contained units with caster mounting and plug-in power connections serve temporary isolation environments and construction-phase air quality management. Demand clusters in US healthcare emergency preparedness stockpiling and Japanese disaster response procurement, where rapid deployment overrides efficiency optimization.
- Exhaust:Single-flow units without heat recovery function occupy mature residential replacement cycles where first-cost sensitivity dominates procurement. These units face phase-out pressure under EU Green Deal efficiency thresholds.
- Hybrid:Dual-mode systems switch between heat recovery and direct exhaust based on occupancy sensors or contamination detection. These units capture specification share in Nordic commercial buildings with variable occupancy patterns.
Today's leader: Fixed. Tomorrow's challenger: Hybrid.
Technology:
Cost tier stratification separates premium sensor-integrated systems from commodity electromechanical units, with price multiples of 3-4x between smart and mechanical categories.
- Smart:IoT-enabled units embed particulate sensors, CO2 monitors, and cloud-connected predictive maintenance algorithms. Demand concentrates in US commercial healthcare networks pursuing Joint Commission accreditation through continuous air quality documentation. Johnson Controls and Daikin Industries anchor this segment through proprietary building management system integration.
- Electric:Grid-powered units with variable-speed EC motors and electronic commutated drive systems dominate mid-market commercial specifications. These units balance efficiency compliance with capital cost constraints across German and Japanese building codes.
- Solar Powered:Photovoltaic-integrated units with battery storage target off-grid healthcare facilities and net-zero certification pathways in California and Australia. Limited production scale constrains cost competitiveness below 50 units per project.
- Mechanical:Basic electromechanical units with AC induction motors and fixed-speed operation serve price-sensitive residential retrofits and developing market greenfield construction. These units face specification erosion as minimum efficiency regulations tighten.
Smart technology commands premium positioning. Electric systems defend volume dominance.
End User:
Application maturity separates regulated healthcare procurement from discretionary commercial construction, with healthcare contracts carrying 18-24 month qualification timelines versus 3-6 month commercial cycles.
- Healthcare Institutions:Hospitals, clinics, and long-term care facilities specify medical-grade units with HEPA filtration integration and ultra-low leakage certification. China's NMPA facility codes and US ASHRAE ventilation standards create dual compliance burdens for cross-border suppliers. Daikin Industries and Siemens AG maintain dedicated healthcare certification teams.
- Commercial Buildings:Office towers, retail complexes, and hospitality properties prioritize heat recovery efficiency for operating cost reduction. Demand concentrates in US Inflation Reduction Act retrofit pathways and EU Green Deal commercial building renovations.
- Industrial Facilities:Manufacturing plants and warehousing operations specify heavy-duty units with corrosion-resistant coatings and explosion-proof electrical enclosures. These applications tolerate higher noise profiles and prioritize airflow capacity over efficiency metrics.
- Residential Homes:Single-family and multi-family housing units drive exhaust-type volume through replacement cycles triggered by failure rather than efficiency upgrade. Japanese METI Top Runner labeling is compressing product lifecycles in this segment.
Healthcare Institutions anchor margin pools. Commercial Buildings offer volume scale.
Application:
Customer type stratification separates integrated HVAC contractors seeking full-system solutions from component specialists competing on unit price.
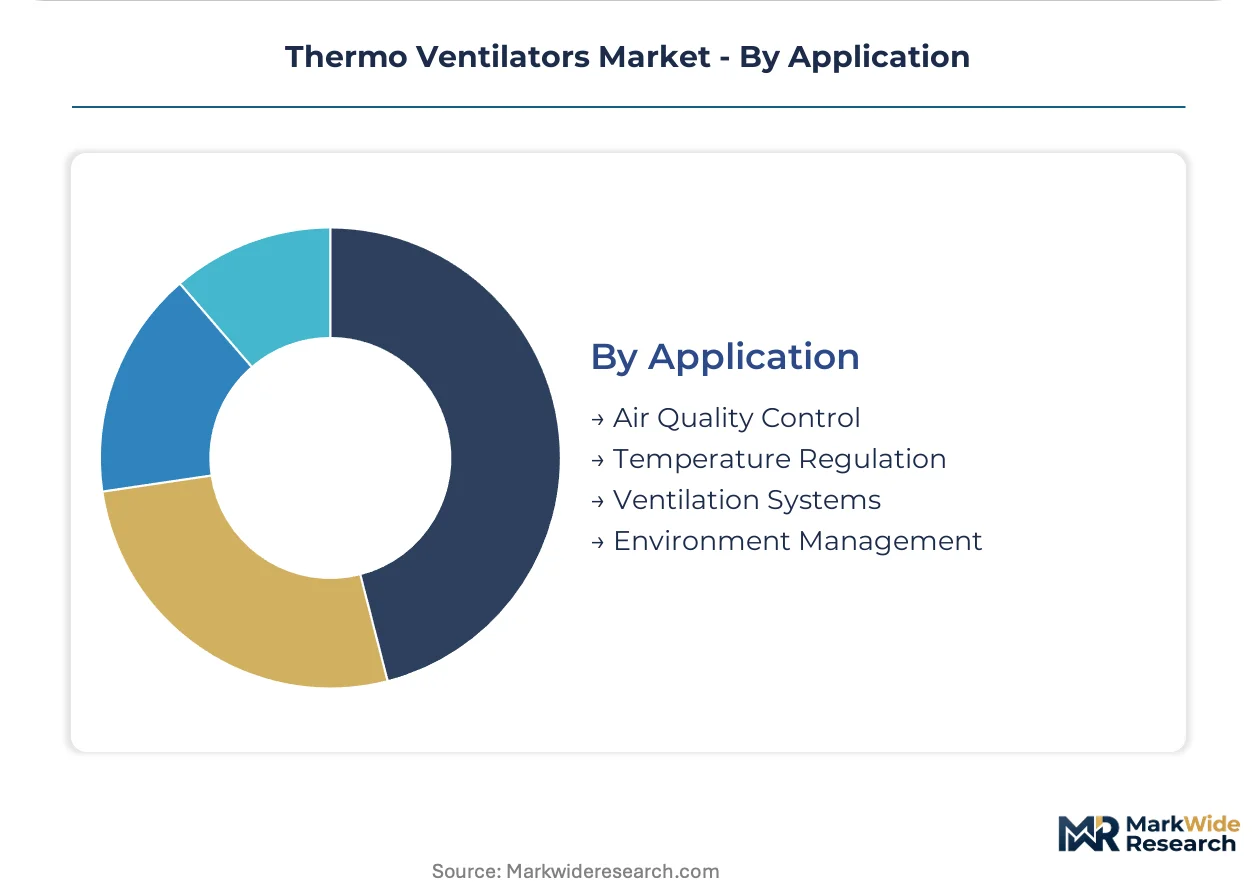
- Air Quality Control:Particulate filtration, VOC removal, and pathogen containment applications specify units with extended filter banks and UV-C sterilization stages. Demand concentrates in US healthcare isolation rooms and Netherlands operating theater networks.
- Temperature Regulation:Climate stabilization in precision manufacturing and pharmaceutical storage specifies tight temperature control bands with ±0.5°C tolerance. These units integrate with building-wide chiller and boiler systems through BACnet protocols.
- Ventilation Systems:General dilution ventilation for occupancy compliance specifies minimum outdoor air delivery rates without advanced treatment. This application faces commoditization as code-minimum requirements standardize specifications.
- Environment Management:Humidity control, pressure differential maintenance, and contamination containment for cleanrooms and laboratories. Desiccant-enhanced enthalpy wheels from Belgian and Dutch suppliers are unifying humidity and ventilation capital expenditures.
Air Quality Control commands specification influence. Environment Management shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping thermo ventilator supply chains as manufacturers relocate assembly capacity to jurisdictions with lower compliance costs while maintaining certification in high-barrier markets. Production migration toward Southeast Asian contract manufacturers accelerates even as end-market demand concentrates in Germany, Japan, and the United States.
United States
Healthcare infrastructure retrofits and Inflation Reduction Act efficiency credits are driving specification demand. The Department of Energy enforces minimum heat recovery efficiency thresholds that filter non-compliant imports. Hospital networks in California and Texas are consolidating procurement around integrated HVAC contractors.
Germany
EU Ecodesign regulations under the Green Deal framework mandate 73% minimum heat recovery efficiency for healthcare deployments. Siemens AG anchors specification channels through bundled building automation contracts. The Rhine-Ruhr industrial corridor hosts concentrated heat exchanger fabrication capacity serving hospital retrofit cycles.
China
Greenfield healthcare construction under national hospital expansion programs lacks installed HVAC base. GB standards and NMPA-linked facility codes constrain import eligibility for medical-grade units. Manufacturing clusters in the Yangtze River Delta supply heat recovery components to European and North American OEMs.
Japan
METI Top Runner program energy labeling compresses product lifecycles in commercial buildings. Building operators in Tokyo and Osaka face procurement pressure to exceed baseline efficiency standards. Aging technician cohorts concentrate refrigerant handling certifications in the Kanto region.
India
Ayushman Bharat hospital expansion creates specification windows for integrated thermo ventilator systems in tier-2 and tier-3 cities. Central Electricity Authority building codes are tightening efficiency requirements for commercial construction. Greenfield projects in Maharashtra and Gujarat lack legacy ductwork constraints that stall retrofits elsewhere.
Thermo Ventilators Market Vendor Landscape
Strategic partnerships dominate the current landscape as component specialists seek building automation integration. The vendor base clusters around three tiers: diversified industrial conglomerates with HVAC portfolios, dedicated climate-control specialists, and regional fabrication contractors serving price-sensitive retrofits. Technology licensing arrangements and backward integration into heat exchanger manufacturing represent the primary competitive vectors.
Among diversified building technology conglomerates, Johnson Controls International plc and Siemens AG exemplify the integrated-platform archetype. Daikin Industries, Ltd. occupies a position representing refrigerant technology leadership and Asian supply chain scale. These three anchors demonstrate how competitive positioning stratifies between automation-integrated, component-specialist, and manufacturing-scale archetypes.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Siemens AG |
| Honeywell International Inc |
| Daikin Industries, Ltd. |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| Carrier Global Corporation |
| Trane Technologies plc |
| Lennox International Inc. |
| Others |
Supply Flow & Price Mechanics
Refrigerant handling technicians concentrated in Japan's Kanto region and Germany's Rhine-Ruhr corridor create labor-cost differentials that widen pricing-tier spreads between premium smart-ventilator systems and commodity electromechanical units. These specialized workforce clusters enable premium-tier OEMs to defend margin pools through service-bundled contracts while forcing price-sensitive segments toward standardized electric-motor configurations.
Pricing Analysis
Distributor markups spanning 18-25 percentage points separate factory-gate pricing from end-user procurement in healthcare channels. Three-tier pricing structure across premium smart, standard electric, and economy mechanical levels stratifies by certification grade and sensor integration depth. Cost compression in the mechanical tier is intensifying because Chinese contract manufacturers are scaling EC-motor production. Residential retrofit buyers exhibit highest price sensitivity; hospital networks purchasing through GPO contracts show lowest.
Supply Chain Analysis
CE marking and NMPA facility-code compliance gates constrain supplier eligibility for medical-grade heat exchanger sourcing. Manufacturing concentrates in China, Germany, and Japan; aluminum and copper coil fabrication draws from Yangtze River Delta mills. Single-source vulnerability runs through Chinese low-GWP refrigerant production clusters. Distribution runs through integrated HVAC contractors capturing specification influence from independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion runway as sensor-integrated smart tiers capture specification share from mechanical baselines, compressing cost structures through EC-motor standardization and cloud-connected predictive maintenance bundling.
For Market Incumbents: Anticipate refrigerant supply concentration risk by securing dual-source low-GWP procurement from Japanese and Chinese producers. Deepen backward integration into heat exchanger fabrication to offset copper price volatility. Defend specification channels through Joint Commission compliance documentation that extends incumbent qualification timelines. For New Entrants and Emerging Players: Launch via equipment-as-a-service financing models targeting mid-sized US commercial buildings seeking IRA efficiency credit capture. India's tier-2 and tier-3 hospital construction under Ayushman Bharat presents the most penetrable geography. Target greenfield specifications where legacy ductwork constraints do not stall retrofit approvals. For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, seeking sensor-embedded ventilator specialists to fill IoT platform gaps. Over a multi-year horizon, viability hinges on software recurring revenue attach rates. Monitor F-Gas quota allocation announcements as inflection signals for refrigerant cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Manufacturing | Captive aluminum coil supply insulates Johnson Controls and Daikin from commodity volatility. |
| IoT Platform Integration | Cloud-connected predictive maintenance opens recurring revenue streams for Siemens healthcare contracts. |
| Joint Commission Certification Investment | Dual ASHRAE and infection-control compliance documentation extends incumbent bid-to-award cycles. |
| Equipment-as-a-Service Launch | Subscription financing reduces upfront capital barriers for mid-sized US facility operators. |
| India Greenfield Specification Capture | Ayushman Bharat tier-2 hospital construction lacks legacy HVAC base, creating first-mover windows. |
Methodological Framework
Direct dialogue with hospital procurement managers, HVAC contractor estimators, refrigerant supply specialists, and building automation integration engineers grounded qualitative findings. Secondary validation drew from EPA efficiency standard filings, EU Ecodesign directive texts, METI Top Runner program specifications, and hospital GPO contract databases. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations.
Top-down macroeconomic drivers and bottom-up segment-level unit economics converged across the analysis window. Modeled dimensions span product type, technology tier, end-user vertical, and application purpose. CAGRs derived from regression against historical efficiency regulation adoption curves and healthcare construction permit flows. Forecast inputs incorporated copper price futures and F-Gas quota allocation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden refrigerant supply disruption or accelerated EU Green Deal enforcement. Model assumptions reflect documented regulatory timelines and OEM capacity expansion announcements. A model refresh is warranted upon material change in IRA tax credit eligibility or NMPA facility-code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Air Duct Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Residential Air-to-Air Heat Pump Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Residential Furnaces Market