
 Commercial RAC PD Compressor Market | 2026-2036
Commercial RAC PD Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial RAC PD Compressor Market Outlook
Compressor engineer shortages in Europe and North America is redrawing where R&D investment flows. Panasonic Corporation leverages its in-house motor and inverter expertise to sustain leadership in variable-speed scroll systems. BITZER SE anchors the European market through deep specialization in semi-hermetic reciprocating platforms for commercial refrigeration.
A commercial RAC PD compressor is a positive-displacement mechanical device that compresses refrigerant vapor through volumetric reduction, typically operating at discharge pressures up to 30 bar and employing oil-lubricated or oil-free architectures to drive vapor-compression refrigeration cycles in commercial buildings and industrial facilities. Scroll compressors dominate unitary air conditioning applications due to superior efficiency at part-load conditions, while screw compressors occupy the large-tonnage industrial cooling segment where continuous operation and high refrigeration capacity justify the capital outlay. Variable speed drive technology leads technology adoption as supermarkets and cold-storage warehouses prioritize energy-index compliance and demand-responsive cooling.
The EPA Significant New Alternatives Policy program and the EU F-Gas Regulation are tightening refrigerant eligibility criteria, forcing compressor manufacturers to redesign displacement chambers and valve geometries for flammable A2L and A3 refrigerants. China's GB standards and India's BIS certification requirements add parallel compliance layers for equipment sold into Asia's fastest-growing commercial construction markets. Stakeholders must monitor refrigerant-phaseout schedules alongside regional efficiency mandates to align product roadmaps with compliance deadlines.
Market Dynamics
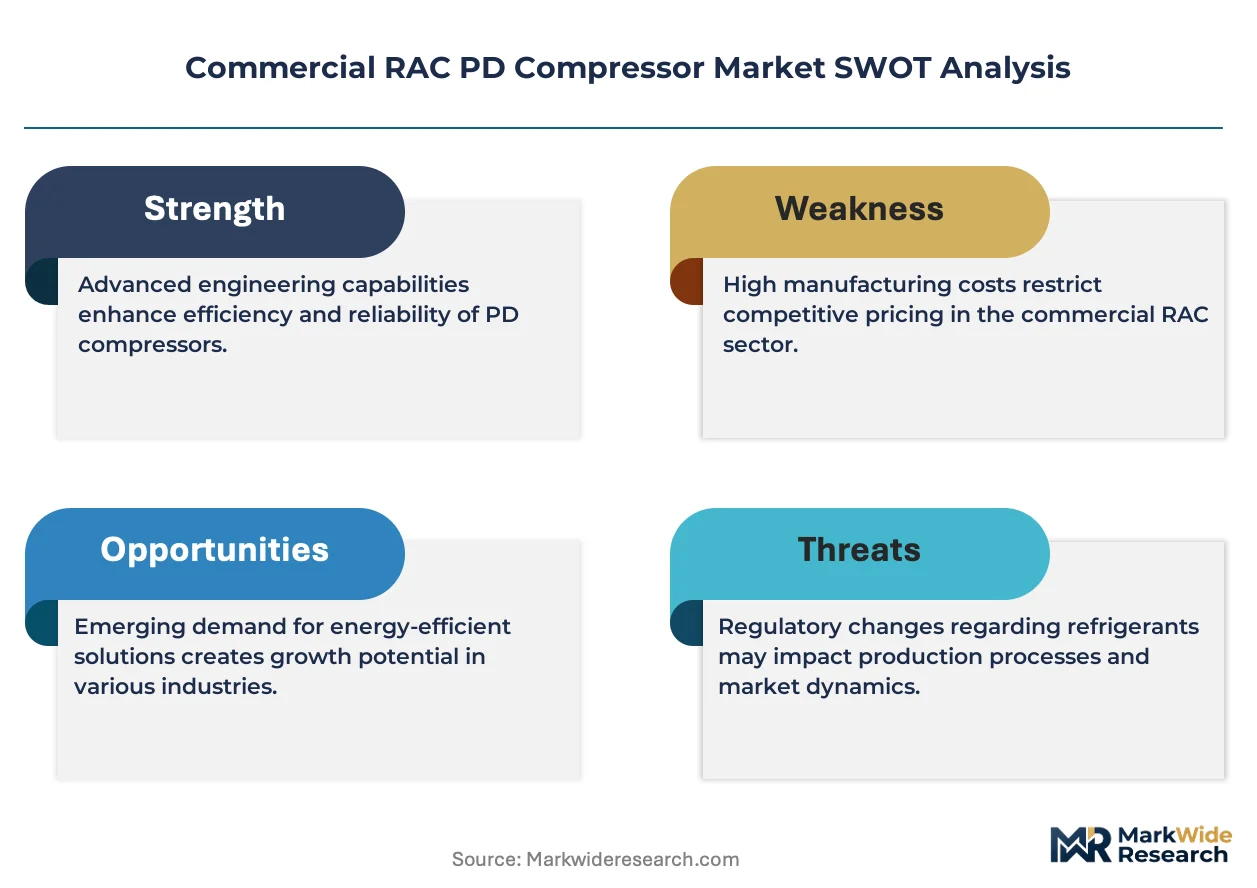
The EU F-Gas Regulation is compressing refrigerant-phaseout timelines, forcing compressor manufacturers to requalify displacement architectures for A2L and A3 refrigerants while simultaneously redesigning for higher thermal loads and flammability containment.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for high-GWP refrigerants accelerates demand for lower-GWP-compatible compressor designs across European cold-chain infrastructure.
- Hotel and restaurant expansion:Southeast Asian hospitality chains are extending refrigerated storage footprints, driving unit demand for scroll and reciprocating systems in tropical climates.
- Variable-speed drive technology:Energy-index compliance mandates in supermarket and cold-storage applications pull adoption of inverter-driven scroll compressors for part-load efficiency.
Market Restraints
- Copper and rare-earth magnet cost volatility:Input price swings for motor laminations and permanent magnets compress margin buffers for mid-tier compressor assemblers.
- Specialized compressor engineer scarcity:Europe and North America face acute talent shortages in refrigeration thermodynamics and high-pressure seal design, throttling R&D throughput.
- Semi-hermetic reciprocating platform concentration:European supply for large-tonnage commercial units clusters among a narrow supplier base, amplifying delivery risk for cold-storage projects.
Strategic Opportunities
- India's urban commercial corridors:BIS certification requirements create a compliance moat for early entrants in Mumbai, Delhi, and Bangalore retail refrigeration buildouts.
- A2L-A3 refrigerant convergence with inverter controls:Integration of flammable-refrigerant safety systems with variable-speed electronics opens new product architectures for OEM partnerships.
- Direct-to-contractor digital channels:HVAC-R wholesalers in China are piloting platform-based procurement for replacement compressors, bypassing traditional distribution tiers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA SNAP, EU F-Gas, and China's GB standard compliance extends product validation cycles by 18-24 months.
- Legacy system integration friction:Retrofit of variable-speed drives into existing fixed-speed rack systems demands custom control mapping and refrigerant circuit rebalancing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial RAC PD Compressor Market |
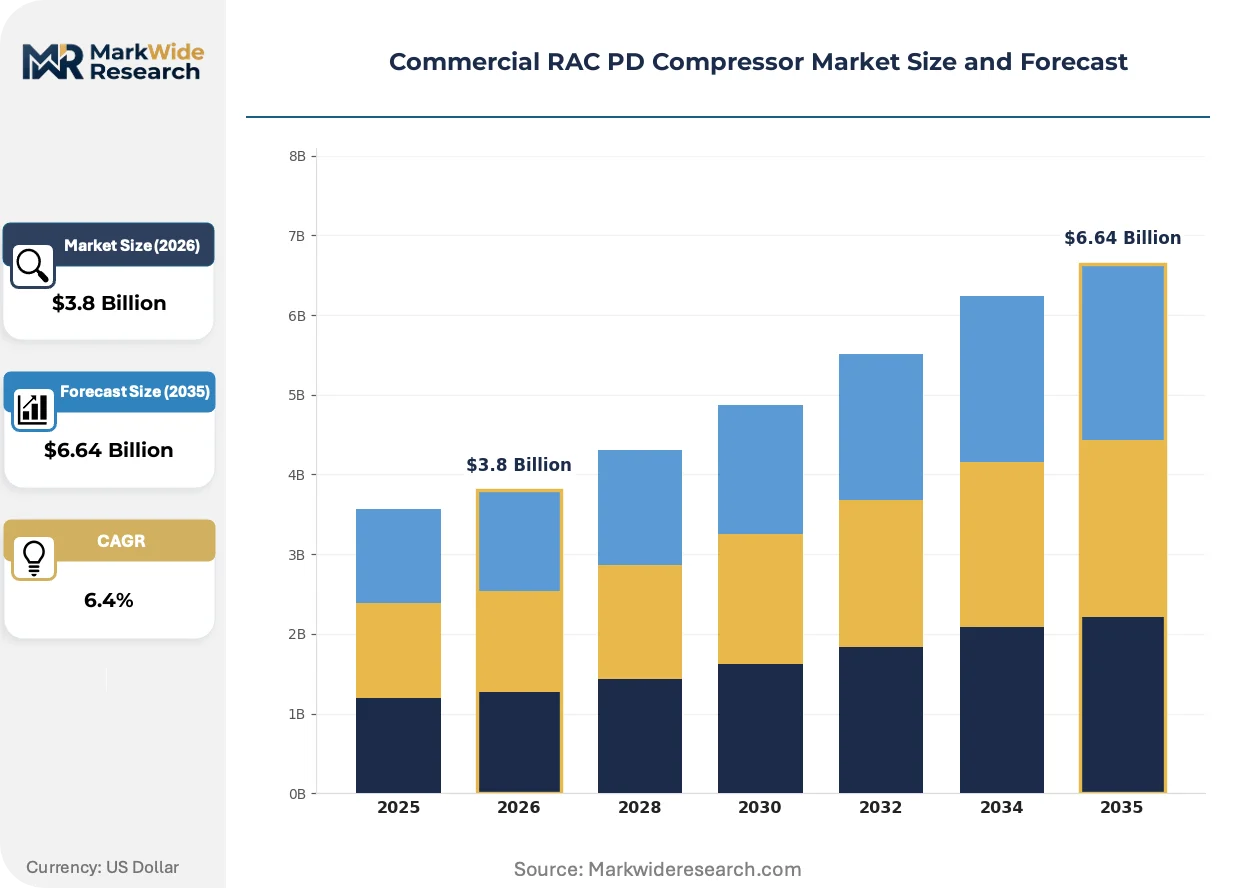
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Scroll Compressors, Reciprocating Compressors, Screw Compressors, Centrifugal Compressors Application: Commercial Refrigeration, Air Conditioning Systems, Industrial Cooling, Heat Pumps End User: Supermarkets, Hotels, Restaurants, Warehouses Technology: Variable Speed Drive, Fixed Speed Drive, Smart Controls, Traditional Controls |
| Companies Covered | Panasonic Corporation, Midea Group, Emerson Electric Co., BITZER SE, Huayi Compressor, Danfoss A/S, Mitsubishi Electric Corporation, Nidec Corporation, Daikin Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial RAC PD Compressor Market Strategic Shifts
Refrigerant chemistry constraints are fragmenting compressor design roadmaps, splitting engineering resources between near-term HFO adaptations and longer-term natural refrigerant architectures.
Scroll compressor platforms optimized for A2L refrigerants are fragmenting the mid-tonnage commercial AC segment. Japanese and Korean OEMs are accelerating qualification timelines for R-454B and R-32 variants. This technology is fragmenting supplier relationships as end-users demand refrigerant-flexible platforms that span multiple regulatory jurisdictions.
The EPA SNAP program is tightening refrigerant eligibility criteria for commercial refrigeration equipment. Compressor manufacturers must redesign discharge valve geometries and motor cooling circuits to accommodate lower-flammability-limit refrigerants. Supermarket chains in California and New York are prioritizing A2L-ready rack systems to preempt state-level phaseout acceleration.
Energy-as-a-service contracting is displacing traditional equipment ownership in European cold-storage. Facility operators in Germany and the Netherlands are leasing compressor capacity with guaranteed kW/ton performance. This model concentrates buyer power among energy service companies while compressing OEM margins through long-term performance guarantees.
Commercial RAC PD Compressor Market Segmentation
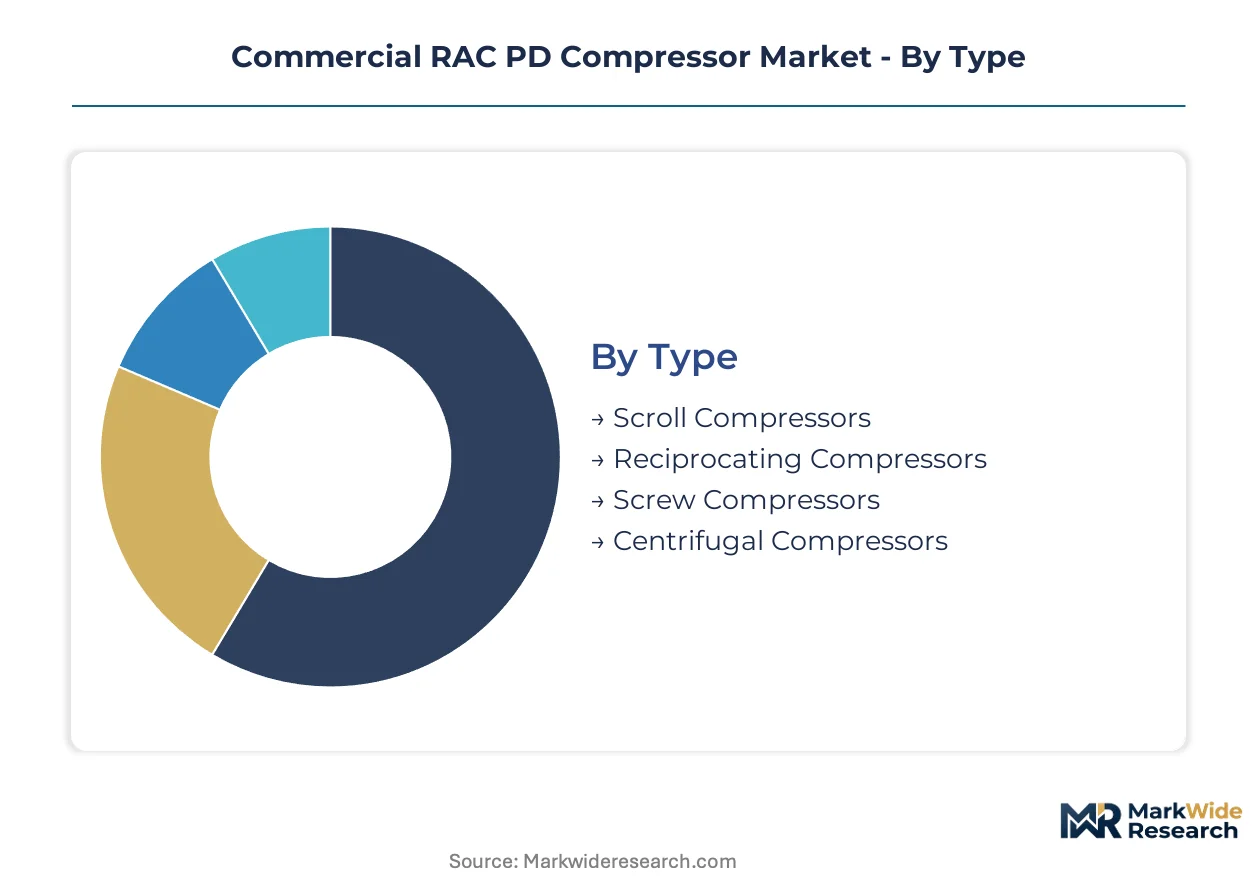
Compressor architecture and control technology fragment procurement decisions across distinct operational profiles. End-use requirements for part-load efficiency, refrigerant compatibility, and maintenance accessibility create non-overlapping segment boundaries that reshape supplier relationships.
Type:
Scroll compressors dominate domestic manufacturing clusters serving unitary air conditioning, while screw and centrifugal platforms concentrate in export-led industrial cooling supply chains.
- Scroll Compressors:Orbiting and fixed scroll elements compress refrigerant through continuous volumetric reduction. Demand clusters in China's Pearl River Delta manufacturing corridors for unitary commercial AC systems, driven by inverter integration mandates under GB energy efficiency standards.
- Reciprocating Compressors:Piston-driven displacement chambers handle high pressure differentials with robust sealing. European cold-storage projects in Germany and the Netherlands specify semi-hermetic variants, constrained by specialized compressor engineer scarcity throttling supplier capacity expansion.
- Screw Compressors:Twin helical rotors deliver continuous compression for large-tonnage applications. Indian pharmaceutical cold-chain buildouts in Hyderabad and Pune drive import demand for oil-injected industrial platforms.
- Centrifugal Compressors:Dynamic compression via impeller acceleration serves district cooling and mega-scale HVAC. Gulf Cooperation Council hospitality developments in Dubai and Riyadh anchor procurement volumes for magnetic bearing-equipped systems.
Scroll compressors hold the largest share; momentum sits with screw compressors in industrial cooling expansion.
Application:
Cost tier stratification separates premium inverter-driven systems from standard fixed-speed equipment across installation scales.
- Commercial Refrigeration:Rack systems and distributed compressor arrays serve display cases and walk-in coolers. EPA SNAP refrigerant phaseout timelines in California and New York accelerate A2L-compatible platform qualification.
- Air Conditioning Systems:Unitary and split systems dominate Southeast Asian hotel construction in Bangkok and Jakarta, pulled by tropical climate load profiles and energy-index compliance mandates.
- Industrial Cooling:Process refrigeration and cold-storage warehouses demand continuous-duty architectures. German energy-as-a-service contracting models concentrate buyer power among facility operators leasing compressor capacity.
- Heat Pumps:Reversible vapor-compression cycles deliver space heating and domestic hot water. Nordic district heating retrofits in Sweden and Finland specify CO2 transcritical compressors for sub-zero ambient operation.
Commercial refrigeration captures the dominant revenue position; heat pumps are expanding most quickly amid building decarbonization mandates.
End User:
Volume concentration varies sharply between fragmented restaurant replacement markets and concentrated supermarket chain procurement.
- Supermarkets:Centralized rack systems with multiple compressor stages serve display case circuits. EU F-Gas Regulation compliance deadlines force simultaneous refrigerant and compressor fleet transitions across French and Italian retail chains.
- Hotels:Distributed unitary systems serve guest room and common area cooling. Southeast Asian hospitality expansion in Vietnam and the Philippines drives scroll compressor demand for tropical climate operation.
- Restaurants:Walk-in coolers and reach-in display cases require compact hermetic units. India's urban commercial corridors in Mumbai and Delhi generate replacement demand as BIS certification requirements filter non-compliant imports.
- Warehouses:Large-tonnage systems maintain temperature-controlled storage for pharmaceuticals and perishables. Chinese e-commerce logistics hubs in Shanghai and Shenzhen specify variable-speed screw compressors for demand-responsive cooling.
Supermarkets anchor procurement volumes; warehouses gain share fastest from cold-chain infrastructure buildouts.
Technology:
Supply concentration in power electronics and motor control IP creates margin differentiation between inverter specialists and commodity fixed-speed assemblers.
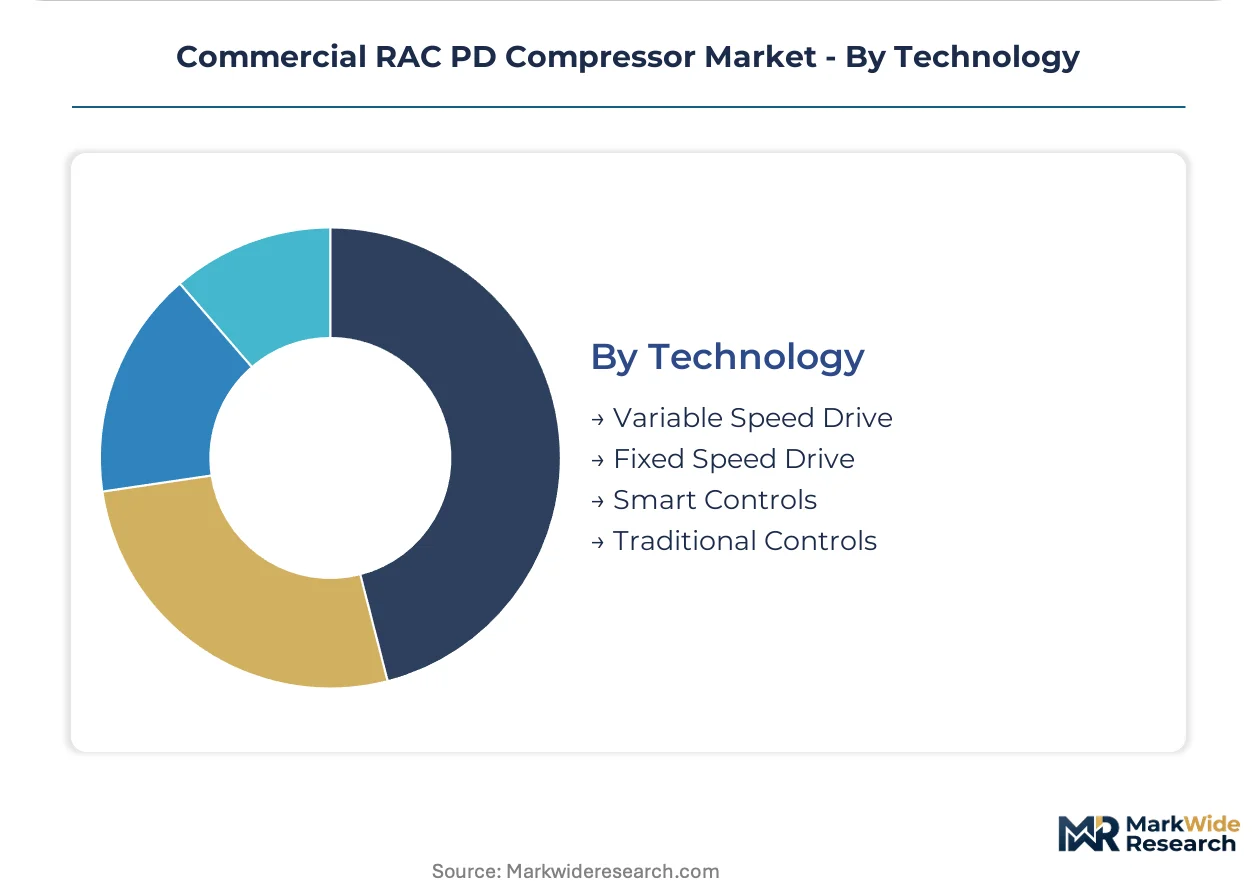
- Variable Speed Drive:Inverter electronics modulate compressor speed for part-load efficiency optimization. Japanese OEMs leverage in-house motor and inverter expertise to dominate supermarket and data center specifications.
- Fixed Speed Drive:Constant-speed operation with cyclic on-off control serves cost-sensitive replacement markets. India's tier-2 city restaurant refrigeration relies on standardized hermetic reciprocating units.
- Smart Controls:IoT-enabled diagnostics and predictive maintenance algorithms reduce unplanned downtime. German cold-storage operators integrate compressor telemetry with energy management platforms.
- Traditional Controls:Electromechanical pressure switches and thermostats govern basic refrigeration cycles. Legacy system integration friction limits retrofit potential in Southeast Asian installed bases.
Variable speed drive technology commands the premium tier; smart controls show the steepest expansion trajectory from outcome-based service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys scroll compressors for mass-market unitary air conditioning, while Germany and the Netherlands favor semi-hermetic reciprocating systems for industrial cold-storage under energy-as-a-service contracts. This consumption-mix differential reflects climate conditions, regulatory stringency, and ownership-model divergence across geographies.
China
GB energy efficiency standards mandate inverter integration for commercial AC systems, pulling scroll compressor demand through Pearl River Delta manufacturing corridors. MIIT dual carbon goals accelerate refrigerant-phaseout timelines for industrial cooling equipment. Shanghai and Shenzhen logistics hubs specify variable-speed screw compressors for e-commerce cold-chain infrastructure.
Germany
EU F-Gas Regulation compliance deadlines force simultaneous refrigerant and compressor fleet transitions across retail cold-storage networks. Energy-as-a-service contracting concentrates buyer power among facility operators leasing compressor capacity with guaranteed performance. Bavarian and North Rhine-Westphalian industrial zones anchor semi-hermetic reciprocating system procurement for pharmaceutical warehouses.
United States
EPA SNAP program phaseout timelines in California and New York accelerate A2L-compatible platform qualification for supermarket rack systems. IRA clean energy incentives support heat pump compressor deployment in commercial building retrofits. Texas and Florida hospitality construction drives scroll unit demand for tropical climate operation.
India
BIS certification requirements create compliance moats for early entrants in Mumbai, Delhi, and Bangalore retail refrigeration buildouts. Urban commercial corridor expansion generates replacement demand as standards filter non-compliant imports. Telangana and Maharashtra pharmaceutical clusters drive import demand for large-tonnage industrial cooling platforms.
Japan
METI efficiency mandates push variable-speed drive adoption in data center and supermarket specifications. Domestic OEMs leverage in-house motor and inverter expertise to sustain leadership positions. Kanto and Kansai manufacturing belts concentrate scroll compressor production for export-led unitary AC supply chains.
Commercial RAC PD Compressor Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Japanese and Korean conglomerates controlling inverter electronics IP while European specialists anchor semi-hermetic reciprocating platforms. The market structure favors players with captive motor manufacturing and refrigerant-flexible displacement architectures. Two strategic archetypes dominate: vertically integrated electromechanical conglomerates and focused refrigeration component specialists. Competitive moves concentrate on refrigerant-platform diversification and geographic expansion into BIS-regulated Indian corridors.
Within the integrated electromechanical tier, Panasonic Corporation and Mitsubishi Electric Corporation exemplify the convergence of in-house motor, inverter, and compressor design capabilities. BITZER SE occupies a distinct position among European specialists, anchoring semi-hermetic reciprocating supply for industrial cold-storage applications. These three entities represent divergent strategic postures: Asian conglomerates leverage electronics integration for variable-speed scroll dominance, while the German specialist deepens platform-specific expertise for large-tonnage commercial refrigeration.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Midea Group |
| Emerson Electric Co. |
| BITZER SE |
| Huayi Compressor |
| Danfoss A/S |
| Mitsubishi Electric Corporation |
| Nidec Corporation |
| Daikin Industries, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between European cold-storage operators and semi-hermetic reciprocating suppliers lock in both copper and rare-earth magnet supply access and price visibility across 18-24 month qualification cycles. These arrangements insulate BITZER SE and similar specialists from spot market volatility while compressing margin buffers for mid-tier assemblers lacking comparable procurement scale.
Pricing Analysis
Contract-based long-term offtake dominates procurement for industrial cooling platforms, while spot purchasing governs replacement scroll units in India's fragmented restaurant sector. Price differentiation rests on certification grade—EU F-Gas and EPA SNAP compliance tiers command 15-20% premia over baseline equipment—and volume scale, with supermarket chains extracting favorable terms through fleet-wide transitions. Cost compression in mid-tier fixed-speed reciprocating units is intensifying because Chinese manufacturers are flooding Southeast Asian hospitality replacement markets. Tier-2 city restaurant operators in India exhibit the highest price sensitivity, whereas German energy-as-a-service companies prioritize performance guarantees over unit cost.
Supply Chain Analysis
Inventory cycles for rare-earth permanent magnets and copper motor laminations now stretch 16-22 weeks, forcing Japanese and Korean OEMs to pre-position buffer stock ahead of inverter production ramps. Manufacturing gravity centers on China for scroll compressor final assembly, Germany for semi-hermetic reciprocating platforms, and Japan for variable-speed drive electronics. The supply chain draws from Chilean copper concentrates, Chinese rare-earth processing facilities, and German precision-machined valve components. Single-source vulnerability in NdFeB magnet supply from Chinese processors exposes European and North American motor manufacturers to export restriction risk. Distribution runs through HVAC-R wholesalers in China, direct-to-contractor digital platforms in India, and energy service companies in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant chemistry constraints are fragmenting engineering roadmaps, creating specialist niches for A2L-compatible platform developers and natural refrigerant architects as incumbent OEMs split resources between near-term HFO adaptations and longer-term CO2 transcritical systems.
For Market Incumbents: Consolidate inverter electronics IP through backward integration into motor lamination and permanent magnet supply, countering the threat of rare-earth price volatility eroding variable-speed scroll margins. Deepen certification investment in India's BIS-mandated corridors to preempt Chinese competitors from establishing compliant distribution. Prioritize captive R&D capacity in high-pressure seal design to offset specialized compressor engineer scarcity throttling European expansion.
For New Entrants and Emerging Players: Differentiate on A2L-A3 refrigerant safety system integration with variable-speed controls, targeting the penetrable supermarket rack retrofit segment in California and New York where EPA SNAP timelines have outpaced incumbent qualification cycles. India's BIS-filtered urban commercial corridors offer white-space access for early entrants with certified hermetic reciprocating units. Pursue direct-to-contractor digital channels as the primary go-to-market angle, bypassing entrenched HVAC-R wholesale tiers in Mumbai and Delhi.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated electromechanical conglomerates with captive motor manufacturing and refrigerant-flexible displacement architectures, as these capabilities compound across the medium-term transition to lower-GWP refrigerants. Acquisition targets should display in-house inverter IP and established A2L qualification pipelines. Monitor EU F-Gas Regulation phaseout acceleration announcements as the critical inflection signal for compressor fleet replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Diversification | Enables simultaneous A2L and natural refrigerant qualification, satisfying EU F-Gas and EPA SNAP compliance deadlines. |
| Backward Integration into Magnet Supply | Secures NdFeB permanent magnet access, insulating variable-speed motor production from Chinese export volatility. |
| Digital Channel Development | Bypasses traditional HVAC-R wholesale tiers, capturing margin in China's platform-based procurement pilots. |
| Energy-as-a-Service Partnership | Locks in long-term compressor capacity contracts with German and Dutch facility operators seeking guaranteed kW/ton performance. |
| BIS Certification Pre-positioning | Creates compliance moats for early entrants in Mumbai, Delhi, and Bangalore retail refrigeration buildouts. |
Study Parameters
A spread of perspectives from compressor engineering directors, supermarket chain procurement heads, cold-storage facility operators, and HVAC-R wholesale distributors converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through SEC 10-K filings, EU F-Gas regulatory databases, China's GB standard documentation, and customs trade data on compressor motor component flows. Bottom-up unit demand modeling and top-down market sizing triangulated on volume estimates across the analysis window.
Segmentation dimensions modeled include compressor architecture type, application category, end-user vertical, control technology tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline demand data, cross-checked against refrigerant-phaseout schedule impacts and energy-index compliance mandate diffusion rates. Industry-specific forecast inputs incorporated MIIT dual carbon goal timelines for Chinese industrial cooling and German energy-as-a-service contract penetration assumptions.
The analysis sits within stated boundaries; outcomes outside simultaneous EPA SNAP, EU F-Gas, and BIS certification compliance would require recalibration. Forecasts reflect documented assumptions regarding refrigerant transition velocity, rare-earth magnet supply continuity, and specialized engineering talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
United States Residential Heating Equipment Market