
 North America Vertical Farming Market | 2026-2036
North America Vertical Farming Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vertical Farming Market Intelligence
The cultivation of high-value, specialty crops like berries and edible flowers is rotating the market away from a sole focus on leafy greens. Bowery Farming leverages its proprietary operating system to optimize for diverse crop varieties. Plenty Unlimited Inc. specializes in scalable farm architecture to serve large retail partners. Meanwhile, BrightFarms operates a network of regional greenhouses that supply local supermarkets.
Vertical farming is a method of Controlled Environment Agriculture (CEA) where crops are cultivated in vertically stacked layers inside buildings. This process utilizes soilless techniques and precisely controlled artificial lighting, often with specific LED wavelengths, to optimize plant growth and yield year-round. Hydroponics remains the dominant production method due to its maturity and efficiency, though aeroponics gains traction for high-value crops. While leafy greens constitute the largest crop type by volume, the berries segment represents the fastest-growing category due to higher margins.
Food safety regulations from the U.S. Food and Drug Administration (FDA) and Health Canada set stringent standards for produce handling and traceability. The USDA's organic certification guidelines also influence production protocols for farms seeking to capture premium consumer segments. Future profitability for operators will depend on achieving energy efficiency at scale and securing long-term offtake agreements with major food service providers and retailers.
Market Dynamics
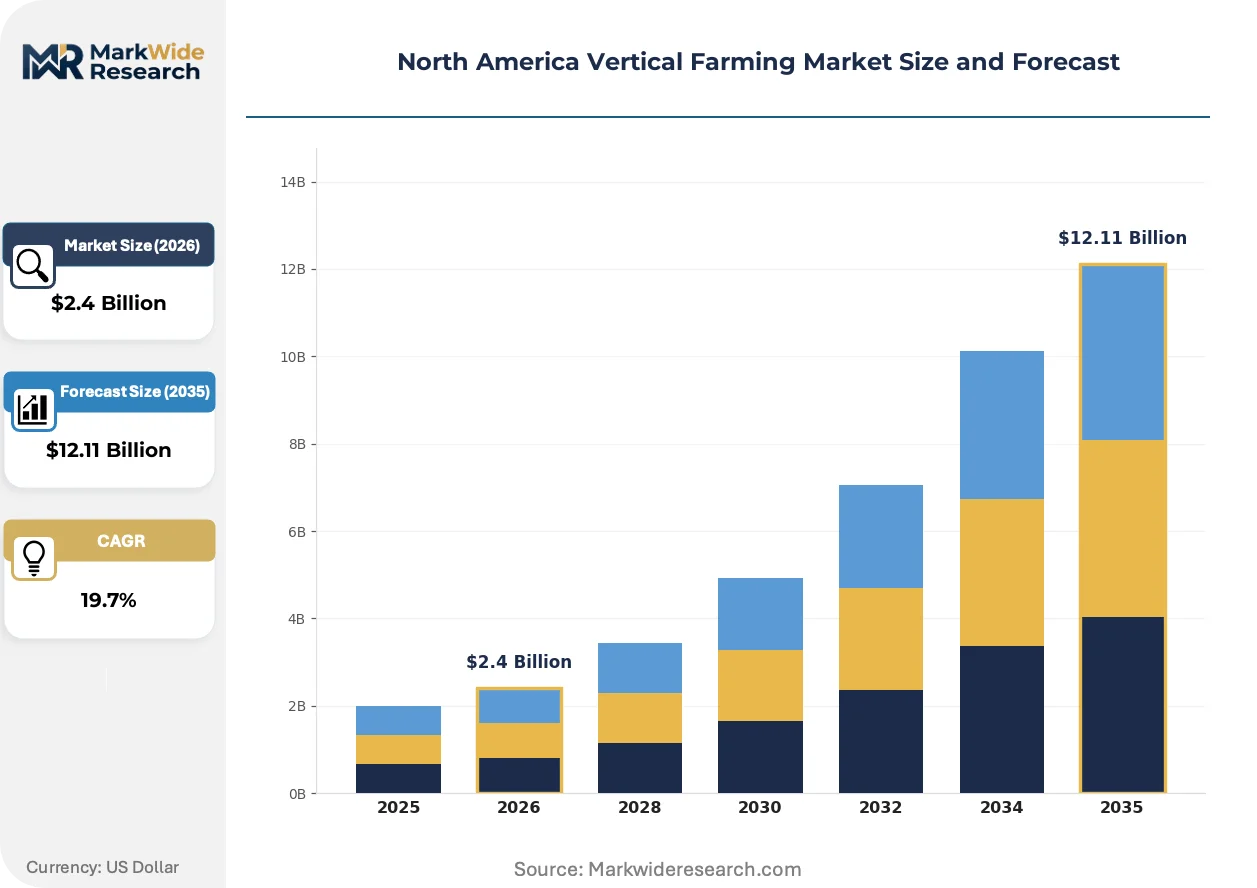
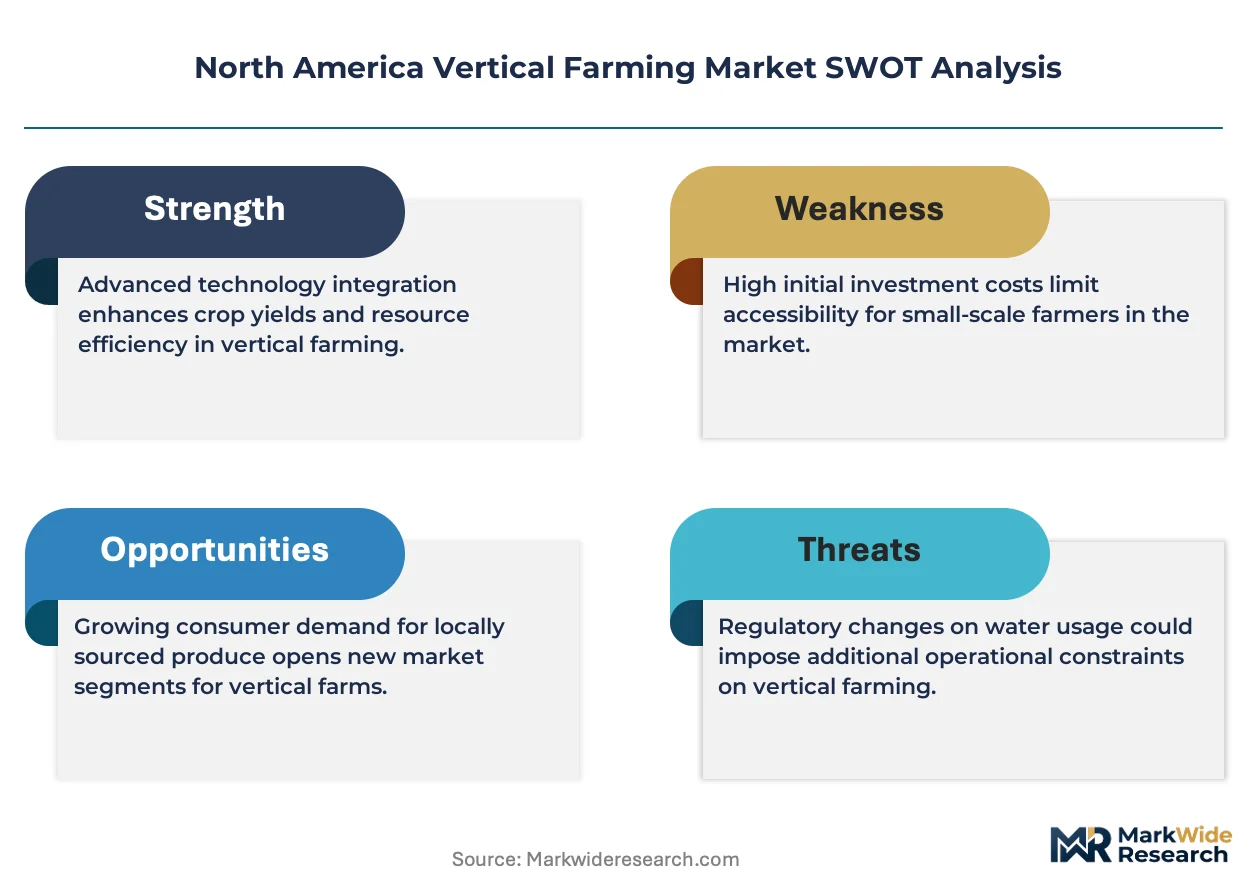
The central dynamic shaping the North America vertical farming market is the economic tension between high energy and capital costs and the intense demand from retailers for year-round, locally-sourced, and traceable produce. This conflict is forcing operators to pursue technological innovation and operational scale to achieve profitability and meet supply agreements.
Growth Catalysts
- Retailer Demand:Major supermarket chains in the United States and Canada require a consistent, year-round supply of fresh produce, driving investment in local CEA facilities.
- Technology Advancement:The development of specialized, energy-efficient LED lighting and automated climate control systems is lowering operational expenditures and improving crop yields.
- Consumer Preferences:Shopper demand for pesticide-free products with transparent origins and a lower transportation footprint supports the premium positioning of vertically farmed goods.
Market Restraints
- Energy Costs:High and often volatile electricity prices represent a significant portion of operational costs, impacting profitability, particularly for facilities not using renewable energy sources.
- High Capital Intensity:The substantial upfront investment required to build and equip automated, multi-level indoor farms presents a significant barrier to entry for smaller operators.
- Technical Limitations:While improving, the commercial viability for many crop types beyond leafy greens, herbs, and microgreens remains constrained by specific growth requirements and economics.
Strategic Opportunities
- Crop Diversification:Cultivating high-value, niche products such as berries, edible flowers, and pharmaceutical-grade botanicals opens new revenue streams with higher profit margins.
- Geographic Expansion:Establishing facilities in secondary metropolitan areas and regions classified as food deserts across the United States can capture underserved markets and address food security.
- Technology Integration:Combining AI-powered analytics with robotic systems for seeding, monitoring, and harvesting can optimize resource use and significantly reduce labor-dependent operational costs.
Industry Challenges
- Skilled Labor Scarcity:A shortage of trained personnel, including plant scientists, horticulturalists, and control systems engineers, constrains the ability to manage and scale sophisticated farming operations. *Regulatory Compliance: Navigating the complex food safety and handling standards set by the FDA and Health Canada, alongside requirements for USDA organic certification, demands significant investment.
- Energy Sourcing:Securing long-term, fixed-price power purchase agreements or developing on-site renewable generation is a critical but difficult step for ensuring financial stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vertical Farming Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $12.11 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Hydroponics, Aeroponics, Aquaponics, Soil-Based Crop Type: Leafy Greens, Herbs, Microgreens, Berries, Edible Flowers Technology: LED Lighting, Climate Control, IoT Sensors, Automated Irrigation, Artificial Intelligence End User: Supermarket Chains, Food Service Providers, Urban Farms, Research Institutions |
| Companies Covered | AeroFarms, Plenty Unlimited Inc., Bowery Farming, BrightFarms, Gotham Greens, 80 Acres Farms, GoodLeaf Farms, Freight Farms, Infarm, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vertical Farming Market Strategic Shifts & Innovations
Automation and data analytics are transforming vertical farms from simple cultivation centers into highly controlled, data-rich production platforms. This evolution enables precise optimization for specific crop traits, yield maximization, and deeper integration with sophisticated food supply chains across North America.
Advanced Sensor Integration
Advanced environmental sensors provide real-time data on temperature, humidity, and CO2 levels within cultivation zones. Commercial-scale operators in the United States and Canada are rapidly deploying these systems to monitor conditions. This trend is miniaturizing data collection from manual spot-checks into a constant stream of plant-level analytics, enabling precise resource and nutrient management.
Enhanced Food Safety and Traceability
The U.S. Food and Drug Administration's (FDA) Food Safety Modernization Act imposes strict preventative controls and traceability requirements on produce. This regulation creates a distinct advantage for vertical farms, whose closed-loop systems offer inherent control over contaminants. The leafy greens segment, highly susceptible to foodborne illness, benefits most from this demonstrable compliance edge.
Evolving Retailer Partnerships
A shift toward long-term supply contracts is altering procurement from major retailers. This model displaces transactional purchasing from wholesale markets, favoring operators who can guarantee consistent volume and quality specified by the grocery partner. The trend is most prominent among large supermarket chains in dense urban corridors of the United States seeking to secure local supply.
North America Vertical Farming Market Segmentation
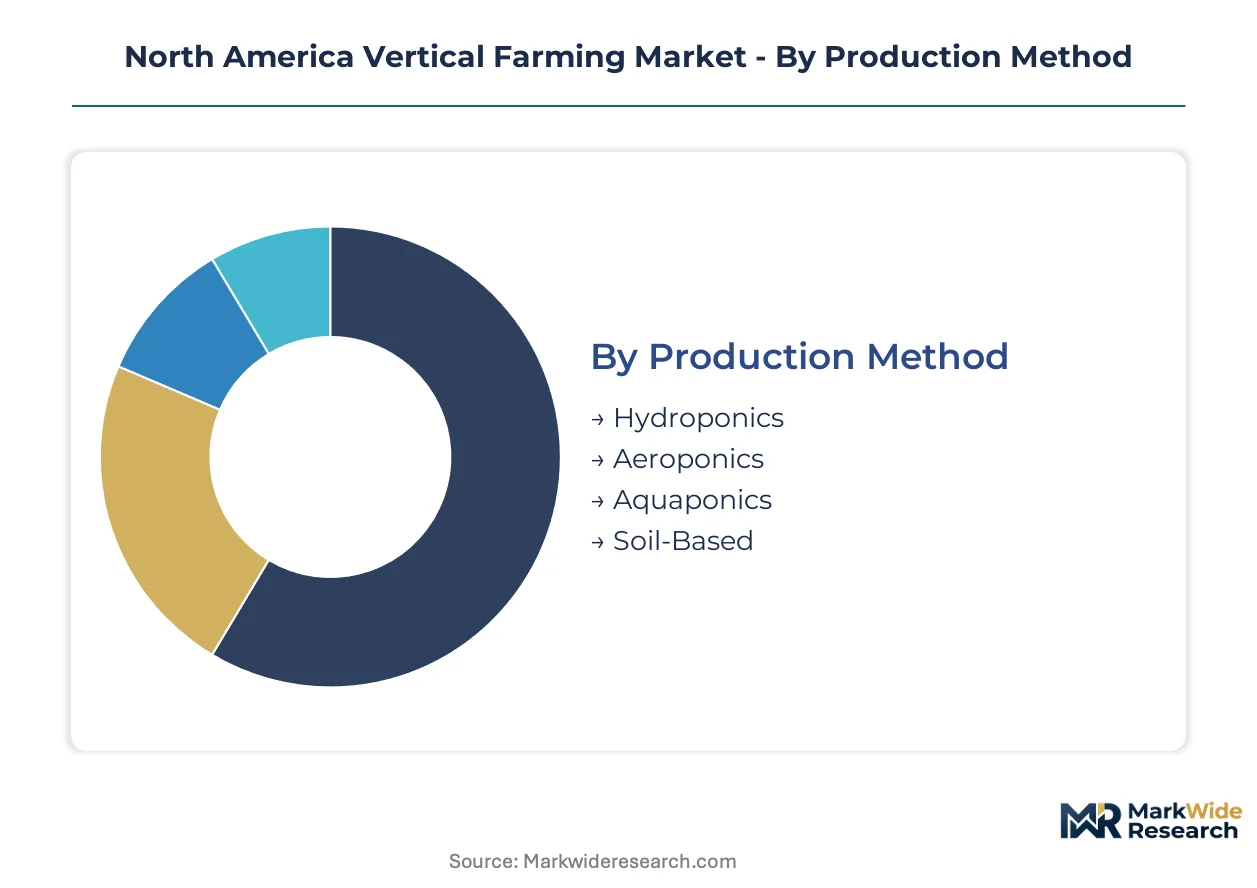
Segmentation analysis reveals the diverse operational and market structures within the North America vertical farming market. Understanding these distinct categories allows stakeholders to identify specific growth vectors and competitive pressures. This granular view highlights where technological innovation and demand concentration are reshaping investment priorities for vertical farm operators.
Production Method:
The production method segment faces significant substitution pressure, particularly from traditional agriculture for lower-value crops, forcing indoor farms to differentiate on consistency and quality.
- Hydroponics:This soilless cultivation method uses nutrient-rich water solutions to grow plants, representing the dominant production technique. Demand concentrates in large-scale commercial facilities serving supermarket chains due to its established efficiency and maturity.
- Aeroponics:Plants are suspended in air and misted with nutrient solutions, promoting rapid growth and minimal water use. This method gains traction for high-value specialty crops like berries, where precise nutrient delivery optimizes yield and quality.
- Aquaponics:This integrated system combines aquaculture (raising aquatic animals) with hydroponics, using fish waste to fertilize plants.
- Soil-Based:While less common in controlled environment agriculture, some indoor farms utilize enhanced soil mediums for specific niche crops requiring traditional root support.
Hydroponics anchors the volume base while Aeroponics gains share at the steepest rate.
Crop Type:
Crop type segmentation highlights varying margin profiles and cultivation complexities, influencing investment decisions for vertical farm operators.
- Leafy Greens:This category includes crops like lettuce, spinach, and kale, forming the largest volume segment due to consistent consumer demand. Supermarket chains in urban centers drive demand for these crops, valuing their year-round availability and reduced transportation footprint.
- Berries:High-value fruits such as strawberries and blueberries represent a rapidly expanding segment with premium pricing potential. Cultivation focuses on optimizing flavor and shelf-life, attracting investment from farms targeting specialty retail markets.
- Herbs:Basil, mint, and cilantro are cultivated for consistent supply to food service providers and specialty grocery stores.
- Microgreens:Young, edible seedlings like arugula and radish are prized for their intense flavor and nutritional density, often supplied to high-end restaurants.
- Edible Flowers:Niche products like pansies and nasturtiums cater to gourmet chefs and confectioners, offering high margins for specialized growers.
Leafy Greens maintain the largest market share, while the Berries segment expands most quickly.
Technology:
The technology segment showcases the critical infrastructure investments required for operational efficiency and scalability in vertical farming.
- LED Lighting:Specialized light-emitting diode systems provide precise spectral control and energy efficiency for plant growth. These systems are crucial for reducing operational expenditures, enabling cost-effective cultivation across North American facilities.
- IoT Sensors:Networks of internet-connected sensors monitor environmental parameters like temperature, humidity, and CO2 levels. Real-time data from these sensors allows for precise resource management and optimized plant growth cycles.
- Climate Control:Automated systems regulate temperature, humidity, and air circulation within controlled environments, ensuring optimal growing conditions.
- Automated Irrigation:Systems deliver precise amounts of water and nutrients directly to plants, minimizing waste and labor requirements.
- Artificial Intelligence:AI algorithms analyze sensor data to optimize growing recipes, predict yields, and manage farm operations autonomously.
LED Lighting forms the foundational technology, with Artificial Intelligence demonstrating the steepest expansion trajectory.
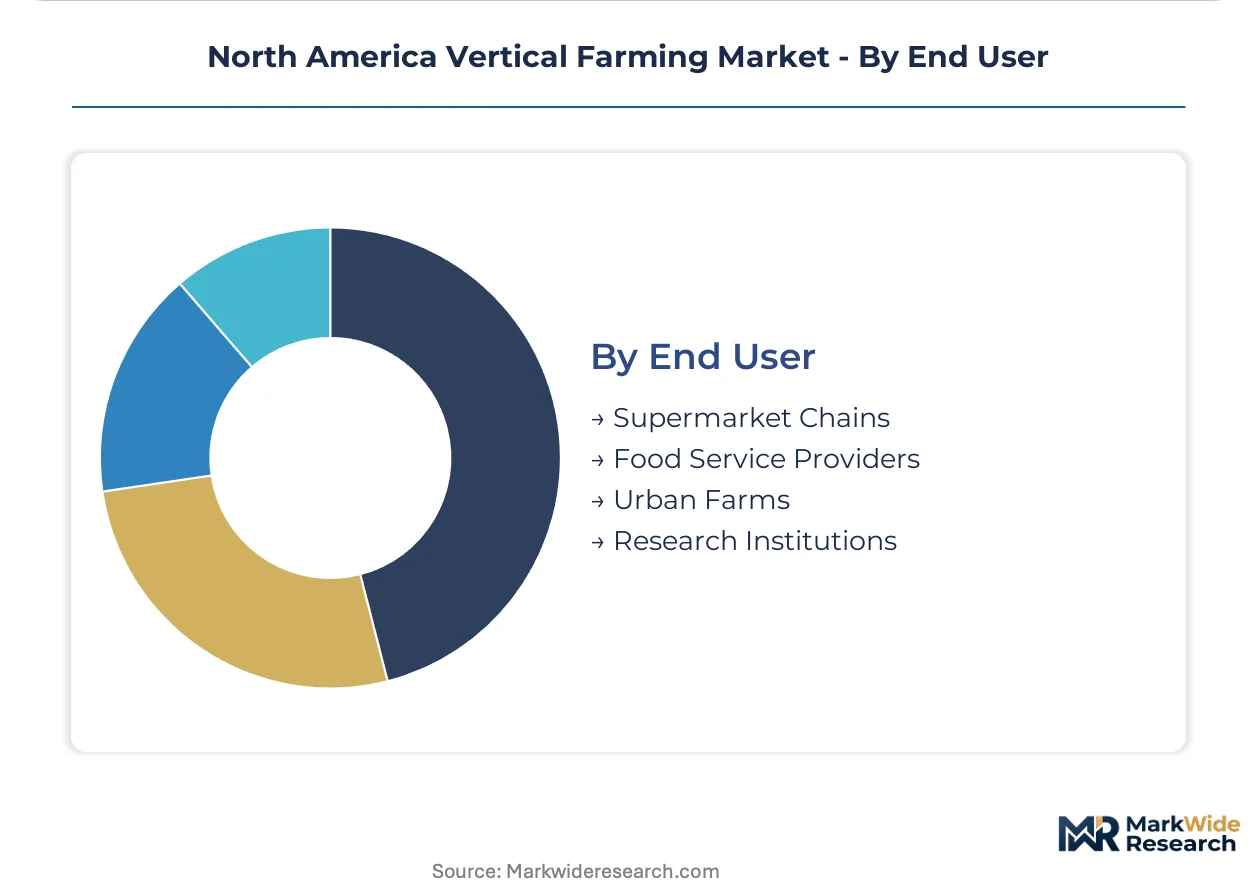
End User:
End user segmentation reflects the diverse procurement needs and volume requirements of different customer types for vertically farmed produce.
- Supermarket Chains:Major grocery retailers represent a primary demand source, seeking consistent, locally-sourced, and traceable produce year-round. These chains drive large-volume, long-term supply contracts for fresh greens and specialty crops.
- Food Service Providers:Restaurants, catering companies, and institutional kitchens require reliable supplies of fresh, high-quality ingredients. Securing long-term offtake agreements with these providers is crucial for future profitability of vertical farms.
- Urban Farms:Smaller, community-focused operations often serve local markets, farmers' markets, and direct-to-consumer sales channels.
- Research Institutions:Universities and corporate R&D centers utilize vertical farms for plant science studies, crop optimization, and new technology development.
Supermarket Chains command the largest purchasing volume, while Urban Farms are climbing the fastest in terms of market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America's vertical farming market seeks to reduce reliance on imported produce, enhancing regional food security and supply chain resilience. Localized cultivation minimizes transportation costs and spoilage, directly impacting fresh produce availability across the continent. This strategic shift addresses consumer demand for consistent, high-quality, year-round produce, driving significant investment.
United States
Demand from supermarket chains for consistent, locally grown produce drives significant investment across the United States. The U.S. Food and Drug Administration's (FDA) Food Safety Modernization Act mandates stringent traceability and safety protocols for all food producers. Urban centers like New York City, Chicago, and Los Angeles are becoming key areas for large-scale vertical farm development. These facilities aim to reduce reliance on produce imported from warmer climates.
Canada
Consumer demand for year-round fresh produce in diverse climates stimulates Canadian market expansion. Health Canada establishes strict guidelines for food safety and quality in controlled environment agriculture operations. Ontario and British Columbia are seeing increased development of vertical farms, particularly around major metropolitan areas like Toronto and Vancouver. This localized production mitigates supply chain vulnerabilities and enhances food security.
Mexico
Growing urban populations and export opportunities to the United States create demand for high-quality produce in Mexico. Mexico's National Service for Agri-food Health, Safety and Quality (SENASICA) regulates agricultural practices and certifications. Mexico City and Guadalajara are emerging as significant hubs for indoor farming, serving both domestic retail and international markets. Operators focus on optimizing yields for year-round supply to meet these demands.
North America Vertical Farming Market Key Industry Players
Concentration sits with technology-driven growers who prioritize operational efficiency and yield maximization. The market exhibits a blend of established large-scale operators and numerous specialized startups targeting niche segments. Consolidation efforts are visible among entities aiming for significant retail partnerships to secure long-term contracts. Dominant competitive moves involve capacity expansion to meet retailer demand and strategic partnerships for technology co-development.
Scale-driven operators like Plenty Unlimited Inc. exemplify the push for large-format facilities to serve major retail partners across North America. Technology-focused entities such as Bowery Farming represent the integration of proprietary operating systems for crop optimization and diverse variety cultivation. Regional supply chain integrators, including BrightFarms, occupy a position focused on localized distribution networks for supermarkets. These companies collectively anchor significant capital investment in advanced cultivation systems, reflecting the industry's drive toward operational efficiency and consistent product delivery.
| Leading Market Players |
|---|
| AeroFarms |
| Plenty Unlimited Inc. |
| Bowery Farming |
| BrightFarms |
| Gotham Greens |
| 80 Acres Farms |
| GoodLeaf Farms |
| Freight Farms |
| Infarm |
Cost & Logistics Intelligence
Long-term offtake agreements increasingly lock in supply access and price visibility for North America's vertical farming operators. These contracts stabilize revenue streams, mitigating volatility from energy and capital costs.
Pricing Analysis
Supermarket chains anchor contract-based long-term offtake pricing in North America's vertical farming market. Pricing differentiation stems from consistent quality grades and guaranteed volume scale. Pricing softness reflects high energy costs and capital intensity, particularly for smaller operators. Supermarket Chains exhibit lower price sensitivity due to demand for year-round fresh produce, while Urban Farms selling direct-to-consumer are highly price-sensitive.
Supply Chain Analysis
Just-in-time inventory strategies dominate North American vertical farming, driven by the perishable nature of fresh produce. Supply concentrates near urban centers across the United States and Canada, with some specialized component sourcing from Mexico. This model draws from advanced LED lighting systems and proprietary nutrient solutions. Energy price volatility represents a significant structural risk, directly impacting operational costs. Distribution runs through localized direct-to-retail partnerships with major supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America vertical farming market presents a fragmentation opportunity, driven by consumer preferences for pesticide-free products and transparent origins. This demand creates niches for specialized cultivation and localized distribution models.
For Market Incumbents: Shield existing market share by deepening vertical integration into proprietary technology development for LED lighting systems. Invest in advanced certifications, like USDA organic, to counter emerging niche entrants targeting premium consumer segments. Secure long-term offtake agreements with major supermarket chains against volatile energy costs.
For New Entrants and Emerging Players: Underserved secondary metropolitan areas represent a significant white-space target for localized production. Focus on high-value specialty crops like berries, which offer higher margins than leafy greens. Leverage agile technology integration, such as AI-powered analytics, to optimize resource use. A direct-to-consumer or specialty food service go-to-market angle can bypass established retail channels.
For Investors and Strategic Acquirers: Technology-driven growers with proprietary operating systems represent attractive acquisition targets over the next five to ten years. These firms optimize diverse crop varieties and demonstrate strong unit economics. Seek companies with established long-term retailer partnerships and a clear path to energy efficiency. The signal to watch is sustained profitability across multiple large-scale facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables operators to meet the consistent, year-round demand from major supermarket chains across North America. |
| Green Manufacturing Transition | Reduces energy costs and enhances brand perception among consumers prioritizing environmental sustainability. |
| Long-term Supply Agreement | Secures predictable revenue streams and stable volume commitments from large food service providers. |
| Strategic Partnership | Facilitates co-development of advanced LED lighting systems or automated climate control technologies. |
| Technology Acquisition | Integrates AI-powered analytics or robotic systems to optimize resource use and reduce labor-dependent costs. |
Research Approach
A standing panel of plant scientists, horticulturalists, control systems engineers, and retail procurement managers provided ongoing calibration for this market analysis. This study combined primary interviews with industry stakeholders and secondary validation from sources like FDA filings, Health Canada guidelines, and USDA organic certification standards. Bottom-up data collection was triangulated with top-down market sizing, ensuring robust estimation across all segments.
Market outputs were consistently validated against external benchmarks and published industry reports to ensure accuracy across the analysis window. The analytical framework modeled key dimensions including production method, crop type, technology, and end-user segments. Compound annual growth rates were derived from historical trends and projected technological advancements. Forecast inputs included energy cost projections and retailer demand patterns.
Forecasts assume regulatory continuity in United States FDA and Health Canada regimes; material policy shifts would require re-modeling. These projections reflect current assumptions regarding energy prices and technology adoption rates. Revision becomes warranted when significant shifts in consumer preferences or capital investment patterns cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Global Horticulture Lighting Market