
 Middle East Vertical Farming Market | 2026-2036
Middle East Vertical Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Vertical Farming Market Foresight
Subscription-based crop monitoring and predictive harvest software is decoupling revenue from pure tonnage sales across the Middle East vertical farming sector. Pure Harvest Smart Farms leverages its advanced greenhouse technology to sustain year-round production in the Arabian Desert climate. Badia Farms anchors its competitive position through deep specialization in premium microgreens for high-end hospitality channels. Bustanica differentiates via its massive scale operation serving airline catering and institutional foodservice across the Gulf.
Vertical farming denotes the practice of cultivating crops in stacked layers or vertically inclined surfaces, typically employing hydroponic or aeroponic systems with LED spectrum control, closed-loop nutrient delivery, and climate-regulated environments achieving 95% water reduction versus open-field agriculture. Its primary purpose is to produce food crops in arid or land-constrained regions where conventional agriculture faces extreme water scarcity or salinity challenges. Hydroponic installations dominate current regional capacity due to lower capital thresholds and proven operational track records in Gulf conditions. Aeroponic approaches represent the fastest-expanding technological category, attracting R&D investment for their superior water efficiency and accelerated growth cycles. Leafy greens command the largest product-type volume, though microgreens concentrate the highest margin pools per kilogram through premium restaurant and hotel procurement.
The UAE's Ministry of Climate Change and Environment and Saudi Arabia's Ministry of Environment, Water and Agriculture both enforce food security frameworks that channel public investment into controlled-environment agriculture, shaping permit allocation and subsidy eligibility for vertical farm operators. Saudi Food and Drug Authority standards for pesticide-free certification and produce traceability create compliance thresholds that filter market access toward technologically capable growers. Stakeholders must monitor how evolving Gulf Cooperation Council harmonization of agricultural investment rules reshapes cross-border expansion pathways and capital deployment timing for facility scaling decisions.
Market Dynamics
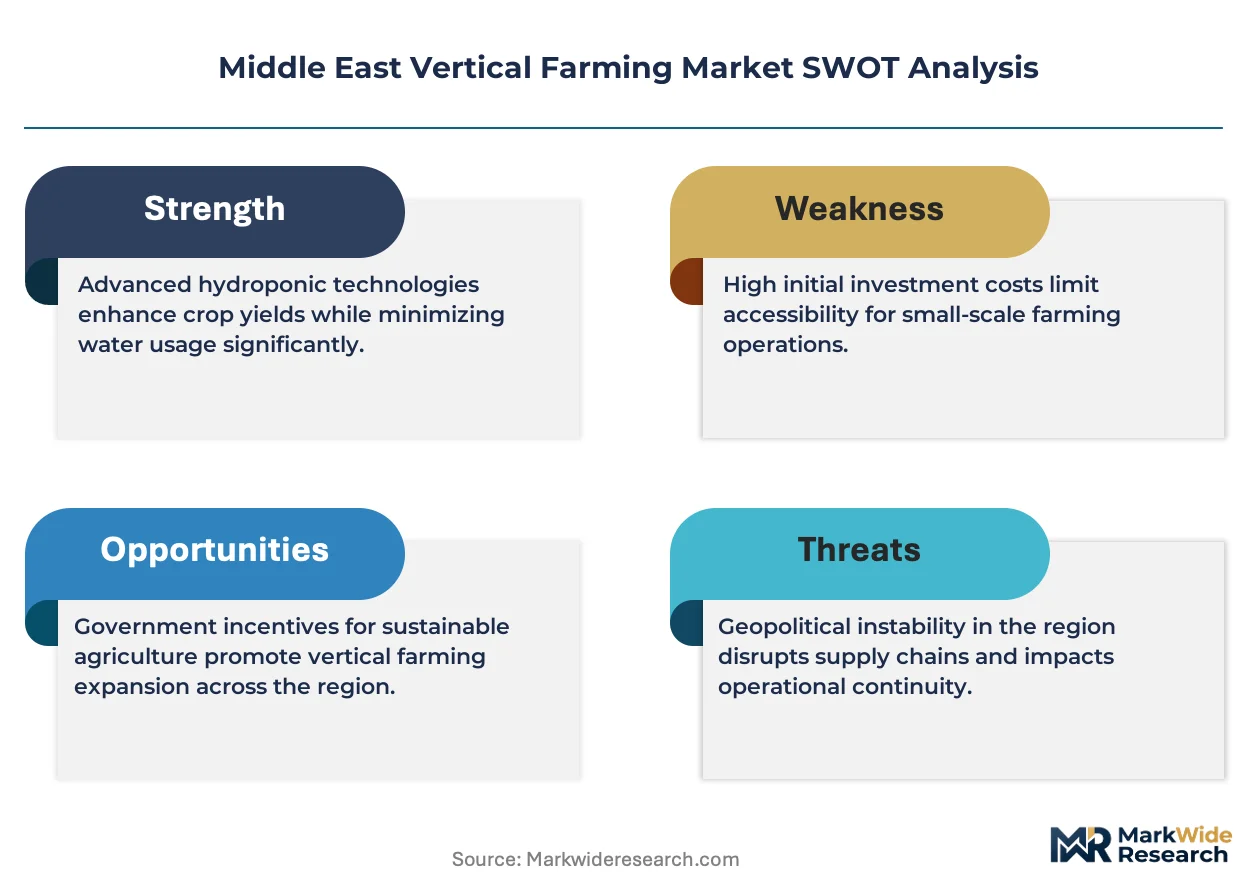
Water scarcity across the Arabian Peninsula is compressing adoption timelines for closed-loop agriculture systems, with sovereign capital now treating controlled-environment farming as critical infrastructure rather than experimental technology.
Growth Catalysts
- SFDA pesticide-free certification:Saudi Food and Drug Authority standards for residue-free produce create procurement preference channels for vertical farm operators supplying institutional foodservice.
- Airline catering procurement:Gulf carriers expanding premium cabin dining programs are contracting hyperlocal greens to reduce supply chain miles and improve freshness metrics for long-haul routes.
- Aeroponic R&D clusters:Water efficiency gains from mist-based nutrient delivery are attracting public-private research partnerships in the UAE and Saudi Arabia.
Market Restraints
- LED energy costs:Cooling loads and spectrum-tuned lighting systems consume 60-70% of facility operating expenditure, tying margin sustainability to grid electricity pricing volatility.
- Equipment import dependency:Climate control systems and sensor arrays concentrate manufacturing in East Asian supply bases, exposing operators to shipping cost swings and customs clearance delays.
- Yield ceiling constraints:Current photosynthetic efficiency limits for leafy greens prevent vertical farms from matching field-scale unit economics for commodity crops.
Strategic Opportunities
- Kuwait underpenetration:The emirate's food import dependency and limited arable land create whitespace for controlled-environment facilities serving local retail and hospitality channels.
- Subscription monitoring software:Predictive harvest platforms decouple revenue from pure tonnage sales, enabling recurring income streams from data-as-a-service models.
- MOHAP green building incentives:Dubai's health authority offers accelerated permitting for vertical farms integrated into mixed-use developments, reducing time-to-revenue for new facilities.
Industry Challenges
- Horticultural automation expertise:The region lacks sufficient agritech engineers capable of calibrating closed-loop nutrient systems and LED spectrum protocols for desert-adapted cultivars.
- Produce traceability integration:Blockchain-based supply chain verification required by premium hotel chains demands capital investment in sensor infrastructure and data architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Vertical Farming Market |
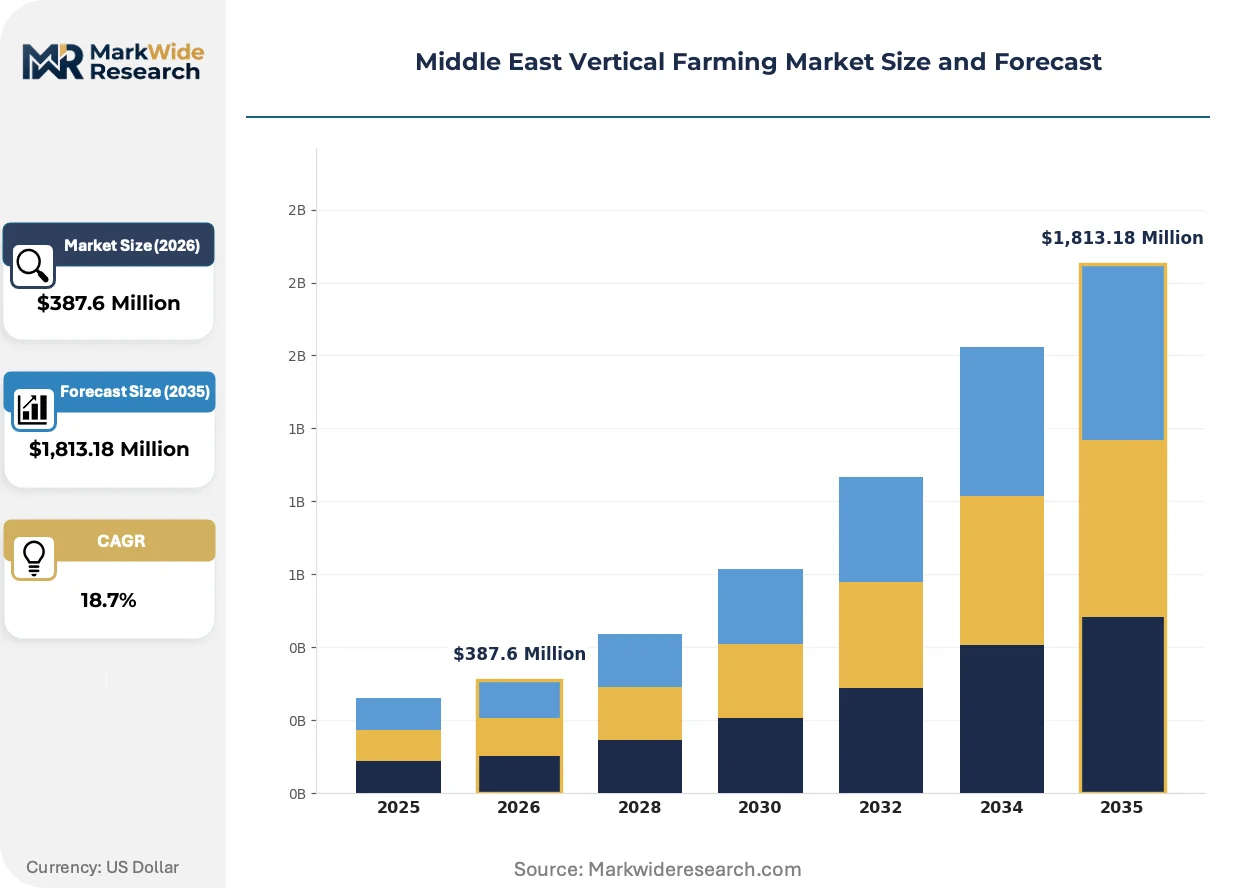
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,813.18 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafy Greens, Herbs, Berries, Microgreens Technological Approach: Hydroponics, Aeroponics, Aquaponics, Soil-based Systems End User: Restaurants, Supermarkets, Farms, Educational Institutions Distribution Channel: Direct Sales, Wholesale, Online Retail, Partnerships |
| Companies Covered | Agricool, Emirates Hydroponics Farms, Badia Farms, Bustanica, GreenBridge, Madar Farms, Pure Harvest Smart Farms, Babil Farms, AeroFarms, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Vertical Farming Market Shifts & Advancements
Technology convergence between precision agriculture and building management systems is redefining facility design standards across Gulf vertical farming operations.
Spectrum-adjustable LED arrays is overtaking fixed-spectrum installations as the dominant lighting technology in new facilities. Hotel and fine-dining procurement teams now specify cultivar-specific light recipes as contract terms. This capability compression is enabling harvest scheduling precision that matches restaurant menu cycles rather than wholesale distribution windows.
MOCCAE's controlled-environment agriculture subsidy framework channels public investment toward facilities demonstrating closed-loop water recycling above 90% efficiency. Operators meeting this threshold receive expedited permitting for expansion sites. Premium microgreens producers targeting hospitality channels are restructuring capital plans to capture these eligibility criteria.
Hyperlocal sourcing mandates from luxury hotel groups are replacing traditional produce distribution relationships. Procurement contracts now specify maximum transport distances and harvest-to-plate time limits. The UAE's seven-star hospitality cluster exhibits the most aggressive adoption of this sourcing model, with some properties requiring on-site or sub-50-kilometer supply origins.
Middle East Vertical Farming Market Segmentation
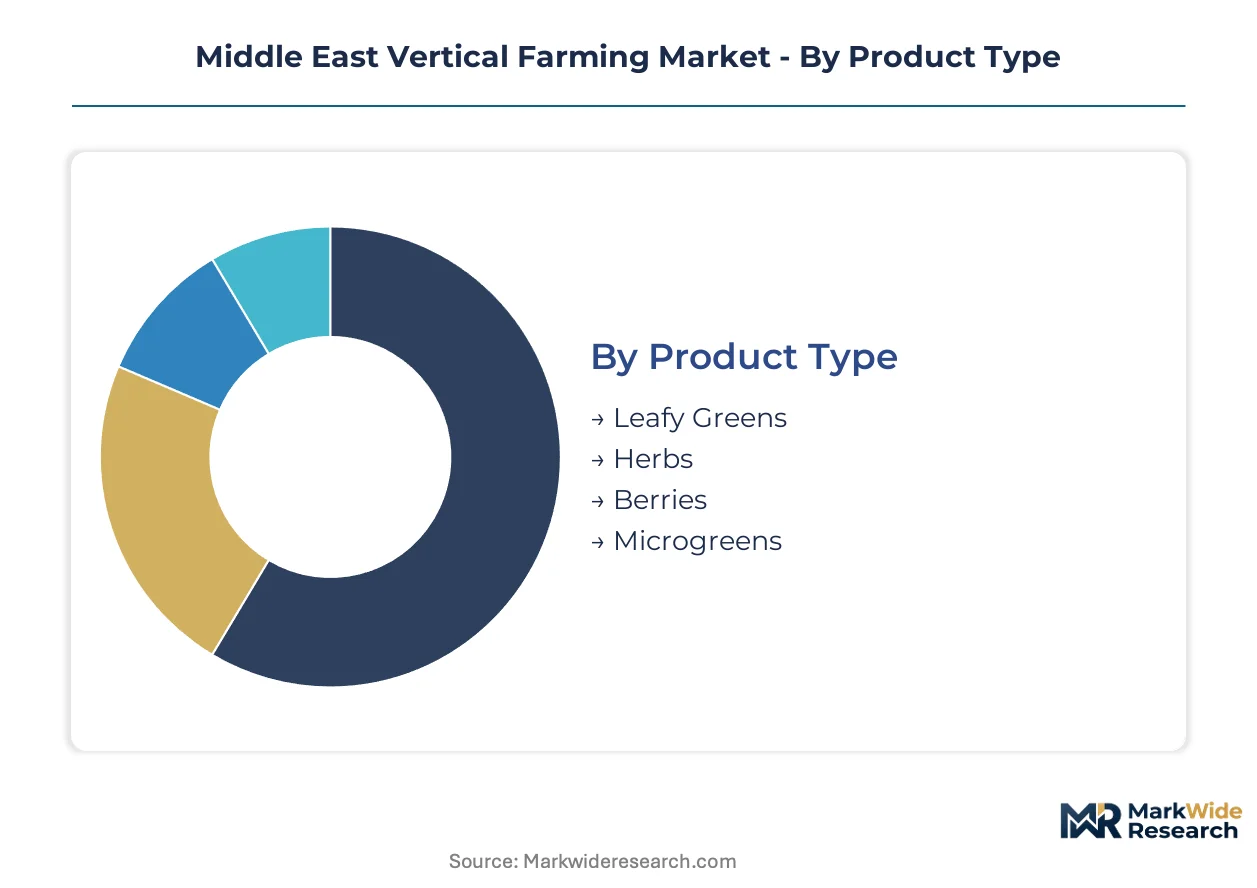
Segmentation in Middle East vertical farming reveals how water scarcity and hospitality procurement reshape crop selection and technology deployment. Buyers differentiate by margin tolerance, freshness requirements, and integration complexity rather than commodity scale.
Product Type:
Margin concentration separates premium buyers seeking harvest-to-plate precision from volume operators serving retail channels.
- Leafy Greens:Lettuce, spinach, and kale varieties dominate facility output volumes through standardized hydroponic protocols. UAE hotels and Saudi institutional foodservice anchor procurement, though per-kilogram margins compress under wholesale pricing pressure.
- Microgreens:Concentrated flavor profiles and 7-14 day harvest cycles command pricing multiples over mature greens. Dubai's seven-star hospitality cluster specifies sub-50-kilometer sourcing for these cultivars, creating geographic moats for nearby operators.
- Herbs:Basil, cilantro, and mint varieties serve Middle Eastern and Mediterranean restaurant menus with moderate technical complexity.
- Berries:Strawberry and raspberry cultivation requires advanced pollination management and extended grow cycles, limiting current regional adoption.
Volume sits with Leafy Greens; growth tilts toward Microgreens.
Technological Approach:
Capital efficiency and water recovery rates determine which systems attract sovereign wealth deployment versus private operator investment.
- Hydroponics:Nutrient film technique and deep water culture systems deliver proven yields with lower capital thresholds. Saudi Food and Drug Authority certification pathways favor these established configurations for institutional supply contracts.
- Aeroponics:Mist-based nutrient delivery achieves 95%+ water efficiency, qualifying operators for MOCCAE subsidy eligibility. UAE research partnerships are climbing the fastest for this category as sovereign capital treats water recovery as critical infrastructure.
- Aquaponics:Integrated fish cultivation adds protein output and biological filtration, though operational complexity constrains scaling.
- Soil-based Systems:Substrate cultivation in controlled environments bridges conventional and vertical methods for specific heritage cultivars.
Installations concentrate in Hydroponics; capability investment flows toward Aeroponics.
End User:
Traceability requirements and harvest-to-plate windows segment buyers by technical sophistication and contract structure.
- Restaurants:Fine-dining establishments in Dubai and Riyadh specify cultivar-specific light recipes and maximum transport distances. Blockchain verification requirements from luxury hotel groups filter supplier access toward capital-intensive operators.
- Supermarkets:UAE retail chains are consolidating procurement through direct farm partnerships, displacing traditional produce distributors.
- Farms:Existing agricultural operations adopt vertical modules for seedling propagation and year-round mother stock maintenance.
- Educational Institutions:Universities and research centers deploy small-scale systems for agritech training and cultivar adaptation studies.
Revenue concentrates with Restaurants; contract volume expands fastest in Supermarkets.
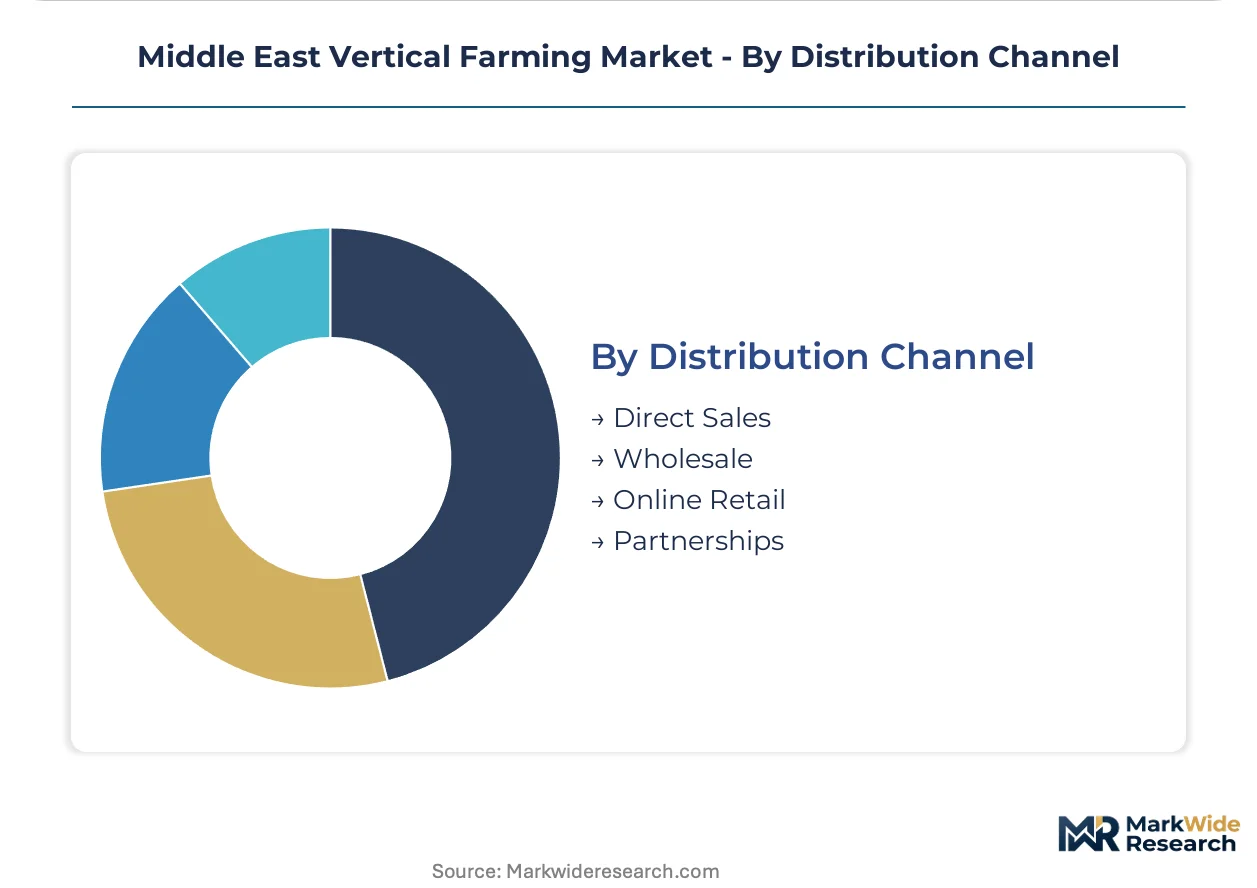
Distribution Channel:
Supply chain control and freshness guarantees separate channels serving premium hospitality from commodity retail.
- Direct Sales:On-site farm shops and dedicated contracts with hotel groups eliminate intermediary handling. Gulf airline catering procurement for premium cabin programs runs exclusively through this channel.
- Wholesale:Traditional produce distributors aggregate output from multiple facilities for supermarket and foodservice consolidation.
- Online Retail:Subscription-based home delivery platforms are emerging in Dubai and Riyadh for affluent consumer segments.
- Partnerships:Mixed-use development integrations leverage MOHAP green building incentives for accelerated permitting.
Margin capture favors Direct Sales; infrastructure scaling depends on Wholesale consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity across the Middle East vertical farming sector lags behind consumption demand from hospitality and institutional foodservice channels, creating import dependency that sovereign capital now treats as a strategic vulnerability. Water scarcity and arable land constraints compress adoption timelines for controlled-environment agriculture systems. National food security frameworks channel public investment toward facilities demonstrating closed-loop efficiency above 90%.
United Arab Emirates
Dubai's seven-star hospitality cluster drives procurement of hyperlocal microgreens with sub-50-kilometer sourcing mandates. MOCCAE subsidy frameworks expedite permitting for operators achieving 95% water recycling efficiency. The emirate's airline catering sector contracts premium cabin greens exclusively through direct farm partnerships, bypassing traditional distribution.
Saudi Arabia
Riyadh's institutional foodservice expansion anchors demand for pesticide-free leafy greens certified under SFDA traceability standards. The Ministry of Environment, Water and Agriculture channels sovereign wealth into controlled-environment agriculture as critical national infrastructure. NEOM's northwest development zone attracts aeroponic R&D clusters seeking desert-adapted cultivar protocols.
Kuwait
Limited arable land and 90% food import dependency create whitespace for vertical farm operators serving local retail and hospitality channels. The country's national agricultural investment authority evaluates controlled-environment proposals against water recovery benchmarks. Kuwait City hotel procurement teams increasingly specify harvest-to-plate windows under 24 hours for premium greens.
Qatar
Doha's hospitality sector recovery post-2022 World Cup infrastructure sustains demand for high-margin microgreens and specialty herbs. The national food security program subsidizes greenhouse technology imports to reduce supply chain vulnerability. Lusail's mixed-use developments integrate vertical farming modules qualifying for accelerated permitting under green building incentives.
Israel
Advanced agritech R&D clusters in the central coastal plain export precision agriculture expertise to Gulf operators seeking desert cultivation protocols. The national innovation authority funds closed-loop system development for water-stressed environments. Tel Aviv-based technology licensors increasingly partner with UAE and Saudi facilities for LED spectrum calibration and predictive harvest software deployment.
Middle East Vertical Farming Market Competitive Landscape
Top-tier vendors anchor sovereign-backed mega-facilities serving airline catering and institutional channels, while mid-scale operators concentrate on premium hospitality microgreens with geographic moats around Dubai and Riyadh. The vendor base stratifies across three tiers: technology-integrated scale players, specialization-driven regional growers, and R&D-focused technology licensors. Market consolidation proceeds through strategic partnerships with mixed-use developers rather than outright acquisition. Competitive positioning depends increasingly on MOCCAE and SFDA certification velocity rather than pure capacity metrics.
Among UAE-based operators, Bustanica and Madar Farms exemplify the scale-driven archetype serving mass institutional channels, while Badia Farms occupies a specialist position in premium microgreens for fine-dining procurement. Pure Harvest Smart Farms represents the technology-integrated tier with advanced greenhouse protocols adapted to Arabian Desert conditions. These three anchors demonstrate how competitive differentiation fragments across volume efficiency, margin concentration, and climate adaptation capability rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Agricool |
| Emirates Hydroponics Farms |
| Badia Farms |
| Bustanica |
| GreenBridge |
| Madar Farms |
| Pure Harvest Smart Farms |
| Babil Farms |
| AeroFarms |
| Others |
Supply & Pricing Matrix
Dubai's seven-star hospitality procurement clusters anchor pricing power for premium microgreens, compressing margin tolerance for operators lacking sub-50-kilometer geographic positioning. Contract structures bifurcate between subscription-based crop monitoring platforms and per-kilogram spot arrangements, with the former capturing recurring revenue insulation against commodity volatility.
Pricing Analysis
Margin tightening in premium microgreens reflects harvest-to-plate window compression demanded by luxury hotel groups. Three-tier pricing structure across premium, standard, and economy levels separates MOCCAE-certified operators from uncertified competitors and wholesale commodity suppliers. Price differentiation traces to SFDA pesticide-free certification status and LED spectrum customization capability. Institutional foodservice buyers exhibit highest price sensitivity; airline catering procurement teams prioritize freshness metrics over unit cost.
Supply Chain Analysis
Equipment refurbishment flows from decommissioned Gulf facilities are nascent, with most operators preferring direct replacement of LED arrays and climate control systems. Manufacturing concentrates in China, South Korea, and Japan for spectrum-tunable lighting and sensor infrastructure. Raw material dependencies span semiconductor-grade LEDs, precision nutrient formulations, and climate-grade aluminum extrusions. Single-source vulnerability concentrates in advanced greenhouse automation controllers. Distribution runs through direct farm partnerships for hospitality channels and wholesale consolidation for retail supermarket supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in Middle East vertical farming is becoming a vertical-integration race, with upstream control over LED calibration protocols and downstream capture of airline catering contracts determining margin sustainability.
For Market Incumbents: Hedge against aeroponic R&D disruption by securing exclusive cultivar licensing agreements with Israeli agritech clusters. Expand capacity in Kuwait's underpenetrated retail corridor before subsidy frameworks mature. Prioritize MOCCAE certification velocity over pure tonnage scaling to defend institutional procurement relationships. For New Entrants and Emerging Players: Enter via subscription-based predictive harvest software rather than capital-intensive facility construction. Target Qatar's post-World Cup hospitality recovery for premium herb contracts. Pursue mixed-use development partnerships qualifying for MOHAP green building accelerated permitting. For Investors and Strategic Acquirers: The window for entry favors technology-integrated operators with proven desert climate adaptation protocols. Long-term viability hinges on water recovery efficiency above 90% and closed-loop nutrient system IP. Monitor SFDA harmonization with GCC agricultural investment rules as inflection signal for cross-border scaling feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Manufacturing | Captures spectrum-tuning IP and reduces exposure to East Asian shipping volatility. |
| MOCCAE Certification Fast-Track Program | Expedites permitting for 95% water recycling facilities accessing sovereign subsidy pools. |
| Airline Catering Direct Partnership | Locks in premium cabin freshness requirements bypassing wholesale distribution margins. |
| Predictive Harvest Platform Launch | Decouples revenue from commodity tonnage through data-as-a-service recurring contracts. |
| Kuwait Retail Channel Expansion | Exploits 90% food import dependency before competitive facility saturation emerges. |
Research Methodology
Independent corroboration across vertical farm operations managers, hospitality procurement directors, and agritech R&D leads underwrites the qualitative findings. Primary interviews with MOCCAE regulatory officials, SFDA certification auditors, and airline catering supply chain heads combined with secondary validation from customs records, sovereign wealth investment disclosures, and hospitality procurement databases. Bottom-up facility capacity modeling and top-down food security policy analysis triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by product type, technological approach, end user, and distribution channel. CAGRs derive from facility deployment pipelines, subsidy allocation trajectories, and hospitality sector expansion plans. Forecast inputs incorporate water scarcity intensity indices and LED energy cost projections without specific year anchoring.
Revisions become necessary when GCC agricultural investment harmonization accelerates, aeroponic R&D yields breakthrough cultivar protocols, or sovereign subsidy eligibility thresholds shift. Forecasts reflect documented assumptions regarding permit timelines and technology cost curves. Practitioners should monitor SFDA-MOCCAE regulatory convergence and Kuwaiti national agricultural authority investment decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Controlled Environment Agriculture Market