
 Vertical Farming Produce Market | 2026-2036
Vertical Farming Produce Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Farming Produce Market Intelligence
The EU Green Deal is rebalancing procurement priorities across European retail chains toward pesticide-free domestic sourcing. AeroFarms leverages closed-loop aeroponic systems to sustain year-round basil and arugula output for urban distribution. Plenty Unlimited anchors large-scale indoor strawberry production near major metropolitan demand centers. Bowery Farming differentiates through proprietary operating systems that control light spectra and nutrient delivery.
Vertical farming produce comprises crops cultivated in stacked, climate-controlled environments using soilless techniques with precise LED photoperiod management and recirculated nutrient solutions. These facilities typically operate at 95 percent water efficiency compared with field agriculture, supplying local markets with harvest-to-shelf cycles under 48 hours. Hydroponic leafy greens dominate current volume, while aeroponic berries command premium positioning due to complexity and perishability. LED lighting technology absorbs significant capital allocation, though declining diode costs are reshaping facility economics. Grocery stores represent the fastest-growing end user channel as retailers build direct supplier relationships to secure consistent quality and traceability.
The EPA regulates agricultural water discharge and pesticide alternatives in the United States, while the EU Green Deal and REACH framework govern chemical inputs and carbon accounting for European operators. FDA food safety rules and FSMA traceability mandates shape packaging, labeling, and lot-tracking requirements across interstate commerce. Stakeholders must monitor evolving energy tariffs and building code classifications that determine whether indoor farms qualify for agricultural or commercial utility rates.
Market Dynamics
LED diode cost deflation is compressing facility breakeven timelines while EU pesticide residue rules are redirecting retail procurement toward controlled-environment domestic suppliers.
Growth Catalysts
- EU Green Deal residue limits:Tightening thresholds on imported field vegetables are forcing European grocers to source from local hydroponic and aeroponic operations.
- Wageningen research corridor:Concentrated agritech expertise in the Netherlands accelerates cultivar development and system optimization for commercial deployment.
- Stacked climate control:Precision HVAC and LED photoperiod management enable year-round production irrespective of external weather volatility.
Market Restraints
- Electricity tariff structures:Ambiguous building code classifications in multiple jurisdictions leave operators exposed to commercial rather than agricultural utility rates.
- LED supply concentration:Diode manufacturing concentrates in East Asian foundries, exposing facility builders to input cost volatility and lead time risk.
- Technical yield ceilings:Photosynthetic efficiency limits and cultivar-specific light recipes constrain output per square meter for fruiting crops.
Strategic Opportunities
- Germany's REPowerPlan agricultural incentives:Federal energy transition funding creates capital subsidy pools for domestic food security infrastructure.
- Direct-to-retail channel expansion:Grocers are building captive supplier relationships that bypass traditional produce distribution intermediaries.
- Sensor-automation convergence:Integration of computer vision with nutrient dosing systems enables real-time crop health intervention.
Industry Challenges
- Controlled-environment agronomy talent:Shortage of technicians trained in simultaneous management of HVAC, lighting, and hydroponic chemistry slows facility commissioning.
- FSMA traceability compliance:FDA lot-tracking mandates require serialization infrastructure that smaller operators struggle to implement.
- Capex intensity for berry conversion:Shifting from leafy greens to strawberries demands trellis systems, pollination management, and extended grow cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Farming Produce Market |
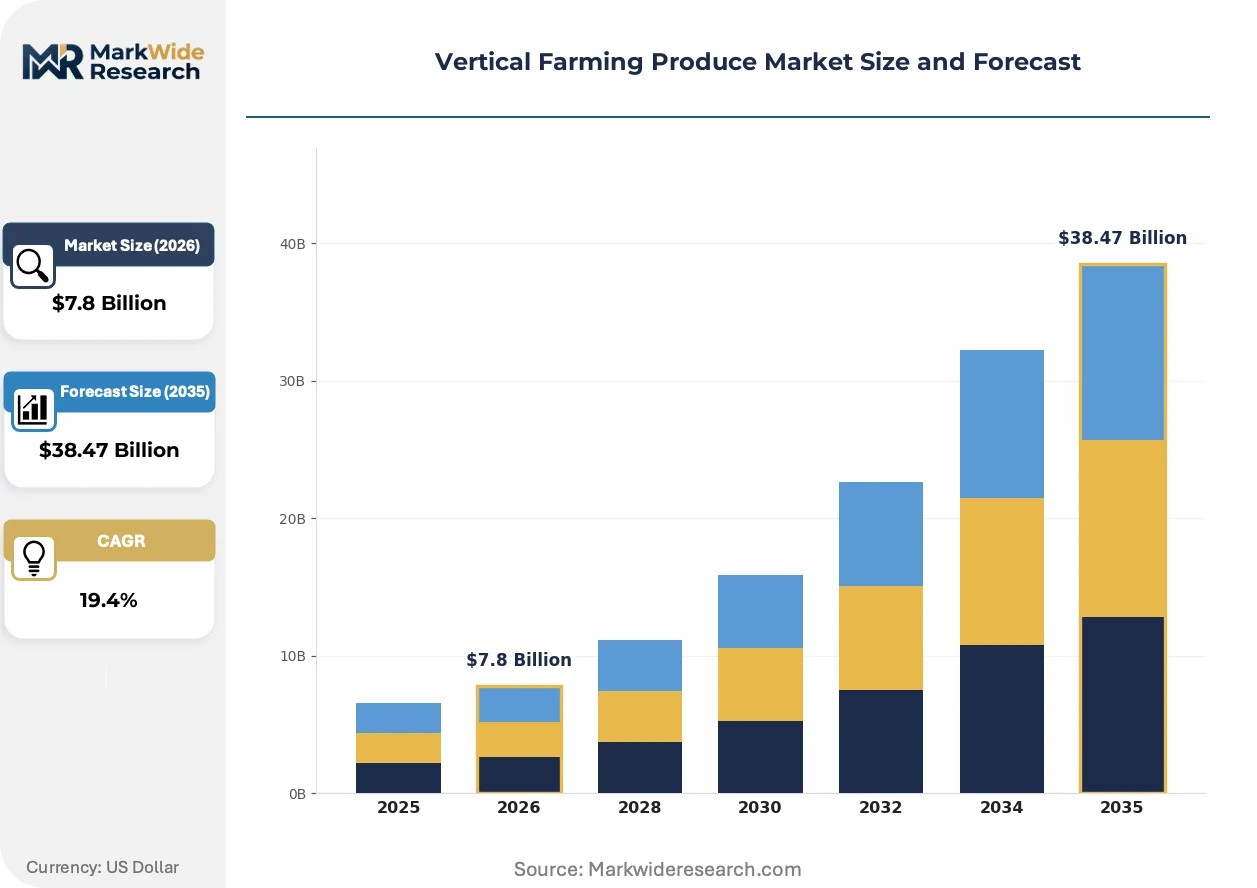
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $38.47 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafy Greens, Herbs, Berries, Microgreens Technology: Hydroponics, Aeroponics, Aquaponics, LED Lighting End User: Restaurants, Grocery Stores, Food Distributors, Home Consumers Distribution Channel: Direct Sales, Online Retail, Wholesale, Farmers Markets |
| Companies Covered | AeroFarms, Plenty Unlimited, Signify Holding, Bowery Farming, InFarm, 80 Acres Farms, BrightFarms, Kalera, CubicFarms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Farming Produce Market Strategic Shifts & Innovations
Automation and spectral tuning are converging to reshape facility economics, while regulatory pressure on chemical residues accelerates soilless method adoption across premium retail channels.
Solid-state lighting with tunable spectra is overtaking fixed-spectrum installations in new facility construction. Large-scale operators are adopting dynamic diode arrays that adjust wavelength composition through crop growth stages. This flexibility is overtaking the legacy approach of single-spectrum rooms dedicated to specific cultivars, compressing capital allocation per output unit.
REACH framework chemical authorization requirements are tightening input sourcing for European operators. The regulation now demands extensive substance dossiers for hydroponic nutrient compounds previously grandfathered under older exemptions. Leafy green producers in the Netherlands and Belgium are responding by consolidating supplier relationships and accelerating organic-input certification timelines.
Hyperlocal procurement contracts are displacing traditional produce auction systems in urban retail. Grocers within fifty kilometers of vertical farms are negotiating direct supply agreements that guarantee harvest-to-shelf cycles under forty-eight hours. This pattern is most visible in metropolitan corridors of the United States and Germany where real estate costs justify premium positioning for traceable, pesticide-free produce.
Vertical Farming Produce Market Segmentation
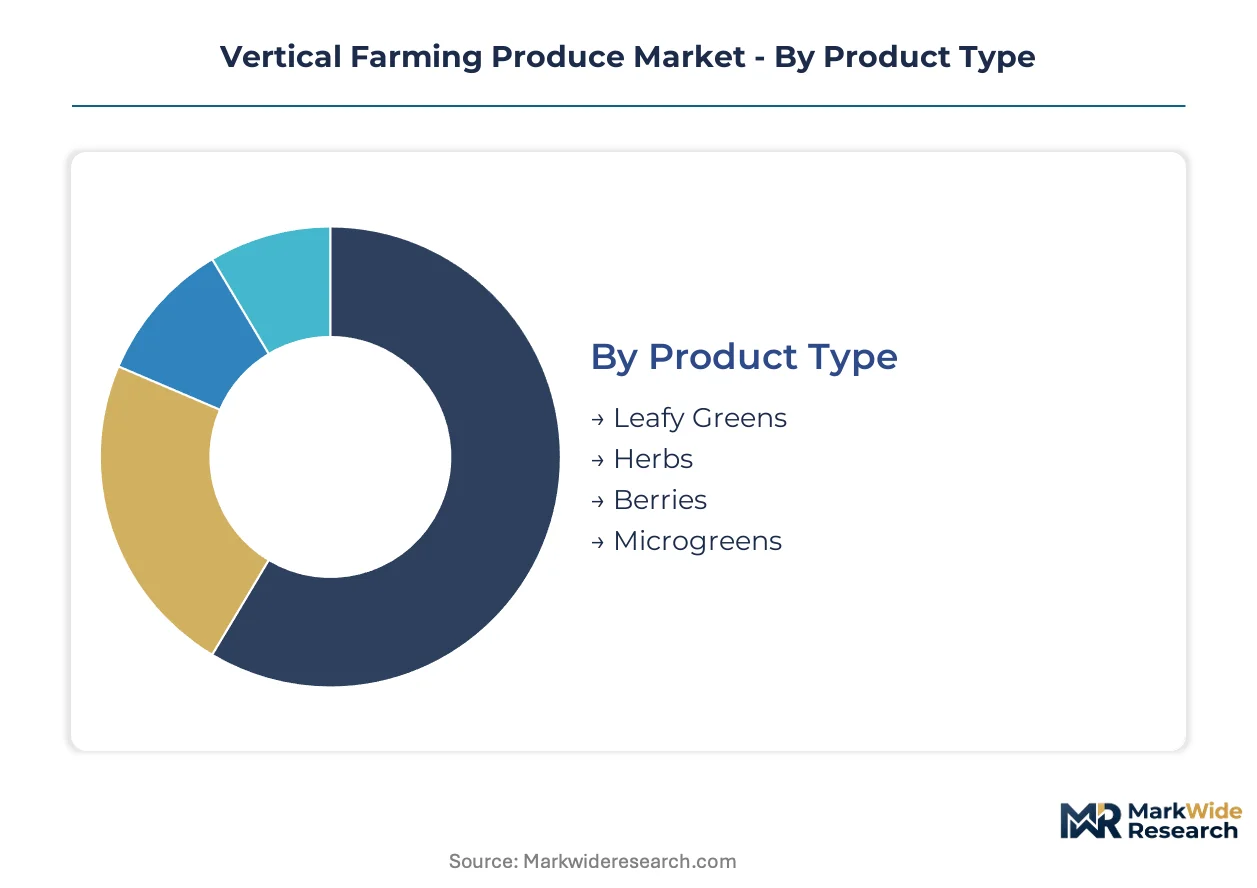
Segmentation in vertical farming produce reveals how facility operators allocate capital across crop types, system technologies, and channel structures. Each dimension carries distinct margin profiles, regulatory exposure, and upgrade-cycle timing that shape investment decisions.
Product Type:
Replacement cycles vary sharply across crop categories, with short-cycle leafy greens demanding annual infrastructure refresh while perennial berry systems require multi-year trellis and pollination investments.
- Leafy Greens:Lettuce, spinach, and kale dominate current facility output due to rapid harvest cycles and established nutrient protocols. Demand concentrates in German and Dutch grocery chains seeking pesticide-free domestic sourcing under EU Green Deal residue limits.
- Herbs:Basil, cilantro, and mint command premium positioning through flavor intensity achievable in controlled environments. US East Coast metropolitan retailers prioritize these for direct procurement contracts guaranteeing sub-48-hour harvest-to-shelf windows.
- Berries:Strawberry and raspberry production requires extended grow cycles and specialized pollination management.
- Microgreens:Young vegetable seedlings serve high-end restaurant channels with concentrated nutrient density claims.
Volume placements concentrate in Leafy Greens; the faster expansion belongs to Berries.
Technology:
Cost tier separation distinguishes legacy system investments from next-generation automation deployments, with capital intensity widening between basic hydroponic installations and precision aeroponic infrastructure.
- Hydroponics:Water-based nutrient delivery systems represent the installed base majority, utilizing NFT and deep-water culture methods. Netherlands-based research clusters around Wageningen University accelerate cultivar optimization for these systems.
- Aeroponics:Mist-based root irrigation achieves superior water efficiency and oxygenation for high-value crops. Commercial deployment concentrates near US metropolitan demand centers where real estate costs justify premium system economics.
- Aquaponics:Integrated fish-and-plant recirculation systems face regulatory complexity under EPA discharge rules.
- LED Lighting:Solid-state photoperiod management absorbs the largest capital allocation share in new facility construction.
Installed capacity concentrates in Hydroponics; steepest expansion trajectory belongs to Aeroponics.
End User:
Customer type determines contract structure, with institutional buyers demanding traceability serialization while home consumers prioritize subscription convenience.
- Restaurants:Fine-dining and fast-casual chains source microgreens and herbs for plate presentation and flavor differentiation. Procurement concentrates in urban corridors of New York, London, and Singapore where chef-driven specifications override commodity pricing.
- Grocery Stores:Supermarkets and specialty retailers build direct supplier relationships bypassing traditional produce auctions. German REPowerPlan agricultural incentives accelerate domestic vertical farm partnerships for these channels.
- Food Distributors:Traditional intermediaries face margin compression from disintermediation trends.
- Home Consumers:Residential countertop systems and subscription boxes serve hobbyist growers.
Contract value concentrates in Grocery Stores; subscriber growth climbs fastest among Home Consumers.
Distribution Channel:
Supply concentration patterns favor channels with shortest path from harvest to consumption, compressing intermediaries in premium produce categories.
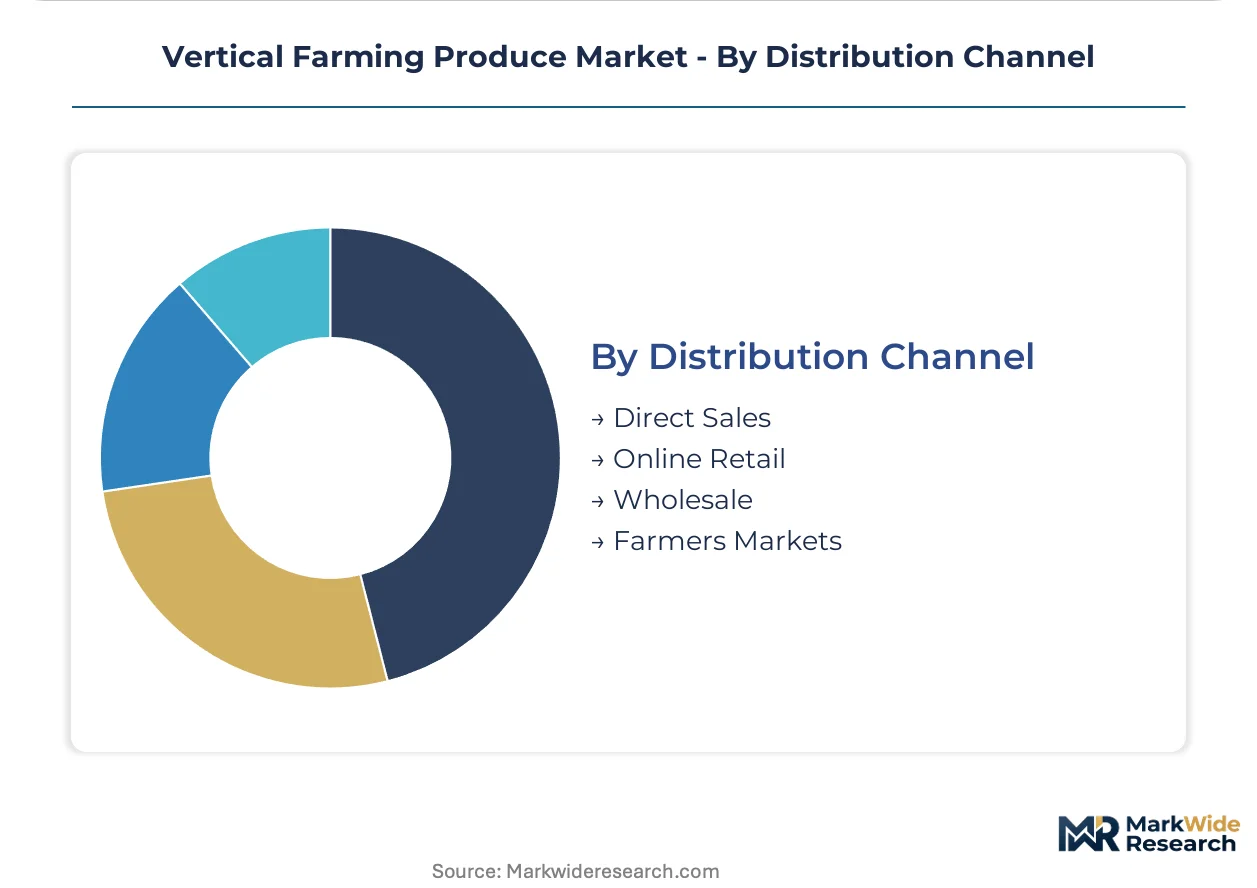
- Direct Sales:Producer-to-retailer agreements eliminate distribution markups and enable lot-level traceability compliance with FDA FSMA mandates. These contracts expand fastest in fifty-kilometer radiuses around major US and German metropolitan facilities.
- Online Retail:E-commerce platforms aggregate home delivery subscriptions and specialty ingredient sourcing. Urban consumer penetration drives expansion in markets with mature cold-chain logistics infrastructure.
- Wholesale:Traditional produce terminals and foodservice distributors handle volume leafy green movement.
- Farmers Markets:Local pickup points serve brand-building and consumer education functions for emerging operators.
Shipment value concentrates in Direct Sales; digital onboarding gains share fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in research-intensive clusters while consumption pulls from metropolitan retail corridors. The Netherlands generates outsized system innovation relative to its domestic market size. United States absorption centers on coastal urban demand density.
Netherlands
Wageningen University research clusters and commercial greenhouse corridors drive cultivar development for European export markets. The EU Green Deal pesticide residue limits redirect supermarket procurement toward domestic hydroponic suppliers. Facilities around Bleiswijk and Westland supply German and Belgian retail chains with harvest-to-shelf cycles under forty-eight hours.
Germany
REPowerPlan agricultural incentives subsidize energy-efficient food security infrastructure near metropolitan demand centers. Federal building code classifications determine whether indoor farms qualify for agricultural utility rates versus commercial tariffs. Berlin and Munich retail corridors host direct procurement contracts with regional vertical farms bypassing traditional produce auctions.
United States
East and West Coast grocery chains expand shelf space for pesticide-free leafy greens and herbs. FDA FSMA traceability mandates shape packaging and lot-tracking requirements across interstate commerce. New York Metro and California facilities anchor direct-to-retail relationships with sub-forty-eight-hour delivery windows.
United Kingdom
London metropolitan retailers prioritize hyperlocal procurement contracts for traceable produce categories. REACH framework chemical authorization requirements tighten input sourcing for hydroponic nutrient compounds. Facilities in southeast England and the Midlands serve urban distribution networks with year-round basil and arugula output.
Singapore
Land-scarce urban planning prioritizes vertical integration of food production into industrial zones. The national food agency regulates novel farming inputs under safety assessment protocols. Research partnerships with Wageningen-trained agronomists accelerate commercial deployment of aeroponic systems for tropical cultivars.
Vertical Farming Produce Market Key Industry Players
The competitive structure tilts toward technology-integrated operators with proprietary control systems. Facility builders and produce cultivators occupy partially overlapping spheres with divergent capital intensity profiles. Three archetypes dominate: research-spinout commercializers, retail-captive suppliers, and equipment-technology licensors. Consolidation pressure runs through direct-to-retail channel expansion and LED automation convergence.
Among research-corridor commercializers, AeroFarms and Plenty Unlimited exemplify divergent scale strategies within controlled-environment agriculture. AeroFarms occupies a position emphasizing closed-loop aeroponic system integration for urban distribution. Plenty Unlimited anchors large-scale metropolitan-proximate production for strawberry and high-value fruiting crops. Signify Holding sits within the enabling-technology tier as a lighting-system supplier rather than produce cultivator.
| Leading Market Players |
|---|
| AeroFarms |
| Plenty Unlimited |
| Signify Holding |
| Bowery Farming |
| InFarm |
| 80 Acres Farms |
| BrightFarms |
| Kalera |
| CubicFarms |
| Others |
Cost & Logistics Intelligence
The EU Green Deal pesticide residue thresholds gate qualified supply for European retail chains and determine premium-tier pricing access for domestic hydroponic operators. Compliance with REACH chemical authorization requirements separates certified producers commanding shelf-space premiums from uncertified competitors facing import displacement.
Pricing Analysis
Yield-per-square-meter throughput anchors value-based pricing for controlled-environment produce, with harvest frequency and cultivar complexity determining contract rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU organic-input protocols and geographic proximity to metropolitan demand centers. Cost compression in leafy green categories is intensifying because LED diode deflation has compressed facility breakeven timelines and attracted new capacity entrants. Grocery chains exhibit highest price sensitivity for commodity lettuce volumes, while fine-dining procurement shows lowest sensitivity for flavor-differentiated herbs and microgreens.
Supply Chain Analysis
Reverse-logistics flows for nutrient solution recycling and LED fixture refurbishment create secondary value recovery streams for large-scale operators. Component manufacturing concentrates in China, South Korea, and Taiwan for solid-state lighting diodes, while cultivar development clusters in the Netherlands around Wageningen research corridors. Raw material dependencies include gallium nitride substrates for LED arrays, specialized hydroponic nutrient salts, and climate-control HVAC components. Single-source vulnerability for diode foundries exposes facility builders to input cost volatility and extended lead time risk. Distribution runs through direct producer-to-retailer agreements that bypass traditional produce auction intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertical farming produce market reads as a cost-of-compliance story where REACH chemical authorization and EU Green Deal residue limits construct barrier-to-entry moats favoring certified incumbent operators.
For Market Incumbents: Extend proprietary control system advantages into adjacent berry categories requiring extended grow cycles and pollination management. Consolidate supplier relationships under REACH framework compliance to lock in organic-input certification timelines before regulatory grandfathering expires. Defensive positioning against emerging retail-captive suppliers demands deepening direct procurement contracts with German REPowerPlan-subsidized grocery chains. For New Entrants and Emerging Players: Begin with metropolitan-proximate herb production for US East Coast fine-dining channels where chef-driven specifications override commodity pricing and sub-48-hour harvest-to-shelf windows command premium positioning. White-space concentration appears in strawberry aeroponics near California and New York Metro demand centers where real estate costs justify premium system economics. Go-to-market execution should emphasize sensor-automation convergence with computer vision nutrient dosing as technical differentiation. For Investors and Strategic Acquirers: German REPowerPlan subsidy disbursement acceleration is the leading indicator that capital allocation toward domestic food security infrastructure has reached institutional scale. Five-to-ten year viability framing favors technology-integrated operators with proprietary spectral tuning and climate-control software over pure-play cultivators exposed to input cost volatility. Acquisition target archetype: research-spinout commercializers with Wageningen-trained agronomy teams and existing retail-captive contracts. Monitor LED diode cost deflation rates as the leading signal for facility breakeven timeline compression and subsequent capacity expansion waves.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Retail Channel Expansion | Bypasses traditional produce auction intermediaries for German and US metropolitan grocery chains. |
| Backward Integration into LED Systems | Captures declining diode cost benefits and reduces East Asian foundry exposure for facility operators. |
| REACH Compliance Certification | Secures premium shelf-space positioning under EU Green Deal pesticide residue limits for European retail. |
| Berry Category Conversion | Demands trellis infrastructure and pollination management for higher-margin strawberry production. |
| Sensor-Automation Convergence | Integrates computer vision with nutrient dosing for real-time crop health intervention. |
Research Approach
Multi-period observation of LED diode cost trajectories, EU pesticide residue threshold enforcement patterns, and facility commissioning timelines anchored the trend analysis, supplemented by interviews with controlled-environment agronomists, grocery category buyers, HVAC system engineers, and hydroponic nutrient compound suppliers. Secondary validation drew from ECHA substance dossier filings, EU Green Deal implementation guidance, EPA agricultural water discharge records, and FDA FSMA traceability mandate documentation. Bottom-up facility capacity tallies triangulated against top-down retail procurement volume estimates across the analysis window.
Segment-weighting approaches distributed value and volume projections across crop type, cultivation technology, and end-user channel dimensions. Crop-specific modeling incorporated harvest cycle frequency, cultivar photosynthetic efficiency limits, and perishability-driven distribution radius constraints. Technology tier analysis weighted capital intensity differentials between hydroponic NFT systems and precision aeroponic infrastructure. End-user channel segmentation captured contract structure variation between institutional traceability mandates and consumer subscription convenience preferences. CAGRs derived from facility commissioning pipeline visibility and retail shelf-space expansion commitments.
Regulatory enforcement variance, LED supply chain disruption events, and electricity tariff reclassification decisions are the dominant revision risks that could compress or extend facility breakeven timelines. Practitioners should monitor ECHA substance authorization timelines, East Asian foundry capacity utilization rates, and German building code classification rulings for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
North America Indoor Farming Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Hydroponic Substrate Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
LED Farming Market