
 Global Square Straw Baler Market | 2026-2036
Global Square Straw Baler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Square Straw Baler Market Outlook
Skilled agricultural equipment technician availability is collapsing across major producing regions, forcing OEMs to redesign service architectures and fleet connectivity. Deere & Company leverages its dealer network density to sustain aftermarket revenue streams. Kuhn SAS specializes in precision baling technology for premium hay export grades. Vermeer Corporation anchors its position through aggressive channel control in the North American contractor segment.
A square straw baler is a farm machine that compresses cut straw or hay into rectangular, stackable bales using plunger-driven compression chambers with typical densities exceeding 180 kg per cubic meter, producing uniform bales for efficient transport and storage. The equipment serves commercial hay operations, livestock bedding supply chains, and biomass collection systems where handling efficiency determines logistics economics. Automatic baler systems dominate volume sales among agricultural enterprises running extended harvest windows, while heavy-duty balers command margin pools in contractor fleets subject to extreme duty cycles. Hydraulic technology retains the largest installed base, though electric drive architectures are gaining traction in regions with strict emissions frameworks.
The EPA regulates off-road diesel emissions under Tier 4 Final standards, compelling engine redesigns and after-treatment integration that inflate base machine costs. ISO 12100 machinery safety standards shape guard design and operator interface requirements across export-bound production. EU Green Deal farm mechanization incentives are redirecting procurement subsidies toward lower-carbon equipment configurations. Stakeholders must monitor how emissions compliance timelines intersect with replacement demand in aging contractor fleets.
Market Dynamics
Hydraulic-to-electric drivetrain transitions are compressing replacement cycles across contractor fleets, while Tier 4 Final compliance costs accelerate consolidation among smaller OEMs unable to absorb after-treatment integration expenses.
Growth Catalysts
- EU Green Deal farm mechanization subsidies:Procurement incentives for lower-carbon equipment configurations are redirecting capital toward electric-drive baler architectures in Germany, France, and the Netherlands.
- Composting facility demand:Organic waste diversion mandates across California, Oregon, and Washington are pulling straw biomass into industrial composting supply chains.
- High-density bale specifications:Export-grade hay operations in the US Great Plains require automatic baling systems capable of exceeding 180 kg per cubic meter for containerized shipping efficiency.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-grade steel and precision hydraulic cylinders compress OEM margins and destabilize contractor fleet financing.
- Tier 4 Final engine redesigns:EPA off-road diesel standards inflate base machine costs by 12-18% for diesel-hydraulic architectures, pricing smaller hay operations out of new equipment markets.
- Biomass pellet substitution:Densified pellet fuels for livestock bedding and energy applications displace traditional straw bale demand in Scandinavian district heating networks.
Strategic Opportunities
- Indian agricultural mechanization:The country's PLI scheme for farm equipment and fragmented smallholder consolidation create white space for compact automatic baler penetration.
- Brazilian sugarcane straw recovery:Post-harvest biomass collection mandates for cogeneration feedstock open new application verticals beyond traditional hay markets.
- Telematics-integrated service contracts:Predictive maintenance platforms bundled with equipment finance are capturing aftermarket revenue streams from risk-averse contractor fleets.
Industry Challenges
- Agricultural equipment technician scarcity:Skilled hydraulic and electric drivetrain specialist availability is collapsing across the US Midwest and Canadian prairies, forcing OEMs to retrain automotive technicians.
- ISO 12100 guard redesign complexity:Machinery safety standard updates require simultaneous operator interface and physical guarding modifications, extending certification timelines.
- Legacy fleet connectivity integration:Retrofitting telematics onto ten-year-old hydraulic balers in Australian contractor fleets demands proprietary adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Square Straw Baler Market |
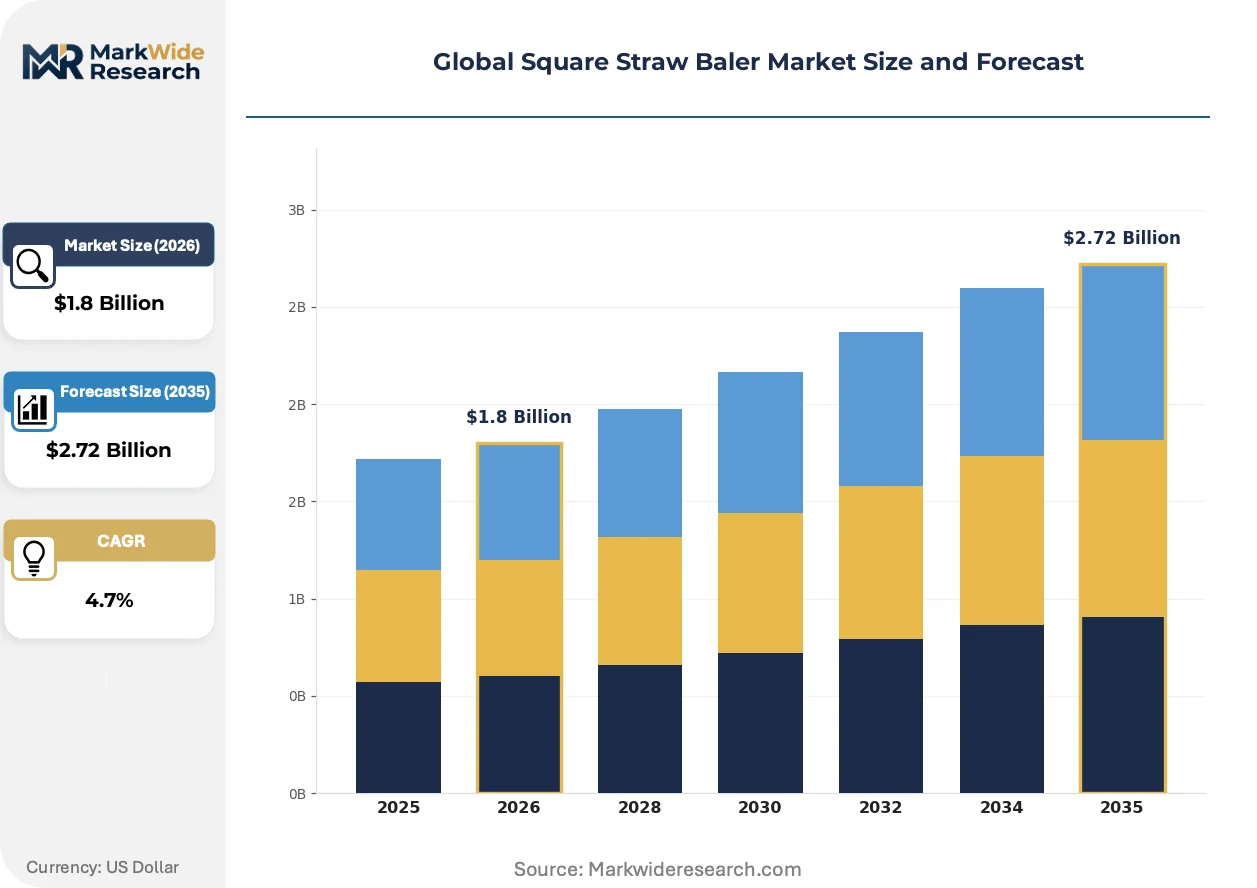
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Baler, Automatic Baler, Semi-Automatic Baler, Heavy-Duty Baler End User: Agricultural Enterprises, Farmers, Contractors, Composting Facilities Technology: Hydraulic, Pneumatic, Mechanical, Electric Application: Hay Production, Straw Management, Waste Processing, Animal Bedding |
| Companies Covered | AGCO Corporation, Maschinenfabrik Bernard Krone GmbH, Deere & Company, Kuhn SAS, Kubota Corporation, CLAAS KGaA mbH, Vermeer Corporation, Mahindra & Mahindra Limited, CNH Industrial NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Square Straw Baler Market Strategic Shifts
Electric drivetrain architectures are decomposing the hydraulic technology monopoly, while emissions compliance timelines and precision agriculture integration reshape equipment specification patterns across export-oriented hay operations.
Brushless electric motor systems paired with lithium-ion powerpacks are decomposing the century-long dominance of hydraulic compression chambers in square straw balers. Premium hay export contractors in Nebraska and Kansas are piloting these systems to eliminate hydraulic fluid contamination risks in certified organic supply chains. The technology is decomposing traditional 7-10 year replacement cycles by enabling predictive maintenance algorithms that flag plunger wear before field failure.
REACH chemical restrictions on hydraulic fluid formulations are compelling European OEMs to accelerate electric-drive roadmaps ahead of original commercialization timelines. The regulation forces reformulation of legacy mineral oil-based systems or complete architecture abandonment for export-bound production. German and Danish manufacturers are responding with modular electric platforms that isolate high-wear compression components from drivetrain electronics.
Outcome-based equipment utilization contracts are displacing traditional ownership models among North American hay contractors facing compressed harvest windows and capital constraints. Fleet management companies are inserting themselves between OEMs and end-users, absorbing residual value risk in exchange for guaranteed uptime commitments. This restructuring is most visible across the Alberta and Saskatchewan contractor segments where labor scarcity amplifies downtime costs.
Global Square Straw Baler Market Segmentation
Equipment specification patterns diverge sharply between export-oriented hay contractors and domestic livestock operations, with technology choices increasingly constrained by emissions compliance timelines and labor availability. Understanding segment boundaries reveals where substitution pressures from densified biomass and service-based ownership models are compressing traditional equipment procurement cycles.
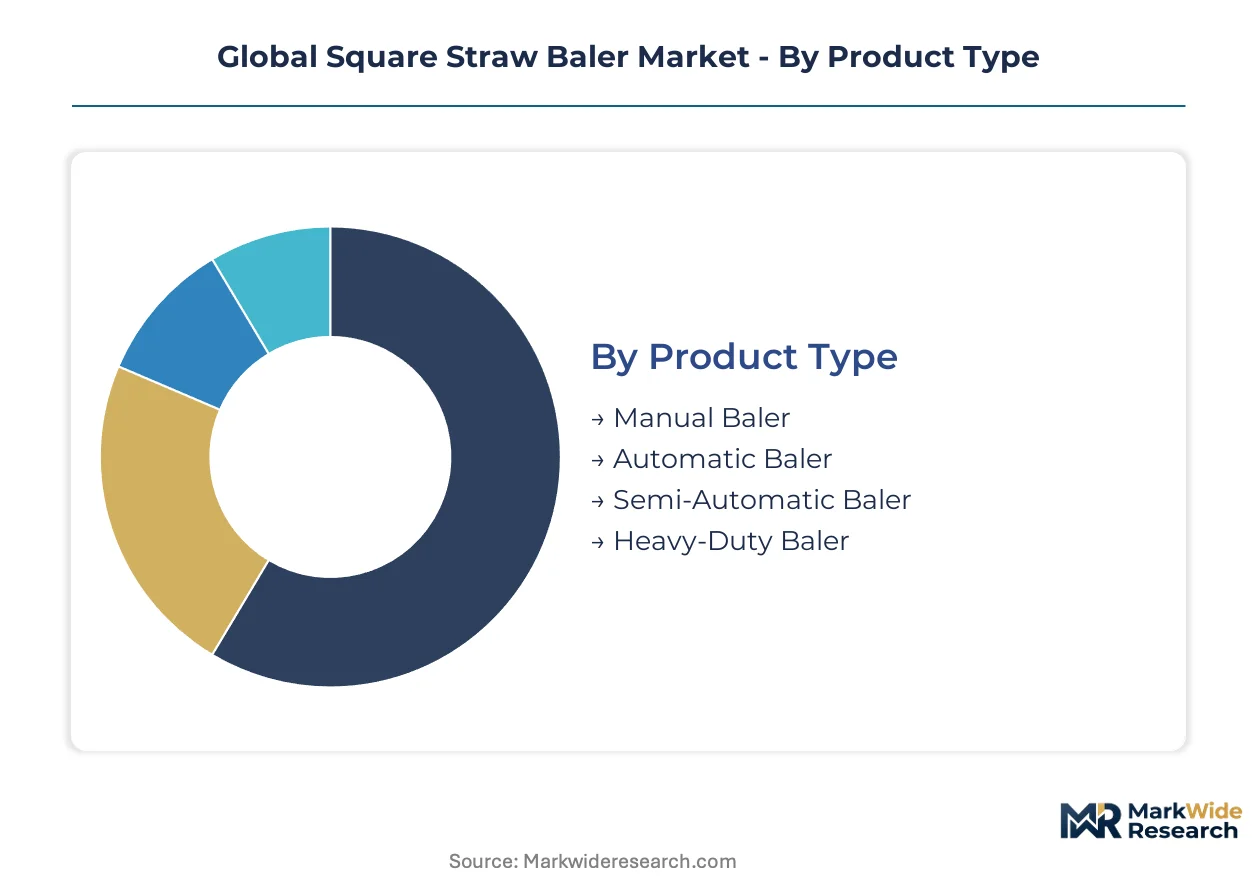
Product Type:
Substitution pressure from densified pellet fuels and industrial composting systems hits manual and semi-automatic balers hardest, while automatic and heavy-duty architectures defend position through throughput advantages and financing integration.
- Automatic Baler:Plunger-driven compression chambers with continuous feed systems achieve densities exceeding 180 kg per cubic meter for containerized shipping efficiency. Demand concentrates across Nebraska and Kansas hay export corridors where compressed harvest windows amplify downtime costs.
- Heavy-Duty Baler:Reinforced frames and extended-duty cycle components withstand 16-hour daily operation across contractor fleets. Alberta and Saskatchewan operations prioritize these units where labor scarcity magnifies equipment reliability premiums.
- Manual Baler:Basic compression systems requiring direct operator control suit smallholder operations with limited capital access.
- Semi-Automatic Baler:Hybrid feed mechanisms bridge manual loading with automated tying functions for mid-scale livestock bedding suppliers.
Automatic balers anchor the volume base while heavy-duty balers gain share at the steepest rate.
End User:
Cost tier stratification separates capital-rich export contractors from price-constrained smallholders, with composting facilities emerging as a distinct procurement segment driven by organic waste mandates rather than traditional agricultural economics.
- Contractors:Fleet operators running multiple units across extended harvest windows demand telematics integration and guaranteed uptime contracts. These buyers concentrate in the US Great Plains where hay export volumes justify premium equipment specifications and predictive maintenance subscriptions.
- Composting Facilities:Industrial-scale straw intake for aerobic digestion and windrow processing requires contamination-resistant baling systems. California, Oregon, and Washington procurement surges as organic waste diversion mandates tighten feedstock supply chains.
- Agricultural Enterprises:Large integrated operations with captive hay production balance ownership against outcome-based utilization contracts.
- Farmers:Owner-operators with seasonal baling needs face Tier 4 Final cost inflation that prices new equipment beyond reach.
Contractors dominate absolute unit demand while composting facilities expand most quickly as a customer category.
Technology:
Application requirements for certified organic supply chains and REACH chemical restrictions are accelerating electric drivetrain penetration, though hydraulic architectures retain installed base dominance through technician familiarity and parts availability.
- Hydraulic:Mineral oil-based compression systems with century-long field provenance retain the largest installed base. EPA Tier 4 Final compliance inflates base costs 12-18% for diesel-hydraulic configurations, compressing margins for smaller hay operations.
- Electric:Brushless motor systems paired with lithium-ion powerpacks eliminate hydraulic fluid contamination risks in organic-certified supply chains. German and Danish OEMs are accelerating modular platform development ahead of REACH reformulation deadlines.
- Pneumatic:Compressed air actuation suits specialized low-density bedding applications with limited powertrain complexity.
- Mechanical:Direct-drive PTO systems persist in emerging markets with simplified maintenance requirements and minimal electronics.
Hydraulic technology anchors the installed base while electric architectures climb the fastest on new order books.
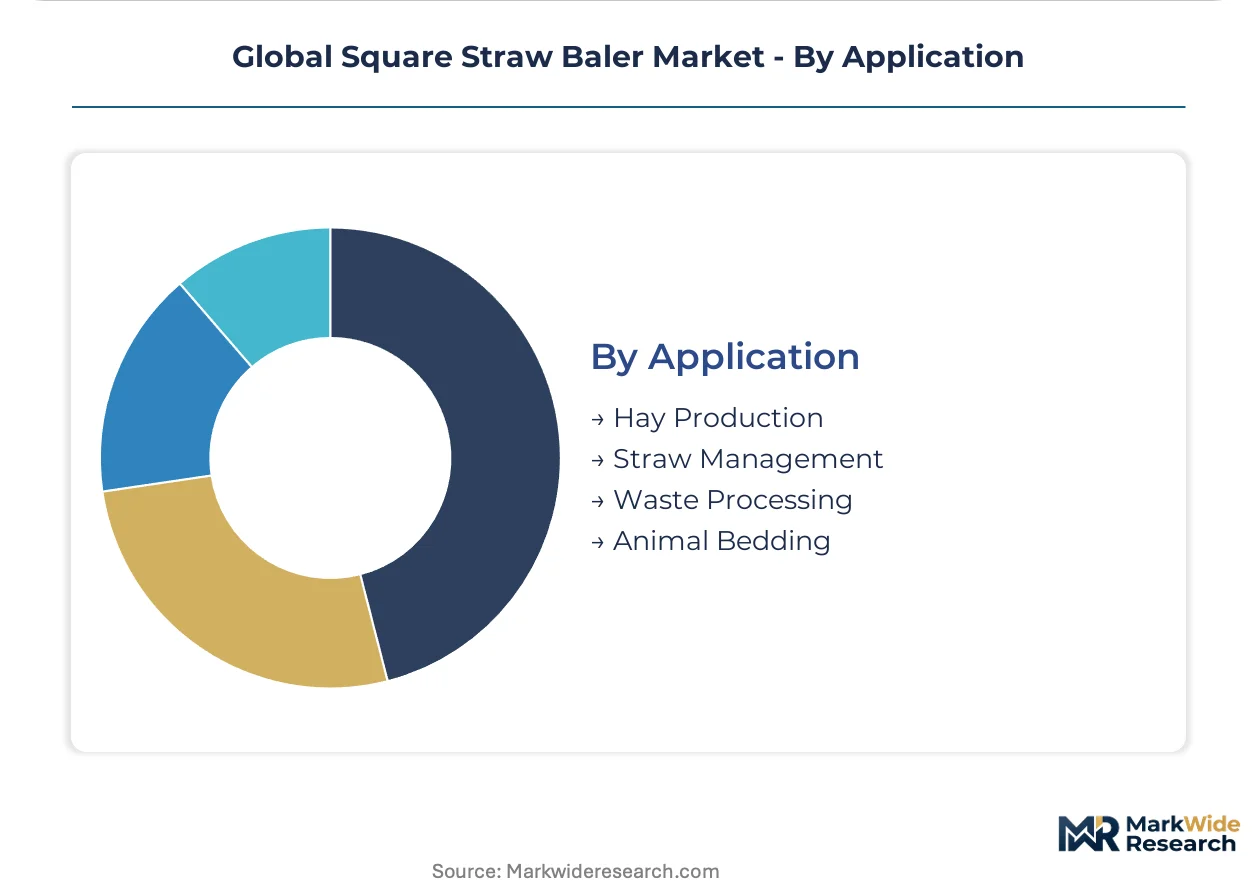
Application:
Geographic concentration of end-use demand shapes equipment specification patterns, with hay production and straw management pulling divergent density and contamination requirements.
- Hay Production:Premium export-grade operations demand automatic baling systems with consistent bale dimensions for containerized shipping. US Great Plains contractors specify high-density configurations exceeding 180 kg per cubic meter to maximize ocean freight economics.
- Straw Management:Post-harvest biomass collection for cogeneration feedstock opens application verticals beyond traditional hay markets. Brazilian sugarcane operations and Scandinavian district heating networks pull straw recovery systems into industrial energy supply chains.
- Waste Processing:Municipal and agricultural residue diversion into composting and anaerobic digestion requires contamination-tolerant baling architectures.
- Animal Bedding:Livestock comfort specifications drive lower-density bale production with absorbency prioritization over transport efficiency.
Hay production anchors the revenue base while straw management applications for bioenergy show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States Great Plains while European OEMs absorb REACH compliance premiums that compress margins. German and Danish manufacturers face 8-12% cost inflation from hydraulic fluid reformulation deadlines. Indian and Brazilian markets present volume expansion vectors through mechanization subsidies and biomass recovery mandates.
United States
Nebraska and Kansas hay export corridors drive automatic baler specifications exceeding 180 kg per cubic meter for containerized shipping efficiency. EPA Tier 4 Final standards inflate diesel-hydraulic base costs 12-18%, pricing smaller operations out of new equipment markets. Alberta and Saskatchewan contractor fleets prioritize heavy-duty architectures where labor scarcity magnifies reliability premiums.
Germany
EU Green Deal farm mechanization subsidies redirect capital toward electric-drive baler architectures in precision hay operations. REACH chemical restrictions on hydraulic fluid formulations compel reformulation or complete architecture abandonment for export-bound production. Baden-Württemberg and Lower Saxony industrial clusters accelerate modular electric platform development ahead of compliance deadlines.
India
The PLI scheme for farm equipment and fragmented smallholder consolidation create white space for compact automatic baler penetration across Punjab and Haryana mechanization corridors. Central government agricultural mechanization subsidies lower capital barriers for owner-operators transitioning from manual systems. Maharashtra and Gujarat processing cooperatives pilot contamination-resistant baling for industrial composting feedstock.
Brazil
Post-harvest sugarcane straw recovery mandates for cogeneration feedstock open new application verticals beyond traditional hay markets in São Paulo and Minas Gerais bioenergy zones. ANVISA agricultural equipment certification requirements shape guard design and operator interface specifications for domestic production. Paraná and Rio Grande do Sul contractor fleets absorb residual value risk through fleet management intermediaries.
China
Yangtze River Delta and Shandong Peninsula agricultural machinery clusters supply compact baler architectures for domestic straw management and export markets. MIIT farm equipment standardization programs align domestic production with ISO 12100 machinery safety requirements. Dual carbon goals accelerate electric drivetrain pilot programs in Jiangsu and Zhejiang demonstration counties.
Global Square Straw Baler Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision agriculture specialists commanding premium pricing while scale manufacturers defend volume positions. The vendor base stratifies across three tiers: integrated agricultural equipment conglomerates with captive distribution networks, regional specialists in hay export-grade specifications, and emerging Asian fabricators serving price-constrained smallholder markets. Dominant competitive moves include telematics-integrated service contract bundling and backward integration into high-grade steel and precision hydraulic cylinder supply.
Within the integrated equipment conglomerate tier, Deere & Company and CNH Industrial NV exemplify archetypes that leverage dealer network density to sustain aftermarket revenue streams. AGCO Corporation occupies a position representing North American and European manufacturing footprints with diversified crop equipment portfolios. Among precision baling specialists, Kuhn SAS and CLAAS KGaA mbH exemplify European-origin manufacturers serving premium hay export grades through advanced compression chamber engineering.
| Leading Market Players |
|---|
| AGCO Corporation |
| Maschinenfabrik Bernard Krone GmbH |
| Deere & Company |
| Kuhn SAS |
| Kubota Corporation |
| CLAAS KGaA mbH |
| Vermeer Corporation |
| Mahindra & Mahindra Limited |
| CNH Industrial NV |
| Others |
Value Chain & Pricing Dynamics
Electric drivetrain substitution for hydraulic architectures is redrawing supply geography toward German and Danish manufacturing clusters while compressing pricing premiums for fluid-free certification tiers. Tier 4 Final after-treatment integration inflates diesel-hydraulic base configurations, forcing price divergence between emissions-compliant and legacy equipment pools.
Pricing Analysis
Nebraska and Kansas hay export corridors command 15-20% premiums over domestic livestock bedding markets due to density specifications exceeding 180 kg per cubic meter. Three-tier pricing structure across premium automatic, standard semi-automatic, and economy manual levels separates contractors from smallholders. Pricing pressure stems from steel and hydraulic component volatility compressing OEM margins. Farmers face acute price sensitivity as Tier 4 Final compliance costs price new equipment beyond seasonal revenue capture.
Supply Chain Analysis
Strategic stockpiling of high-grade steel and precision hydraulic cylinders dominates procurement behavior among German, Chinese, and US manufacturers facing input volatility. Component sourcing draws from Baden-Württemberg forging clusters, Yangtze River Delta machining centers, and Midwest steel distributors. Single-source vulnerability concentrates in specialized plunger alloy formulations. Distribution runs through captive dealer networks for integrated OEMs and independent agricultural equipment distributors for regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Square Straw Baler Market is entering a cyclical upswing as replacement demand from aging contractor fleets intersects with EU Green Deal subsidy windows and REACH compliance deadlines.
For Market Incumbents: Secure technician training pipelines through partnerships with automotive vocational programs to offset hydraulic and electric drivetrain specialist scarcity. Deepen backward integration into high-grade steel supply to defend margin position against commodity volatility. Channel control investments in Alberta and Saskatchewan contractor segments protect aftermarket revenue from fleet management intermediaries.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission opens European electric-drive penetration ahead of REACH reformulation deadlines. Target Indian Punjab and Haryana mechanization corridors where PLI scheme subsidies lower capital barriers for compact automatic baler adoption. Telematics-integrated service contracts offer differentiation against established dealer networks.
For Investors and Strategic Acquirers: Capital is best deployed toward precision baling specialists with modular electric platforms and established organic certification relationships. Long-term viability hinges on technology transition execution rather than volume scale. Watch Brazilian sugarcane straw recovery mandate implementation as inflection indicator for bioenergy application verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydraulic-to-Electric Platform Transition | REACH chemical restrictions in Germany and Denmark accelerate architecture abandonment timelines. |
| Telematics-Integrated Service Contracts | Predictive maintenance platforms capture aftermarket revenue from risk-averse North American contractor fleets. |
| Technician Training Pipeline Development | Partnerships with automotive vocational programs address collapsing hydraulic specialist availability across US Midwest. |
| Backward Integration into Steel Supply | In-house production of high-grade components insulates margins from commodity volatility. |
| Composting Facility Application Development | Contamination-resistant baling architectures capture California and Washington organic waste diversion procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hay export contractors, composting facility procurement managers, OEM aftermarket service heads, and agricultural equipment dealership principals. Secondary validation drew from EPA Tier 4 Final filings, EU Green Deal subsidy disbursement records, REACH chemical restriction notices, and customs trade data for baler component flows. Bottom-up equipment shipment tallies and top-down agricultural mechanization spending estimates were triangulated to anchor volume projections.
Across the analysis window, the forecasting framework modeled product type specifications, technology architecture transitions, end-user cost tier stratification, and geographic regulatory cluster divergence. CAGRs were derived from replacement cycle compression rates and subsidy-driven procurement acceleration patterns. Industry-specific inputs included hydraulic fluid price indices, certified organic hay premium spreads, and sugarcane straw recovery mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU subsidy execution and stable steel input costs; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions regarding emissions compliance timeline adherence and technician training pipeline development. Revision becomes warranted when REACH reformulation deadlines or Tier 4 Final enforcement intensity crosses threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market