
 Grow Tents Market | 2026-2036
Grow Tents Market Size, Share, and Industry Trends Forecast 2026-2036
Grow Tents Market Foresight
Horticultural engineering talent scarcity is redrawing competitive boundaries in the grow tents sector. Mars Hydro leverages in-house LED climate system integration to sustain pricing power across North American channels. Gorilla Grow Tent anchors premium positioning through thicker canvas construction and reinforced pole architecture. Vivosun competes aggressively on volume, extending its SKU breadth to capture entry-level and mid-tier buyers simultaneously.
Grow tents are enclosed fabric structures, typically fabricated from Oxford canvas with Mylar interior lining and powder-coated steel frames, engineered to create light-tight, climate-controlled microenvironments for plant cultivation. Their primary commercial purpose is to maximize photon delivery efficiency while containing odor, humidity, and thermal loads in indoor agricultural settings. Indoor grow tents dominate revenue contribution due to year-round operational utility across hydroponics and soil cultivation applications, where the segment captures the bulk of margin pools from commercial operators. Reflective tents represent the fastest-expanding material sub-category as cultivators prioritize photon redistribution efficiency to optimize fixture density and energy economics.
The EPA regulates volatile organic compound emissions from adhesives and coatings used in tent manufacturing, while OSHA workplace safety standards govern electrical component integration for climate control accessories. The EU REACH framework restricts certain phthalates and flame retardants in textile treatments, compelling European suppliers to reformulate material specifications or source alternative chemistries. Stakeholders must monitor evolving state-level energy efficiency mandates and building code interpretations that could reclassify tent-based cultivation as permanent agricultural infrastructure rather than temporary equipment.
Market Dynamics
Controlled environment agriculture is fragmenting traditional outdoor cultivation economics as energy-intensive climate systems reshape capital deployment patterns across indoor farming operations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating adoption of low-emission climate control systems integrated into grow tent architectures.
- State-level cannabis legalization:Expanding licensed cultivation frameworks in the United States are broadening the addressable base for commercial-grade tent installations.
- Reflective Mylar lining:Advanced photon redistribution materials are improving fixture density economics and reducing energy consumption per square meter of canopy.
Market Restraints
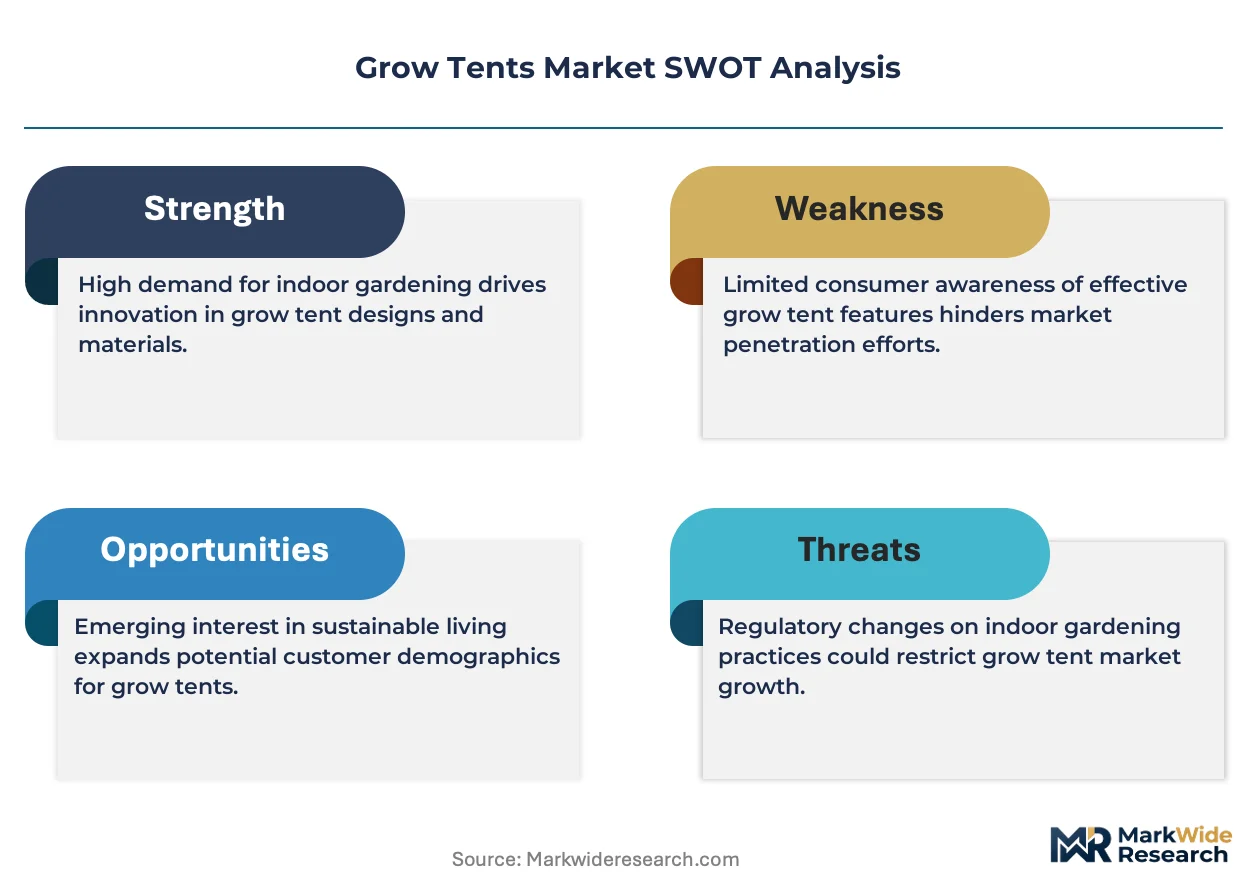
- Oxford canvas input volatility:Petroleum-derived synthetic textile feedstocks expose manufacturers to crude oil price swings and supply rationing.
- Chinese pole and frame concentration:Powder-coated steel component sourcing clusters heavily in East Asian manufacturing basins, creating single-point vulnerability.
- REACH compliance friction:The EU framework's restrictions on phthalates and flame retardants force reformulation cycles that extend product development timelines.
Strategic Opportunities
- German commercial hydroponics:Controlled environment agriculture adoption in Central European markets remains underpenetrated relative to North American intensity.
- Smart controller convergence:Integration of IoT sensors with LED drivers and HVAC systems creates premium pricing tiers for connected cultivation environments.
- Direct-to-cultivator e-commerce:Bypassing traditional horticultural distribution channels captures margin and builds proprietary customer data assets.
Industry Challenges
- Horticultural engineering talent scarcity:The specialized knowledge required for climate system integration and photon mapping outstrips available workforce supply.
- OSHA electrical compliance complexity:Climate control accessory integration must satisfy workplace safety standards governing wet-environment electrical installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grow Tents Market |
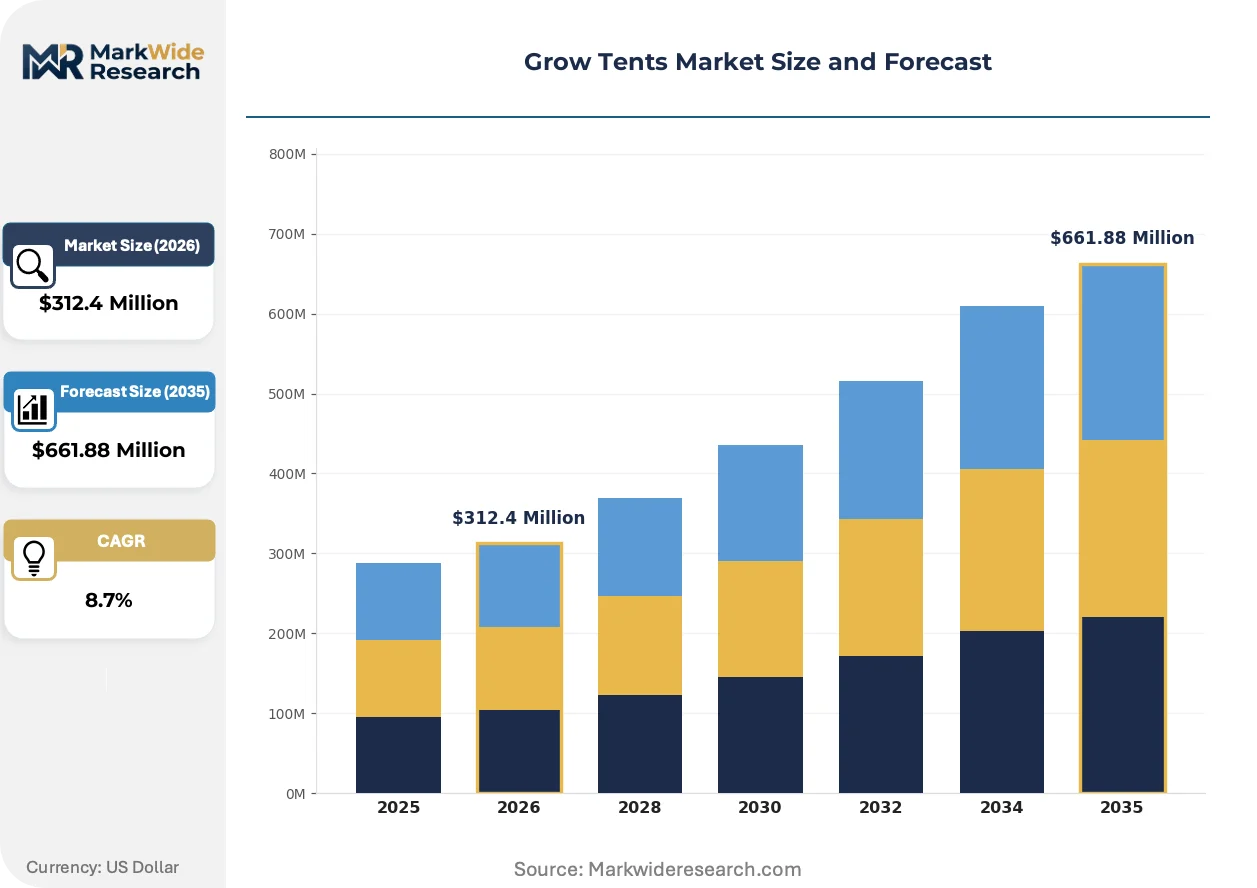
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Indoor Grow Tents, Outdoor Grow Tents, Propagation Tents, Reflective Tents Material: Canvas, Mylar, Nylon, PE Size: Small, Medium, Large, Extra Large Application: Hydroponics, Soil Cultivation, Seed Germination, Plant Propagation |
| Companies Covered | CoolGrows, Mars Hydro, Gorilla Grow Tent, Opulent Systems, Apollo Horticulture, Vivosun, iPower, Quictent, AC Infinity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grow Tents Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are forcing simultaneous innovation across fabric treatments, frame alloys, and climate system interfaces.
Quantum board LED architectures are fragmenting the legacy high-pressure sodium fixture base as commercial operators pursue spectrum-tunable photon delivery. Mid-scale hydroponic facilities in Colorado and California are retrofitting tents with these systems to optimize cannabinoid production profiles. The technology is fragmenting equipment vendor relationships as cultivators source lighting separately from tent packages.
The EU F-Gas Regulation is compressing refrigerant choices for integrated cooling systems, compelling manufacturers to redesign heat exchange architectures around natural working fluids. Tent suppliers serving European markets must now certify climate accessories for lower global warming potential chemistries. German and Dutch commercial operators face the steepest retrofit obligations under national implementation timelines.
Buyers are unbundling tent and climate system procurement, treating the fabric enclosure as a commodity input while investing premium capital in controllable environment technology. This pattern compresses margin capture for canvas and frame suppliers while elevating pricing power for integrated system vendors. The behavior is most pronounced among United States multi-state operators standardizing facility designs across jurisdictions.
Grow Tents Market Segmentation
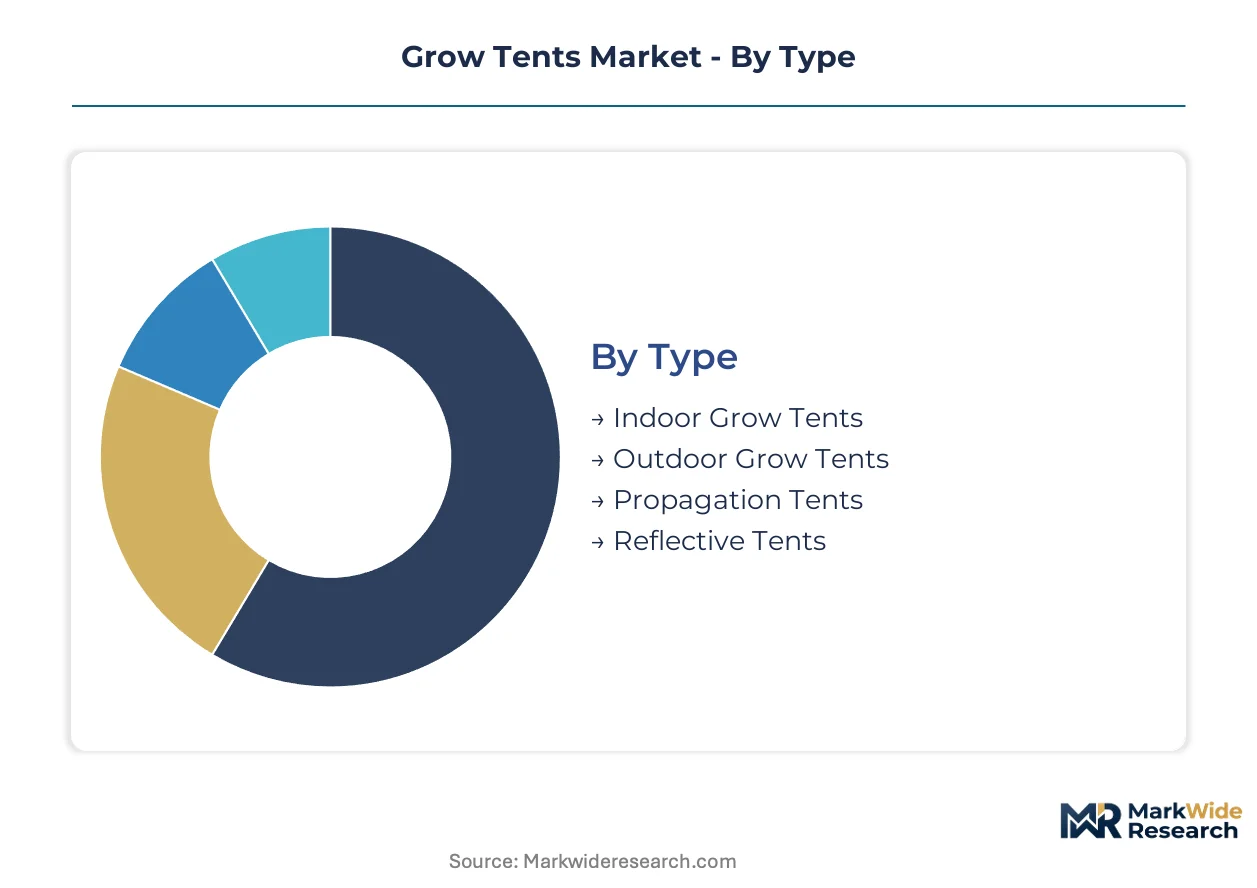
Segmentation in the grow tents market reveals divergent channel strategies. Commercial hydroponic operators source large-format indoor units through direct vendor relationships, while hobbyist cultivators purchase smaller propagation tents via e-commerce platforms.
Type:
Channel concentration varies sharply by enclosure format. Indoor and reflective variants flow through specialized horticultural distributors, while propagation and outdoor models reach consumers through mass-market retail and online marketplaces.
- Indoor Grow Tents:Oxford canvas structures with Mylar interior lining and powder-coated steel frames engineered for year-round climate control. Commercial operators in Colorado and California deploy these for licensed cannabis cultivation, driving specification requirements for thicker pole gauges and reinforced corner joints.
- Reflective Tents:Advanced photon redistribution enclosures utilizing diamond-pattern Mylar or white PE films to maximize fixture efficiency. German commercial hydroponic facilities are retrofitting with these systems to reduce energy consumption per square meter of canopy under EU efficiency mandates.
- Propagation Tents:Compact enclosures designed for seedling and clone development with integrated humidity domes. Entry-level buyers in United States state-legal markets purchase these through Amazon and direct-to-consumer channels.
- Outdoor Grow Tents:Weather-resistant structures with UV-stabilized fabrics for seasonal cultivation. Limited commercial adoption restricts these to hobbyist gardeners in temperate climate zones.
By volume, Indoor Grow Tents leads. By growth pace, Reflective Tents is expanding most quickly.
Material:
Cost tier stratification separates premium fabric treatments from commodity inputs. High-performance Mylar and specialized canvas formulations command pricing premiums, while nylon and PE serve price-sensitive segments.
- Canvas:Heavy-duty Oxford weave polyester with polyurethane coating provides structural durability and light-tight sealing. Commercial-grade specifications in the United States require 600D or 1680D denier ratings to satisfy multi-cycle deployment demands.
- Mylar:Metallized polyester film delivering 95-98% reflectivity for photon redistribution. European suppliers reformulate adhesive bonding agents to comply with REACH phthalate restrictions, extending development timelines.
- Nylon:Lightweight synthetic alternative for portable and budget-tier enclosures. Limited thermal stability constrains deployment in high-temperature LED environments.
- PE:Polyethylene sheeting for entry-level and temporary installations. Chinese manufacturers dominate supply, creating single-point vulnerability for Western distributors.
By revenue contribution, Canvas dominates. By specification intensity, Mylar commands the steepest premium tier.
Size:
Customer type and application scale determine format selection. Small and medium units serve residential and research applications, while large and extra-large configurations address commercial canopy requirements.
- Large:Multi-fixture enclosures accommodating 1000W+ LED arrays or high-pressure sodium systems for commercial production. Multi-state operators in the United States standardize on 10x10 and 10x20 foot formats for facility replication.
- Extra Large:Custom-configured modular systems for warehouse-scale installations. California cultivation facilities deploy these with integrated HVAC and irrigation infrastructure.
- Medium:Versatile formats for serious hobbyists and small commercial trials. Colorado caregiver provisions drive steady demand in state-legal frameworks.
- Small:Compact units for seed germination and restricted-space cultivation. E-commerce channels capture margin through accessory bundling with LED panels and carbon filters.
By installation base, Medium leads. By margin per square meter, Extra Large generates the highest returns.
Application:
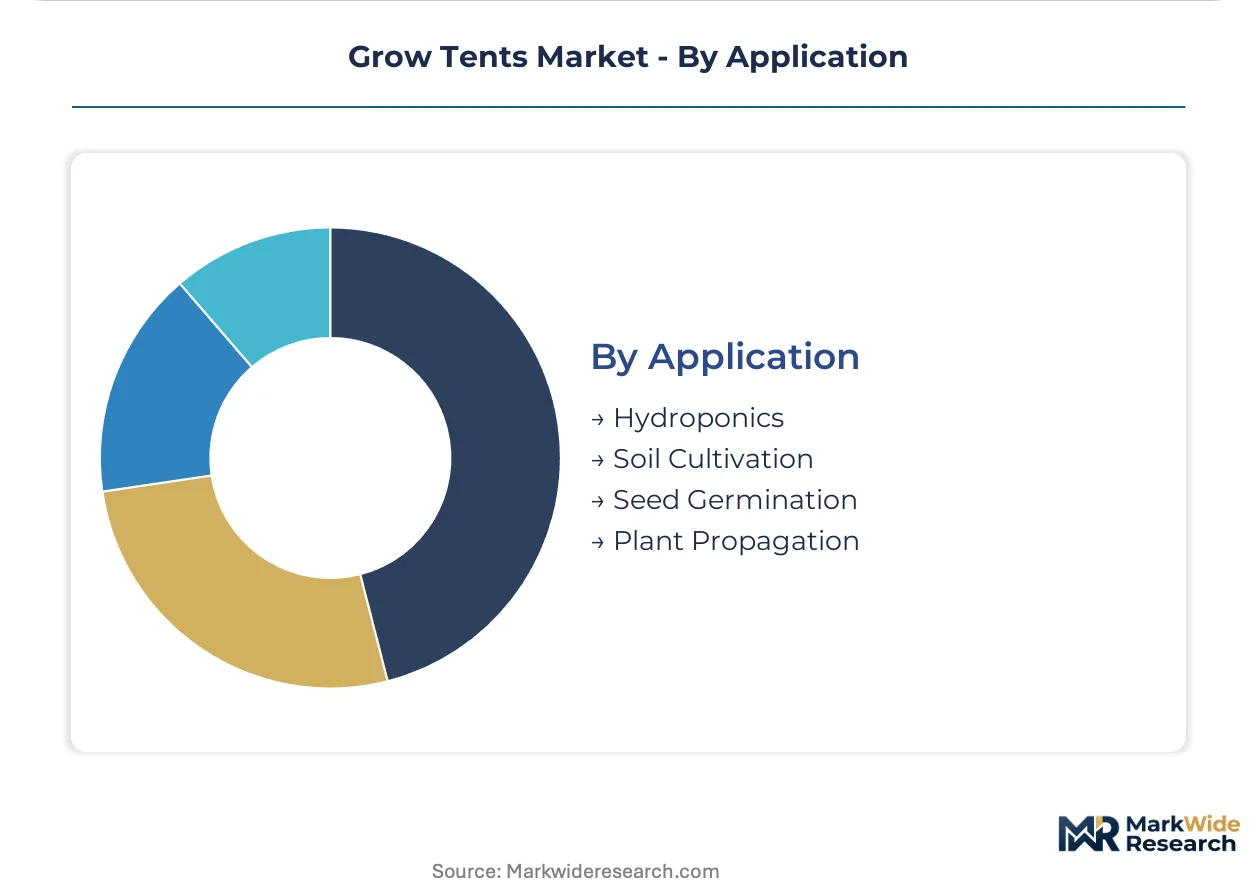
Maturity gradients separate established cultivation methods from emerging techniques. Hydroponics and soil cultivation represent deployed base, while propagation applications show technology refresh intensity.
- Hydroponics:Soilless cultivation systems requiring precise environmental control for nutrient film technique, deep water culture, or aeroponic methods. Dutch and German commercial operators are expanding adoption as controlled environment agriculture gains regulatory support.
- Soil Cultivation:Traditional substrate-based growing with organic or synthetic amendments. United States craft cannabis producers favor these methods for terpene profile differentiation.
- Seed Germination:Controlled-start environments with humidity and temperature precision. Research institutions and breeding operations specify these for genetic preservation.
- Plant Propagation:Cloning and vegetative staging enclosures with spectral tuning for root development. LED quantum board retrofits are fragmenting equipment vendor relationships as cultivators source lighting separately.
By revenue concentration, Hydroponics captures the dominant share. By technology refresh rate, Plant Propagation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety standards govern electrical component integration for climate control accessories in the United States, where state-level cannabis legalization frameworks continue broadening the addressable base for commercial-grade tent installations.
United States
Multi-state operators in Colorado and California deploy large-format indoor units for licensed cannabis cultivation, driving specification requirements for thicker pole gauges. The EPA regulates volatile organic compound emissions from adhesives and coatings used in tent manufacturing. Denver and Oakland cultivation facilities are retrofitting tents with quantum board LED architectures to optimize cannabinoid production profiles.
Germany
Commercial hydroponic facilities in Central European markets are expanding adoption as controlled environment agriculture gains regulatory support. The EU F-Gas Regulation is compressing refrigerant choices for integrated cooling systems, compelling manufacturers to redesign heat exchange architectures. Dutch and German commercial operators face the steepest retrofit obligations under national implementation timelines for lower global warming potential chemistries.
Canada
Health Canada oversees licensing frameworks for cannabis cultivation that shape demand for controlled environment equipment. Provincial energy efficiency mandates in British Columbia and Ontario influence specification requirements for climate control integration. Toronto and Vancouver metropolitan areas concentrate commercial operator activity, with facilities standardizing on modular tent configurations for facility replication.
China
Manufacturing clusters in East Asian basins dominate powder-coated steel component sourcing for frame and pole production. GB standards govern product safety and material specifications for domestic market supply. Zhejiang and Guangdong provinces concentrate textile treatment and metal fabrication capacity, creating single-point vulnerability for Western distributors dependent on these supply chains.
United Kingdom
Urban agriculture initiatives in London and Birmingham are stimulating demand for compact propagation tents among hobbyist cultivators. The UK operates under EU REACH framework restrictions on phthalates and flame retardants in textile treatments, compelling suppliers to reformulate material specifications. Manchester and Bristol research institutions specify controlled-start environments for genetic preservation applications.
Grow Tents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the grow tents sector. The vendor base separates into three strategic tiers: integrated system vendors commanding premium positioning through LED climate system bundling, canvas specialists defending share through reinforced construction specifications, and volume-oriented suppliers capturing entry-level and mid-tier buyers through SKU breadth expansion. Dominant competitive moves include backward integration into component manufacturing and direct-to-cultivator e-commerce channel development.
Among North American fabricators, Gorilla Grow Tent and Mars Hydro occupy positions on the premium-tier vector, exemplifying archetypes that anchor pricing power through differentiated construction or integrated system offerings. Vivosun sits within the scale-driven end, representing the volume-competitive archetype that extends SKU breadth to capture simultaneous segment penetration. These three company profiles illustrate the structural segmentation between specification intensity and accessibility pricing across distribution channels.
| Leading Market Players |
|---|
| CoolGrows |
| Mars Hydro |
| Gorilla Grow Tent |
| Opulent Systems |
| Apollo Horticulture |
| Vivosun |
| iPower |
| Quictent |
| AC Infinity |
| Others |
Supply & Pricing Matrix
East Asian powder-coated steel capacity utilization above 85 percent concentrates frame and pole sourcing in Zhejiang and Guangdong provinces, creating scale-driven cost floors that Western distributors cannot match through domestic fabrication. This concentration compresses margin capture for canvas specialists while elevating pricing power for integrated system vendors bundling LED climate control.
Pricing Analysis
North American commercial operators pay 40-60 percent premiums over European hobbyist channels for identical canvas specifications. Three-tier pricing structure across premium, standard, and economy levels differentiates by pole gauge thickness and Mylar reflectivity grade. Cost compression in entry-tier nylon enclosures is intensifying because Chinese manufacturers are absorbing petroleum feedstock volatility to maintain volume share. Multi-state operators show lowest price sensitivity; Amazon-sourced hobbyists exhibit highest.
Supply Chain Analysis
Inventory cycles for Oxford canvas extend 90-120 days as petroleum-derived textile feedstocks face rationing during crude price spikes. Manufacturing draws from China for powder-coated steel frames, Taiwan for LED driver components, and India for specialized textile treatments. Single-source vulnerability concentrates in Zhejiang metal fabrication basins subject to environmental compliance shutdowns. Distribution runs through horticultural distributors for commercial tiers and direct-to-consumer e-commerce for hobbyist segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horticultural engineering talent scarcity constrains climate system integration capabilities across vendor tiers, with photon mapping and HVAC control expertise particularly under-supplied relative to commercial operator demand. This capability gap separates integrated system vendors from commodity canvas suppliers.
For Market Incumbents: Shield premium positioning through captive LED driver production and in-house climate controller firmware development. Quantum board LED retrofits by cultivators threaten bundled equipment relationships; backward integration into semiconductor sourcing secures component availability during Taiwan supply crunches. Certification investment for EU F-Gas compliant heat exchange architectures defends European channel access against REACH-compliant European entrants. For New Entrants and Emerging Players: Direct-to-cultivator data analytics services represent the most penetrable white-space as incumbents under-serve yield optimization intelligence. German commercial hydroponic facilities lack standardized facility management platforms; cloud-based environmental logging with predictive failure alerts captures this segment. Go-to-market through cultivation consulting relationships bypasses entrenched horticultural distributor gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled climate controller vendors with subscription-based remote monitoring tiers. Long-term viability favors platform archetypes integrating hardware enclosure sales with consumable nutrient and media replenishment. Acquisition targets should demonstrate installed base density in state-legal United States markets with sticky cultivation management software attachment. Watch for OSHA electrical safety enforcement intensification as inflection signal favoring UL-listed system vendors over unbranded imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver Production | Captive semiconductor sourcing insulates margins from Taiwan supply crunches affecting quantum board availability. |
| EU F-Gas Compliance Certification | Heat exchange architecture redesign secures German and Dutch commercial operator retrofit obligations under REACH. |
| Direct-to-Cultivator E-Commerce Platform | Proprietary yield data assets from Amazon-bypassing channels enable predictive nutrient replenishment subscription revenue. |
| IoT Sensor Integration with HVAC Systems | Connected environment premium pricing captures multi-state operator standardization demands across Colorado and California. |
| Horticultural Engineering Talent Acquisition | Photon mapping expertise scarcity creates defensive moat against commodity canvas competitors in commercial segments. |
Research Methodology
A standing panel of commercial cultivation facility managers, LED fixture procurement leads, and climate control system integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA VOC emission filings, EU ECHA REACH substance restriction updates, and OSHA electrical safety interpretation letters. Customs records for Oxford canvas and powder-coated steel frame imports, alongside horticultural distributor inventory disclosures, anchored bottom-up demand estimation. Top-down triangulation against controlled environment agriculture capital expenditure surveys ensured segmentation coherence.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled enclosure type, material specification intensity, customer scale tier, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from fitted growth curves incorporating state-level cannabis licensing velocity, EU F-Gas implementation timelines, and LED fixture replacement cycle data. Industry-specific inputs included commercial operator facility replication patterns and hobbyist channel e-commerce conversion rates.
Forecasts assume regulatory continuity in United States state-level cannabis frameworks and EU REACH phthalate restriction regimes; material policy shifts would require re-modeling. Petroleum feedstock price volatility and Chinese environmental compliance enforcement represent specific revision risks for canvas and frame supply assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Aeroponics Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
GCC Grow Light Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Quantum Board Grow Light Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Plant Growth Chambers Market