
 Global Acute Hospital Care Market | 2026-2036
Global Acute Hospital Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Hospital Care Market Foresight
Software-defined care coordination is restructuring how acute hospitals package and monetize clinical workflows. HCA Healthcare leverages its scale across nearly 200 hospitals to standardize electronic health record integration and command favorable payer contracts. Fresenius SE & Co. KGaA anchors its position through captive dialysis-to-hospital referral networks and specialized critical care equipment supply. Mayo Clinic differentiates via destination-complex-care branding that draws interstate and international patient flows.
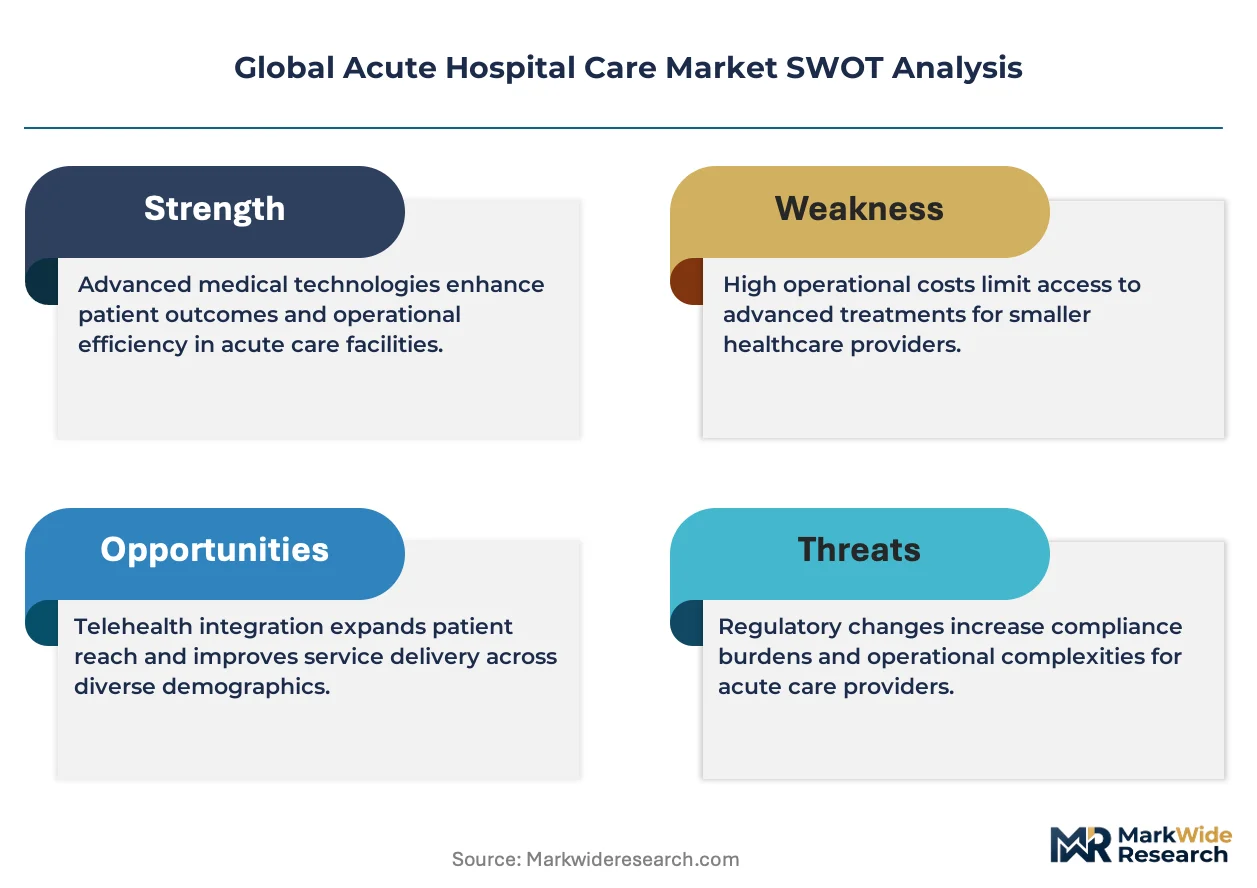
Acute hospital care encompasses time-sensitive diagnosis, intervention, and stabilization delivered in inpatient settings with 24-hour physician coverage, operating suites, and intensive monitoring capabilities; facilities must maintain surge capacity for trauma and sepsis response while coordinating discharge to lower-acuity settings. Surgical services generate the dominant revenue pool across most facility ownership structures, particularly within private and academic institutions where high-margin orthopedic and cardiovascular procedures concentrate. Critical care segments face capacity strain from biometric monitoring integration, while telemedicine adoption reshapes emergency triage and observation protocols without eliminating physical bed requirements.
FDA device clearance pathways and CMS reimbursement rules shape capital allocation toward robotic surgery and minimally invasive platforms in US facilities, while EMA medical device regulation and EU AI Act compliance requirements filter technology procurement across European systems. WHO emergency care standards and ISO 15189 laboratory accreditation further constrain market access for non-compliant operators. Stakeholders must weigh regulatory divergence against platform standardization as they allocate R&D budgets and expansion capital across jurisdictions.
Market Dynamics
Value-based reimbursement frameworks are redirecting capital flows across acute hospital systems, forcing facility operators to restructure revenue models around episode-of-care outcomes rather than fee-for-service throughput. CMS bundled payment mandates and similar mechanisms in Germany and Japan are compressing margins while rewarding integrated care networks.
Growth Catalysts
- CMS bundled payment expansion:Medicare's mandatory joint replacement and cardiac bundles in the United States accelerate investment in care coordination infrastructure and post-acute partnerships.
- Minimally invasive surgical platforms:Robotic-assisted systems reduce length-of-stay metrics that determine value-based contract performance, driving capital allocation toward da Vinci and competing platforms.
- Geriatric admission concentration:Japan's super-aged population and Germany's demographic compression generate sustained demand for complex cardiac and orthopedic intervention capacity.
Market Restraints
- Specialized nursing labor scarcity:Critical care and operating room nurse shortages in the United States and United Kingdom constrain bed utilization rates regardless of physical capacity.
- Medical device supply concentration:Dialysis equipment and cardiac stent manufacturing clusters in Ireland and Switzerland create vulnerability to single-source disruption.
- EU AI Act compliance burden:European acute hospitals face 18-24 month validation timelines for diagnostic algorithms, delaying clinical deployment of imaging AI tools.
Strategic Opportunities
- India's tier-2 city hospital networks:Underpenetrated markets in Lucknow, Indore, and Coimbatore offer first-mover positioning for standardized acute care formats.
- Telemedicine-physical hybrid triage:Emergency department observation protocols integrating remote physician consultation reduce unnecessary admissions while preserving revenue capture.
- Japan's regional medical care support function:Government-mandated hub-and-spoke networks create acquisition opportunities for metropolitan systems to consolidate rural general hospitals.
Industry Challenges
- Interoperable EHR implementation:Legacy system fragmentation across HCA, Community Health Systems, and Tenet networks blocks seamless patient data portability required for value-based contracting.
- Biometric monitoring integration complexity:ICU device convergence from GE, Philips, and Medtronic requires middleware development that strains hospital IT budgets and cybersecurity posture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Hospital Care Market |
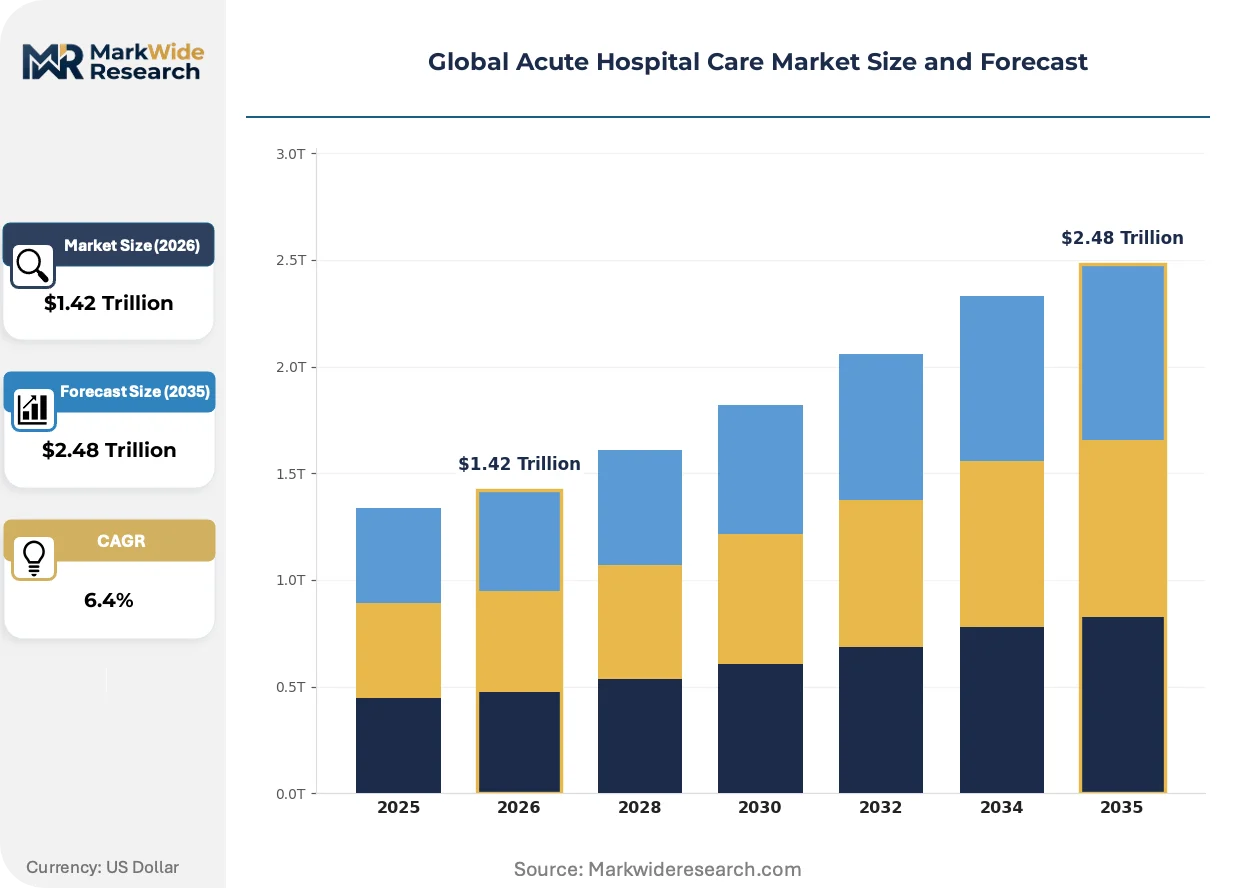
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.48 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Care Service Type: Emergency, Surgical, Critical Care, Trauma, Observation, Palliative Facility Ownership: Public, Private, Charitable Trust, Government-Run, Academic, Community-Based Patient Category: Adult, Pediatric, Geriatric, Maternity, Oncology, Psychiatric Treatment Technology: Telemedicine, Robotic Surgery, Minimally Invasive, Conventional Surgery, Imaging Diagnostics, Biometric Monitoring |
| Companies Covered | HCA Healthcare, Tenet Healthcare, Universal Health Services, Cleveland Clinic, Mayo Clinic, Ascension Health, Community Health Systems, Ramsay Health Care, Fresenius SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Hospital Care Market Shifts & Advancements
Acute hospital operations are converging around predictive analytics and automation layers that compress clinical decision cycles. Three developments are restructuring competitive positioning across inpatient settings.
Artificial intelligence diagnostic tools are absorbing radiologist and pathologist workflow volume in leading academic medical centers. Mayo Clinic and Cleveland Clinic deployments of FDA-cleared algorithms for stroke detection and sepsis prediction are compressing time-to-intervention metrics. This technology is absorbing routine image interpretation tasks while reallocating specialist capacity toward complex case review.
EMA's Medical Device Regulation and EU AI Act combined requirements are forcing European hospital procurement departments to revalidate entire device portfolios. Manufacturers must submit clinical evidence packages that delay new technology adoption by 12-18 months. German university hospitals are responding by concentrating purchasing power through regional consortiums that demand pre-certified product lines.
Self-insured employers and Medicare Advantage plans are contracting directly with hospital systems for bundled surgical episodes, bypassing traditional commercial payer intermediaries. Walmart's Centers of Excellence program and similar arrangements concentrate high-margin orthopedic and cardiac volumes at designated facilities. This channel shift is most visible in the United States where employer healthcare costs exceed 12 percent of payroll.
Global Acute Hospital Care Market Segmentation
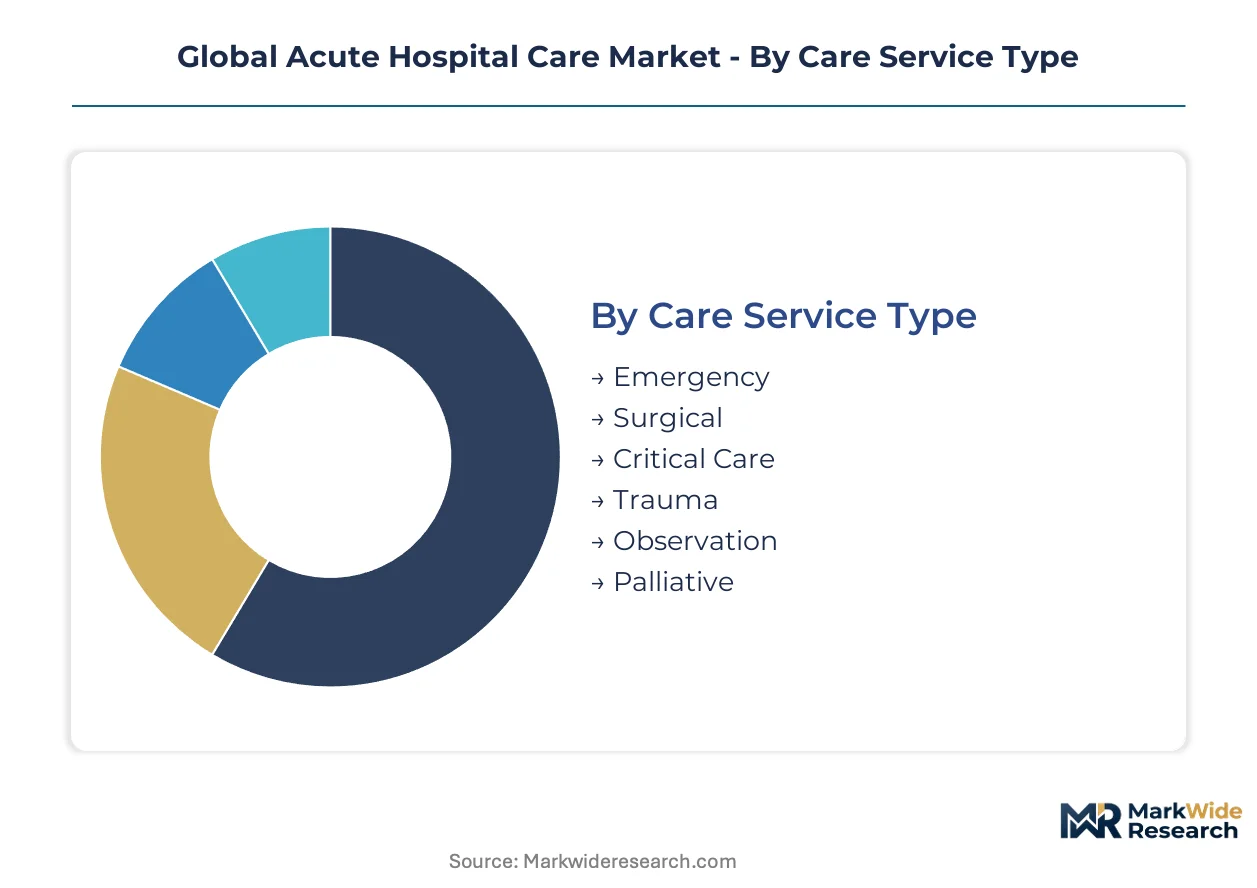
Acute hospital care segmentation reveals how capital allocation and operational priorities diverge across service lines, ownership structures, and patient populations. Understanding these divisions exposes where reimbursement pressure concentrates and where technology investment yields measurable throughput gains.
Care Service Type:
Supply concentration in surgical and critical care services shapes facility-level capital deployment and staffing ratios across health systems.
- Surgical:Inpatient procedures requiring anesthesia support and post-operative recovery infrastructure generate the dominant revenue pool across private and academic institutions. Orthopedic and cardiovascular intervention demand concentrates in the United States, Germany, and Japan where aging demographics strain existing capacity and value-based contracts reward shorter length-of-stay outcomes.
- Critical Care:Intensive care units deliver continuous physiological monitoring and mechanical ventilation support for organ failure and sepsis management. Capacity strain from biometric monitoring integration and specialized nursing labor scarcity constrains bed utilization rates regardless of physical infrastructure investment.
- Emergency:Time-sensitive triage and stabilization services operating 24 hours with trauma-ready surgical backup.
- Trauma:Designated centers maintaining surge capacity for mass casualty events and severe injury response protocols.
- Observation:Short-stay units bridging emergency evaluation and inpatient admission decisions.
- Palliative:Symptom-focused care for patients with serious illness, typically delivered in dedicated units or consultation services.
Surgical services absorb the bulk of installed capacity; critical care is expanding most quickly as biometric monitoring integration and sepsis prediction algorithms drive ICU investment.
Facility Ownership:
Cost tier differentiation between public reimbursement dependence and private capital flexibility determines technology procurement speed and service line breadth.
- Private:Investor-owned and nonprofit hospital systems operate with balance sheet capacity for robotic surgery platforms and electronic health record standardization. HCA Healthcare leverages scale across nearly 200 hospitals to command favorable payer contracts and integrate care coordination infrastructure.
- Academic:University-affiliated medical centers combine research missions with complex tertiary and quaternary referral volumes. Mayo Clinic and Cleveland Clinic deployments of FDA-cleared diagnostic algorithms concentrate in this segment where research budgets subsidize technology validation.
- Public:Government-funded facilities serving safety-net populations with constrained capital budgets and higher uncompensated care burdens.
- Government-Run:Direct state or federal operation, common in military health systems and certain national health service structures.
- Charitable Trust:Mission-driven ownership with endowment support and community benefit obligations.
- Community-Based:Smaller independent hospitals serving localized populations with limited specialty service depth.
Private facilities absorb the bulk of installed capacity; academic medical centers are expanding most quickly as research partnerships and destination-complex-care branding draw interstate and international patient flows.
Patient Category:
Volume concentration in adult and geriatric admissions aligns with disease burden demographics and reimbursement rate structures across developed health systems.
- Geriatric:Patients aged 65 and older present complex comorbidity profiles requiring coordinated cardiac, orthopedic, and neurological intervention. Japan's super-aged population and Germany's demographic compression generate sustained demand for specialized geriatric acute care capacity and post-acute transition management.
- Adult:Working-age patients drive trauma, cardiovascular, and cancer-related admission volumes with higher commercial insurance mix.
- Pediatric:Specialized pediatric hospitals and dedicated units within general facilities manage congenital conditions and childhood injury.
- Maternity:Labor and delivery services with neonatal intensive care backup for high-risk pregnancies.
- Oncology:Cancer-directed therapy including surgical oncology, chemotherapy administration, and stem cell transplant.
- Psychiatric:Inpatient mental health stabilization with varying degrees of medical-surgical integration.
Adult admissions absorb the bulk of installed capacity; geriatric services are expanding most quickly as CMS bundled payment mandates and similar mechanisms in Germany and Japan redirect capital toward outcomes-driven infrastructure for aging populations.
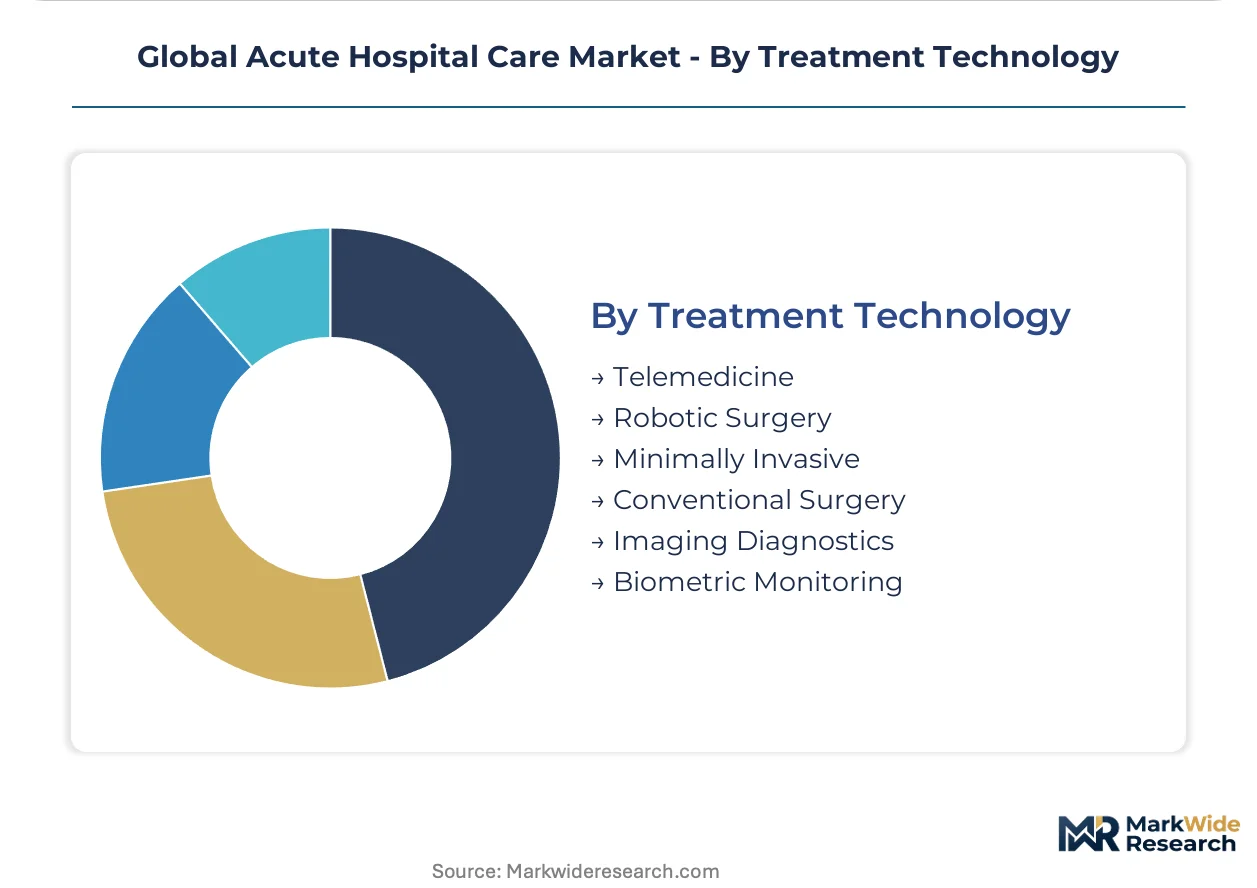
Treatment Technology:
Margin differentiation between capital-intensive robotic platforms and conventional surgical approaches shapes procurement decisions under value-based reimbursement pressure.
- Robotic Surgery:Computer-assisted platforms enabling minimally invasive procedures with enhanced precision and reduced recovery times. FDA device clearance pathways and CMS reimbursement rules shape capital allocation toward da Vinci and competing systems in US facilities.
- Minimally Invasive:Laparoscopic and endoscopic techniques reducing tissue trauma and length-of-stay metrics that determine value-based contract performance.
- Telemedicine:Remote physician consultation integrated into emergency triage and observation protocols. EMA's Medical Device Regulation and EU AI Act compliance requirements filter technology procurement across European systems with 18-24 month validation timelines.
- Imaging Diagnostics:CT, MRI, and interventional radiology services supporting time-sensitive diagnosis.
- Biometric Monitoring:Continuous physiological parameter tracking in ICU and step-down settings.
- Conventional Surgery:Open procedural techniques remaining necessary for certain complex cases and resource-constrained environments.
Conventional surgery absorbs the bulk of installed capacity; robotic platforms are expanding most quickly as self-insured employers and Medicare Advantage plans contract directly with hospital systems for bundled surgical episodes that reward shorter recovery trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility investment concentrates in markets where aging demographics and reimbursement reform create simultaneous pressure on capacity. Consumption patterns diverge between systems with mature value-based frameworks and those still transitioning from fee-for-service models.
United States
CMS bundled payment mandates for joint replacement and cardiac episodes redirect capital toward care coordination infrastructure. FDA device clearance pathways shape procurement timelines for robotic surgery platforms. Metropolitan hospital systems in Texas and Florida expand through acquisition of community hospitals to capture Medicare Advantage volumes.
Germany
Demographic compression generates sustained demand for complex cardiac and orthopedic intervention capacity. EMA Medical Device Regulation and EU AI Act compliance requirements extend validation timelines for diagnostic algorithms. University hospitals in Bavaria and Baden-Württemberg concentrate purchasing power through regional consortiums demanding pre-certified product lines.
Japan
Super-aged population dynamics strain existing acute care infrastructure with geriatric admission concentration. Government-mandated regional medical care support functions create acquisition opportunities for metropolitan systems consolidating rural general hospitals. Tokyo and Osaka medical hubs draw patients from surrounding prefectures for complex tertiary procedures.
India
Underpenetrated acute care markets in Lucknow, Indore, and Coimbatore offer first-mover positioning for standardized hospital formats. CDSCO medical device regulations and PLI scheme incentives filter technology procurement toward domestically manufactured equipment. Apollo and Max Healthcare networks expand tier-2 city presence through asset-light management contracts.
United Kingdom
Specialized nursing labor scarcity in critical care and operating rooms constrains bed utilization rates regardless of physical capacity. NHS England integrated care system reforms compress margins while rewarding post-acute partnership networks. London teaching hospitals concentrate advanced surgical volumes while regional trusts face delayed elective procedure backlogs.
Global Acute Hospital Care Market Competitive Landscape
Top-tier vendors anchor metropolitan and academic medical center networks, while regional hospital operators and specialized service platforms occupy mid-market positions. Market structure reflects consolidation pressure from value-based reimbursement mandates alongside fragmentation from community hospital independence. Three archetypes dominate: scale-driven multi-hospital systems, destination-complex-care academic brands, and vertically integrated specialty service chains. Competitive moves concentrate on M&A-driven geographic densification and strategic partnerships for post-acute care integration.
Within the scale-driven tier, HCA Healthcare and Tenet Healthcare exemplify multi-state network operators leveraging standardized electronic health record platforms to command favorable payer contracts. Fresenius SE & Co. KGaA anchors the specialty-integrated archetype through captive dialysis-to-hospital referral networks and critical care equipment supply chains. Mayo Clinic and Cleveland Clinic occupy positions as destination-complex-care brands drawing interstate and international patient flows through research-validated outcome metrics.
| Leading Market Players |
|---|
| HCA Healthcare |
| Tenet Healthcare |
| Universal Health Services |
| Cleveland Clinic |
| Mayo Clinic |
| Ascension Health |
| Community Health Systems |
| Ramsay Health Care |
| Fresenius SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Medicare Advantage plan concentration in the United States anchors the dominant value-based pricing model, where bundled episode payments compress surgical service margins while rewarding shorter length-of-stay outcomes. This buyer archetype's procurement scale forces facility operators to absorb upfront technology costs for robotic platforms and care coordination infrastructure.
Pricing Analysis
Margin tightening in surgical services reflects CMS bundled payment compression and post-acute partnership requirements. Three-tier pricing structure across academic medical centers, metropolitan hospital systems, and community facilities separates premium robotic-assisted procedures from standard laparoscopic and economy open-surgery tiers. Price differentiation hinges on FDA device clearance tier and after-sales clinical support bundling. Cost-down pressure on observation services accelerates because telemedicine-physical hybrid triage protocols reduce unnecessary admissions. Public facilities and safety-net hospitals exhibit highest price sensitivity; destination-complex-care academic brands command lowest sensitivity through interstate patient capture.
Supply Chain Analysis
Dialysis equipment supply rests on manufacturing clusters in Ireland and Switzerland, creating single-source vulnerability for Fresenius SE & Co. KGaA's captive referral networks. Robotic surgery platforms draw from semiconductor components in Taiwan, precision motors in Germany, and sterile disposables in Mexico. Biometric monitoring devices for ICU integration source from Medtronic's production in Ireland, Philips manufacturing in the Netherlands, and GE Healthcare facilities in the United States. Tariff exposure on Chinese-sourced imaging components threatens capital equipment procurement timelines. Distribution runs through group purchasing organizations in the United States, regional hospital consortiums in Germany, and government procurement frameworks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acute hospital care is becoming a vertical-integration race where control over post-acute discharge destinations determines value-based contract profitability. Players are pursuing downstream bed capacity and home health networks to capture episode margins.
For Market Incumbents: Lock in post-acute partnership networks before Medicare Advantage plans consolidate their Centers of Excellence contracting. Defend margin position by standardizing electronic health record platforms across acquired community hospitals to reduce IT fragmentation blocking seamless patient data portability. Deepen backward integration into ambulatory surgery centers to capture lower-acuity volumes shifting from inpatient settings.
For New Entrants and Emerging Players: The price-point gap between premium robotic surgery and economy conventional procedures in India's tier-2 cities offers first-mover positioning. Target Lucknow, Indore, and Coimbatore with asset-light management contracts that leverage domestic equipment incentives under India's PLI scheme. Pursue telemedicine-physical hybrid triage protocols as the go-to-market angle to reduce capital intensity versus full inpatient buildout.
For Investors and Strategic Acquirers: The window for entry favors regional hospital operators with unconsolidated post-acute networks in Japan's rural prefectures. Long-term viability over the next decade hinges on acquiring facilities with government-mandated regional medical care support function designations. Watch CMS bundled payment expansion into additional surgical episodes as the inflection signal for accelerated M&A in care coordination infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Acute Network Acquisition | Captures episode margins under CMS bundled payment mandates for joint replacement. |
| Robotic Surgery Platform Deployment | Reduces length-of-stay metrics that determine Medicare Advantage contract performance. |
| EHR Standardization Investment | Enables seamless patient data portability required for value-based reimbursement. |
| Telemedicine Triage Integration | Preserves revenue capture while reducing unnecessary emergency department admissions. |
| Regional Medical Care Support Consolidation | Leverages Japan's government-mandated hub-and-spoke rural hospital acquisition framework. |
Research Methodology
Multi-period observation of hospital bed utilization rates, CMS reimbursement rule changes, and robotic surgery platform adoption anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and post-acute network directors. Secondary validation drew from CMS Medicare cost reports, FDA 510(k) device clearance databases, hospital procurement records, and EMA medical device regulation filings. Bottom-up facility-level capacity modeling and top-down health system revenue analysis provided triangulation across data sources.
Segment-weighting across care service type, facility ownership structure, patient category demographics, and treatment technology tier shaped the analytical framework throughout the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Modeled inputs included geriatric admission trajectories in Japan and Germany, CMS bundled payment expansion schedules, and EU AI Act compliance timeline impacts on diagnostic algorithm deployment.
Underlying measurement precision varies by segment; surgical and critical care service lines carry tighter precision than emergency and observation categories due to more standardized reporting requirements. Forecasts reflect assumptions about regulatory stability and reimbursement rule continuity. Supply chain disruption from single-source medical device manufacturing clusters and specialized nursing labor scarcity represent primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Assisted Living Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Care Services Market