
 US Long Term Care Market | 2026-2036
US Long Term Care Market Size, Share, and Industry Trends Forecast 2026-2036
US Long Term Care Market Intelligence
State Medicaid certification is rotating as the primary gatekeeper for facility-based operators seeking reimbursement eligibility. Genesis HealthCare leverages its multi-state footprint to sustain bed capacity across diverse regulatory environments. Ensign Group differentiates through operational discipline in skilled nursing turnaround management. Mutual of Omaha anchors the private insurance channel with long-term care policy underwriting expertise.
Long term care encompasses medical and non-medical services delivered over extended periods to individuals with chronic conditions, functional limitations, or cognitive impairment, typically requiring licensed nursing oversight, medication administration protocols, and activities of daily living assistance. The service type dimension shows home health care capturing the fastest expansion as hospital-at-home models gain payer traction, while skilled nursing facilities remain the largest revenue pool despite occupancy pressures. Payment type analysis reveals Medicaid dominating volume but squeezing margins, whereas private pay and long-term care insurance concentrate in higher-acuity assisted living segments.
CMS rules, state Medicaid plans, and HIPAA privacy standards collectively determine reimbursement rates, staffing minimums, and data interoperability requirements across the US. FDA oversight intersects where long term care pharmacies compound specialized medications for facility populations. Stakeholders must monitor how CMS innovation center demonstrations reshape site-of-service incentives and whether state workforce registry mandates alter labor supply dynamics.
Market Dynamics
CMS reimbursement compression is decomposing traditional facility-based economics while simultaneously accelerating home-based care infrastructure investment across state Medicaid programs.
Growth Catalysts
- Medicaid 1115 Waivers:State-level expansion of home and community-based services eligibility is unlocking capitated funding streams for non-facility providers in Texas and Florida.
- Remote Patient Monitoring:FDA-cleared biometric sensors are extending clinical oversight into residential settings without brick-and-mortar overhead.
- Sun Belt Demographics:Retiree migration corridors through Arizona and the Carolinas are concentrating demand for assisted living capacity.
Market Restraints
- Medicaid Rate Compression:State fiscal pressures are capping reimbursement below operating cost inflation for skilled nursing facilities.
- Workforce Supply Constraints:Certified nursing assistant pipeline shortages in rural Midwest markets are limiting bed expansion feasibility.
- Private Insurance Erosion:Long-term care policy lapse rates and carrier exits are shifting payment burden onto state Medicaid programs.
Strategic Opportunities
- Hospital-at-Home Medicare Waivers:CMS Acute Hospital Care at Home demonstrations are creating licensed revenue streams for home health agencies.
- Technology-Enabled Care Delivery:AI-powered fall detection and medication adherence platforms are opening private-pay subscription models.
- Underserved Rural Counties:Micropolitan areas in the Mountain West lack sufficient skilled nursing bed inventory relative to aging population density.
Industry Challenges
- Interoperability Compliance:HIPAA-aligned data exchange mandates are forcing legacy electronic health record system upgrades.
- Clinical Workforce Turnover:Registered nurse retention in post-acute settings requires compensation restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Long Term Care Market |
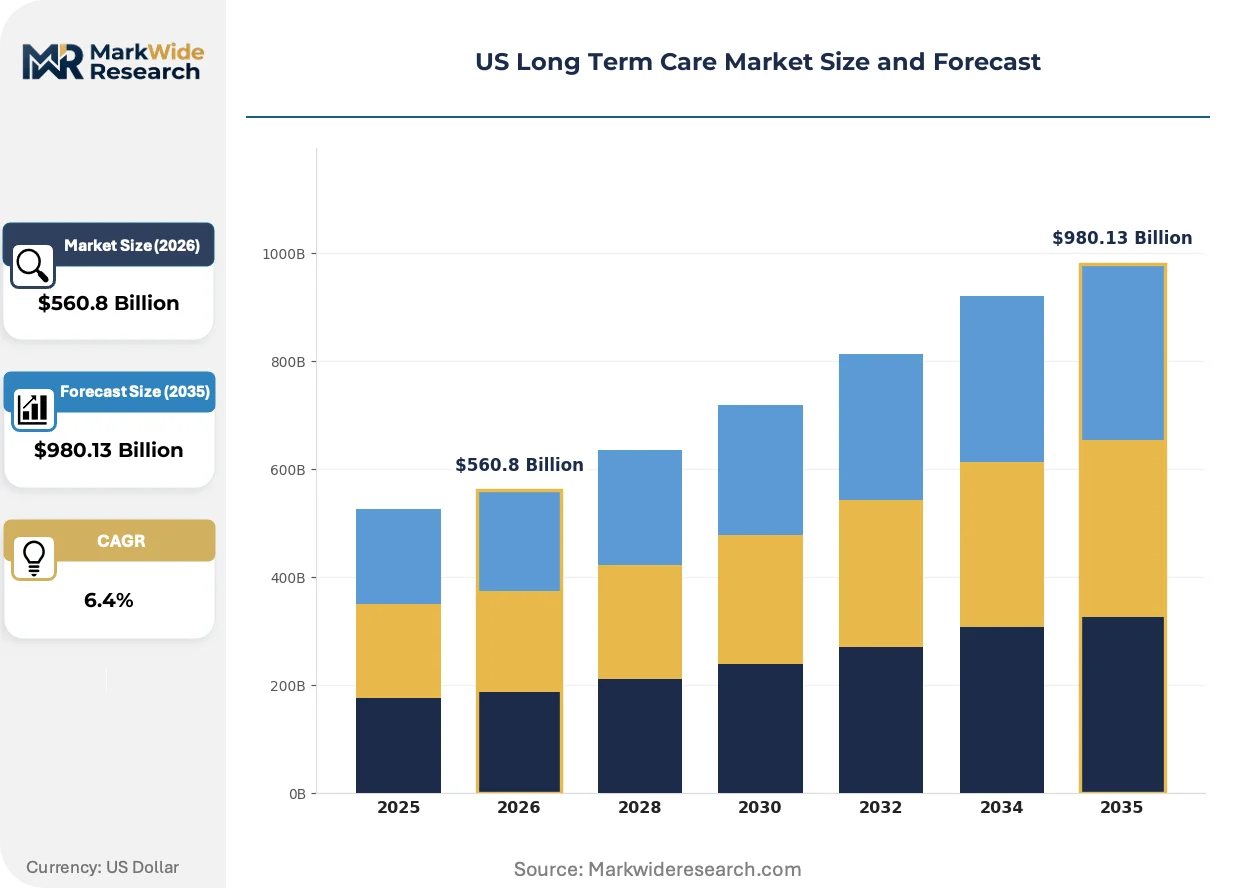
| Market Size in 2026 | $560.8 Billion |
| Market Size in 2035 | $980.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Skilled Nursing Facilities, Assisted Living, Home Health Care, Hospice Care Customer Type: Senior Citizens, Veterans, Patients with Chronic Illness, Disabled Individuals Payment Type: Private Pay, Medicare, Medicaid, Long-Term Care Insurance Setting: Residential Care, Community-Based, Facility-Based, In-Home |
| Companies Covered | Genworth Financial, Ensign Group, Mutual of Omaha, Northwestern Mutual, New York Life, Nationwide Financial, National Guardian Life, Genesis HealthCare, OneAmerica Financial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Long Term Care Market Strategic Shifts & Innovations
Value-based payment mechanics are penetrating long term care reimbursement, replacing fee-for-service structures with episode-based accountability.
Telehealth-integrated care coordination platforms are decomposing the traditional boundary between acute discharge and post-acute recovery. Medicare Advantage plans are embedding these tools into contracted home health networks. The technology is decomposing site-of-service distinctions that previously separated hospital revenue from home-based providers.
CMS workforce minimum staffing mandates are recalibrating operational cost structures for skilled nursing operators. The rule establishes registered nurse presence requirements and certified nursing assistant hour floors. Facilities in states with existing staffing regulations are adapting faster than those in minimally regulated markets.
Consumer-directed care budgets are fragmenting traditional agency relationships in Medicaid-funded personal care services. Individual employers are replacing licensed home health agencies as the direct hiring entity in some state waiver programs. This pattern concentrates in states with structured family caregiving supports like California and Washington.
US Long Term Care Market Segmentation
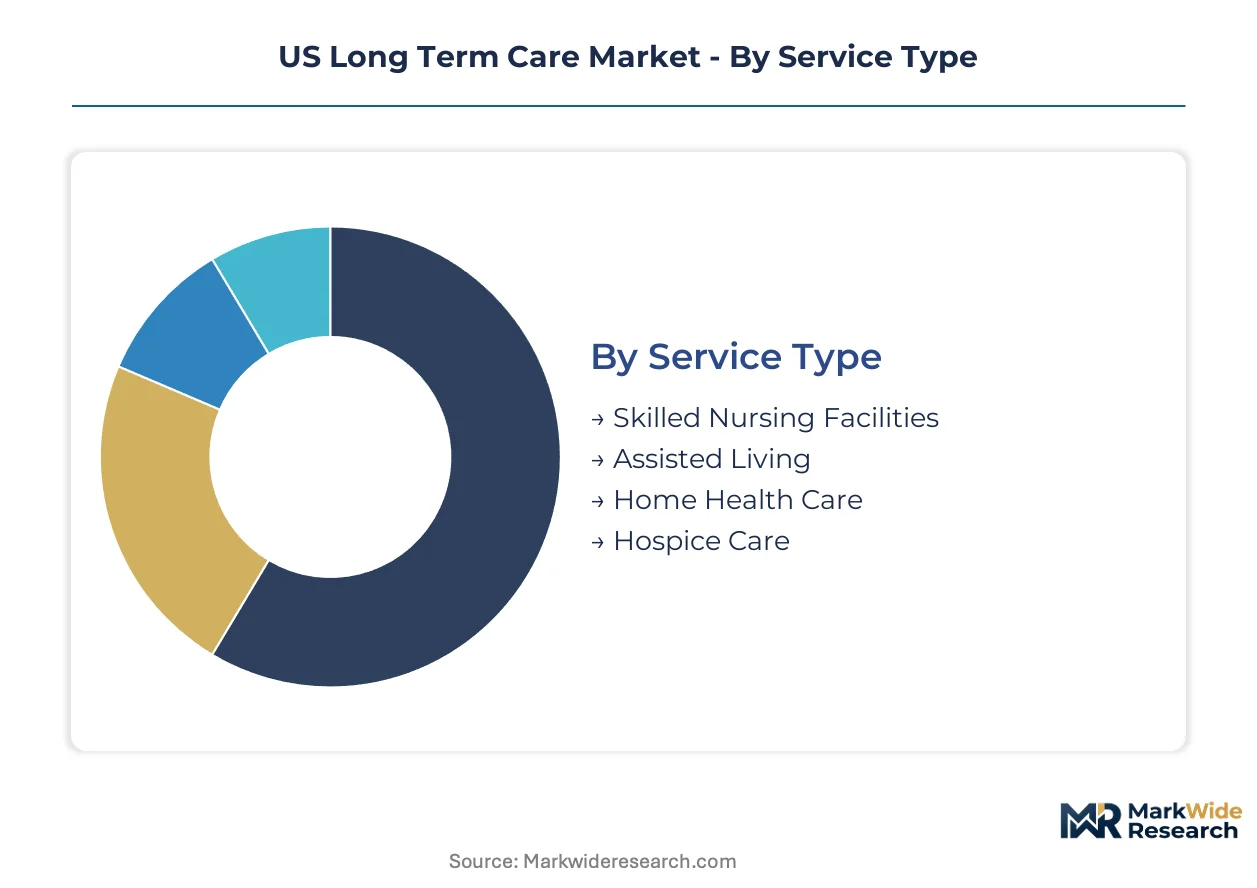
Long term care demand fragments across service modalities, payer sources, and care settings that each carry distinct regulatory requirements and margin profiles. Understanding these segment boundaries clarifies where capital deployment and operational investment generate differentiated returns.
Service Type:
Channel mix varies sharply across service modalities, with facility-based care flowing through institutional reimbursement tracks while home-based services increasingly bypass traditional brick-and-mortar gatekeepers.
- Skilled Nursing Facilities:These licensed institutions deliver 24-hour nursing supervision, post-acute rehabilitation, and complex medical management for residents requiring skilled interventions. Demand concentrates in Sun Belt retirement corridors where Florida and Texas operators compete for Medicare post-acute referrals amid occupancy pressures.
- Home Health Care:Intermittent skilled nursing, therapy, and aide services delivered in private residences. Arizona and the Carolinas show the steepest demand acceleration as hospital-at-home waivers extend CMS reimbursement into residential settings without facility overhead.
- Assisted Living:Residential environments providing personal care assistance and medication management for seniors needing supervision but not skilled nursing. Private-pay concentration in higher-acuity segments insulates margin structures from Medicaid rate compression.
- Hospice Care:Palliative services focused on symptom management and quality of life for terminal diagnoses. Medicare hospice benefit eligibility drives volume, with rural access gaps persisting in micropolitan Mountain West counties.
By volume, skilled nursing facilities lead. By growth pace, home health care is climbing the fastest.
Customer Type:
Cost tier stratification separates acute clinical needs from custodial support requirements, with chronic disease complexity driving resource intensity and reimbursement eligibility.
- Senior Citizens:Adults aged 65 and older constitute the predominant demand base, spanning independent living through end-of-life care. Age-related functional decline and multi-morbidity patterns concentrate utilization in Medicare Advantage coordinated care networks.
- Patients with Chronic Illness:Individuals with diabetes, heart failure, COPD, or dementia requiring ongoing disease management and ADL assistance. Medicaid 1115 waiver expansions in Texas and Florida are unlocking capitated funding for this population's community-based services.
- Disabled Individuals:Non-elderly adults with physical or developmental disabilities needing long-term supports. State vocational rehabilitation and Medicaid buy-in programs determine service access, with California and Washington offering structured family caregiving alternatives to agency delivery.
- Veterans:Eligible former service members accessing VA Community Care networks and state veterans homes. VA pension benefits and Aid and Attendance allowances supplement service financing for this segment.
By population scale, senior citizens dominate. By unmet need intensity, patients with chronic illness show the steepest expansion trajectory.
Payment Type:
Margin profiles diverge across payer sources, with public programs dominating volume while private mechanisms concentrate in premium service tiers.
- Medicaid:State-federal partnership financing long-term care for low-income eligible individuals, predominantly through facility and home-based personal care. Rate compression below operating cost inflation squeezes provider economics across rural Midwest markets.
- Medicare:Federal program covering skilled nursing and home health for post-acute recovery periods, not custodial long-term care. Site-neutral payment reforms are compressing differentials between hospital and post-acute reimbursement.
- Private Pay:Out-of-pocket spending by individuals and families for assisted living and non-skilled services. Sun Belt retiree migration concentrates this payment source in Florida and Arizona luxury senior living developments.
- Long-Term Care Insurance:Private policies covering specified services after elimination periods, with benefit triggers tied to ADL impairment. Carrier exits and lapse rate erosion are shifting payment burden onto state Medicaid programs.
By claim volume, Medicaid leads. By margin contribution, private pay is gaining share fastest.
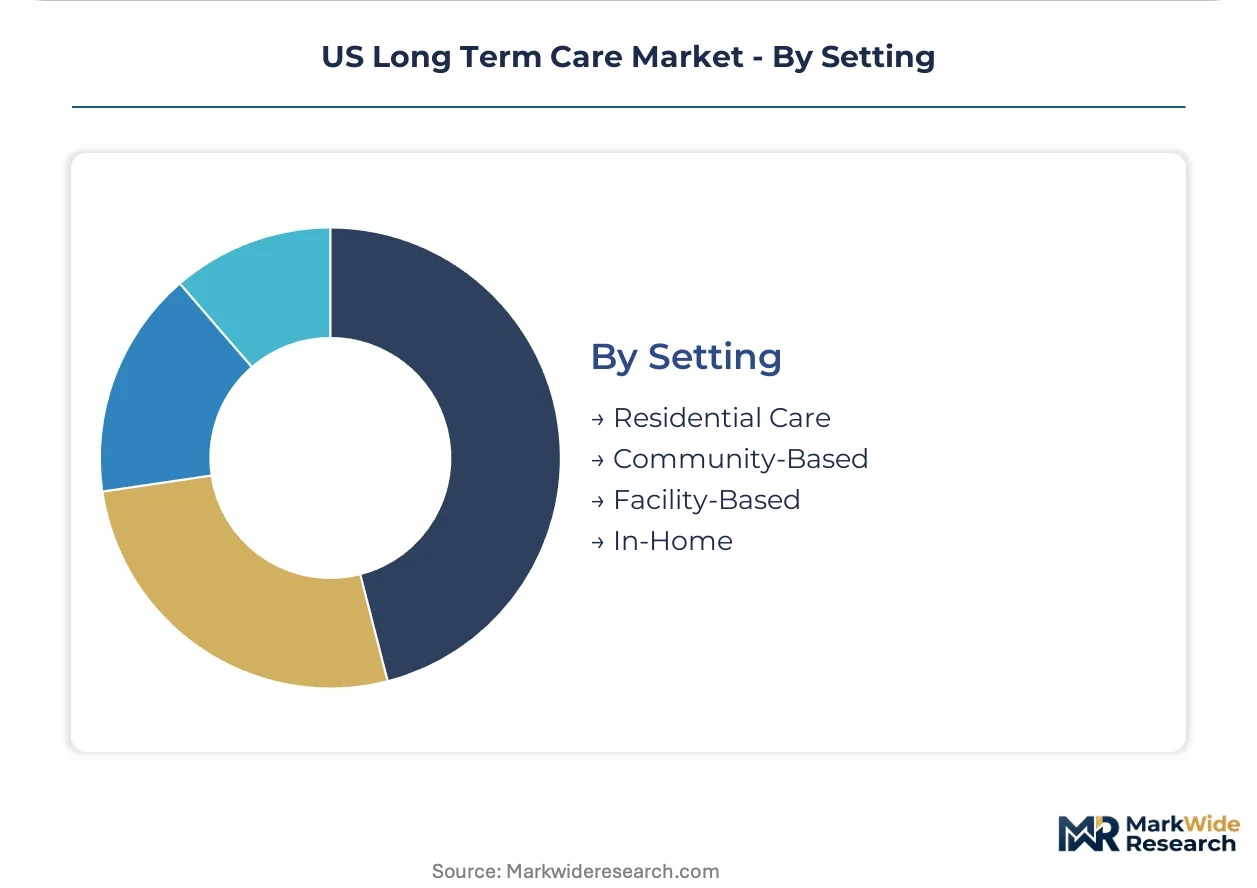
Setting:
Supply concentration reflects capital intensity requirements, with facility-based infrastructure demanding real estate investment while community models leverage existing residential stock.
- Facility-Based:Purpose-built institutional environments including skilled nursing and assisted living campuses. CMS workforce minimum staffing mandates are recalibrating operational cost structures for these operators.
- In-Home:Services delivered within private residences, spanning Medicare home health to Medicaid personal care. Remote patient monitoring and AI-powered fall detection platforms are extending clinical oversight without brick-and-mortar investment.
- Residential Care:Group living arrangements for smaller populations, including adult family homes and board-and-care facilities. Regulatory oversight varies by state, with some markets requiring licensure and others operating under exemption thresholds.
- Community-Based:Adult day services, PACE programs, and senior centers providing daytime support while preserving nighttime independence. Transportation infrastructure gaps limit rural accessibility for these models.
By bed capacity, facility-based settings lead. By investment attraction, in-home delivery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid 1115 waiver expansions are redistributing long term care capacity across US states, with federal matching incentives accelerating home-based infrastructure investment in high-migration corridors. State fiscal health and retiree demographic density now determine provider economics more than national policy uniformity.
Florida
Retiree migration from the Northeast and Midwest sustains assisted living demand in Tampa and Orlando metropolitan corridors. State Medicaid managed care long-term care programs capitate home and community-based services through approved plans. Miami-Dade and Broward counties concentrate skilled nursing bed capacity amid occupancy competition for Medicare post-acute referrals.
Texas
Medicaid 1115 waiver expansions unlock community-based service funding for seniors and disabled populations in Houston and Dallas-Fort Worth metro areas. State workforce registry mandates alter certified nursing assistant labor supply dynamics for facility operators. Austin and San Antonio micropolitan areas show emerging demand gaps relative to aging population growth.
Arizona
Sun Belt retiree relocation concentrates assisted living development in Phoenix and Tucson suburban corridors. State Medicaid acute care contracting reforms influence long-term care reimbursement rates for dual-eligible populations. Maricopa County hosts the densest home health agency network competing for hospital-at-home waiver eligibility.
California
Structured family caregiving supports and consumer-directed care budgets fragment traditional agency relationships in Los Angeles and San Francisco Bay Area markets. State minimum staffing mandates exceed federal CMS floors for skilled nursing facilities. San Diego and Sacramento sub-regions show divergent Medicaid expansion uptake affecting provider payer mix.
Carolinas
Charlotte and Raleigh-Durham retiree in-migration drives assisted living construction in North Carolina piedmont corridors. South Carolina Medicaid waiver waitlists constrain home-based service access in rural upstate counties. Regional health system vertical integration into post-acute networks reshapes referral patterns for skilled nursing discharge planning.
US Long Term Care Market Key Industry Players
Player mix skews toward multi-state facility operators and insurance underwriters with diversified payer exposure. Market structure shows moderate consolidation at the operator level alongside fragmentation in home health agency networks. Strategic archetypes include scale-driven nursing facility chains, insurance-backed senior living developers, and technology-enabled home health platforms. Competitive moves center on geographic footprint expansion through Medicaid market entry and vertical integration into care coordination services.
Within the insurance underwriting tier, Genworth Financial, Mutual of Omaha, and Northwestern Mutual anchor private long-term care policy distribution. These carriers exemplify the shift toward hybrid life-LTC products as traditional standalone policy lapse rates erode. Among facility operators, Ensign Group and Genesis HealthCare represent contrasting models of operational discipline versus multi-state scale aggregation. The competitive tension between insurance-channel patient acquisition and direct-to-consumer facility marketing continues to reshape customer acquisition economics across Sun Belt markets.
| Leading Market Players |
|---|
| Genworth Financial |
| Ensign Group |
| Mutual of Omaha |
| Northwestern Mutual |
| New York Life |
| Nationwide Financial |
| National Guardian Life |
| Genesis HealthCare |
| OneAmerica Financial |
| Others |
Cost & Logistics Intelligence
Ninety-day Medicaid reimbursement cycles for skilled nursing facilities compress working capital windows and force operators to carry higher days-sales-outstanding, concentrating pricing power with state Medicaid agencies while squeezing margin recovery from private-pay residents.
Pricing Analysis
Certification level creates the primary spread between Medicare-reimbursed skilled nursing and Medicaid-funded personal care, with five-star CMS ratings commanding premium room rates and preferred network placement in Medicare Advantage contracts. Three-tier pricing structure across premium assisted living, standard skilled nursing, and economy residential care segments reflects acuity-based service bundling. Pricing pressure stems from Medicaid rate compression below operating cost inflation in rural Midwest markets. Private-pay assisted living residents show lowest price sensitivity, while Medicaid-dependent skilled nursing populations face strict eligibility thresholds.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for long term care pharmacy compounding, while domestic US manufacturers concentrate in high-margin biologic and specialty medication categories. Supply chains draw from Chinese chemical precursors, Indian finished-dose formulations, and domestic distribution networks for temperature-controlled delivery. Single-source vulnerability concentrates in parenteral nutrition and oncology supportive care agents where FDA-approved alternatives remain limited. Distribution runs through three-tier wholesale networks linking manufacturers to long term care pharmacies, with direct-to-facility contracting gaining share for high-volume generic categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-at-home waiver expansion signals early-cycle penetration for residential clinical services, with Medicare Advantage plan embedding accelerating provider network formation beyond traditional facility boundaries.
For Market Incumbents: Fortify census stability through preferred provider network contracts with Medicare Advantage plans and integrated health systems. Defend against home health agency displacement by embedding remote patient monitoring capabilities into existing skilled nursing discharge protocols. Prioritize workforce registry compliance in states with pending certified nursing assistant mandate legislation. For New Entrants and Emerging Players: Rural micropolitan skilled nursing bed scarcity in Mountain West counties offers immediate census fill opportunity with limited incumbent competition. Target Medicaid 1115 waiver personal care services in Texas and Florida where capitated funding streams bypass traditional facility gatekeepers. Pursue direct-to-employer contracting for Medicare-eligible retiree populations seeking aging-in-place alternatives. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-inevitability play because senior population growth ensures demand expansion regardless of reimbursement cyclicality. Acquisition targets should emphasize home health agencies with hospital-at-home waiver eligibility and technology-enabled care coordination platforms. Monitor CMS innovation center demonstration expansion as signal for site-of-service payment parity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital-at-Home Waiver Pursuit | CMS Acute Hospital Care at Home demonstrations unlock licensed revenue streams outside facility overhead structures. |
| Remote Patient Monitoring Deployment | FDA-cleared biometric sensors extend clinical oversight into residential settings without brick-and-mortar investment. |
| Medicaid Managed Care Contracting | State 1115 waiver capitation agreements concentrate volume with approved plans in Texas and Florida markets. |
| Workforce Registry Compliance Investment | State certified nursing assistant pipeline mandates recalibrate labor supply access for facility operators. |
| Hybrid Life-LTC Product Development | Insurance carriers pivot from standalone policy erosion toward integrated longevity risk solutions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of CMS Medicare cost reports, state Medicaid waiver filings, and skilled nursing facility licensing databases, combining interviews with post-acute care executives, state Medicaid program directors, and Medicare Advantage plan contracting officers with validation against SEC 10-K disclosures and hospital referral pattern analytics. Bottom-up facility census modeling triangulates against top-down payer expenditure projections.
Segmentation dimensions modeled include service modality, payer source, care setting, and geographic regulatory cluster across the analysis window. CAGRs derive from regression-based trend extrapolation calibrated to historical Medicaid expenditure growth rates and Medicare post-acute utilization patterns. Forecast inputs incorporate CMS workforce mandate implementation timelines and state 1115 waiver expansion trajectories.
Material uncertainties — CMS reimbursement rule finalization, state Medicaid fiscal pressure responses, and certified nursing assistant pipeline recovery — sit outside the modeled envelope. Forecasts reflect assumptions about waiver program continuity and demographic migration stability. Recalibration cycles align with material shifts in federal site-of-service payment policy and state Medicaid managed care procurement outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
India Senior Living Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Medical Spa Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Hospice Market
Healthcare Services
Healthcare CMO Market