
 Medical Case Management Services Market | 2026-2036
Medical Case Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Case Management Services Market Outlook
Subscription-based care coordination is rebalancing how medical case management services get monetized, shifting from per-episode fees toward recurring revenue tied to patient panel size and outcome guarantees. Axiom Medical leverages its occupational health focus to anchor workers' compensation case management across manufacturing-heavy employer portfolios. ChartSpan competes on technology leadership in chronic care remote monitoring, while CareHarmony specializes in virtual-first primary care integration for Medicare Advantage plans.
Medical case management services encompass structured assessment, planning, facilitation, and advocacy activities that optimize patient care outcomes and cost efficiency across complex health episodes, typically operating through licensed nurses or social workers who coordinate multidisciplinary provider networks. The service type dimension shows care coordination outpacing traditional utilization review in growth velocity, as value-based contracting rewards longitudinal patient navigation over episodic pre-authorization checks. Within end users, health plans command the deepest margin pools due to their scale and multi-year vendor commitments, whereas employer direct contracts represent the fastest-growing access channel as self-insured corporations bypass traditional payer intermediaries.
FDA oversight of clinical decision support tools increasingly shapes how virtual platform delivery models incorporate algorithmic risk stratification, while HIPAA mandates govern data exchange architectures between case managers and covered entities. State insurance commissioners in California, New York, and Texas enforce distinct utilization management timeliness standards that fragment compliance burdens across multi-state service providers. Stakeholders must monitor evolving CMS interoperability rules and state telehealth parity laws to determine platform investment priorities and staffing licensure strategies.
Market Dynamics
Subscription-based care coordination is overtaking episodic utilization review as the dominant monetization model, rebalancing vendor economics toward recurring revenue tied to patient panel size and outcome guarantees rather than per-episode fees.
Growth Catalysts
- Catastrophic claim cost pressure:Self-insured employers and health plans are expanding outsourced case management to control expenses from complex, high-duration medical episodes and disability claims.
- HIPAA interoperability mandates:CMS rules requiring seamless data exchange between case managers and covered entities are accelerating platform investments that enable longitudinal patient tracking.
- Workers' compensation reforms:State-level utilization review tightening in California, Texas, and New York is mandating licensed case management for complex claims, creating compliance-driven demand pull.
Market Restraints
- Multi-state licensure fragmentation:Case managers must maintain separate credentials across jurisdictions, with California, New York, and Texas enforcing distinct timeliness standards that inflate compliance overhead.
- Clinical workforce scarcity:Licensed nurses and social workers with case management specialization face supply constraints that limit service expansion velocity.
- Legacy EHR integration friction:Proprietary data architectures at major health systems resist standardized API connections, delaying platform deployment timelines.
Strategic Opportunities
- Medicare Advantage virtual-first integration:Plans seeking chronic care remote monitoring partnerships present white space for vendors with virtual care coordination capabilities.
- AI-driven risk stratification:FDA oversight of clinical decision support tools creates opportunity for algorithmic patient prioritization systems that reduce manual case review burden.
- Direct employer contracting:Self-insured corporations bypassing traditional payer intermediaries represent an emerging channel with faster sales cycles and outcome-based pricing acceptance.
Industry Challenges
- Telehealth parity law fragmentation:State-by-state reimbursement and licensure rules for virtual case management create operational complexity for multi-state service delivery.
- Outcome measurement standardization:Absence of uniform metrics for care coordination efficacy complicates value-based contract negotiation and performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Case Management Services Market |
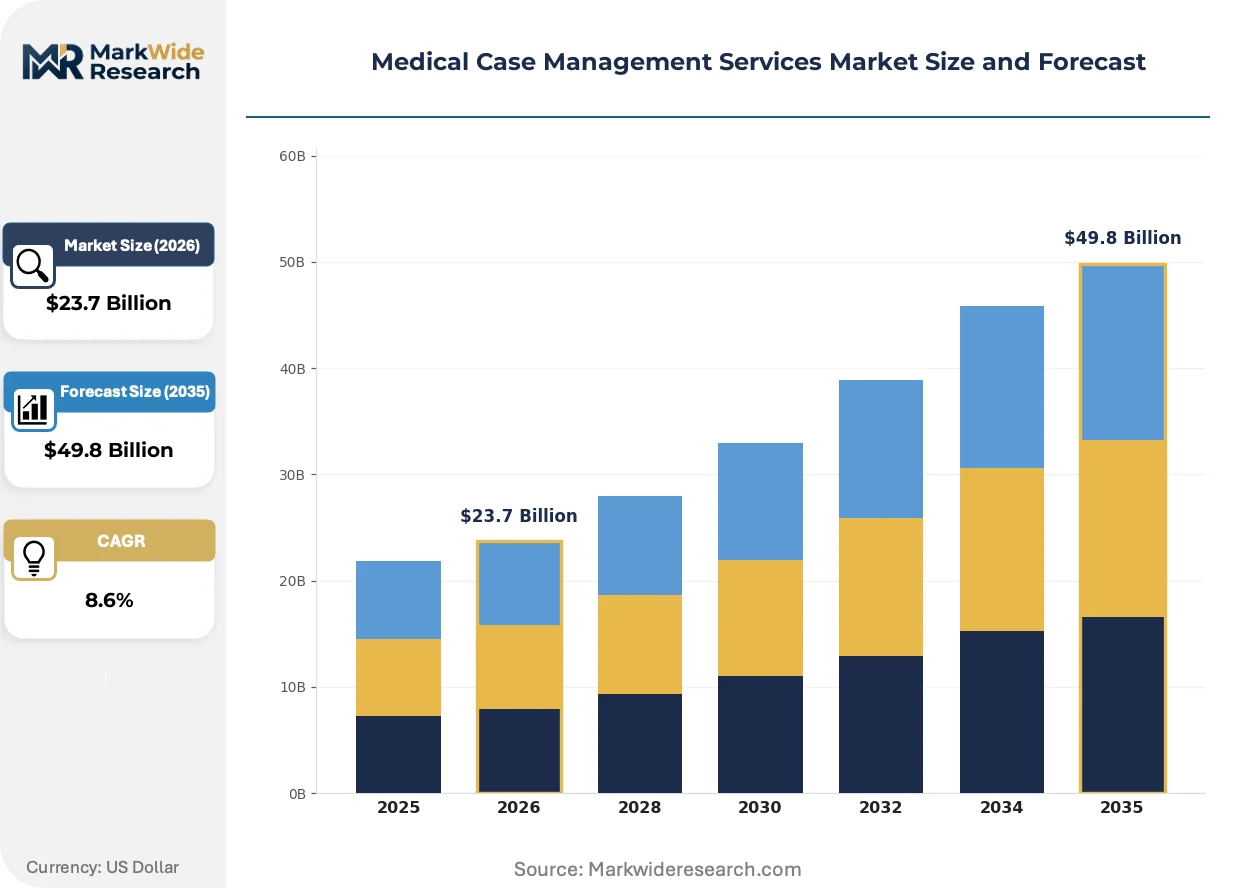
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Utilization Review, Disease Management, Care Coordination, Patient Advocacy End User: Healthcare Providers, Insurance Companies, Employers, Government Agencies Delivery Model: Telephonic Support, In-person Consultations, Virtual Platforms, Onsite Services Client Type: Individuals, Corporations, Non-profits, Health Plans |
| Companies Covered | Axiom Medical, IPMG, Choices Case Management, ChartSpan, CareHarmony, OccuMED1, Premise Health, HealthXL, WorkPartners USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Case Management Services Market Strategic Shifts
Algorithmic patient prioritization and remote biometric monitoring are compressing the traditional case management workflow, shifting human nurse hours toward exception handling while automated systems manage routine longitudinal tracking.
Remote patient monitoring platforms with integrated chronic disease dashboards is overtaking telephone-based check-ins as the standard care coordination interface. Medicare Advantage plans and large self-insured employers are adopting these systems at accelerated procurement cycles, compressing the addressable market for legacy episodic case review services into specialized catastrophic claim niches.
CMS interoperability rules and state telehealth parity laws are forcing platform architecture redesigns across vendor portfolios. These mandates require real-time data exchange capabilities between case managers, health plans, and provider networks, with California's Department of Insurance and Texas Department of Insurance enforcing the most stringent timeliness standards that shape national product roadmaps.
Employer procurement committees are consolidating vendor relationships around integrated occupational health and disability management suites. Manufacturing-heavy employer portfolios in particular are replacing fragmented point solutions with single-source contracts spanning workers' compensation case management, return-to-work coordination, and preventive health screening, with this pattern most visible in automotive and logistics sectors across the Midwest and Southeast United States.
Medical Case Management Services Market Segmentation
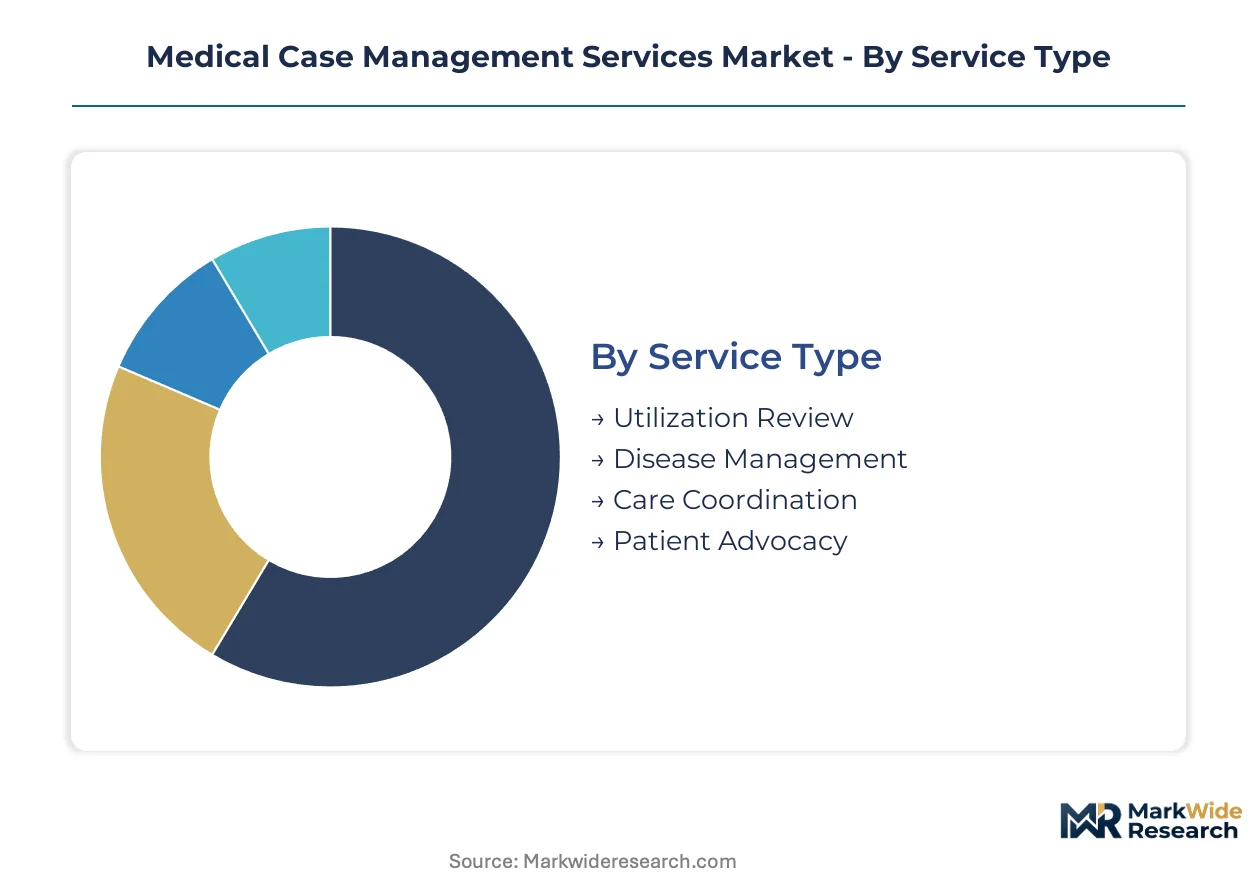
Medical case management services fragment across service intensity, buyer procurement power, and care delivery modality. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor positioning strategies.
Service Type:
Buyers prioritize longitudinal patient engagement over episodic cost containment when selecting service contracts.
- Care Coordination:Licensed nurses and social workers orchestrate multidisciplinary provider networks across complex health episodes. Health plans in the United States drive procurement expansion as value-based contracting rewards sustained patient navigation over transactional pre-authorization checks.
- Utilization Review:Licensed clinicians conduct prospective, concurrent, and retrospective medical necessity assessments against evidence-based criteria. California, Texas, and New York workers' compensation reforms mandate these services for catastrophic claims, creating compliance-driven demand concentration.
- Disease Management:Targeted interventions for chronic conditions including diabetes, heart failure, and COPD through structured protocols and biometric monitoring.
- Patient Advocacy:Independent navigation support helping individuals resolve billing disputes, access denials, and care access barriers.
Volume sits with Utilization Review; growth tilts toward Care Coordination.
End User:
Procurement scale and contract duration separate margin-rich relationships from transactional engagements.
- Insurance Companies:Multi-year vendor commitments spanning millions of covered lives anchor the deepest margin pools. These buyers demand integrated platforms combining utilization management with care coordination under unified data architectures.
- Employers:Self-insured corporations bypass traditional payer intermediaries with accelerating frequency. Direct contracting patterns concentrate in manufacturing-heavy Midwest and Southeast portfolios where occupational health and disability management needs converge.
- Healthcare Providers:Health systems purchase case management to reduce readmission penalties and manage bundled payment risk.
- Government Agencies:State Medicaid programs and federal workers' compensation systems procure through RFP processes with extended evaluation cycles.
Revenue concentrates with Insurance Companies; Employers gain share fastest.
Delivery Model:
Technology infrastructure requirements and staffing licensure complexity determine operational feasibility across deployment modes.
- Virtual Platforms:Integrated chronic disease dashboards with remote biometric monitoring compress traditional telephone-based workflows. Medicare Advantage plans adopt these systems at accelerated procurement cycles, displacing legacy episodic review into specialized catastrophic claim niches.
- Telephonic Support:Nurse-led outreach through centralized call centers remains the default for utilization review and initial care coordination triage.
- In-person Consultations:Face-to-face assessments for complex disability evaluations and workers' compensation return-to-work planning.
- Onsite Services:Embedded case managers at large employer facilities or within health system care teams for high-touch population segments.
Virtual Platforms command investment priority; Onsite Services retain premium pricing power.
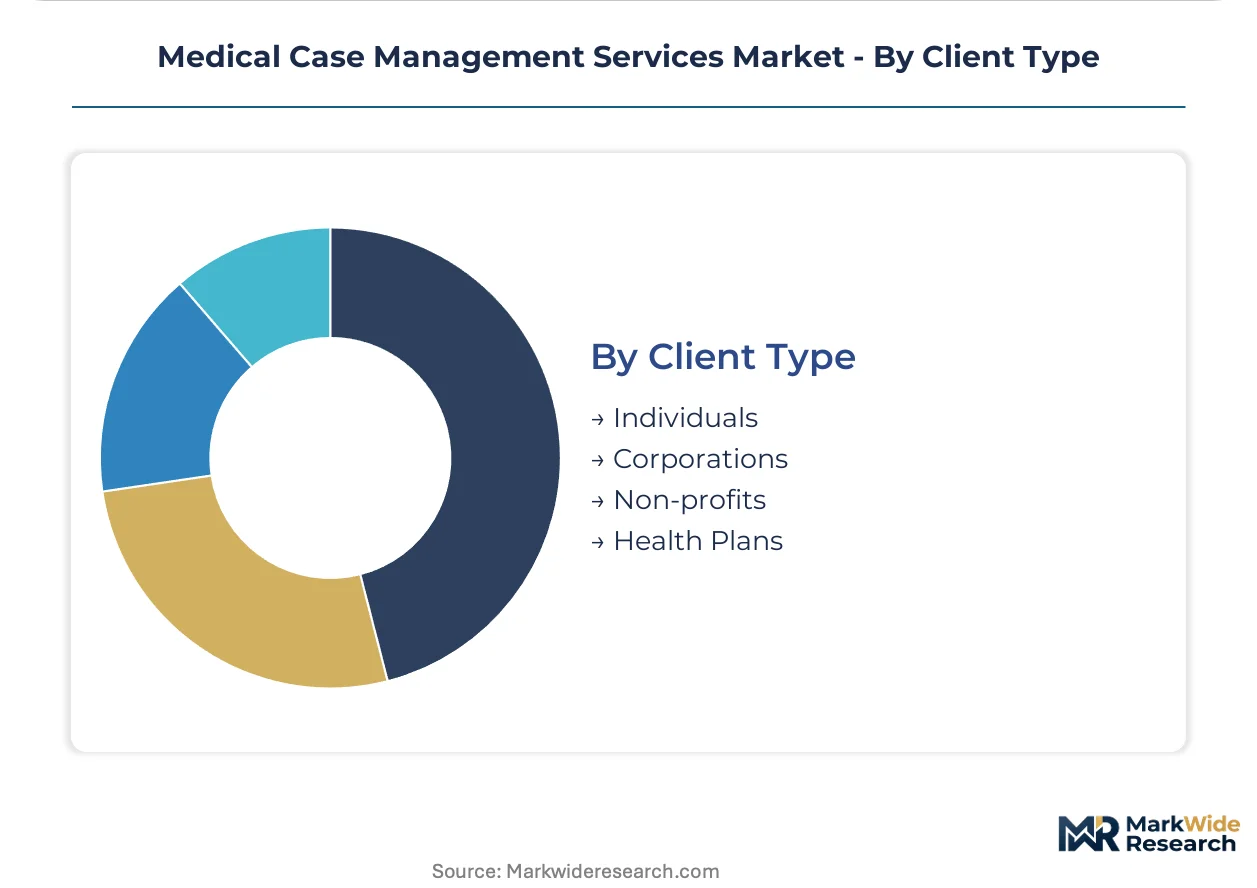
Client Type:
Payment certainty and outcome accountability vary sharply across buyer organizational forms.
- Health Plans:Medicare Advantage and commercial risk-bearing entities procure comprehensive care coordination with outcome guarantees tied to total cost of care reduction.
- Corporations:Self-insured employers with manufacturing, logistics, and automotive footprints consolidate vendor relationships around integrated occupational health suites.
- Individuals:Direct-pay navigation services for complex cancer diagnoses or rare disease management, typically funded through health savings accounts or employer-sponsored advocacy benefits.
- Non-profits:Disease-specific organizations subsidizing case management for underserved populations with particular condition burdens.
Contract value peaks with Health Plans; Corporations expand their vendor footprint most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American case management procurement through its concentration of self-insured manufacturing employers and health plan headquarters. The metropolitan corridor generates outsized demand for workers' compensation and disability coordination services.
United States
Self-insured employers in automotive and logistics sectors drive outsourced case management adoption to control catastrophic claim costs. HIPAA interoperability mandates from CMS accelerate platform investments enabling real-time data exchange between case managers and covered entities. The Texas Medical Board enforces strict utilization review timeliness standards that shape vendor compliance architectures nationwide.
Germany
Industrial employers in the Ruhr Valley and Baden-Württemberg procure integrated occupational health and disability management suites. The country's national health regulator oversees digital health application approvals that govern algorithmic risk stratification tools. Munich-based health insurers consolidate vendor relationships around unified data architectures combining care coordination with utilization management.
United Kingdom
NHS Integrated Care Systems expand procurement of virtual care coordination for chronic disease populations. The Medicines and Healthcare products Regulatory Agency shapes oversight frameworks for clinical decision support software. London health technology clusters drive platform development for remote biometric monitoring integration with case management workflows.
Canada
Provincial workers' compensation boards in Ontario and British Columbia mandate licensed case management for complex disability claims. Health Canada regulates medical device software classifications affecting remote monitoring platform deployments. Toronto employer consortia in financial services and technology sectors pilot direct contracting models bypassing traditional payer intermediaries.
Australia
Return-to-work insurers in New South Wales and Victoria expand care coordination for musculoskeletal and mental health claims. The Therapeutic Goods Administration oversees software-based medical device registrations impacting virtual platform delivery. Sydney-based health plans accelerate procurement of chronic disease remote monitoring systems for Medicare-eligible populations.
Medical Case Management Services Market Competitive Environment
Capital-heavy platform developers compete with asset-light service specialists across the case management value chain. The vendor base clusters around three strategic tiers: integrated health plan vendors with multi-year commitments, occupational health specialists serving manufacturing employers, and virtual-first chronic care platforms targeting Medicare Advantage plans. Consolidation pressures favor vendors with unified data architectures spanning utilization review and longitudinal care coordination. Geographic expansion into multi-state service delivery and AI-driven risk stratification capabilities represent the dominant competitive vectors.
Within the occupational health tier, Axiom Medical anchors service provision for manufacturing-heavy employer portfolios. ChartSpan occupies a position exemplifying technology-led chronic care remote monitoring. CareHarmony represents the virtual-first primary care integration archetype targeting Medicare Advantage procurement committees.
| Leading Market Players |
|---|
| Axiom Medical |
| IPMG |
| Choices Case Management |
| ChartSpan |
| CareHarmony |
| OccuMED1 |
| Premise Health |
| HealthXL |
| WorkPartners USA |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists dominate vendor ownership, concentrating pricing power among consolidated platforms while fragmenting supply-side labor pools across state licensure boundaries. This ownership pattern tightens margin discipline through recurring-revenue subscription models, yet inflates compliance costs that feed back into tiered service pricing.
Pricing Analysis
Outcome-based pricing anchors vendor economics, with subscription fees tied to patient panel size and total-cost-of-care reduction guarantees rather than per-episode utilization review charges. Price differentiation separates health plan multi-year commitments from employer direct contracts, with manufacturing-heavy portfolios in the Midwest and Southeast commanding premium pricing for integrated occupational health suites. Pricing pressure stems from self-insured employers consolidating vendor relationships around unified platforms, squeezing standalone utilization review specialists. Health plans exhibit lowest price sensitivity due to scale and outcome guarantee structures, while mid-market employers show acute sensitivity to per-member-per-month fees.
Supply Chain Analysis
Licensed clinical talent supply rests on United States nursing and social work education pipelines, with Texas, California, and Florida producing the highest case management certification volumes. Technology infrastructure inputs draw from cloud services providers and remote monitoring device manufacturers concentrated in California and Massachusetts. Supply chain risk centers on clinical workforce scarcity limiting service expansion velocity across multi-state delivery footprints. Distribution runs through health plan procurement committees, employer benefits consultants, and direct sales teams targeting self-insured corporations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HIPAA interoperability mandates and state-level utilization review reforms have erected a cost-of-compliance barrier that favors established vendors with multi-state licensure infrastructure and unified data architectures.
For Market Incumbents: Anchor market position through backward integration into AI-driven risk stratification capabilities and embedded onsite services at manufacturing-heavy employer facilities. Consolidate fragmented point-solution competitors to capture direct employer contracting momentum. Defend against virtual-first chronic care entrants by deepening Medicare Advantage plan relationships with outcome guarantees tied to hospital readmission reduction. For New Entrants and Emerging Players: The premium-economy pricing gap in mid-market employer direct contracts creates white-space opportunity for virtual-first platforms with streamlined care coordination offerings. Target self-insured corporations in automotive and logistics sectors bypassing traditional payer intermediaries. Penetrate through subscription-based pricing with rapid deployment timelines and minimal EHR integration friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor clinical workforce-heavy platforms in Texas and California facing temporary margin compression from multi-state licensure overhead. Long-term viability hinges on algorithmic patient prioritization capabilities and Medicare Advantage virtual-first integration. Monitor CMS interoperability rule enforcement as the inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Risk Stratification Development | FDA oversight of clinical decision support tools shapes algorithmic patient prioritization investment priorities. |
| Medicare Advantage Virtual-First Integration | CareHarmony and ChartSpan archetypes demonstrate procurement committee appetite for remote chronic care platforms. |
| Multi-State Licensure Infrastructure Expansion | California, Texas, and New York timeliness standards fragment compliance burdens and favor scaled vendors. |
| Direct Employer Contracting Channel Buildout | Self-insured corporations in Midwest manufacturing corridors seek integrated occupational health and disability management suites. |
| Unified Data Architecture Consolidation | Health plans demand integrated platforms spanning utilization review and longitudinal care coordination under single vendor relationships. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with health plan procurement directors, case management vendor executives, employer benefits consultants, and state insurance commissioners. CMS Medicare data, HIPAA enforcement records, and workers' compensation reform documentation provided secondary validation. Bottom-up service volume estimates triangulated against top-down health plan spending disclosures.
Reconciliation of health plan vendor commitment data, employer benefits survey responses, and state-level utilization review mandate tracking informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type intensity, delivery modality, end-user procurement power, and client organizational form. CAGRs derived from longitudinal patient panel growth rates and outcome-based contract penetration curves, with Medicare Advantage enrollment trajectories and self-insured employer adoption patterns serving as key forecast inputs.
Underlying measurement precision varies by segment; health plan multi-year commitments carry tighter precision than individual direct-pay navigation services. Forecasts reflect assumptions around HIPAA interoperability implementation timelines and state telehealth parity law convergence. Workforce scarcity, EHR integration friction, and outcome measurement standardization gaps constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Medical Spa Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Hospice Market
Healthcare Services
Long Term Care Market
Healthcare Services
Medical Second Opinion Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
US Care Services Market