
 Global Concierge Medicine Market | 2026-2036
Global Concierge Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concierge Medicine Market Foresight
Employer-sponsored corporate wellness programs is broadening the addressable base for concierge medicine beyond traditional high-net-worth individuals. MDVIP leverages its national physician network to sustain geographic coverage density across suburban markets. Specialdocs Consultants, LLC anchors its competitive position through practice-transition consulting that converts traditional primary care offices to retainer models. Crossover Health differentiates via on-site and near-site employer clinics that integrate concierge-style access with occupational health services.
Concierge medicine denotes a direct-primary-care arrangement where patients pay periodic retainers or membership fees for enhanced physician access, shorter wait times, and comprehensive preventive screening protocols. The model typically guarantees same-day or next-day appointments, extended consultation durations, and coordinated specialist referrals outside standard insurance frameworks. Annual membership and retainer-based service types capture the dominant share of revenue as patients prioritize predictable costs over episodic fee-for-service billing. Virtual consultations and telehealth services within the care delivery model segment are expanding fastest, though in-person visits still command premium pricing and stronger patient retention metrics.
The FDA governs telehealth prescribing and remote monitoring devices used in virtual concierge encounters, while HIPAA mandates encryption and breach-notification standards for patient data exchanged through digital platforms. The EU AI Act imposes conformity requirements on diagnostic algorithms deployed in European virtual consultation workflows, affecting cross-border service scalability. Stakeholders must monitor how CMS reimbursement policy evolution for remote therapeutic monitoring influences hybrid model pricing and patient acquisition economics.
Market Dynamics
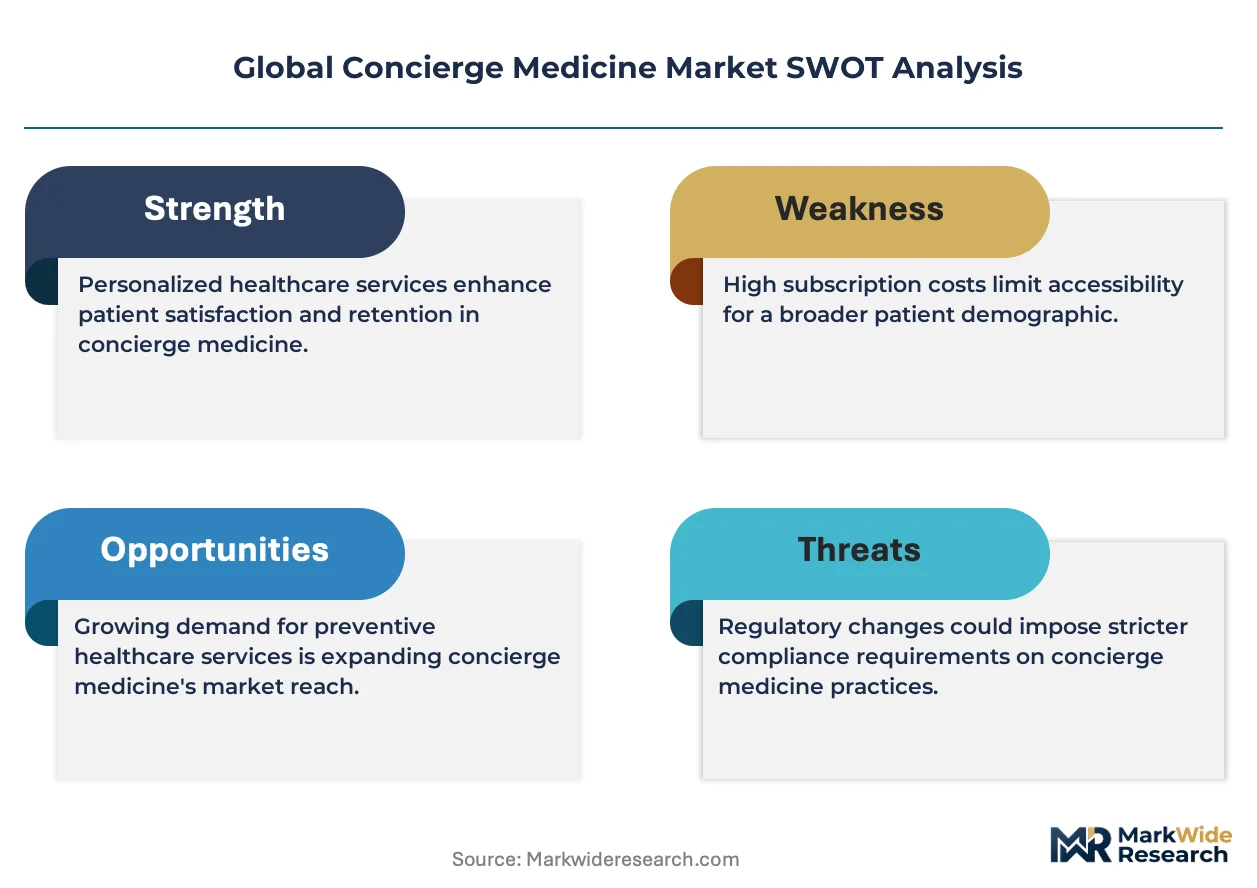
Employer self-insurance and direct-primary-care contracting are compressing traditional payer intermediation, forcing physicians to choose between volume-based insurance reimbursement and retainer-based patient relationships.
Growth Catalysts
- CMS Remote Therapeutic Monitoring:Expanded reimbursement codes for biometric tracking devices incentivize hybrid concierge practices to deploy continuous glucose monitors and blood pressure cuffs. Physician groups in Texas and Florida are retrofitting exam rooms with FDA-cleared RPM hardware.
- High-deductible health plan proliferation:Employers with self-funded arrangements in California and New York are subsidizing concierge memberships as a cost-containment layer for catastrophic claims prevention.
- Telehealth parity laws:State-level mandates requiring equivalent reimbursement for virtual visits remove pricing friction for hybrid concierge models combining in-person and remote care delivery.
Market Restraints
- Physician supply concentration:Retainer-based conversion requires board-certified internists willing to abandon panel sizes exceeding two thousand patients; rural markets face acute recruitment gaps.
- HIPAA compliance overhead:Encryption standards for patient data transmitted through third-party telehealth platforms impose recurring technology audit costs on independent practice operators.
- Direct primary care substitution:Lower-cost membership models without comprehensive preventive screening protocols attract price-sensitive patients in suburban Atlanta and Phoenix metropolitan areas.
Strategic Opportunities
- Germany and Switzerland:Private health insurance frameworks in these markets accommodate out-of-pocket wellness spending, creating expansion vectors for US-based concierge networks seeking European footprint.
- Chronic disease management bundling:Diabetes and hypertension patient cohorts generate predictable utilization patterns suitable for capitated retainer structures with embedded specialist coordination.
- Artificial intelligence diagnostic assistance:Convergence of large language models with FDA-cleared decision support tools enables asynchronous patient triage at scale.
Industry Challenges
- Electronic health record interoperability:Retainer-based practices operating outside hospital system networks struggle to exchange clinical data with specialist referral networks using incompatible Epic and Cerner deployments.
- Malpractice coverage recalibration:Underwriting actuaries have not standardized premium schedules for hybrid virtual-physical care models, creating coverage gaps during platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concierge Medicine Market |
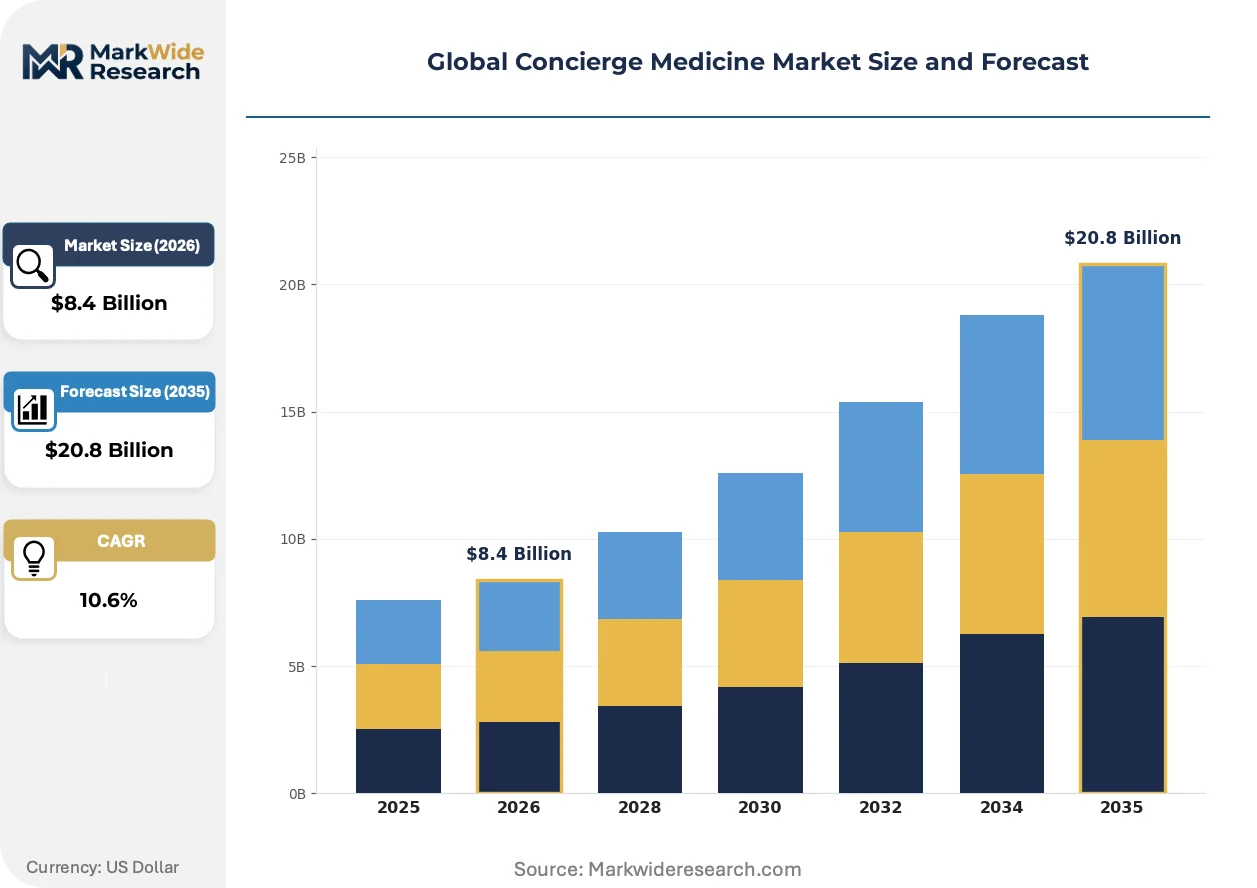
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $20.8 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Annual Membership, Retainer-Based, Fee-for-Service, Hybrid Model Patient Age Group: Pediatrics, Adults, Geriatrics, Adolescents Practice Setting: Private Clinics, Multi-Specialty Clinics, Academic Centers, Corporate Wellness Centers Care Delivery Model: In-Person Visits, Virtual Consultations, Home Visits, Telehealth Services |
| Companies Covered | Castle Connolly Private Health Partners, Specialdocs Consultants, LLC, MDVIP, Priority Physicians, Inc., Concierge Choice Physicians, SignatureMD, PartnerMD, Peninsula Doctor, Crossover Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concierge Medicine Market Shifts & Advancements
Continuous biometric monitoring and asynchronous care delivery are dissolving the traditional appointment-based care model, enabling concierge physicians to intervene before acute episodes materialize.
Remote patient monitoring platforms using cellular-connected wearable devices are integrating continuous vital sign streams into physician dashboards. Self-insured employers in Minnesota and Wisconsin are subsidizing device deployment for covered employees. This technology is integrating preventive intervention timelines with real-time physiologic alerts, compressing the gap between symptom onset and clinical response.
The EU AI Act imposes conformity assessment requirements on diagnostic algorithms deployed in virtual consultation workflows. European concierge operators must document risk classification and post-market surveillance protocols for AI-assisted triage tools. German and Swiss practices are restructuring vendor contracts to ensure algorithmic transparency documentation meets notified body standards.
Annual retainer contracts with embedded specialist network access are displacing episodic fee-for-service billing among high-net-worth patients. Family offices in Miami and Greenwich are negotiating multi-year memberships with guaranteed physician continuity. This preference shift concentrates revenue predictability with established concierge networks possessing dense specialist referral relationships.
Global Concierge Medicine Market Segmentation
Segmentation in concierge medicine reveals how payment structures, patient demographics, and care modalities create distinct operational economics. Each category shapes physician panel sizing, technology infrastructure requirements, and regulatory compliance burdens differently.
Service Type:
Standalone annual contracts dominate patient acquisition, while embedded hybrid models integrate employer-sponsored benefits with traditional retainer structures.
- Annual Membership:Patients pay a fixed yearly fee covering unlimited primary care access, preventive screenings, and same-day appointment guarantees. Demand concentrates among family offices in Greenwich and Miami seeking multi-year contracts with guaranteed physician continuity.
- Retainer-Based:Monthly or quarterly fees secure enhanced access without comprehensive service bundling, appealing to price-sensitive professionals in suburban Atlanta and Phoenix who prioritize appointment speed over preventive protocols. This structure leads volumes today; Hybrid Model is gaining share fastest.
- Fee-for-Service:Episodic billing for individual encounters persists in transitional practices converting from insurance-based panels.
- Hybrid Model:Combines retainer fees with insurance billing for procedural services, enabling broader patient base expansion.
Annual Membership leads volumes today; Hybrid Model is gaining share fastest.
Patient Age Group:
Cost tier segmentation separates high-acuity geriatric management from low-utilization pediatric panels with diverging technology requirements.
- Adults:Working-age patients aged 18-64 generate the core revenue base through employer-sponsored memberships and individual retainers. Corporate wellness programs in California and New York subsidize this segment as a catastrophic claims prevention layer.
- Geriatrics:Patients over 65 require chronic disease management bundling with embedded specialist coordination for diabetes and hypertension cohorts. Medicare Advantage plans in Florida and Texas are piloting supplemental retainer benefits for this demographic.
- Pediatrics:Concierge adoption remains limited due to lower utilization frequency and parental price sensitivity.
- Adolescents:Transitional care needs between pediatric and adult medicine create panel complexity.
Adults dominate current enrollment; Geriatrics shows steepest expansion trajectory as Medicare Advantage evolves.
Practice Setting:
Volume concentration varies by ownership structure, with independent operators facing distinct EHR interoperability challenges compared to system-affiliated sites.
- Private Clinics:Independent physician-owned practices offer maximum scheduling flexibility and personalized relationship depth. Board-certified internists in Texas and Florida are retrofitting exam rooms with FDA-cleared RPM hardware to differentiate their offerings.
- Corporate Wellness Centers:On-site and near-site employer clinics integrate concierge-style access with occupational health services. Self-insured employers in Minnesota and Wisconsin subsidize biometric monitoring device deployment for covered employees at these facilities.
- Multi-Specialty Clinics:Shared infrastructure reduces overhead but dilutes the exclusive access promise central to concierge value propositions.
- Academic Centers:Teaching hospital affiliations introduce resident involvement that conflicts with continuity guarantees.
Private Clinics anchor current supply; Corporate Wellness Centers are expanding most quickly through employer self-insurance growth.
Care Delivery Model:
Application-based segmentation distinguishes synchronous in-person encounters from asynchronous remote monitoring with diverging reimbursement and compliance frameworks.
- In-Person Visits:Traditional office-based consultations command premium pricing and deliver stronger patient retention metrics through physical examination capabilities. Extended consultation durations of 30-60 minutes enable comprehensive preventive screening protocols.
- Virtual Consultations:Telehealth-enabled encounters remove geographic constraints and reduce overhead, though HIPAA compliance overhead for encryption standards imposes recurring technology audit costs on independent practice operators.
- Home Visits:Physician travel to patient residences persists as a premium tier service for high-net-worth individuals with mobility limitations.
- Telehealth Services:State-level parity laws mandating equivalent reimbursement for virtual visits are removing pricing friction for hybrid models combining remote and in-person delivery.
In-Person Visits retain the largest revenue share; Virtual Consultations are climbing the fastest as CMS expands remote therapeutic monitoring codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greenwich family offices and Miami wealth management clusters anchor global concierge medicine demand through multi-year retainer contracts. Employer self-insurance growth in California and New York subsidizes membership expansion as catastrophic claims prevention. Regulatory divergence across FDA, EU AI Act, and national insurance frameworks shapes cross-border scalability.
United States
Self-insured employers in Minnesota and Wisconsin subsidize biometric monitoring device deployment for covered employees. FDA oversight of telehealth prescribing and remote patient monitoring platforms reshapes care delivery compliance requirements. Texas and Florida physician groups retrofit exam rooms with FDA-cleared RPM hardware to differentiate hybrid offerings.
Germany
Private health insurance frameworks accommodate out-of-pocket wellness spending, creating expansion vectors for retainer-based models. EU AI Act conformity assessment requirements govern diagnostic algorithms in virtual consultation workflows. Berlin and Munich practices restructure vendor contracts to ensure algorithmic transparency documentation meets notified body standards.
Switzerland
High-net-worth individuals in Zurich and Geneva drive demand for annual membership contracts with embedded specialist network access. Swissmedic regulates digital health applications deployed in preventive screening protocols. Basel-area private clinics integrate continuous glucose monitors and blood pressure cuffs into concierge service bundles.
United Kingdom
London wealth management clusters negotiate multi-year memberships with guaranteed physician continuity for principal executives. GDPR mandates encryption and breach-notification standards for patient data exchanged through digital platforms. Harley Street private practices face HIPAA-equivalent compliance overhead when serving US expatriate clientele.
Canada
Health Canada regulates remote therapeutic monitoring devices deployed in employer-sponsored corporate wellness programs. Ontario and British Columbia employers pilot concierge memberships as supplementary benefits within self-funded arrangements. Vancouver and Toronto private clinics struggle with EHR interoperability when exchanging clinical data with US specialist referral networks.
Global Concierge Medicine Market Competitive Landscape
Practice-transition consulting dominates the current landscape as physicians abandon volume-based insurance reimbursement for retainer-based patient relationships. The vendor base clusters around three strategic archetypes: national physician networks sustaining geographic coverage density, practice-transition consultancies converting traditional primary care offices, and on-site employer clinic operators integrating occupational health services. M&A activity concentrates on regional practice roll-ups, while technology licensing partnerships proliferate for FDA-cleared remote monitoring hardware.
Within the network-scale tier, MDVIP leverages national physician density across suburban markets. Specialdocs Consultants, LLC anchors the practice-transition consultancy segment through retainer-model conversion services. Crossover Health occupies the employer-clinic vector, integrating concierge-style access with occupational health delivery.
| Leading Market Players |
|---|
| Castle Connolly Private Health Partners |
| Specialdocs Consultants, LLC |
| MDVIP |
| Priority Physicians, Inc. |
| Concierge Choice Physicians |
| SignatureMD |
| PartnerMD |
| Peninsula Doctor |
| Crossover Health |
| Others |
Supply & Pricing Matrix
Annual retainer tier divergence between family offices seeking multi-year physician continuity and price-sensitive suburban professionals creates distinct supply chain configurations across concierge medicine. Premium tier practices in Greenwich and Miami source FDA-cleared RPM hardware directly from US manufacturers, while lower-tier operators in Atlanta and Phoenix rely on third-party telehealth platform aggregators that bundle encryption-compliant infrastructure.
Pricing Analysis
Input-cost pass-through from FDA-cleared biometric hardware and HIPAA-compliant encryption audits flows directly into retainer fee structures across hybrid concierge models. Three-tier pricing structure across premium, standard, and economy levels separates family office memberships with embedded specialist networks from employer-subsidized corporate wellness tiers and individual monthly retainers. Price differentiation intensifies as direct primary care substitutes in suburban Phoenix and Atlanta compress entry-level pricing. Corporate wellness buyers in California and New York exhibit lowest price sensitivity due to self-insured cost-containment framing, while individual subscribers in price-sensitive metros drive commoditization pressure.
Supply Chain Analysis
Physician supply rests on board-certified internist availability concentrated in Texas, Florida, and suburban California markets with established concierge conversion consultancies. RPM hardware draws from FDA-cleared device manufacturers, third-party telehealth encryption platforms, and EHR interoperability middleware vendors. Single-source vulnerability emerges from Epic and Cerner deployment fragmentation blocking specialist referral data exchange. Distribution runs through national physician networks, regional practice-transition consultancies, and direct employer contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between US employer self-insurance subsidies and European private health insurance out-of-pocket frameworks creates expansion vectors for retainer-based models, with EU AI Act compliance costs in Germany and Switzerland offset by premium pricing tolerance.
For Market Incumbents: Deploy embedded specialist network density as a retention lever against direct primary care substitutes gaining share in suburban Atlanta and Phoenix. Consolidate regional practice roll-ups in Texas and Florida to secure physician supply before rural recruitment gaps widen. Fortify HIPAA encryption infrastructure investments to offset technology audit cost inflation pressuring independent operator margins. For New Entrants and Emerging Players: CMS Remote Therapeutic Monitoring reimbursement expansion in the United States opens a window for hybrid virtual-physical care models targeting diabetes and hypertension cohorts with predictable utilization patterns. White-space concentration sits with Medicare Advantage supplemental retainer pilots in Florida and Texas. Pursue chronic disease management bundling with capitated structures as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with practice-transition consultancies possessing proprietary physician conversion methodologies and established RPM hardware vendor relationships. Long-term viability hinges on Medicare Advantage benefit evolution and employer self-insurance penetration sustaining retainer model economics. Watch CMS reimbursement policy for remote therapeutic monitoring codes as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Physician Network Expansion | Geographic density in Texas and Florida secures patient acquisition before rural supply constraints tighten. |
| Reimbursement Strategy Development | CMS remote therapeutic monitoring code optimization unlocks hybrid model economics for employer sponsors. |
| Platform Integration | Epic and Cerner interoperability middleware resolves specialist referral data exchange bottlenecks. |
| Regulatory Compliance Investment | EU AI Act conformity documentation enables Swiss and German market entry for US-based networks. |
| Chronic Disease Bundling | Diabetes and hypertension capitated structures align retainer pricing with predictable utilization patterns. |
Research Methodology
Multiple input streams — concierge practice operators, employer benefits directors, FDA regulatory consultants, and RPM device manufacturers — were reconciled against secondary validation from CMS reimbursement databases, FDA 510(k) clearance records, and hospital procurement contracts. Primary interviews with physician network executives, corporate wellness program managers, and practice-transition consultants informed operational economics and patient acquisition mechanics. Bottom-up panel sizing estimates and top-down employer sponsorship penetration rates were triangulated to anchor market sizing.
Data-stream reconciliation across service type, patient age group, practice setting, and care delivery model dimensions produced volume and value estimates across the analysis window. CAGRs were derived from employer self-insurance growth trajectories, Medicare Advantage supplemental benefit pilot expansion, and telehealth parity law adoption curves. Forecast inputs incorporated physician supply constraints, HIPAA compliance cost inflation, and direct primary care substitution elasticity by metropolitan market.
Revisions become necessary when CMS reimbursement policy shifts, EU AI Act enforcement intensity changes, or employer self-insurance sponsorship patterns deviate from projected trajectories materialize. Forecasts reflect assumptions about physician conversion rates, patient retention benchmarks, and technology platform cost structures. A small set of named triggers — FDA telehealth prescribing guidance evolution, Medicare Advantage benefit design changes, and RPM hardware price deflation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
India Senior Living Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Long Term Care Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Bruxism Management Market