
 Global Funeral Homes and Funeral Services Market | 2026-2036
Global Funeral Homes and Funeral Services Market Size, Share, and Industry Trends Forecast 2026-2036
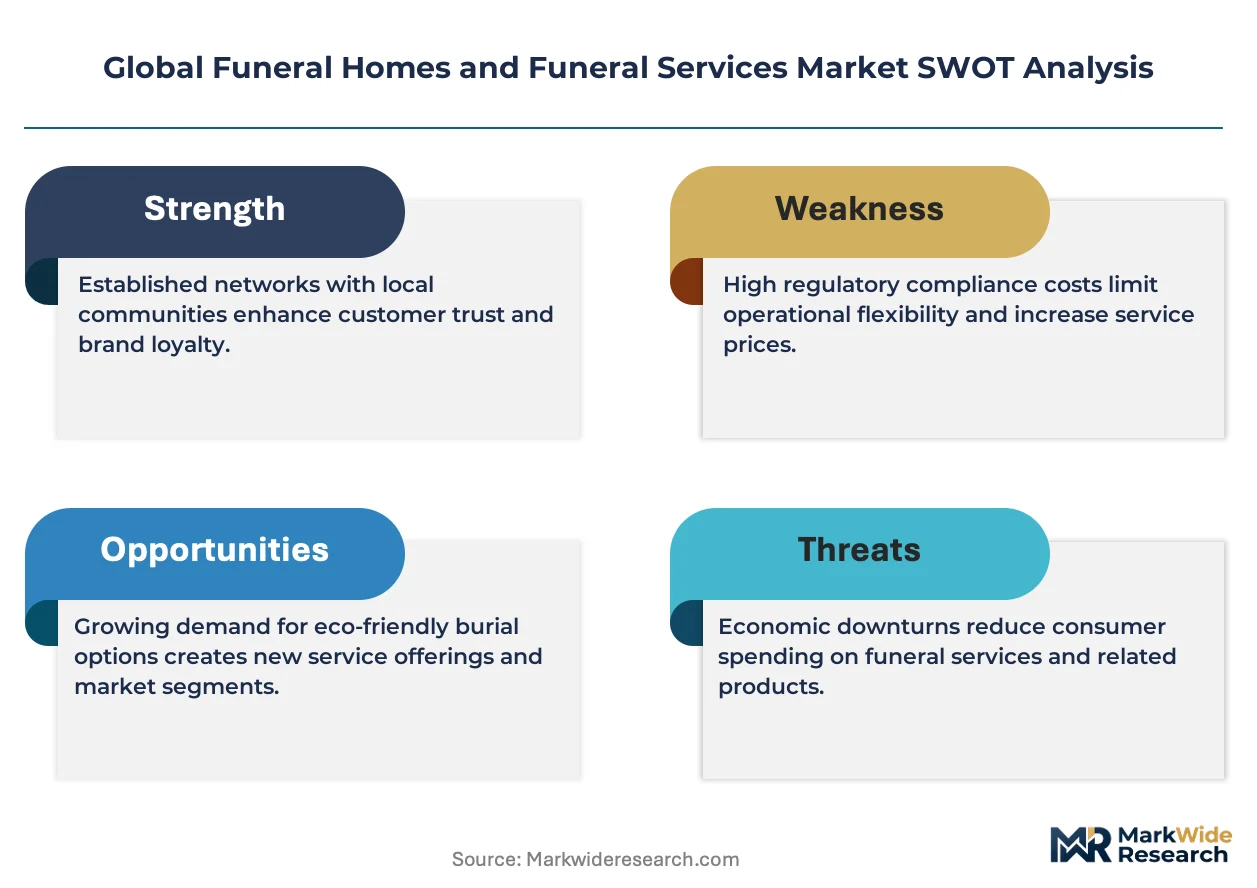
Global Funeral Homes and Funeral Services Market Analysis
North American funeral operator capacity is shifting toward consolidated pre-need sales networks and digital arrangement platforms. Service Corporation International leverages its scale across cemetery-crematory combinations to dominate the U.S. death care landscape. Dignity PLC sustains brand recognition across British high-street funeral locations despite competitive pressure from price-transparent alternatives. InvoCare Limited anchors Australasian market share through vertically integrated cemetery, crematorium, and memorial park assets.
Funeral homes and funeral services encompass the preparation, disposition, and memorialization of deceased persons through embalming, cremation, burial, and ceremony coordination, typically requiring licensed funeral directors and compliance with health and sanitation protocols for human remains handling. The primary commercial purpose centers on managing death-related logistics for bereaved families while navigating regulatory compliance and cultural ritual requirements. Cremation services now lead volume growth across developed markets as religious restrictions ease and environmental preferences intensify, while pre-planning services capture expanding margin pools through locked-in pricing and installment financing structures. Caskets and urns represent mature product segments with stable replacement demand, whereas memorial products including digital tribute platforms and biodegradable containers are attracting faster growth.
The U.S. Federal Trade Commission's Funeral Rule mandates itemized price disclosure, reshaping how American consumers compare services and pressuring opaque bundled pricing. The EU Green Deal and REACH frameworks constrain embalming chemical formulations and crematory emissions standards across European member states. Japan's Ministry of Health, Labour and Welfare oversees funeral business licensing and cemetery land use restrictions that limit new market entry. Stakeholders must monitor regulatory divergence between cremation-friendly jurisdictions and those preserving burial traditions, as this split determines capital allocation toward flame-based or natural organic reduction technologies.
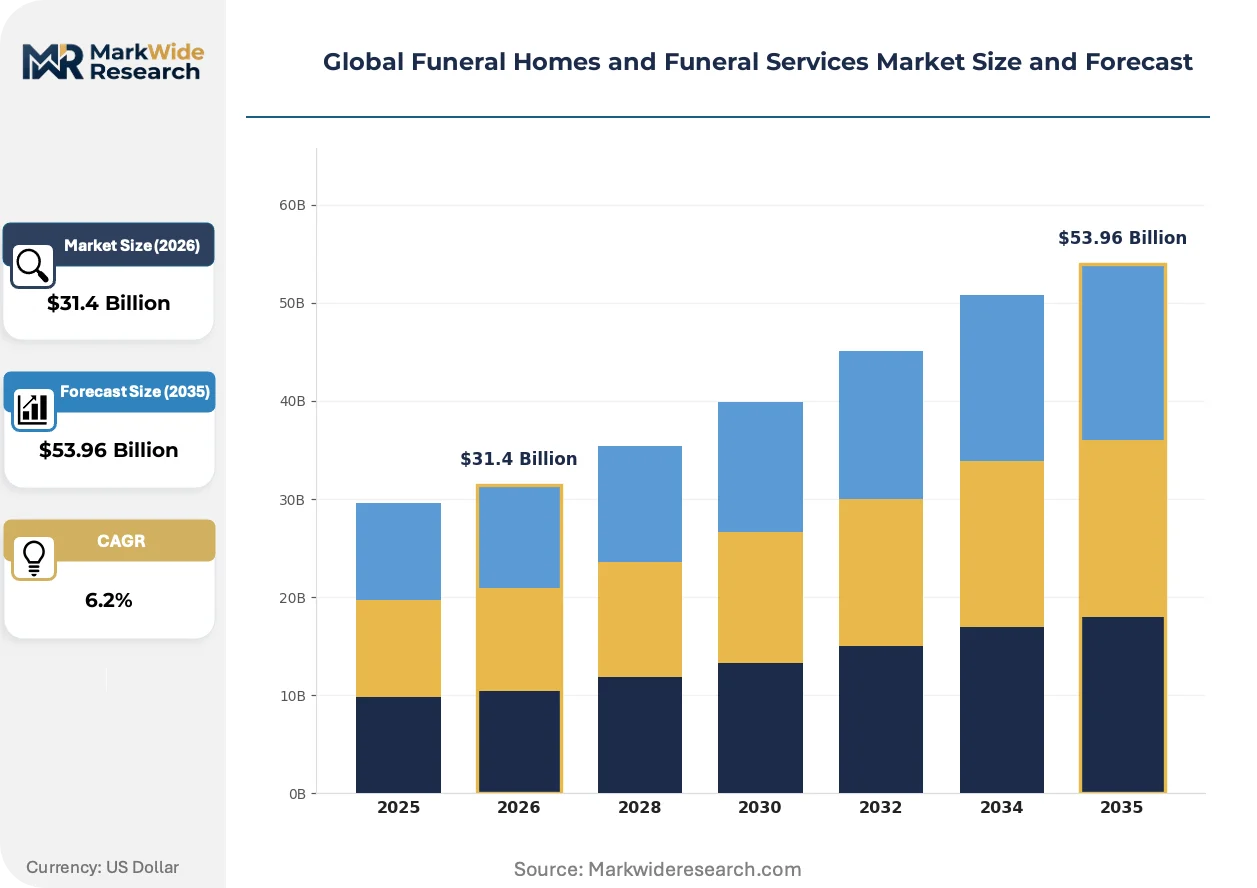
Market Dynamics
Consolidation of independent funeral homes into pre-need sales networks is compressing pricing transparency and forcing legacy operators to adopt digital arrangement platforms or exit metropolitan markets entirely.
Growth Catalysts
- EU Green Deal emission standards:Crematory operators across Germany, France, and Italy are retrofitting filtration systems to meet binding emission caps, creating equipment upgrade cycles and compliance service demand.
- Pre-planning installment financing:Aging cohorts in Japan and the United States are locking in service prices through structured payment plans, expanding operator working capital pools and customer lifetime value.
- Biodegradable container materials:Bamboo fiber and mushroom-based urns are capturing environmentally motivated buyers in Australia and the United Kingdom, opening premium product tiers.
Market Restraints
- Land scarcity for cemetery expansion:Urban plots in Tokyo, London, and Sydney command prices that exclude middle-income families, restricting burial volume growth in dense metropolitan corridors.
- Embalming fluid chemical restrictions:REACH frameworks in the European Union are banning formaldehyde-rich formulations, forcing reformulation costs onto funeral homes with established supplier relationships.
- Direct cremation substitution:No-ceremony disposition is capturing price-sensitive households in the United States and Canada, eroding margin-rich full-service funeral packages.
Strategic Opportunities
- Natural organic reduction:Washington State and Colorado have legalized human composting, creating first-mover licensing advantages for operators investing in alkaline hydrolysis and soil transformation facilities.
- Digital tribute platform integration:Live-streamed memorials and AI-generated life story archives are penetrating underserved rural markets in Spain and Portugal where physical attendance barriers persist.
- Green burial certification expansion:The Green Burial Council's standards are gaining traction among municipal cemetery operators in New Zealand seeking differentiated positioning against commercial crematory chains.
Industry Challenges
- Licensed funeral director shortages:Apprenticeship pipelines in the United States and United Kingdom are failing to replace retiring practitioners, constraining service capacity expansion.
- Crematory retool capex cycles:Mercury abatement and heat-recovery system installations require capital outlays that strain independent operators with limited credit access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Funeral Homes and Funeral Services Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $53.96 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Burial Services, Cremation Services, Memorial Services, Pre-Planning Services Product Type: Caskets, Urns, Memorial Products, Embalming Supplies End User: Private Individuals, Religious Organizations, Funeral Homes, Government Agencies Pricing Model: Standard Packages, Personalized Services, Subscription Plans, Pay-As-You-Go |
| Companies Covered | Service Corporation International, Dignity PLC, InvoCare Limited, Matthews International Corporation, Carriage Services, Park Lawn Corporation, Fu Shou Yuan International Group, Nirvana Asia, San Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Funeral Homes and Funeral Services Market Emerging Trajectories
Digital transformation of arrangement workflows and disposition technologies is fragmenting traditional service bundles while environmental compliance mandates reshape capital deployment priorities across operator tiers.
Alkaline hydrolysis technology uses heated water and potassium hydroxide to accelerate decomposition without flame emissions. Crematory operators in California and Florida are retrofitting existing facilities to accommodate these systems. Water-based disposition is overtaking conventional cremation in jurisdictions with strict air quality enforcement, compressing the installed base of natural gas-fired retorts.
The EU Green Deal's binding crematory emission limits entered force across member states in phases tied to urban airshed classifications. German operators face the strictest nitrogen oxide and mercury thresholds, requiring catalytic afterburners and continuous emissions monitoring. French crematoria in the Île-de-France region are consolidating into shared filtration cooperatives to distribute compliance costs.
Family arrangement patterns are shifting toward self-directed digital planning portals that bypass traditional funeral home consultations. Australian consumers are initiating pre-need contracts through InvoCare's online platforms rather than in-person visits to memorial park locations. This channel migration is most pronounced among metropolitan millennials in Melbourne and Sydney who research price comparisons before engaging licensed directors.
Global Funeral Homes and Funeral Services Market Segmentation
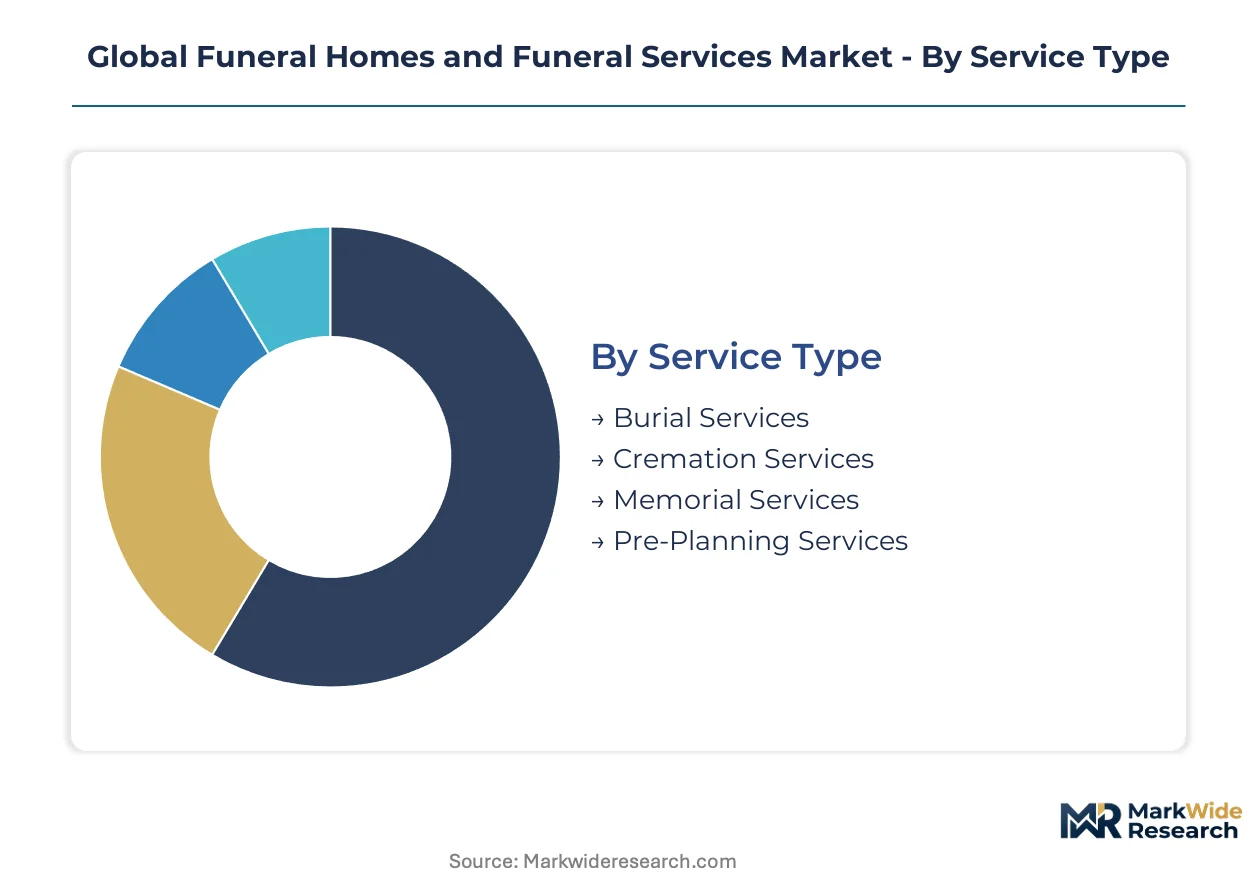
Segmentation in funeral services reveals how operators balance ritual tradition against operational efficiency. Service configuration determines capital intensity, regulatory exposure, and margin structure across geographic markets.
Service Type:
Customization spans from standardized disposition logistics to highly personalized ceremonial programming across this category.
- Burial Services:Traditional interment requires cemetery plot acquisition, grave preparation, and casket placement coordination. Land scarcity in Tokyo, London, and Sydney restricts volume expansion as municipal authorities limit new cemetery development.
- Cremation Services:Flame-based disposition dominates volume in developed markets where religious prohibitions have weakened. EU Green Deal emission standards in Germany and France are forcing retort upgrades and filtration retrofits, elevating compliance costs for independent operators.
- Memorial Services:Ceremony coordination without body present captures demand from families seeking flexible timing and location options.
- Pre-Planning Services:Price-locked arrangements with installment financing structures expand operator working capital pools and customer retention.
Leading the category by volume: Cremation Services. Expanding most quickly: Pre-Planning Services.
Product Type:
Cost tiers separate commodity funeral goods from premium certified alternatives in this category.
- Caskets:Sealed burial containers range from particleboard construction to solid hardwood and metal alloy specifications. Demand concentrates in the United States where FTC Funeral Rule price disclosure requirements pressure bundled pricing strategies.
- Urns:Vessels for cremated remains span biodegradable bamboo fiber, ceramic, and precious metal options. REACH chemical restrictions across the European Union are accelerating substitution away from formaldehyde-treated wooden alternatives.
- Memorial Products:Digital tribute platforms and AI-generated life story archives represent emerging premium categories.
- Embalming Supplies:Chemical formulations for temporary preservation face regulatory pressure from environmental health agencies.
Highest volume concentration: Caskets. Steepest expansion trajectory: Memorial Products.
End User:
Customer type determines service bundling complexity and price sensitivity thresholds across this category.
- Private Individuals:Bereaved families and pre-planning consumers drive the majority of transaction volume. Japanese aging cohorts are accelerating pre-need contract uptake through structured payment plans.
- Religious Organizations:Faith institutions coordinate ritual requirements and cemetery management for affiliated congregations.
- Funeral Homes:Independent operators and consolidated networks procure supplies and subcontract specialized services.
- Government Agencies:Municipal and state entities manage indigent disposition and public cemetery operations.
Dominant transaction volume: Private Individuals. Gaining share fastest: Funeral Homes through consolidation.
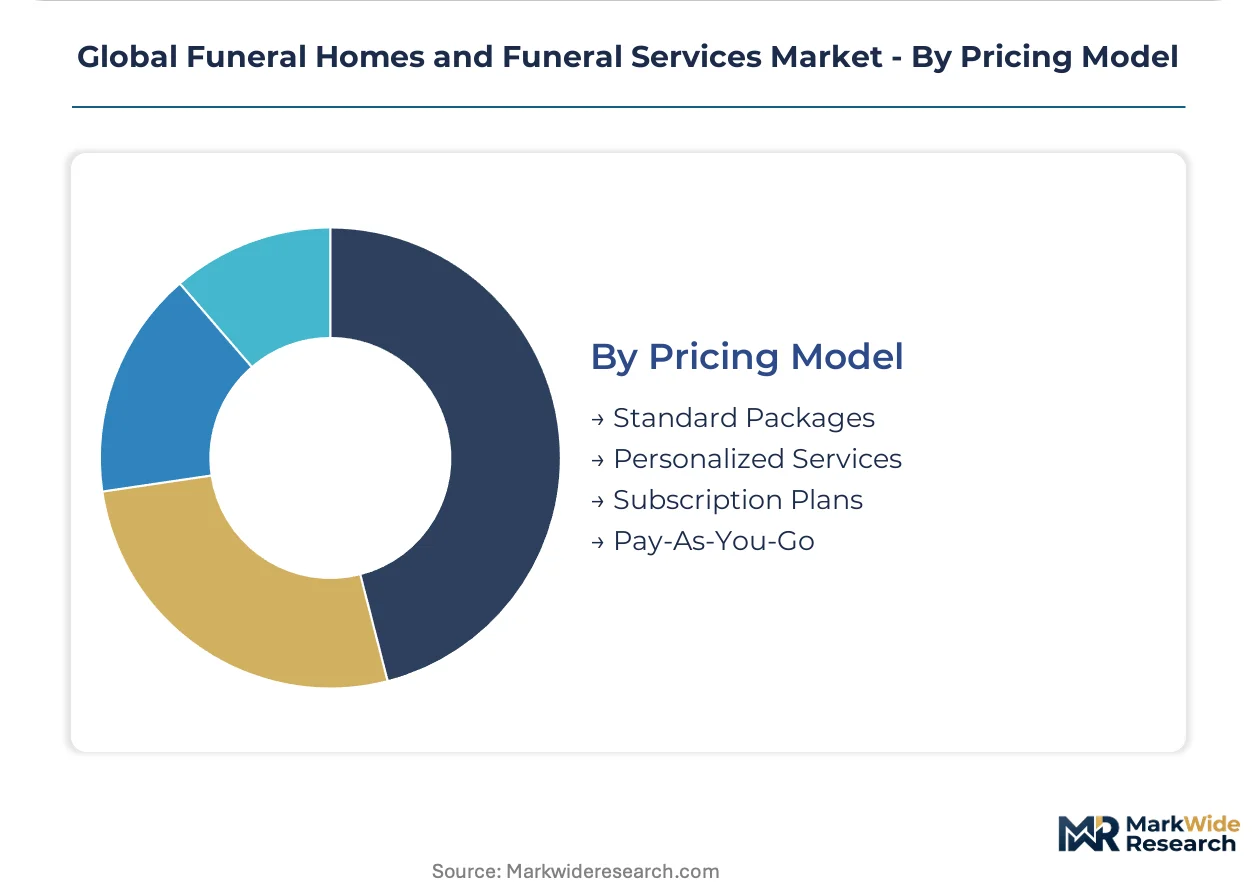
Pricing Model:
Margin structure varies dramatically between fixed-package certainty and open-ended service customization in this category.
- Standard Packages:Bundled service combinations with predetermined price points simplify consumer comparison. Australian consumers increasingly initiate contracts through digital portals rather than in-person consultations.
- Personalized Services:À la carte selection of individual service elements accommodates non-traditional ceremony preferences.
- Subscription Plans:Recurring payment structures for memorial maintenance and digital tribute hosting extend customer relationships.
- Pay-As-You-Go:Transactional pricing for discrete services appeals to price-sensitive households seeking direct cremation alternatives.
Volume leadership: Standard Packages. Climbing the fastest: Subscription Plans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cemetery land scarcity in Tokyo, London, and Sydney anchors geographic variation in service mix and pricing structures across major markets. Regulatory divergence between cremation-friendly jurisdictions and burial-preserving regions determines capital allocation toward flame-based or natural organic reduction technologies.
United States
Pre-need contract financing and direct cremation substitution are reshaping operator revenue models. The FTC Funeral Rule mandates itemized price disclosure, pressuring opaque bundled pricing strategies. Consolidation concentrates in urban corridors across Texas, Florida, and California where independent funeral homes face acquisition pressure from pre-need sales networks.
Japan
Aging cohorts are accelerating pre-planning uptake through structured installment payment plans. The Ministry of Health, Labour and Welfare oversees funeral business licensing and cemetery land use restrictions that limit new market entry. Tokyo's extreme plot scarcity is driving demand toward high-rise columbaria and digital memorial alternatives.
Germany
EU Green Deal emission standards are forcing retort upgrades and catalytic afterburner installations. The strictest nitrogen oxide and mercury thresholds in Europe apply to crematoria in the Ruhr industrial corridor. Operators in North Rhine-Westphalia are consolidating into shared filtration cooperatives to distribute compliance costs.
Australia
Digital arrangement platforms are displacing in-person consultations among metropolitan millennials. The Green Burial Council's certification standards are gaining traction among municipal cemetery operators in New South Wales. InvoCare's vertically integrated cemetery, crematorium, and memorial park assets anchor market share in Sydney and Melbourne.
United Kingdom
Price-transparent alternatives are eroding brand recognition for traditional high-street funeral locations. REACH chemical restrictions are accelerating substitution away from formaldehyde-treated wooden urns. London's burial plot costs now exclude middle-income families, restricting interment volume growth.
Global Funeral Homes and Funeral Services Market Vendor Landscape
Global majors compete with regional champions across cemetery-crematory asset combinations and pre-need sales network density. The market structure tiers between scale-driven consolidators with vertically integrated death care platforms and independent operators serving local ritual preferences. Three archetypes dominate: multinational death care conglomerates with property-heavy balance sheets, regional cemetery-crematory specialists, and price-disruptive direct cremation platforms. Competitive moves center on metropolitan market consolidation and digital arrangement platform deployment.
Within the multinational tier, Service Corporation International and Dignity PLC exemplify scale-driven positioning through property-dense networks across North America and the United Kingdom respectively. Fu Shou Yuan International Group occupies a position among Asia-Pacific operators with concentration in Greater China markets. These three represent divergent geographic anchoring strategies—Americas-focused, European-focused, and Asia-focused—while sharing reliance on cemetery real estate and pre-need contract financing as core business model elements.
| Leading Market Players |
|---|
| Service Corporation International |
| Dignity PLC |
| InvoCare Limited |
| Matthews International Corporation |
| Carriage Services |
| Park Lawn Corporation |
| Fu Shou Yuan International Group |
| Nirvana Asia |
| San Holdings |
| Others |
Supply Flow & Price Mechanics
Casket-grade hardwood and metal alloy feedstock costs cascade through three distinct pricing strata before reaching bereaved families, with FTC-mandated itemization exposing margin structures that previously hid within opaque service bundles.
Pricing Analysis
Service-bundling configurations separate full-service ceremonial packages from unbundled direct cremation alternatives, with the former commanding substantial premiums through licensed director coordination and venue provision. Three-tier pricing structure across premium, standard, and economy levels reflects casket material grade, cemetery plot location tier, and memorial product sophistication. Cost compression in the economy tier is intensifying because direct cremation platforms strip ceremony coordination from value propositions. Private individuals arranging at-need services exhibit highest price sensitivity, while pre-planning consumers locking installment contracts show lowest sensitivity due to psychological distance from immediate payment.
Supply Chain Analysis
Regional distribution centers for casket manufacturers concentrate in the United States, China, and Mexico, with hub-and-spoke patterns radiating toward metropolitan funeral home networks and memorial park locations. Casket production draws from North American hardwood forests, Chinese metal fabrication clusters, and Italian marble quarries for premium memorial markers. Single-source vulnerability pervades formaldehyde-based embalming chemical supply, with REACH restrictions forcing rapid supplier transitions across European markets. Distribution runs through manufacturer-direct relationships with consolidated operator networks, bypassing traditional wholesale intermediaries that served independent funeral homes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in funeral services hinges on controlling cemetery-crematory real estate and pre-need contract financing infrastructure, with operators racing to secure scarce urban land parcels and lock customer lifetime value through installment structures.
For Market Incumbents: Anchor market position through accelerated acquisition of independent funeral homes in metropolitan corridors where land scarcity prevents new entrant facility construction. Consolidate pre-need sales networks to capture installment financing pools before regional competitors establish customer relationships. Defensive priority centers on securing alkaline hydrolysis licensing in jurisdictions where EU Green Deal emission standards are tightening fastest.
For New Entrants and Emerging Players: Capture white-space opportunity in digital tribute platform integration, where underserved rural markets in Southern Europe and Latin America lack live-streamed memorial infrastructure. Natural organic reduction services present the most penetrable segment, with Washington State and Colorado licensing frameworks creating first-mover regulatory pathways. Go-to-market execution should emphasize direct-to-consumer digital arrangement portals that bypass traditional funeral home consultation requirements.
For Investors and Strategic Acquirers: EU Green Deal enforcement waves are the leading indicator that crematory filtration retrofit cycles will concentrate independent operators into distressed sale positions. Long-term viability favors property-heavy balance sheets with vertically integrated cemetery-crematory-memorial park assets across multiple metropolitan clusters. Acquisition target archetype: regional operators with pre-need contract backlogs and unencumbered urban real estate in land-constrained jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Cemetery-Crematory Asset Acquisition | Urban land scarcity in Tokyo, London, and Sydney prevents competitive replication of established footprints. |
| Pre-Need Sales Network Expansion | Installment financing structures lock customer lifetime value and expand operator working capital pools. |
| Alkaline Hydrolysis Facility Licensing | Washington State and Colorado regulatory frameworks create first-mover advantages in water-based disposition. |
| Digital Arrangement Platform Deployment | Metropolitan millennials in Melbourne and Sydney initiate contracts through online portals rather than in-person visits. |
| Green Burial Certification Program | The Green Burial Council's standards differentiate municipal cemetery operators against commercial crematory chains in New Zealand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with funeral home operators, cemetery management executives, licensed funeral directors, and pre-need sales specialists. Secondary sources encompassed FTC enforcement actions, EU Green Deal implementation documents, Japanese Ministry of Health licensing registries, and cemetery land use permits. Bottom-up triangulation across service type volumes and top-down validation against national mortality statistics ensured cross-verification of market sizing.
Granularity-level modeling disaggregated revenue across service type, product category, end-user segment, and pricing model dimensions throughout the projection horizon. CAGRs were derived from segment-specific growth trajectories weighted by base-year revenue contribution. Industry-specific forecast inputs incorporated cremation rate projections by jurisdiction, pre-planning contract penetration curves, and regulatory compliance cost escalations tied to EU emission standard phase-ins.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cremation substitution rates, cemetery land availability restrictions, and licensed funeral director pipeline constraints. Forecasts reflect documented assumptions regarding mortality trends, regulatory enforcement intensity, and consumer preference evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Global Hospice Care Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Spa Services Market
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
European Union Cross Border Healthcare Market