
 Latin America Paper Making Machine Market | 2026-2036
Latin America Paper Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Paper Making Machine Market Insights
Modular rebuild and component-upgrade packages is expanding as a preferred procurement model among Latin American mills seeking to extend asset life without full line replacement. Voith Paper Brazil leverages its local assembly footprint to shorten delivery cycles for Brazilian pulp-to-paper integrators. Valmet Corporation competes through remote diagnostics and energy-efficiency retrofit bundles tailored to aging Fourdrinier installations. ANDRITZ AG anchors its regional position with stock preparation and approach flow systems that integrate with third-party forming sections.
A paper making machine is an integrated system of stock preparation, forming, pressing, drying, and finishing equipment designed to convert pulp slurry into continuous paper web at controlled basis weights, moisture content, and caliper specifications. The forming section employs vacuum-assisted dewatering on woven synthetic fabrics to achieve initial solids content of eighteen to twenty-two percent before the press section. Fourdrinier configurations retain dominant installed capacity across Latin America due to versatility in packaging and printing grades, though specialty machines for molded fiber and barrier-coated food service applications are gaining traction among Mexican converters. Mechanical drive technology still occupies the majority of legacy installations, while hybrid electrification of sectional drives is displacing traditional line-shaft arrangements in greenfield projects seeking energy recovery.
Brazil's IBAMA environmental licensing and Mexico's SEMARNAT wastewater discharge standards shape capital equipment decisions by mandating closed-loop water systems and reduced effluent loads. CE marking alignment through ECHA REACH-compliant materials certification increasingly determines import eligibility for European-sourced machinery entering Mercosur trade zones. Stakeholders must monitor how proposed EU deforestation-free supply chain regulations transmit through cellulose sourcing requirements into Latin American mill investment timelines.
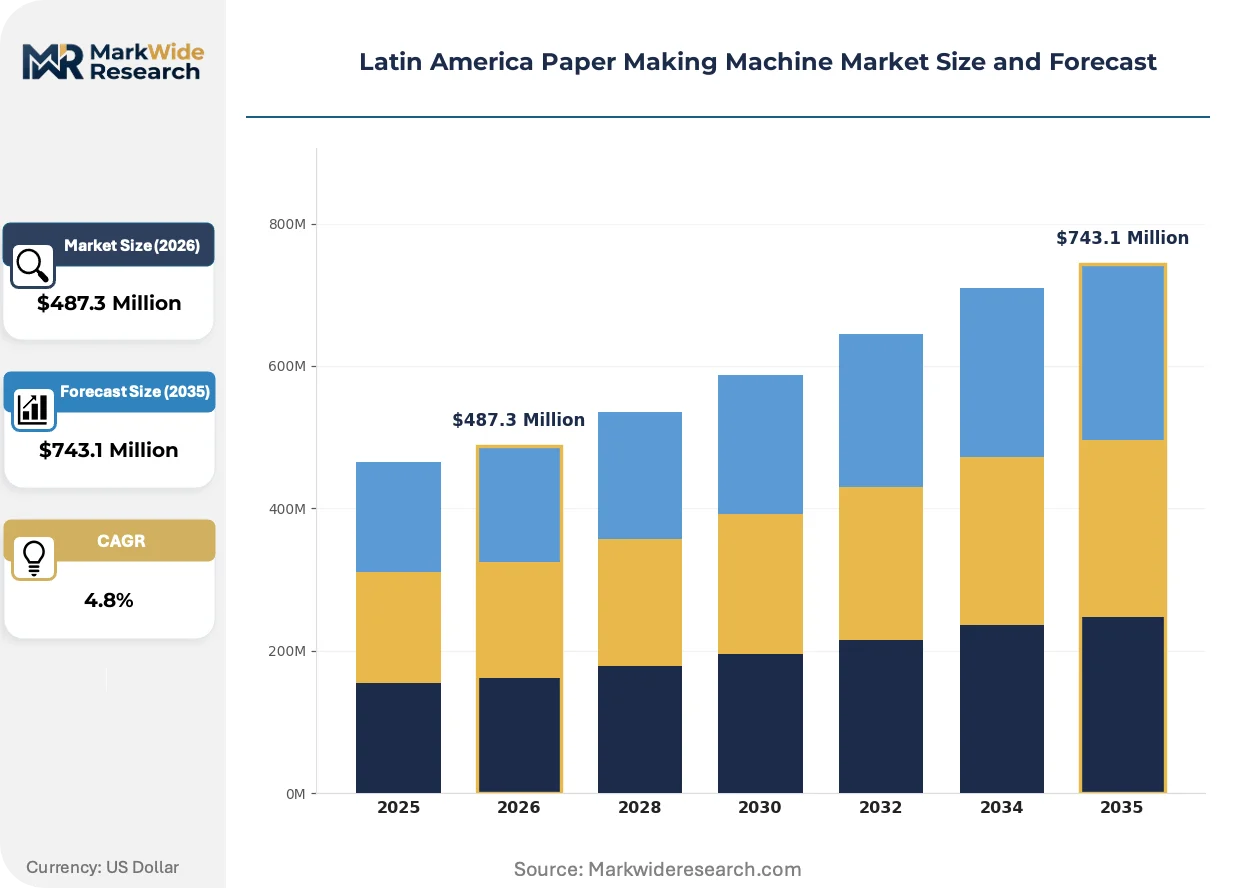
Market Dynamics
Modular rebuild packages are displacing greenfield investments across Latin American mills as environmental licensing timelines under Brazil's IBAMA compress capital deployment windows and extend payback periods on full line replacements.
Growth Catalysts
- E-commerce fulfillment demand:Packaging converters in São Paulo and Monterrey are expanding corrugated capacity to serve regional fulfillment networks, driving press section upgrades and dryer section retrofits.
- IBAMA water-efficiency mandates:Brazil's environmental regulator requires closed-loop white water systems for new pulp-to-paper integrations, accelerating demand for approach flow rebuilds with fiber recovery.
- Recycled fiber processing:Deinking and dispersion equipment installations are expanding as Mexican mills source post-consumer OCC for export-grade linerboard production.
Market Restraints
- Capital equipment import tariffs:Mercosur's industrial machinery duties elevate landed costs for European and Asian forming section components by fifteen to twenty-five percent.
- Specialized technician scarcity:Brazil's SENAI vocational pipeline produces insufficient hydraulic and drive system specialists for sectional electrification retrofits.
- Forming fabric supply concentration:Woven synthetic clothing for Fourdrinier sections concentrates among three global suppliers, creating lead time vulnerability for Colombian converters.
Strategic Opportunities
- Colombian Bogotá corridor expansion:Underpenetrated versus São Paulo and Monterrey, this cluster offers first-mover positioning for stock preparation system providers.
- Barrier-coated food service grades:Mexican converters are piloting molded fiber lines for single-use food containers, creating specialty machine demand outside commodity packaging.
- CE marking alignment:ECHA REACH-compliant materials certification is unlocking Mercosur import eligibility for European rebuild specialists previously excluded by technical barriers.
Industry Challenges
- Legacy mechanical drive integration:Hybrid electrification retrofits on aging line-shaft installations demand custom torque-matching engineering that stretches commissioning timelines.
- Cross-border certification reciprocity:Mexican SEMARNAT effluent standards and Brazilian CONAMA resolutions lack mutual recognition, complicating multi-country mill operator equipment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Paper Making Machine Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fourdrinier, Cylinder, Specialty, Others End User: Packaging, Printing, Tissue, Newsprint Technology: Mechanical, Electrical, Hybrid, Pneumatic Form: Sheet, Roll, Bulk, Board |
| Companies Covered | Voith Paper Brazil, Hergen Paper Machinery, Voith GmbH & Co. KGaA, Valmet Corporation, ANDRITZ AG, Kadant Inc., Bellmer GmbH, A.Celli Group, International Paper Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Paper Making Machine Market Trends and Innovations
Remote diagnostics platforms are compressing maintenance response times across Latin American installations while energy-recovery dryers and vacuum system optimization reshape operating cost structures for aging asset bases.
Hybrid electrification of sectional drives is integrating regenerative braking and variable frequency control into formerly mechanical line-shaft configurations. Brazilian pulp-to-paper integrators are adopting this technology fastest among regional buyers, prioritizing energy recovery over speed gains. The technology is integrating formerly separate drive and process control architectures, reducing spare parts diversity and maintenance crew specialization requirements.
SEMARNAT's 2023 wastewater discharge amendments are tightening BOD and suspended solids limits for Mexican paper mills. Industrial consequence includes mandatory dissolved air flotation upgrades for existing mills and pre-treatment system bundling in new equipment procurement. Specialty grade producers in Monterrey and Guadalajara are responding fastest, retrofitting approach flow systems ahead of corrugated specialists.
After-sales service unbundling is fragmenting traditional full-service contracts across Latin American mill procurement. Brazilian operators are separating spare parts logistics from technical service, sourcing components through independent distributors while retaining OEM specialists for commissioning. This pattern is most visible in São Paulo's industrial corridor, where maintenance outsourcing to third-party technical services firms has compressed OEM attachment rates by one-third.
Latin America Paper Making Machine Market Segmentation
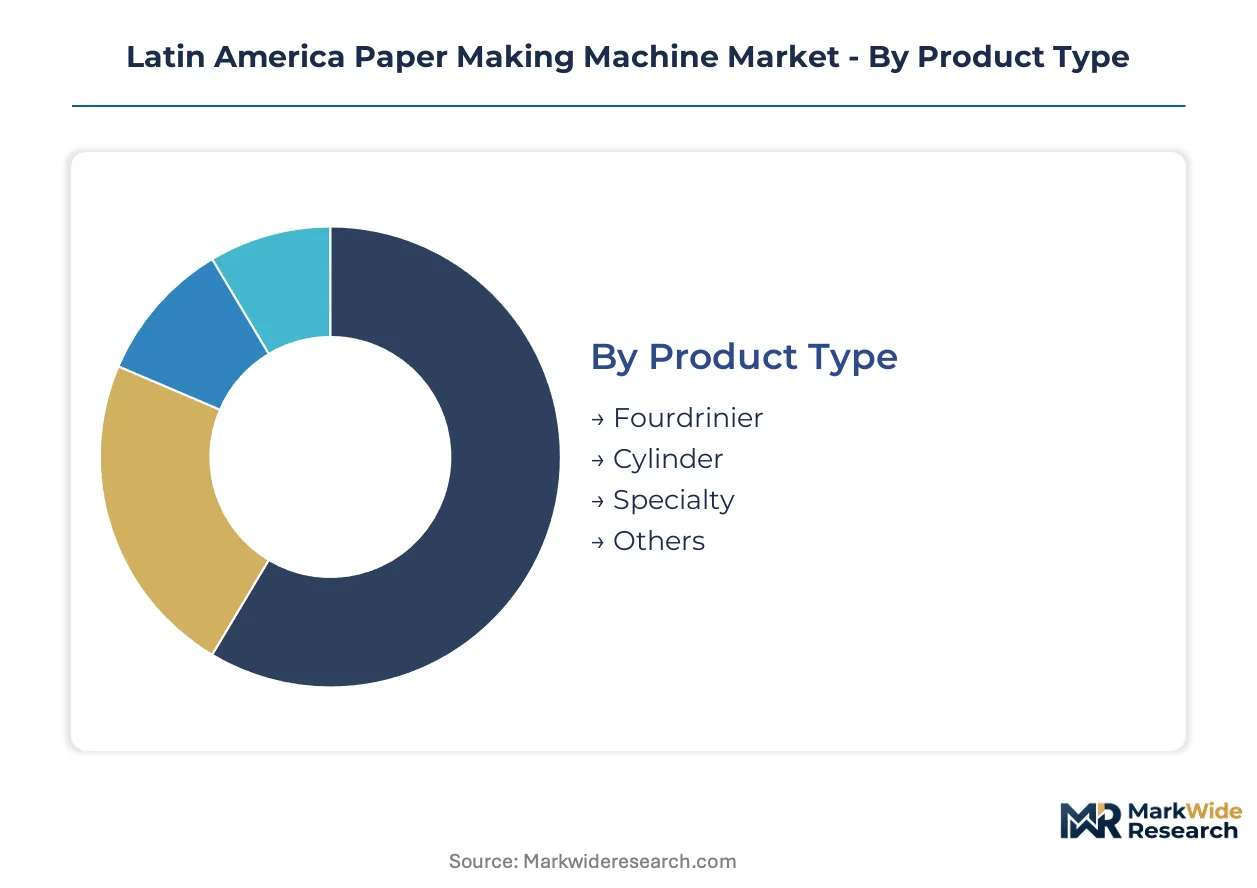
Paper making machine procurement in Latin America diverges sharply between standardized commodity configurations and engineered specialty lines. Equipment specification varies by fiber source, grade target, and regulatory compliance tier across Brazilian, Mexican, and Colombian mill operations.
Product Type:
Customization intensity spans from mass-produced Fourdrinier platforms to application-engineered specialty configurations with modular forming sections.
- Fourdrinier:Vacuum-assisted dewatering on woven synthetic fabrics achieves initial solids content of eighteen to twenty-two percent before pressing. São Paulo packaging converters deploy these for corrugated linerboard and medium production serving e-commerce fulfillment networks.
- Cylinder:Multi-cylinder configurations stack vat-formed sheets for heavyweight board grades. Mexican mills in Monterrey favor this technology for folding carton stock requiring uniform caliper across barrier-coated food service applications.
- Specialty:Molded fiber and advanced forming configurations for single-use food containers.
- Others:Twin-wire and gap-forming variants for specific pulp integrations.
Most installed capacity flows through Fourdrinier configurations. Expansion is steepest in Specialty lines for barrier-coated food service grades.
End User:
Volume concentration versus margin capture divides procurement patterns across grade-specific mill investments.
- Packaging:Corrugated and folding carton production dominates capital deployment. Brazilian São Paulo state industrial corridor leads regional capacity additions for e-commerce boxboard and linerboard.
- Tissue:Creping and through-air drying configurations for consumer towel and bathroom tissue. Colombian Bogotá region shows underpenetrated demand relative to São Paulo and Monterrey clusters.
- Printing:Uncoated woodfree and coated mechanical grades for commercial publishing.
- Newsprint:Declining investment trajectory as digital substitution compresses Latin American publishing demand.
Capital commitment concentrates in Packaging. Tissue represents the fastest-growing end-use trajectory among greenfield investments.
Technology:
Energy recovery potential versus retrofit complexity shapes technology migration across legacy and new-build mill portfolios.
- Hybrid:Integrates regenerative braking and variable frequency control into formerly mechanical line-shaft arrangements. Brazilian pulp-to-paper integrators adopt this fastest, prioritizing energy recovery over speed gains in IBAMA-licensed installations.
- Mechanical:Traditional line-shaft drive systems retain majority legacy installed base across aging Latin American assets.
- Electrical:Full sectional electrification with distributed drive architectures for greenfield projects.
- Pneumatic:Compressed air systems for specific forming and conveying applications.
Mechanical systems anchor existing capacity. Hybrid configurations are gaining share fastest in retrofit procurement.
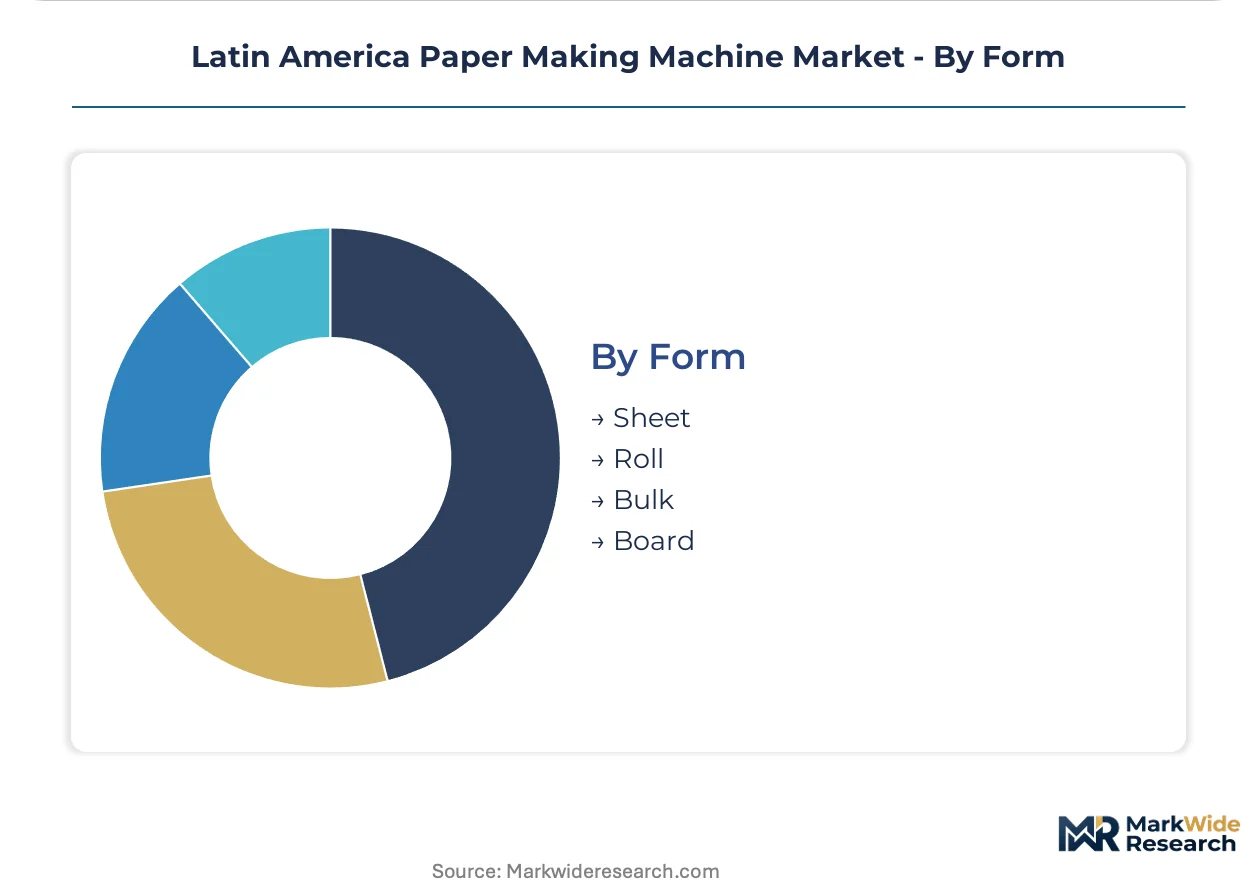
Form:
Downstream integration depth determines whether mills ship commodity roll stock or finished converted products.
- Roll:Parent roll output for external converting operations. Mexican OCC-based linerboard mills supply regional corrugators in Monterrey and Guadalajara manufacturing clusters.
- Sheet:Cut-size and folio deliveries for commercial printing and office product channels.
- Board:Heavyweight cartonboard for folding carton converters serving food and consumer goods packaging.
- Bulk:Pulp bale and intermediate fiber formats for integrated mill complexes.
Roll format commands highest shipment volumes. Board configuration expands most quickly with vertical integration into folding carton production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper making machine deployment across Latin America traces its industrial lineage to mid-20th century European and North American capital imports that established São Paulo and Monterrey as continental manufacturing anchors.
Brazil
IBAMA licensing requirements for closed-loop water systems drive approach flow rebuilds among São Paulo state pulp-to-paper integrators. The regulator's 2024 effluent discharge amendments compress capital deployment windows for greenfield projects. São Paulo's industrial corridor concentrates the heaviest equipment demand, with packaging converters upgrading Fourdrinier sections for e-commerce linerboard production.
Mexico
SEMARNAT's tightened BOD and suspended solids limits mandate dissolved air flotation upgrades across Monterrey and Guadalajara mill operations. The 2023 wastewater discharge amendments force specialty grade producers to retrofit approach flow systems ahead of corrugated specialists. Monterrey's manufacturing cluster leads regional capacity additions for barrier-coated food service applications.
Colombia
Underpenetrated demand relative to São Paulo and Monterrey creates first-mover positioning for stock preparation system providers in Bogotá's industrial corridor. The country's national environmental regulator enforces water-efficiency standards that accelerate fiber recovery equipment procurement. Bogotá region tissue producers show fastest-growing greenfield investment trajectory among Andean mills.
Chile
Pulp-to-paper integration projects in the Bío Bío Region drive demand for hybrid electrification retrofits on legacy mechanical drive installations. The country's environmental assessment service lengthens licensing timelines for full line replacements, favoring modular rebuild packages. Concepción industrial complexes prioritize energy recovery over speed gains in sectional drive upgrades.
Argentina
Mercosur industrial machinery duties elevate landed costs for European forming section components by fifteen to twenty-five percent across Buenos Aires province mills. The country's national industrial technology institute promotes local assembly partnerships to circumvent import tariff exposure. Greater Buenos Aires packaging converters concentrate demand for cylinder machine configurations in folding carton stock production.
Latin America Paper Making Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling intensity, with full-lifecycle contractors commanding pricing power over component-only suppliers. The vendor base organizes into three strategic archetypes: integrated full-line OEMs with local assembly footprints, specialized rebuild contractors focusing on sectional upgrades, and independent distributors unbundling spare parts from technical service. Dominant competitive moves include geographic expansion through Brazilian and Mexican local assembly investments and technology licensing partnerships for hybrid drive electrification.
Among Germany-based engineering conglomerates, Voith GmbH & Co. KGaA and ANDRITZ AG exemplify integrated full-line OEM archetypes with regional assembly positioning. Voith Paper Brazil represents the local subsidiary model that shortens delivery cycles for Brazilian pulp-to-paper integrators. Finland-based Valmet Corporation occupies a position within the remote diagnostics and energy-efficiency retrofit specialist tier. These three anchors demonstrate how European rebuild specialists leverage CE marking alignment through ECHA REACH-compliant materials certification to unlock Mercosur import eligibility previously blocked by technical barriers.
| Leading Market Players |
|---|
| Voith Paper Brazil |
| Hergen Paper Machinery |
| Voith GmbH & Co. KGaA |
| Valmet Corporation |
| ANDRITZ AG |
| Kadant Inc. |
| Bellmer GmbH |
| A.Celli Group |
| International Paper Company |
| Others |
Pricing and Supply Chain Analysis
Brazilian pulp-to-paper integrators anchor procurement volume in São Paulo's industrial corridor, concentrating buyer power around project-based equipment contracts with modular rebuild bundling. This buyer concentration feeds pricing stratification across premium OEM full-line systems, standard sectional upgrade packages, and economy-tier component sourcing through independent distributors.
Pricing Analysis
Project-based capital equipment contracting with multi-year service bundling dominates Latin American mill procurement. Price differentiation rests on CE marking alignment for Mercosur import eligibility and after-sales service intensity across rebuild versus greenfield configurations. Cost compression in standard-tier sectional upgrades is intensifying because Brazilian SENAI vocational pipeline gaps stretch commissioning timelines and elevate technician premiums. Commodity packaging converters in Monterrey show highest price sensitivity, while specialty-grade producers piloting barrier-coated food service lines accept premium positioning for application-engineered configurations.
Supply Chain Analysis
ECHA REACH-compliant materials certification gates European machinery import eligibility into Mercosur trade zones, filtering supplier participation. Equipment assembly concentrates in Germany, Finland, and Brazil through Voith Paper Brazil's local footprint and ANDRITZ regional partnerships. Raw material dependencies span woven synthetic forming fabrics, high-alloy dryer cylinders, and precision drive components. Single-source vulnerability concentrates in forming fabric supply among three global weavers. Distribution runs through OEM-direct project contracting for full-line systems, with independent distributors capturing component aftermarket share in São Paulo and Monterrey clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's paper making machine market functions as a geographic-arbitrage play where European OEMs leverage CE marking alignment to circumvent Mercosur technical barriers while Brazilian local assembly partnerships neutralize industrial machinery duties.
For Market Incumbents: Anchor regional position through backward integration into Brazilian recycled fiber processing equipment and Colombian stock preparation system assembly. Hybrid electrification retrofit capacity represents a critical lever against emerging Asian competitors. Defend margin position by unbundling spare parts logistics from technical service to match Brazilian operator procurement fragmentation. For New Entrants and Emerging Players: Launch via independent distributor partnerships targeting Bogotá corridor tissue producers, the most underpenetrated greenfield investment cluster relative to São Paulo and Monterrey. Barrier-coated food service grade specialty lines offer white-space positioning outside commodity packaging saturation. Prioritize ECHA REACH materials certification to unlock Mercosur import eligibility ahead of technical barrier enforcement. For Investors and Strategic Acquirers: European engineering conglomerates with regional assembly footprints are the most active acquirer in this space, seeking technology licensing partnerships for hybrid drive electrification. Acquisition target archetypes include specialized rebuild contractors with sectional upgrade expertise and independent distributors with spare parts logistics scale. Watch for IBAMA licensing timeline compression as an inflection indicator accelerating modular procurement preference over greenfield investments.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Brazilian duty neutralization through Voith Paper Brazil's regional footprint shortens delivery cycles for pulp-to-paper integrators. |
| Hybrid Drive Electrification Licensing | Technology transfer agreements enable energy recovery retrofit penetration across aging Latin American mechanical drive installations. |
| After-Sales Service Unbundling | São Paulo operator separation of spare parts logistics from technical service compresses OEM attachment rates by one-third. |
| ECHA REACH Certification Investment | Materials compliance unlocks Mercosur import eligibility previously blocked by technical barriers for European rebuild specialists. |
| Colombian Corridor Expansion | Bogotá tissue producer greenfield investments offer first-mover positioning for stock preparation system providers. |
Research Methodology
Multiple input streams — primary interviews with mill maintenance directors, OEM procurement teams, and aftermarket service heads; secondary validation through customs trade data, IBAMA licensing records, and SEC equipment supplier filings; plus industry association capacity surveys — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured equipment specification priorities across Brazilian, Mexican, and Colombian mill operations. Secondary sources included forming fabric supplier disclosures, SEMARNAT wastewater amendment documentation, and regional pulp-to-paper integration project announcements.
Data-stream reconciliation across product type, end-use grade, technology migration pathway, and geographic regulatory cluster enabled segmentation-specific modeling. CAGRs were derived through installed base depreciation curves overlaid with greenfield and retrofit investment pipelines. Industry-specific forecast inputs incorporated IBAMA environmental licensing timeline compression effects and SEMARNAT dissolved air flotation upgrade mandates across Mexican mill operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU deforestation-free supply chain regulation transmission into Latin American cellulose sourcing requirements. Model assumptions reflect IBAMA and SEMARNAT regulatory trajectories, eucalyptus pulp price volatility, and Mercosur tariff policy continuity. A model refresh is warranted upon material change in EU supply chain due diligence enforcement timelines or Brazilian environmental licensing procedural reform.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market