
 Africa Heavy Construction Equipment Rental Market | 2026-2036
Africa Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Heavy Construction Equipment Rental Market Analytics
The Africa heavy construction equipment rental market is recalibrating around a widening split between premium full-service contracts and commodity spot rentals. United Rentals leverages its technology platform to command premium rates on telematics-enabled fleets across North African oil and gas corridors. Talisman Hire anchors its position in Southern Africa through deep maintenance capabilities that reduce client downtime on mining sites. Byrne Equipment Rental differentiates via project-based service models tailored to infrastructure timelines in the Gulf region.
Heavy construction equipment rental encompasses the temporary provision of mechanized earthmoving, lifting, and grading machinery with operating weights exceeding 15 metric tons, typically delivered with operator training, maintenance scheduling, and fuel management protocols to minimize capital lock-up for project owners. Excavators and cranes dominate fleet composition due to their versatility across construction, mining, and infrastructure verticals, with long-term rental contracts capturing the most stable margin pools as clients prioritize predictable cost structures over seasonal flexibility. Short-term and project-based arrangements serve oil and gas exploration cycles where rig mobilization demands surge capacity for limited durations.
South Africa's Department of Labour enforces Construction Regulations requiring documented equipment inspection certificates, while Nigeria's Federal Ministry of Works mandates compliance with SON standards for imported machinery, and Egypt's Ministry of Trade and Industry applies GB/T-equivalent conformity assessments on Chinese-sourced equipment entering Suez Canal development zones. These overlapping compliance frameworks elevate barriers for unverified suppliers and concentrate procurement authority with rental firms maintaining certified technical teams. Stakeholders must monitor how evolving local content requirements reshape cross-border fleet deployment strategies.
Market Dynamics
South Africa's Construction Regulations under the Department of Labour are compressing procurement timelines as contractors scramble for rental partners with pre-certified maintenance documentation. This regulatory pressure is fragmenting the supplier base between compliant fleet operators and informal equipment brokers.
Growth Catalysts
- Copper-cobalt extraction expansion:Mining operators in Zambia and the Democratic Republic of Congo are scaling rental fleets to meet electrification-driven metal demand without capital-intensive equipment purchases.
- Port modernization mandates:Nigeria's Federal Ministry of Works is accelerating crane and excavator deployment along the Lagos-Ibadan corridor for container throughput expansion.
- Telematics integration:IoT-enabled fleet monitoring is reducing idle-time losses for oil and gas contractors across North African exploration corridors.
Market Restraints
- Diesel price volatility:Fuel constitutes 35-45% of operating costs for heavy equipment, exposing rental margins to subsidy removal shocks in Egypt and Nigeria.
- Chinese equipment import friction:Egypt's Ministry of Trade and Industry applies GB/T-equivalent conformity assessments that delay Chinese-sourced fleet entry into Suez Canal development zones.
- Skilled operator scarcity:Certified equipment inspectors remain concentrated in Johannesburg and Cape Town, constraining fleet expansion into secondary mining districts.
Strategic Opportunities
- East African underpenetration:Tanzania's Standard Gauge Railway and Ethiopian dam construction create vacuum for rental providers with hydro-mechanical specialization.
- Local content requirements:Zambia's mining charter amendments are mandating domestic equipment procurement percentages, favoring rental firms with local maintenance facilities.
- Modular crushing systems:Convergence of mobile screening technology with rental financing is opening quarry and aggregate verticals previously served by owned equipment.
Industry Challenges
- Certification backlog compression:South Africa's Department of Labour inspection queues are extending equipment deployment timelines by 6-8 weeks for non-pre-certified rental fleets.
- Parts supply chain fragmentation:OEM spare parts distribution remains concentrated in Durban and Lagos ports, inflating downtime costs for remote mining site operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Heavy Construction Equipment Rental Market |
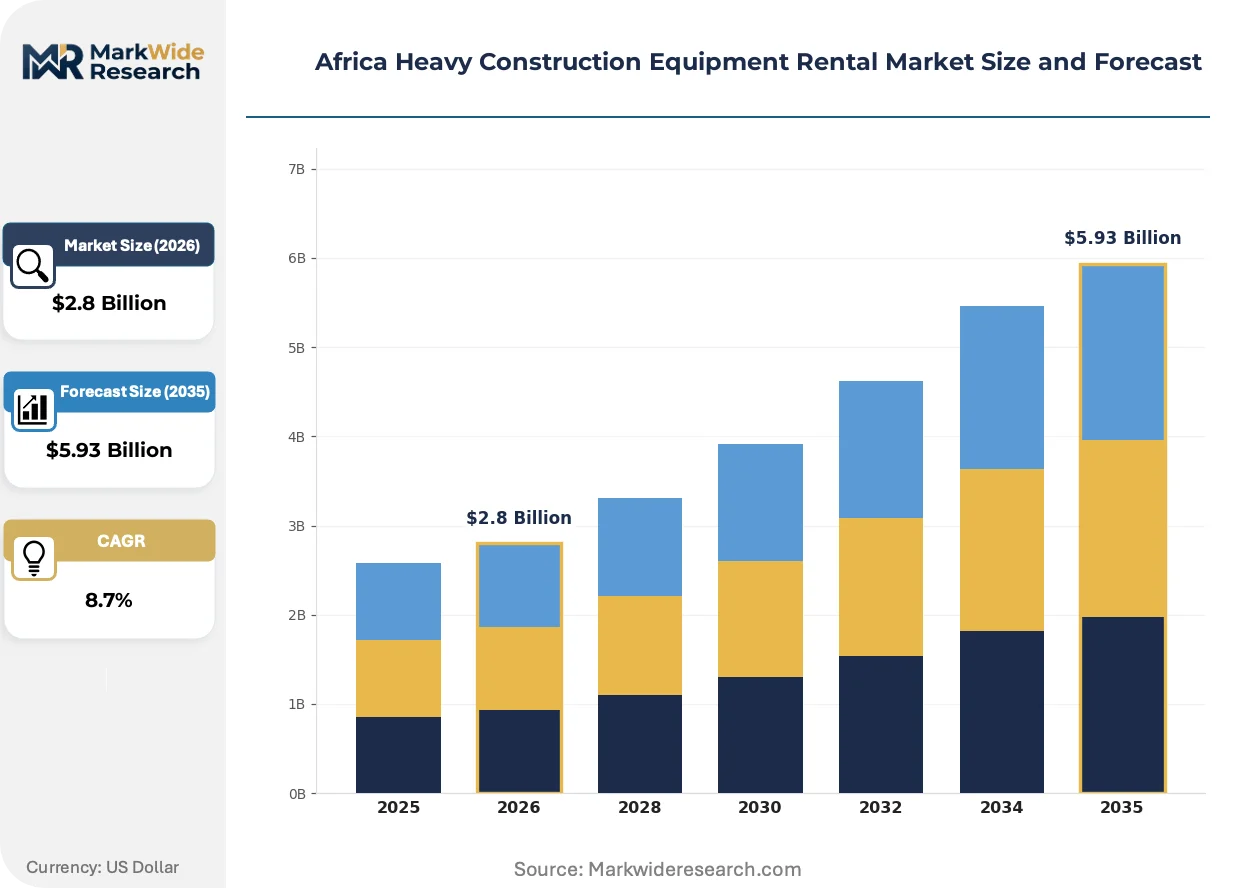
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Graders, Cranes End User: Construction, Mining, Infrastructure, Oil & Gas Rental Duration: Short-Term, Long-Term, Seasonal, Project-Based Service Model: On-Site, Off-Site, Full-Service, Limited-Service |
| Companies Covered | Sunbelt Rentals, Ashtead Group, Talisman Hire, Al Faris, Byrne Equipment Rental, Ramirent, United Rentals, Mohamed Abdulrahman Al-Bahar, Loxam, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Heavy Construction Equipment Rental Market Evolving Landscape
Telematics platforms are compressing the information asymmetry between rental providers and project owners. Equipment utilization data now flows in real-time, enabling dynamic pricing models that penalize idle capacity and reward continuous deployment cycles.
Condition-based monitoring systems are unifying vibration analysis, hydraulic pressure sensing, and engine diagnostics into single-dashboard fleet health visibility. Mining contractors in the Copperbelt are adopting these systems fastest, driven by underground downtime costs exceeding $15,000 per hour. This convergence is compressing maintenance intervals from calendar-based to actual-wear triggers, extending equipment service life and reducing catastrophic failure rates on remote sites.
Egypt's GB/T-equivalent conformity assessment regime for Chinese-sourced machinery is creating a two-tier import market. Equipment meeting the technical documentation requirements gains expedited customs clearance for Suez Canal Economic Zone projects, while non-compliant shipments face 90-120 day inspection queues. Infrastructure contractors are responding by pre-qualifying rental partners with established Chinese OEM relationships and in-country technical validation capabilities.
Project owners are unbundling operator training from equipment rental contracts, sourcing certified equipment handlers through specialized labor brokers instead of bundled fleet packages. This decoupling is most visible in Nigeria's highway expansion sector, where the Federal Ministry of Works mandates SON-certified operator credentials independent of equipment provenance. Rental providers are responding with bare-metal lease rates and separate training certification partnerships to preserve margin on the core equipment component.
Africa Heavy Construction Equipment Rental Market Segmentation
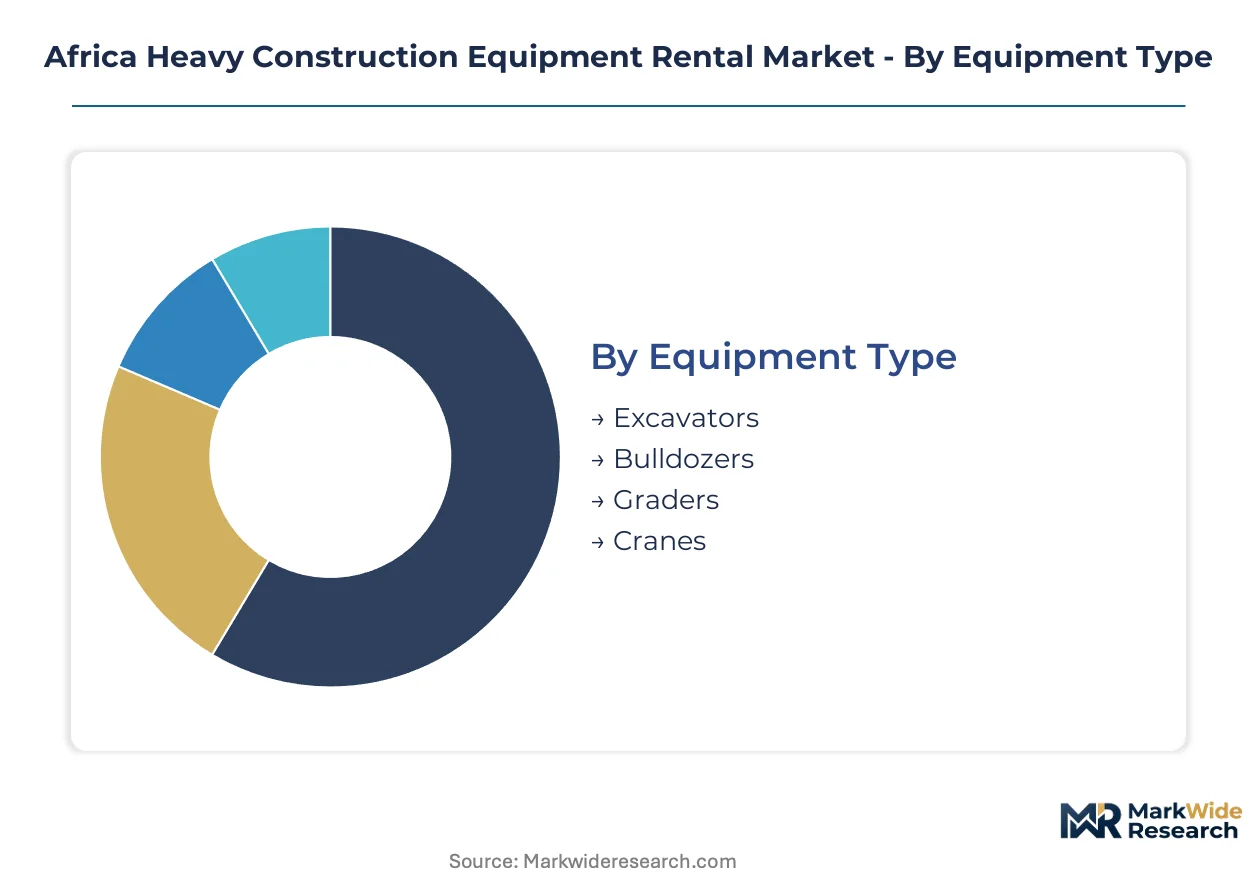
Equipment rental decisions in Africa hinge on deployment duration, site remoteness, and regulatory compliance burdens. Segmentation reveals where rental providers capture premium margins versus commodity spot markets.
Equipment Type:
Standalone machinery dominates spot rental demand, while integrated fleet packages anchor long-term mining contracts.
- Excavators:Hydraulic crawler and wheeled variants with bucket capacities from 0.5 to 4 cubic meters handle trenching, loading, and demolition across construction and quarry operations. Demand clusters in Nigeria's Lagos-Ibadan corridor where port modernization and highway expansion require sustained deployment; telematics-enabled units command 15-20% rate premiums over baseline fleet.
- Cranes:Mobile all-terrain and crawler configurations span 50-750 ton lifting capacities for infrastructure and energy sector verticals. Mining operators in Zambia's Copperbelt favor 200-ton plus crawler cranes for concentrator construction; certified inspection documentation from South Africa's Department of Labour compresses procurement timelines for compliant rental providers.
- Bulldozers:Track-type tractors with 200-850 horsepower ratings serve earthmoving and ripping applications in mining overburden removal.
- Graders:Motor graders with 12-16 foot moldboards deliver precision surface finishing for road construction and mine haul road maintenance.
Volume placements concentrate in excavators; the faster expansion belongs to cranes.
End User:
Capital intensity and project predictability separate high-margin contracted segments from volatile spot markets.
- Mining:Copper-cobalt extraction in Zambia and the Democratic Republic of Congo drives fleet scaling without capital-intensive equipment purchases. Electrification-driven metal demand pushes operators toward rental models that preserve balance sheet flexibility; long-term contracts with embedded maintenance clauses capture the most stable margin pools.
- Infrastructure:Port modernization, railway construction, and dam projects span multi-year timelines requiring equipment continuity. Tanzania's Standard Gauge Railway and Ethiopian dam construction create demand vacuums for rental providers with hydro-mechanical specialization; project finance structures favor predictable rental cost structures over ownership.
- Construction:Residential and commercial building activity generates seasonal demand spikes with lower equipment utilization rates.
- Oil & Gas:Exploration cycles in North African corridors require surge capacity for limited rig mobilization durations.
Revenue concentration sits with mining; infrastructure is climbing the fastest.
Rental Duration:
Contract structure determines maintenance responsibility allocation and rate negotiation leverage.
- Long-Term:Multi-year agreements with embedded operator training and preventive maintenance schedules minimize capital lock-up for project owners. South Africa's certified inspection requirements push contractors toward rental partners with pre-qualified documentation; these contracts capture premium margins through predictable cost structures.
- Project-Based:Timeline-bound arrangements aligned to construction phases or exploration cycles match equipment supply to defined work scopes. Oil and gas contractors across North African corridors favor this model for rig mobilization surges; unbundled operator training preserves margin on the core equipment component.
- Short-Term:Daily and weekly spot rentals serve emergency replacement and peak season overflow needs.
- Seasonal:Agricultural and quarry operations generate predictable annual demand windows with lower rate premiums.
Margin stability flows to long-term; project-based arrangements are expanding most quickly.
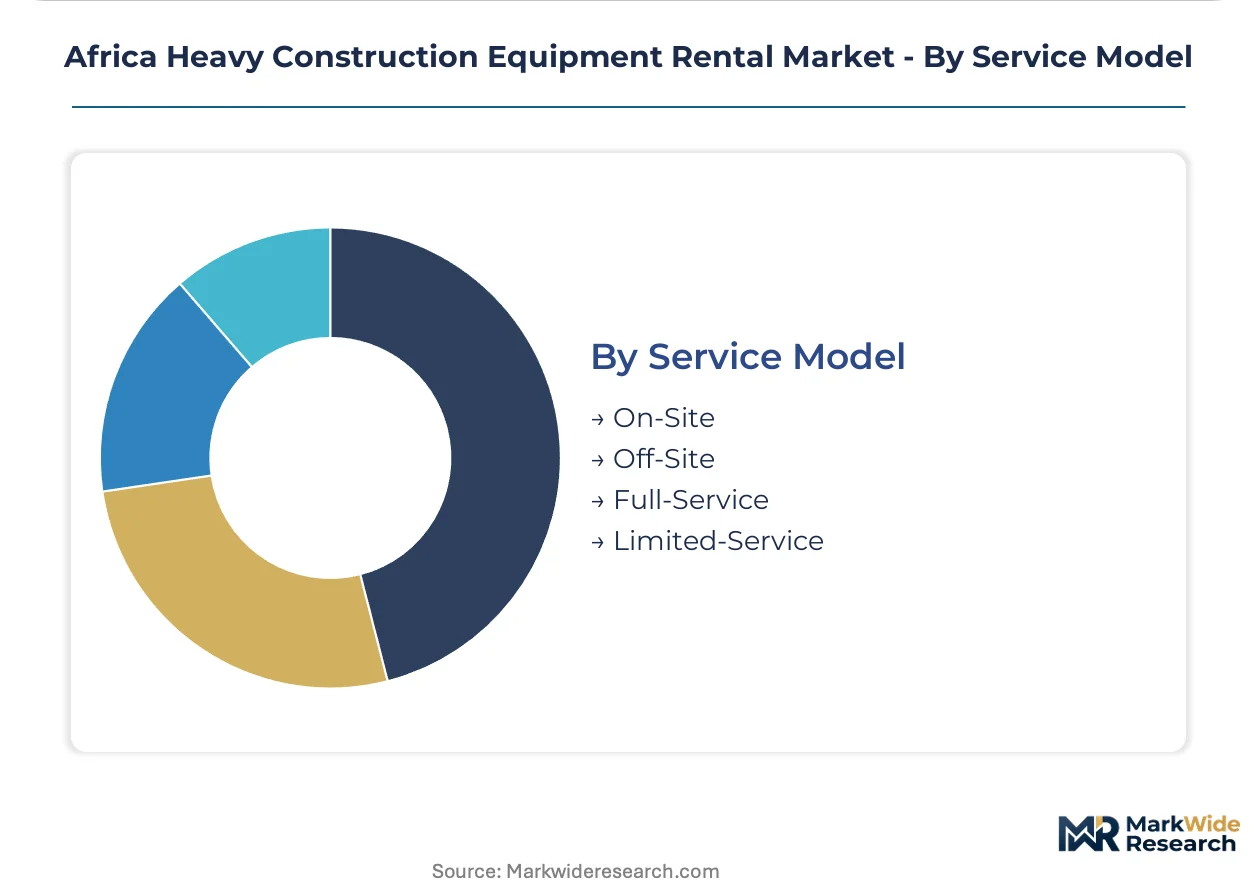
Service Model:
Technical capability depth separates premium full-service providers from bare-metal commodity competitors.
- Full-Service:Bundled packages encompassing equipment delivery, certified operator provision, fuel management, and preventive maintenance reduce client administrative burden. Talisman Hire anchors Southern Africa market position through deep maintenance capabilities that reduce downtime on remote mining sites; compliance with South Africa's Construction Regulations creates procurement preference.
- On-Site:Embedded technical teams and maintenance infrastructure positioned at client locations accelerate response times for critical failures. Underground downtime costs exceeding $15,000 per hour in Zambia's Copperbelt drive adoption; condition-based monitoring systems unify diagnostics into single-dashboard visibility.
- Limited-Service:Equipment-only rentals with client-assumed maintenance responsibility target price-sensitive contractors.
- Off-Site:Centralized maintenance depots with periodic equipment rotation serve lower-utilization applications.
Contract value pools in full-service; on-site deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors rental equipment deployment across Nigeria's busiest construction corridor, with the Lagos-Ibadan highway expansion and port modernization projects sustaining crane and excavator demand through multi-year timelines.
South Africa
Johannesburg and Cape Town concentrate certified equipment inspectors, creating procurement bottlenecks for contractors seeking compliant rental partners. The Department of Labour's Construction Regulations mandate documented inspection certificates, compressing timelines for pre-certified fleet operators. Mining districts in the Northern Cape and Limpopo face equipment deployment delays of 6-8 weeks due to certification backlogs.
Zambia
Copperbelt mining operations drive fleet scaling for copper-cobalt extraction without capital-intensive equipment purchases. The country's mining charter amendments mandate domestic equipment procurement percentages, favoring rental firms with local maintenance facilities. Kitwe and Ndola serve as the primary equipment logistics hubs for underground operations.
Nigeria
Federal Ministry of Works mandates for port modernization accelerate crane deployment along the Lagos-Ibadan corridor. SON standards compliance requirements for imported machinery elevate barriers for unverified suppliers. Container throughput expansion at Lagos Port Complex sustains long-term rental contracts with predictable cost structures.
Egypt
Suez Canal development zones attract equipment rental demand for infrastructure corridors. The Ministry of Trade and Industry applies GB/T-equivalent conformity assessments on Chinese-sourced machinery, creating expedited customs clearance for compliant shipments. Non-compliant equipment faces 90-120 day inspection queues, concentrating procurement with pre-qualified rental partners.
Democratic Republic of Congo
Electrification-driven cobalt demand pushes mining operators toward rental models preserving balance sheet flexibility. Kolwezi and Lubumbashi anchor equipment logistics for remote extraction sites. Long-term contracts with embedded maintenance clauses capture the most stable margin pools in this high-downtime-cost environment.
Africa Heavy Construction Equipment Rental Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification and maintenance documentation capabilities. The supplier base fragments between fleet operators with pre-certified technical teams and informal equipment brokers lacking inspection documentation. Three archetypes dominate: full-service providers bundling maintenance and operator training, technology-enabled platforms commanding rate premiums on telematics fleets, and regional specialists with deep mining site relationships. Competitive moves concentrate on M&A for fleet scale and strategic partnerships for OEM spare parts distribution.
Within the full-service tier, Talisman Hire anchors Southern Africa positioning through maintenance capabilities reducing client downtime. United Rentals exemplifies the technology-enabled archetype with telematics platforms commanding premium rates. Byrne Equipment Rental occupies a position in project-based service models tailored to infrastructure timelines across North African and Gulf corridors.
| Leading Market Players |
|---|
| Sunbelt Rentals |
| Ashtead Group |
| Talisman Hire |
| Al Faris |
| Byrne Equipment Rental |
| Ramirent |
| United Rentals |
| Mohamed Abdulrahman Al-Bahar |
| Loxam |
| Others |
Value Network & Pricing Analysis
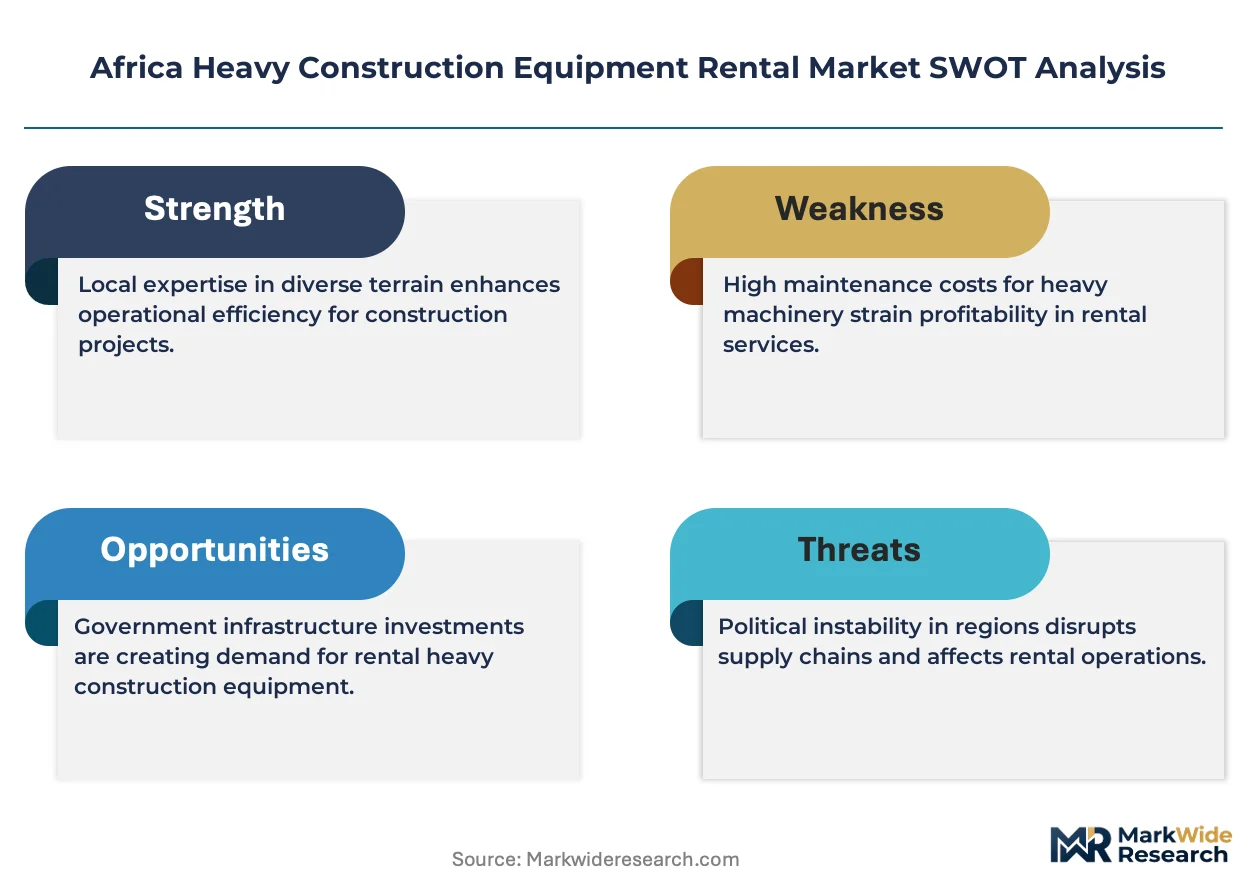
South Africa's Department of Labour inspection mandates are compressing contractor procurement timelines and forcing rapid supplier consolidation around pre-certified fleet operators. This regulatory pressure is reshaping how rental providers structure rate cards and where they position maintenance assets.
Pricing Analysis
Equipment uptime guarantees anchor value-based pricing for telematics-enabled fleets, with providers commanding rate premiums of 15-20% over baseline units in Nigeria's Lagos-Ibadan corridor. Price differentiation hinges on certification documentation grade and embedded maintenance bundling, while cost compression in spot rental tiers intensifies due to diesel price volatility across Egypt and Nigeria. Mining contractors show lowest price sensitivity, prioritizing downtime avoidance over per-day rates, whereas residential construction buyers drive commoditization in short-term excavator markets.
Supply Chain Analysis
Pre-qualified technical documentation gates equipment entry into Suez Canal development zones and South African mining districts, compressing supplier lists to compliant fleet operators. Manufacturing concentrates in China, Germany, and Japan for core earthmoving machinery, while aftermarket parts distribution rests on Durban and Lagos port infrastructure. Single-source vulnerability runs through OEM spare parts channels serving remote Zambian Copperbelt operations. Distribution runs through project-based logistics partnerships aligned to infrastructure timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as rental providers pursue captive maintenance capabilities to defend margin against compliance-driven procurement consolidation.
For Market Incumbents: Deepen on-site technical team deployment at remote mining clusters to reduce client downtime costs exceeding $15,000 per hour in Zambia's Copperbelt. Expand backward integration into OEM spare parts distribution through Durban and Lagos port partnerships to compress response times. Certification investment in South Africa's Department of Labour pre-approval programs creates procurement preference against informal equipment brokers. For New Entrants and Emerging Players: Small-scale infrastructure contractors in Tanzania's Standard Gauge Railway corridor represent an underserved buyer archetype with unmet demand for hydro-mechanical specialized fleets. Ethiopian dam construction sites offer white-space entry points for rental providers with condition-based monitoring capabilities. A project-based service model with unbundled operator training partnerships preserves margin while meeting Federal Ministry of Works credential mandates. For Investors and Strategic Acquirers: The window for entry favors rental firms with established Chinese OEM relationships and in-country GB/T-equivalent validation capabilities for Egyptian Suez Canal zone access. Long-term viability centers on multi-year mining contracts with embedded maintenance clauses capturing stable margin pools. Watch for Zambia's mining charter local content enforcement as an inflection signal for domestic facility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time utilization data enables dynamic pricing models penalizing idle capacity across North African oil corridors. |
| Backward Integration into Parts Distribution | Captive spare parts channels through Durban and Lagos ports reduce downtime costs for remote mining operations. |
| Certification Pre-Approval Investment | South Africa's Department of Labour compliance creates 6-8 week procurement advantages over non-certified competitors. |
| Local Maintenance Facility Buildout | Zambia's mining charter amendments mandate domestic procurement percentages favoring in-country service infrastructure. |
| Project-Based Service Model Deployment | Unbundled operator training partnerships align with Nigeria's SON-certified credential requirements while preserving equipment margins. |
Research Methodology
Multi-period observation of fleet utilization rates, certification queue lengths, and rental contract structures anchored the trend analysis, supplemented by interviews with mining operations managers, infrastructure project procurement leads, equipment maintenance directors, and OEM distribution channel heads. Secondary validation drew from customs import records, Department of Labour inspection filings, mining charter amendment texts, and Suez Canal Economic Zone development disclosures. Bottom-up equipment deployment tracking across Zambia, Nigeria, South Africa, Egypt, and the Democratic Republic of Congo triangulated against top-down market sizing.
The input-output matrix framed projections across equipment type, end-use vertical, rental duration structure, and service model tier. Segmentation modeling captured excavator, crane, bulldozer, and grader deployment patterns alongside mining, infrastructure, construction, and oil and gas demand drivers. CAGRs were derived from fitted trend extrapolation validated against project pipeline announcements and capital expenditure disclosures. Diesel price volatility indices and Chinese equipment import friction metrics informed scenario-weighted outputs across the projection horizon.
Revisions become necessary when regulatory inspection mandates expand to additional African jurisdictions or when local content requirements shift procurement thresholds in mining charter amendments. Forecasts reflect assumptions about telematics adoption velocity and OEM spare parts channel stability. A model refresh is warranted upon material change in Chinese equipment conformity assessment enforcement at Egyptian ports.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Dredge Automation Market