
 Global Construction Machinery Market | 2026-2036
Global Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Machinery Market Analysis
The gap between premium and commodity construction machinery is recalibrating around engine certification tiers and telematics integration rather than raw horsepower alone. Caterpillar leverages its captive engine manufacturing to control emissions compliance costs across product lines. Komatsu Ltd. anchors its position through autonomous haulage systems that differentiate service contracts from hardware sales.
Construction machinery encompasses self-propelled and towed equipment engineered to perform earthmoving, material handling, and vertical lifting operations, with hydraulic systems typically operating at pressures exceeding 3,000 psi and power ratings spanning 50 to 4,000 horsepower for heavy excavators. These machines serve as capital-intensive production tools for civil engineering, resource extraction, and building erection where cycle time and fuel efficiency determine project economics. Excavators command the largest installed base among product types due to versatility across trenching, demolition, and material loading workflows. Diesel technology still dominates revenue volumes though electric and hybrid configurations are capturing disproportionate interest from European rental companies facing municipal emission restrictions. Contractors represent the most fragmented end user segment, creating pricing pressure that favors manufacturers with dense aftermarket parts networks.
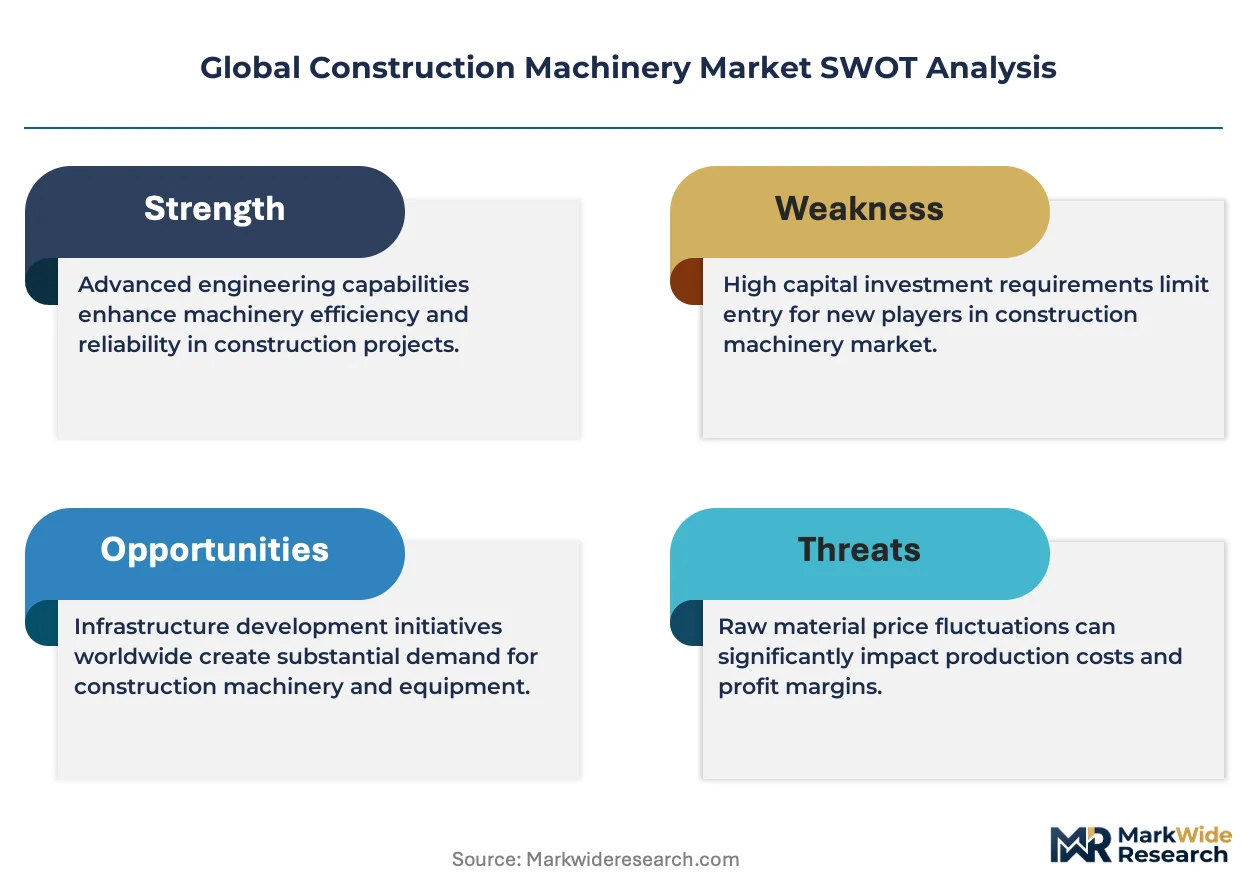
The EPA and EU Stage V frameworks are forcing engine redesigns that add cost to mid-range loaders and bulldozers while creating compliance barriers for smaller Chinese exporters. China's MIIT enforces domestic emission standards that increasingly align with European testing protocols, reshaping which foreign suppliers qualify for state-procurement tenders. ISO 10987 durability testing requirements are becoming a baseline qualifier for mining fleet contracts in Australia and Canada. Stakeholders must weigh whether to absorb certification costs across volume tiers or retreat to premium niches where compliance premiums pass through more cleanly.
Market Dynamics
Engine certification tiers and fleet electrification mandates are bifurcating competitive positioning between integrated manufacturers and component-dependent assemblers across the value chain.
Growth Catalysts
- EU Stage V emission standards:Tightening certification requirements accelerate replacement cycles for aging diesel fleets in Germany and France. Rental companies face municipal restrictions that favor compliant new equipment.
- Autonomous haulage systems:Mining operators in Australia and Chile expand fleet electrification programs that demand integrated telematics and remote operation capabilities.
- China's western provinces:State-funded rail and dam projects concentrate equipment procurement where domestic emission standards increasingly align with European testing protocols.
Market Restraints
- Engine redesign costs:EPA and EU Stage V frameworks add compliance expense to mid-range loaders and bulldozers, compressing margins for volume-tier producers.
- Chinese supply concentration:Smaller exporters face certification barriers as MIIT enforces domestic standards that reshape state-procurement tender qualifications.
- Steel and hydraulic component volatility:Input cost swings destabilize production planning for manufacturers without captive forging or casting capacity.
Strategic Opportunities
- Underpenetrated electric configurations:European rental companies disproportionately favor hybrid and battery-electric machines facing municipal emission restrictions.
- ISO 10987 durability testing:Mining fleet contracts in Australia and Canada increasingly require this baseline qualifier, creating service differentiation for certified suppliers.
- Telematics integration:Convergence of IoT sensors and predictive maintenance platforms enables outcome-based service contracts that separate hardware from recurring revenue.
Industry Challenges
- Embedded systems engineering talent:Shortage of software developers capable of integrating autonomous control with legacy hydraulic architectures slows product roadmaps.
- Retrofit certification timelines:Existing fleet conversions to meet Stage V or China VI standards face prolonged homologation processes with national type-approval authorities.
- Dealer network reconfiguration:Transition from parts-and-service models to data-subscription support strains traditional distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Machinery Market |
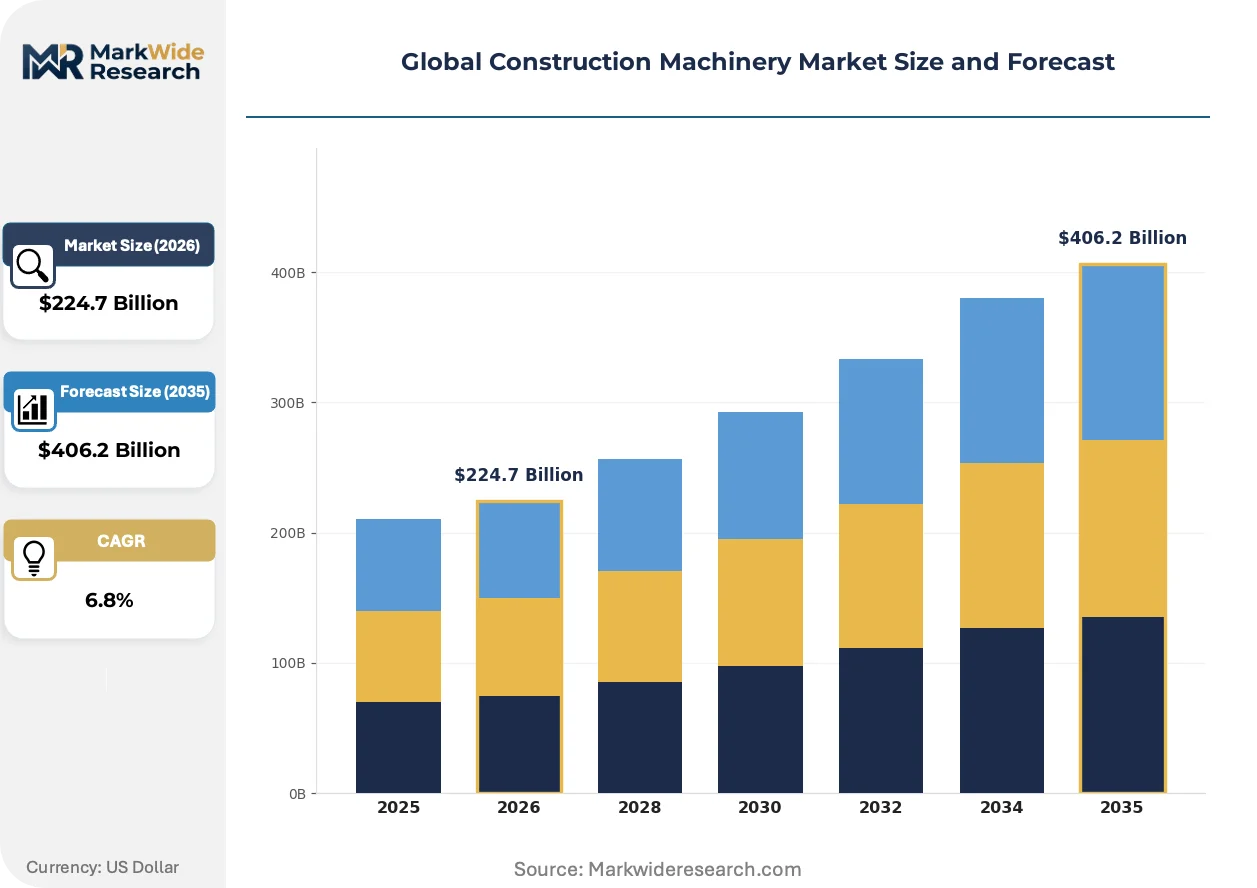
| Market Size in 2026 | $224.7 Billion |
| Market Size in 2035 | $406.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Loaders, Cranes Application: Infrastructure, Mining, Agriculture, Demolition End User: Contractors, Government, OEMs, Rental Companies Technology: Diesel, Electric, Hybrid, Automation |
| Companies Covered | Caterpillar, Komatsu Ltd., Deere & Company, XCMG Group, SANY Group, Liebherr Group, Hitachi Construction Machinery, Volvo Construction Equipment, Zoomlion Heavy Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Machinery Market Emerging Trajectories
Electrification architectures and autonomous control systems are recalibrating how equipment capability is packaged, sold, and serviced across civil engineering and resource extraction verticals.
Battery-electric powertrains are decentralizing equipment deployment patterns. Remote mining sites in Chile and Western Australia adopt off-grid charging infrastructure that untethers fleet operations from diesel fuel logistics. Site operators now specify machines based on energy autonomy windows rather than tank capacity, compressing the traditional advantage of high-horsepower diesel dominance.
REACH chemical restrictions and F-Gas Regulation phase-down schedules are forcing hydraulic fluid reformulation across European-registered equipment. Biodegradable synthetic alternatives penetrate trenching and water-adjacent applications where spill liability concentrates. German and French contractors now pre-qualify suppliers based on fluid compliance documentation ahead of equipment performance benchmarks.
Rental fleet managers are unbundling maintenance contracts from equipment leases. Large civil contractors in Spain and Italy negotiate hourly-availability guarantees where OEMs retain ownership risk. This consumption-pattern shift transfers residual-value exposure to manufacturers while compressing capital deployment for end-users.
Global Construction Machinery Market Segmentation
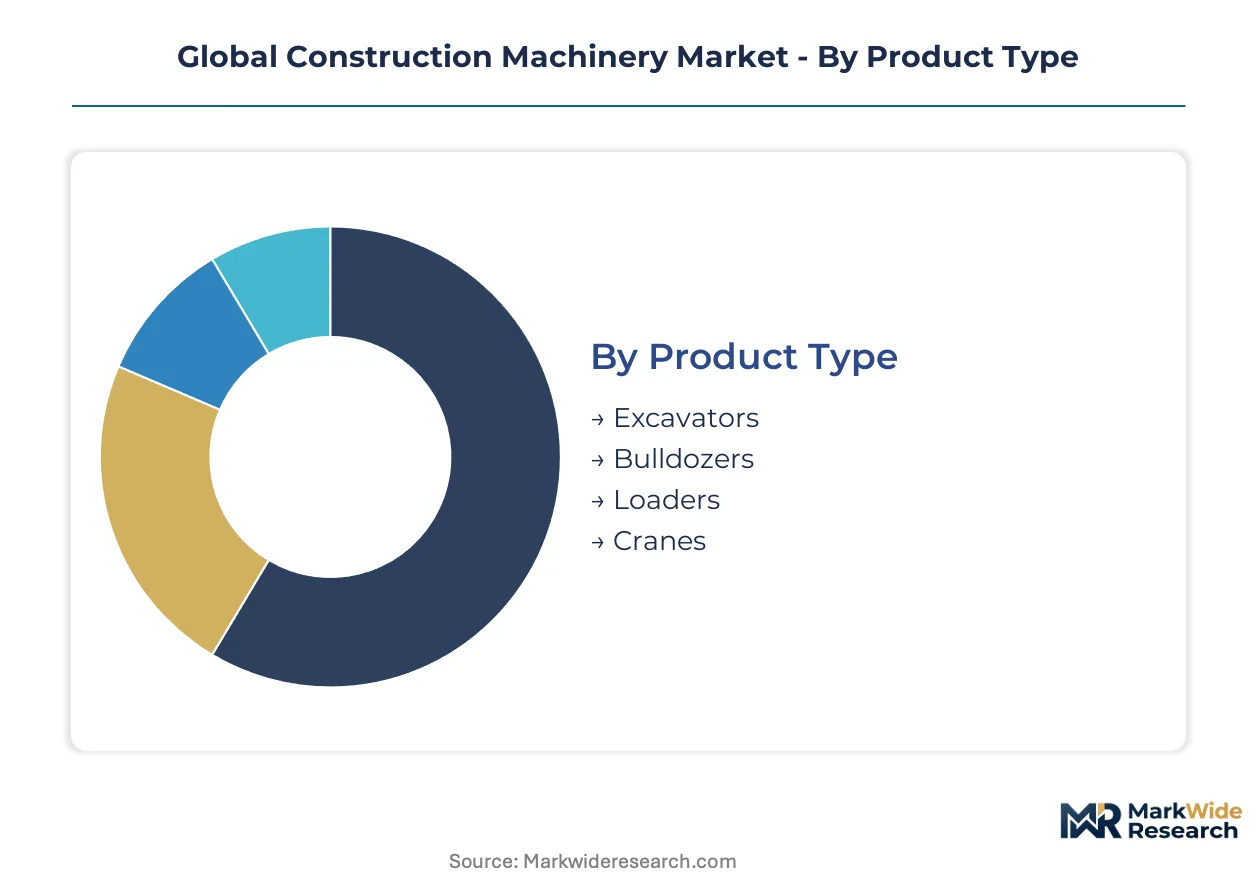
Equipment specification tiers and powertrain architectures are fragmenting procurement patterns across civil engineering and resource extraction. Contractors and mining operators now select machinery based on emission certification compatibility and telematics readiness rather than displacement metrics alone.
Product Type:
Technical sophistication varies sharply across earthmoving categories, with hydraulic system pressure ratings and boom geometry determining project suitability.
- Excavators:These machines deploy variable-displacement piston pumps operating above 3,000 psi, enabling precise trenching and material loading across urban demolition and pipeline installation. Australian mining contractors specify long-reach configurations for pit wall maintenance where cycle time optimization drives fleet economics.
- Loaders:Articulated steering and hydrostatic transmissions dominate wheel loader architectures, with bucket breakout force determining suitability for quarry aggregate handling. German rental fleets prioritize mid-size units with EU Stage V certification to access municipal construction zones facing emission restrictions.
- Bulldozers:Track-type tractors with elevated sprocket undercarriages distribute ground pressure for landfill and site preparation work.
- Cranes:Lattice boom and telescopic configurations serve vertical lifting requirements across building erection and wind turbine installation.
Excavators lead on scale; loaders lead on momentum.
Application:
Project economics and regulatory exposure differ materially across end-use verticals, shaping equipment specification priorities.
- Infrastructure:Road, rail, and dam construction demands versatile equipment fleets with rapid attachment interchange capability. State-funded projects in China's western provinces concentrate procurement volume where domestic emission standards align with European testing protocols.
- Mining:Surface and underground extraction operations prioritize durability certification and autonomous compatibility. Chilean copper operators expand electrified haulage programs that require integrated telematics for remote pit management.
- Agriculture:Land clearing and irrigation canal maintenance represent seasonal demand pockets with price-sensitive procurement patterns.
- Demolition:Structural dismantling and material recycling applications favor specialized high-reach excavators with hydraulic pulverizer attachments.
Infrastructure commands the largest equipment base; mining shows the steepest expansion trajectory.
End User:
Capital deployment models and ownership risk allocation vary substantially across customer categories.
- Contractors:Fragmented civil engineering firms deploy equipment across multiple concurrent projects, favoring rental or lease arrangements over direct purchase. Spanish and Italian contractors increasingly negotiate hourly-availability guarantees that transfer residual-value exposure to manufacturers.
- Rental Companies:Fleet managers face municipal emission restrictions that accelerate replacement cycles for aging diesel machines in France and Germany. Telematics integration enables unbundled maintenance contracts based on utilization metrics rather than calendar schedules.
- Government:State procurement tenders enforce domestic emission standards that reshape supplier qualification requirements.
- OEMs:Component manufacturers and subsystem suppliers represent secondary equipment demand for testing and demonstration purposes.
Contractors absorb the highest equipment volume; rental companies are gaining share fastest.
Technology:
Powertrain architecture selection increasingly determines market access and project eligibility across regulated jurisdictions.
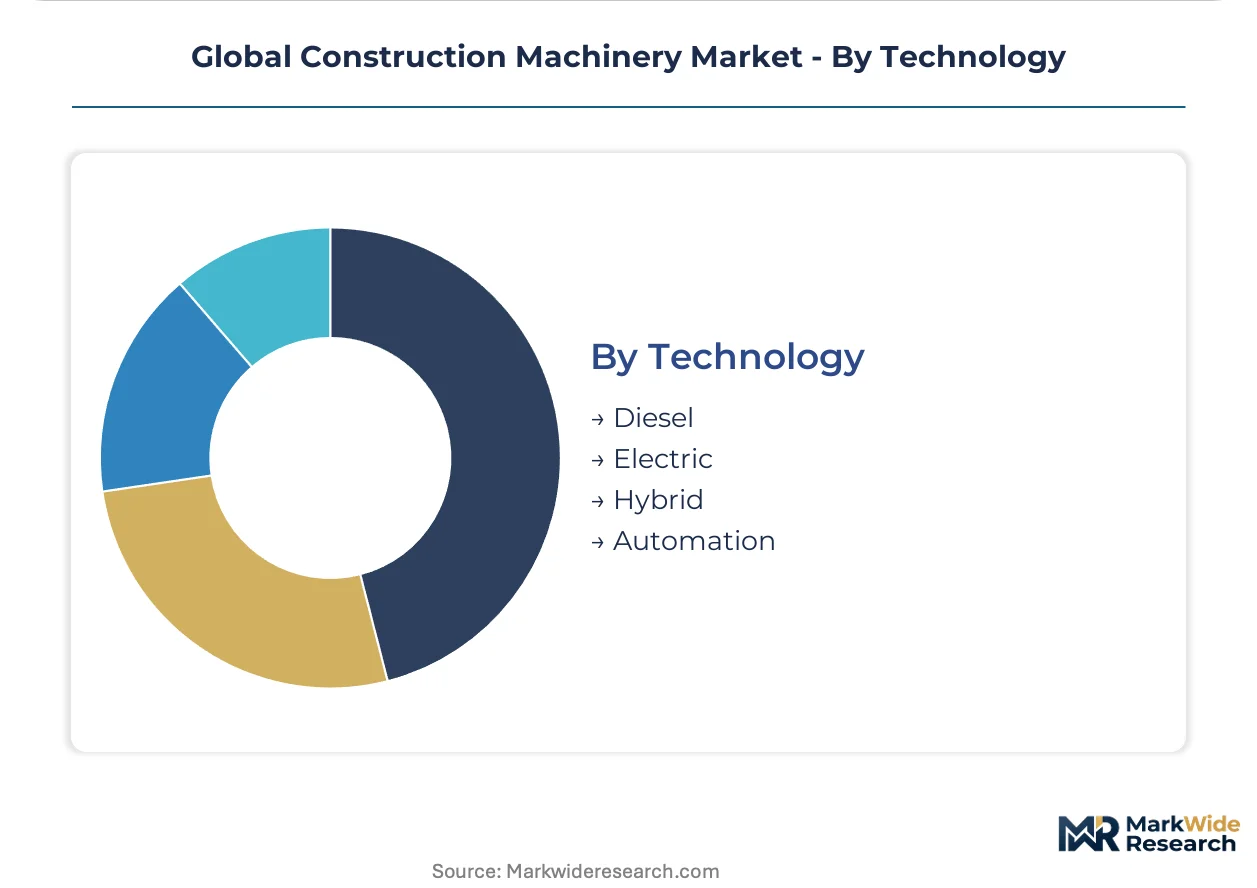
- Diesel:Compression-ignition engines still dominate installed base and revenue volume, though EPA and EU Stage V frameworks force costly redesigns for mid-range equipment tiers. Compliance barriers disproportionately affect smaller Chinese exporters seeking state-procurement access.
- Electric:Battery-electric configurations capture disproportionate interest from European rental companies facing municipal zero-emission zones. Off-grid charging infrastructure at remote Chilean and Australian mining sites enables diesel-free operations untethered from fuel logistics.
- Hybrid:Parallel and series-hybrid architectures blend internal combustion with electric assist for fuel recovery during braking cycles.
- Automation:Autonomous haulage systems differentiate service contracts from hardware sales through integrated remote operation capabilities.
Diesel retains the dominant installed position; electric configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled hydraulic systems engineers and embedded software developers concentrate in Germany's industrial belt and Japan's manufacturing corridors, anchoring precision machinery production. Australia's mining equipment specialists and Chile's copper belt technicians drive fleet electrification deployment. China's western provinces absorb civil engineering graduates for state-funded infrastructure buildout.
United States
Infrastructure Investment and Jobs Act disbursements accelerate highway and bridge reconstruction across Texas and Florida. EPA Tier 4 Final emission standards force engine redesigns for mid-range excavators and wheel loaders. Houston's energy corridor hosts equipment rental fleets serving Permian Basin oilfield services.
Germany
Rental companies in Bavaria and North Rhine-Westphalia replace aging diesel fleets ahead of municipal zero-emission zone expansions. EU Stage V certification requirements reshape supplier qualification for federal highway tenders. Stuttgart's industrial cluster anchors autonomous haulage system development for export markets.
China
State-funded rail corridors and hydropower dams in Sichuan and Yunnan provinces concentrate equipment procurement volume. MIIT emission standards increasingly align with European testing protocols, filtering foreign supplier access to government tenders. Xuzhou's manufacturing base supplies domestic excavator demand for western infrastructure buildout.
Australia
Iron ore and lithium miners in Western Australia's Pilbara region expand electrified haulage programs. ISO 10987 durability testing requirements gate entry to mining fleet contracts. Perth's engineering services cluster supports remote pit management through integrated telematics platforms.
Chile
Copper operators in the Atacama Desert deploy off-grid charging infrastructure for battery-electric haul trucks. The Ministry of Mining's decarbonization roadmap accelerates fleet replacement timelines. Antofagasta's equipment maintenance hubs adapt hydraulic architectures for high-altitude electric powertrain operation.
Global Construction Machinery Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across integrated powertrain and component assembly models. The vendor base clusters around three tiers: full-line manufacturers with captive engine production, specialized autonomous system integrators, and regional assemblers dependent on imported subsystems. Strategic differentiation flows from emissions certification control, telematics platform ownership, and aftermarket parts network density. Consolidation pressure intensifies as compliance costs rise for mid-range equipment tiers without scale economies.
Among Japanese and German industrial conglomerates, Komatsu Ltd. and Liebherr Group occupy positions emphasizing integrated autonomous haulage and precision engineering archetypes. Chinese manufacturers including XCMG Group and SANY Group exemplify scale-driven assembly models serving domestic infrastructure procurement. These named entities anchor competitive positioning without exhausting the full participant set.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd. |
| Deere & Company |
| XCMG Group |
| SANY Group |
| Liebherr Group |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| Zoomlion Heavy Industry |
| Others |
Supply Flow & Price Mechanics
Rental company procurement concentration in Germany and France anchors the shift toward subscription-based availability contracts. Municipal emission restrictions force fleet managers to absorb compliance premiums through unbundled service pricing rather than capital expenditure.
Pricing Analysis
Hardware-software bundling separates premium OEMs from commodity assemblers across European rental markets. Three-tier pricing structure across premium, standard, and economy levels reflects EU Stage V certification status and telematics integration depth. Cost compression in mid-range excavators intensifies because Chinese exporters face MIIT compliance barriers. Contractors prove most price-sensitive due to fragmented project economics; mining operators show least sensitivity given fleet-scale procurement.
Supply Chain Analysis
Domestic content mandates in China's western provinces reshape component sourcing for state-funded infrastructure tenders. Manufacturing gravity centers on Germany, Japan, and China for precision hydraulics and powertrain assembly. Steel forgings, high-pressure hydraulic pumps, and electronic control modules feed from specialized tier-one suppliers. Single-source vulnerability concentrates in semiconductor-dependent telematics controllers. Distribution runs through captive dealer networks and independent rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU Stage V compliance costs and China's MIIT-aligned certification pathways. Manufacturers can capture margin spreads by engineering common powertrain architectures that satisfy both regulatory regimes.
For Market Incumbents: To counter embedded systems engineering talent shortages slowing autonomous product roadmaps, Caterpillar and Komatsu Ltd. should deepen backward integration into control software development. Captive telematics platform ownership defends service contract differentiation from hardware commoditization. For New Entrants and Emerging Players: Battery-electric retrofit specialists represent the most penetrable channel partner type for aftermarket electrification programs. Target Australian mining contractors seeking ISO 10987-certified durability upgrades without full fleet replacement. Pursue hourly-availability guarantee contracts that transfer residual-value risk from end-users. For Investors and Strategic Acquirers: Industrial conglomerates with captive engine manufacturing are the most active acquirer in this space, seeking telematics capabilities to complete autonomous haulage system portfolios. Five-to-ten-year viability hinges on electrification architecture control. Target mid-tier autonomous system integrators with proven pit-management deployments. Monitor EU Stage V enforcement intensity in municipal construction zones as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Electronics | Captive control software development locks in telematics subscription revenue for Komatsu Ltd. and Caterpillar. |
| ISO 10987 Durability Certification Investment | Australian mining fleet contracts gate entry on this baseline qualifier, filtering uncertified Chinese suppliers. |
| Joint Venture for Off-Grid Charging Infrastructure | Chilean copper operators deploy battery-electric haul trucks untethered from diesel fuel logistics. |
| Platform Standardization Across Emission Tiers | Common engine architectures serving EU Stage V and China MIIT reduce compliance cost duplication. |
| Strategic Partnership with Rental Fleet Operators | German and French unbundled maintenance contracts transfer residual-value exposure to OEMs. |
Methodological Framework
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining interviews with fleet maintenance directors, OEM procurement teams, rental company operations heads, and aftermarket service specialists. Secondary validation draws from EPA certification filings, EU Stage V type-approval databases, MIIT emission standard notices, and customs trade records for hydraulic component flows. Bottom-up equipment shipment analysis triangulates against top-down infrastructure investment forecasts.
Granularity-level modeling disaggregates volume and value across product type, powertrain architecture, emission certification tier, and end-user ownership model throughout the forecast period. CAGRs derive from regression analysis of historical replacement cycles correlated with regulatory phase-in schedules. Mining electrification deployment timelines and municipal emission zone expansions serve as industry-specific demand inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density improvements and autonomous control software maturation. Projections reflect assumptions on steel price stability and semiconductor availability for telematics integration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Injection Molding Machine Market