
 Concrete Finishing Equipment Market | 2026-2036
Concrete Finishing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Finishing Equipment Market Insights
Chinese power trowel manufacturing capacity is hardening export competitiveness across Southeast Asia and the Middle East. Somero Enterprises leverages laser-guided screed technology to dominate precision flatwork for warehouse and distribution center clients. Wacker Neuson sustains a broad gas-powered and battery-operated portfolio that anchors its position in European rental channels. Allen Engineering Corporation specializes in ride-on trowel engineering for industrial flooring contractors demanding high-torque finishing.
Concrete finishing equipment encompasses mechanized and handheld tools that level, smooth, and texture cured concrete surfaces through rotary blade action, vibratory screeding, or pressure-driven edging, typically operating at blade speeds between 60 and 150 RPM to achieve specified flatness tolerances. Power trowels and concrete screeds capture the dominant share of replacement demand as commercial construction and infrastructure development projects specify tighter F-numbers and extended surface durability. Battery-operated technology segments expand fastest where municipal noise ordinances and indoor air quality standards restrict gas-powered equipment runtime.
OSHA silica exposure limits and EPA emissions standards for small off-road engines compel manufacturers to redesign enclosures and integrate dust-collection systems across product lines. The EU Green Deal and F-Gas Regulation pressure gas-powered equipment margins while accelerating electric and hydraulic platform development. Stakeholders must monitor how regulatory compliance costs redistribute margin pools between established gas-powered portfolios and emerging battery platforms.
Market Dynamics
Battery-operated power trowels are compressing gas-powered equipment margins as contractors face tightening emissions standards and indoor runtime restrictions. This electrification push is redistributing procurement budgets toward lithium-ion platforms and reshaping fleet replacement cycles across commercial flooring and infrastructure verticals.
Growth Catalysts
- EU Green Deal and F-Gas Regulation:These frameworks are accelerating electric platform adoption by restricting gas-powered equipment in enclosed construction environments and municipal projects.
- National highway expansion in India:Massive road and smart city investments are absorbing power trowels and laser screeds at unprecedented procurement volumes.
- Lithium-ion battery density improvements:Extended runtime per charge is enabling full-shift operation on battery trowels, eliminating previous productivity gaps against combustion engines.
Market Restraints
- Steel and aluminum input volatility:Blade and frame manufacturing faces margin pressure from commodity price swings that equipment makers struggle to pass through in competitive bidding.
- Chinese power trowel manufacturing concentration:Export supply chains cluster in Zhejiang and Jiangsu provinces, creating geopolitical and logistics vulnerability for distributors.
- OSHA silica exposure enforcement:Dust-collection system mandates add per-unit cost burdens that price-sensitive small contractors resist absorbing.
Strategic Opportunities
- Underpenetrated Southeast Asia infrastructure:Vietnam, Indonesia, and Philippines highway programs lack established equipment rental networks, opening direct sales channels.
- Convergence of telematics and predictive maintenance:IoT-enabled trowels offering usage analytics and automated service alerts command premium positioning in fleet management contracts.
- US Inflation Reduction Act clean construction incentives:Tax credits for low-emission equipment are tilting municipal procurement specifications toward battery platforms.
Industry Challenges
- Certified concrete finishing technician shortage:Specialized operators capable of achieving specified F-numbers on laser-guided equipment are scarce in expanding markets.
- Legacy gas-powered fleet stranding risk:Contractors holding depreciating combustion assets face compressed resale values as rental channels electrify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Finishing Equipment Market |
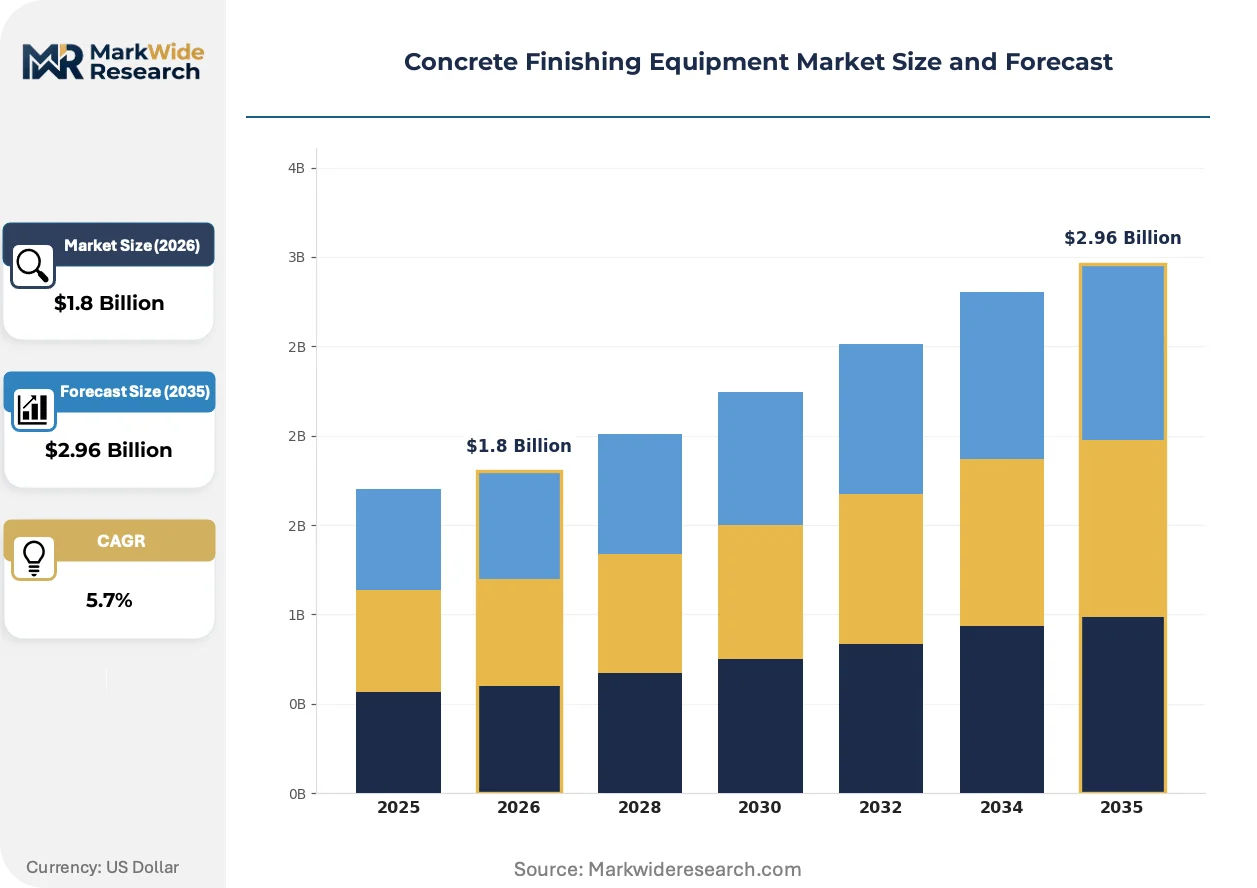
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Trowels, Power Trowels, Concrete Screeds, Edgers, Groovers Technology: Electric, Gas-Powered, Pneumatic, Hydraulic, Battery-Operated Application: Commercial Construction, Residential Projects, Infrastructure Development, Industrial Flooring End User: Construction Companies, Road Contractors, Flooring Specialists, Building Firms |
| Companies Covered | Somero Enterprises, Wacker Neuson, Allen Engineering Corporation, Gomaco Corporation, Ligchine International, Husqvarna Group, Atlas Copco Limited, MBW Inc., Bartell Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Finishing Equipment Market Trends and Innovations
Electrification is rewriting equipment specifications while precision demands from warehouse and data center construction push automation deeper into finishing workflows. These parallel developments are compressing the technology gap between premium and mid-tier product lines.
Lithium-ion battery platforms are overtaking gas-powered alternatives in indoor commercial applications where EPA emissions standards for small off-road engines and municipal noise ordinances restrict runtime. Warehouse and distribution center contractors are specifying battery trowels for multi-shift flatwork, and this specification shift is compressing the addressable market for combustion engines in enclosed environments.
REACH and RoHS compliance requirements in Europe are forcing redesigns of hydraulic fluids, blade coatings, and electronic enclosures across equipment portfolios. Manufacturers serving EU member states must now certify against substance restrictions that add engineering cycles but create regulatory moats against non-compliant imports. Battery platform suppliers with pre-certified supply chains are capturing specification share in German and French rental channels.
Rental channel consolidation is displacing direct equipment ownership among mid-sized flooring contractors. National rental chains are unbundling maintenance and training from base rates, and this service model evolution is most visible in US commercial construction where contractors prioritize balance sheet flexibility over asset ownership. Fleet telematics integration is becoming a standard inclusion rather than premium upsell.
Concrete Finishing Equipment Market Segmentation
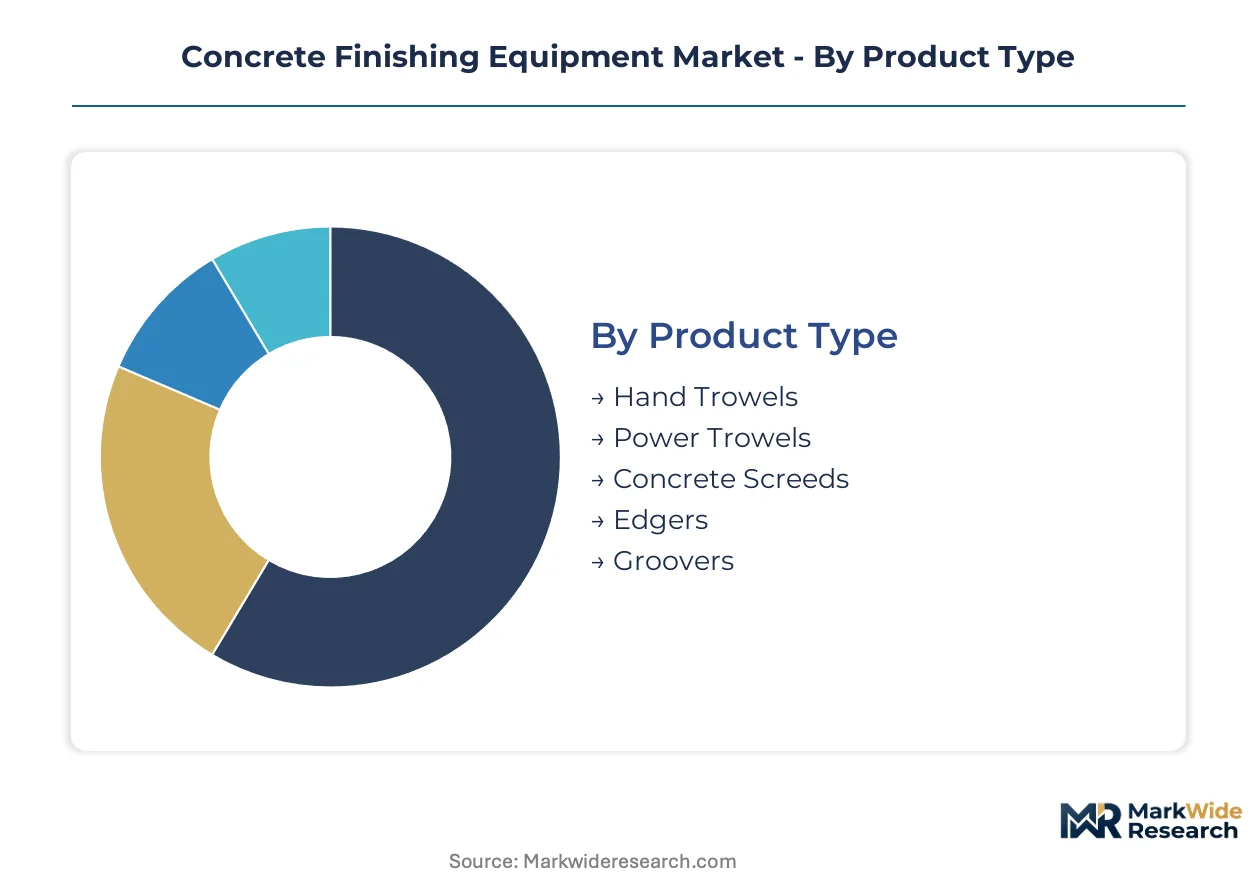
Segmentation in concrete finishing equipment reveals how regulatory pressure and application intensity reshape procurement specifications across product lines. Equipment buyers segment their fleets by emission compliance zones, surface flatness requirements, and project duration cycles.
Product Type:
REACH substance restrictions and OSHA silica mandates impose divergent certification burdens across manual versus mechanized product lines, with dust-collection integration most stringent on rotary-blade equipment.
- Power Trowels:Ride-on and walk-behind rotary-blade machines operating at 60-150 RPM achieve F-number tolerances for warehouse flatwork. Demand concentrates in India where national highway expansion and smart city initiatives absorb units at scale, though steel blade input volatility compresses margins.
- Concrete Screeds:Laser-guided and vibratory platforms level freshly placed concrete through oscillating beams or precision elevation control. Warehouse and data center contractors in Germany and France specify these for superflat specifications, with battery-operated variants gaining rental channel preference under EU Green Deal frameworks.
- Hand Trowels:Manual steel-blade tools for edge finishing and detail work on small residential pours.
- Edgers:Radius-forming tools for joint edges and decorative concrete borders.
- Groovers:Hand-guided or walk-behind units for control joint cutting in pavement and slab applications.
Leading the category by volume: Power Trowels. Growing fastest: Concrete Screeds.
Technology:
Cost tier stratification separates premium battery platforms from economy gas-powered lines, with lithium-ion systems commanding 40-60% price premiums justified by full-shift runtime and indoor compliance.
- Battery-Operated:Lithium-ion platforms with extended runtime per charge now enable full-shift operation, eliminating previous productivity gaps against combustion engines. Municipal noise ordinances and EPA emissions standards for small off-road engines restrict gas-powered runtime in enclosed US commercial construction, tilting procurement specifications toward these platforms.
- Electric:Corded systems for continuous indoor operation where tethered power access eliminates battery swap logistics.
- Gas-Powered:Honda and Vanguard engine packages dominate outdoor infrastructure applications where runtime flexibility outweighs emission constraints.
- Hydraulic:High-torque systems for ride-on trowels demanding sustained blade speed under load.
- Pneumatic:Compressed-air screeds for specialized industrial environments with explosion-proof requirements.
Volume leadership: Gas-Powered. Steepest expansion trajectory: Battery-Operated.
Application:
Customer type differentiation separates specification-heavy industrial flooring from price-sensitive residential segments, with certified technician requirements highest in precision flatwork verticals.
- Industrial Flooring:Superflat specifications for automated warehouse racking and high-bay storage demand laser-guided equipment and certified operators capable of achieving specified F-numbers. US Inflation Reduction Act clean construction incentives tilt municipal procurement toward battery platforms in this segment.
- Infrastructure Development:Road, bridge, and highway projects specify ride-on trowels for pavement durability.
- Commercial Construction:Mid-rise slabs and retail flooring balance flatness requirements against equipment mobility constraints.
- Residential Projects:Single-family foundations and decorative concrete drive price-sensitive demand toward handheld tools and rental power trowels.
Procurement volume concentrates in Infrastructure Development. Margin expansion favors Industrial Flooring.
End User:
Supply concentration shapes channel strategy, with rental networks capturing mid-sized flooring specialists while direct sales dominate road contractor fleets in underpenetrated Southeast Asian markets.
- Road Contractors:Highway and pavement specialists procure ride-on trowels and vibratory screeds for longitudinal finishing at scale. Vietnam, Indonesia, and Philippines highway programs lack established equipment rental networks, opening direct sales channels for manufacturers with localized service capabilities.
- Flooring Specialists:Commercial and industrial flatwork contractors specify laser screeds and high-torque trowels for F-number compliance.
- Construction Companies:Generalist builders with diversified project portfolios favor rental flexibility over fleet ownership.
- Building Firms:Residential-focused developers prioritize cost containment through subcontractor equipment provision.
Road Contractors anchor category volume. Flooring Specialists drive technology upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel blade manufacturing clusters in Zhejiang and Jiangsu provinces anchor supply-side capacity for concrete finishing equipment exported worldwide. These Chinese production centers feed fabrication networks across Southeast Asia, the Middle East, and emerging African markets. Regional demand patterns diverge sharply between mature electrification markets and infrastructure-heavy developing economies.
United States
Warehouse construction in Dallas-Fort Worth and Phoenix drives laser screed procurement for superflat industrial flooring. EPA emissions standards for small off-road engines restrict gas-powered equipment runtime in enclosed commercial environments. California's South Coast Air Quality Management District enforces the nation's strictest indoor air quality mandates, accelerating battery trowel adoption among Los Angeles-area flooring contractors.
Germany
Distribution center development in the Rhine-Ruhr corridor sustains premium equipment demand from logistics real estate developers. EU Green Deal frameworks and F-Gas Regulation compel rental channels to electrify fleets serving municipal construction projects. Bavaria's Munich-Stuttgart industrial belt hosts specialized concrete finishing technician training programs that certify operators for F-number precision work.
India
National highway expansion under the Bharatmala Pariyojana program absorbs ride-on power trowels at unprecedented procurement volumes. The Ministry of Road Transport and Highways mandates quality certification for road construction equipment deployed on centrally sponsored projects. Gujarat's Ahmedabad-Surat industrial corridor concentrates flooring specialist contractors serving pharmaceutical and cold storage warehouse construction.
China
Smart city infrastructure in Chengdu and Xi'an generates sustained demand for precision concrete screeding equipment. MIIT energy efficiency standards for construction machinery push domestic manufacturers toward electric platform development. The Yangtze River Delta manufacturing cluster around Shanghai exports power trowel components to Southeast Asian assembly operations.
United Arab Emirates
Expo 2020 legacy developments and continued logistics hub construction in Dubai sustain high-specification flatwork demand. Dubai Municipality green building regulations incentivize low-emission equipment deployment on government-contracted projects. Jebel Ali's industrial zone hosts regional equipment distribution centers serving Saudi Arabian and Qatari infrastructure markets.
Concrete Finishing Equipment Market Competitive Landscape
Global majors compete with regional champions across technology platforms and rental channel access. The vendor base separates into three tiers: integrated multinational machinery conglomerates, specialized concrete finishing equipment pure-plays, and regional fabrication specialists serving price-sensitive emerging markets. Dominant competitive moves include portfolio electrification and telematics integration for fleet management contracts, alongside geographic expansion through localized service partnerships.
Among specialized pure-plays, Somero Enterprises exemplifies precision flatwork technology leadership, while Wacker Neuson anchors diversified equipment rental channel positioning across European markets. Allen Engineering Corporation occupies a position within the high-torque ride-on trowel specialist tier. These three represent contrasting archetypes: laser-guided precision technology, broad portfolio rental penetration, and industrial flooring application focus.
| Leading Market Players |
|---|
| Somero Enterprises |
| Wacker Neuson |
| Allen Engineering Corporation |
| Gomaco Corporation |
| Ligchine International |
| Husqvarna Group |
| Atlas Copco Limited |
| MBW Inc. |
| Bartell Global |
| Others |
Pricing and Supply Chain Analysis
A sharp certification-performance divide between battery-operated and gas-powered platforms creates divergent margin structures across procurement channels. This bifurcation manifests in premium pricing for EU Green Deal-compliant lithium-ion systems and compressed economics for legacy combustion engines facing stranded asset risk.
Pricing Analysis
Warranty and service bundling separates rental channel offerings from direct sales, with national chains unbundling maintenance and training from base rates. Three-tier pricing structure across premium, standard, and economy levels reflects battery density grades and dust-collection certification tiers. Cost compression in gas-powered segments intensifies as EPA emissions standards for small off-road engines restrict resale liquidity. Small residential contractors exhibit highest price sensitivity, while industrial flooring specialists absorb premium positioning for F-number compliance.
Supply Chain Analysis
CE marking and OSHA silica certification gates filter component suppliers, with REACH-compliant hydraulic fluid and blade coating vendors capturing specification share in European markets. Manufacturing gravity centers on China, Germany, and the United States, with steel blade forging and lithium-ion cell production anchoring cost structures. Aluminum frame extrusions and copper motor windings draw from commodity markets exposed to tariff volatility. Distribution runs through regional equipment rental networks and direct sales channels serving road contractors in underpenetrated Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance deadlines and battery platform R&D requirements are forcing capital-constrained regional fabricators toward exit or acquisition, consolidating competitive structure around electrified portfolios.
For Market Incumbents: To counter Chinese power trowel export price pressure, Somero Enterprises and Wacker Neuson should deepen backward integration into lithium-ion battery pack assembly and captive blade forging capacity. Securing MIIT-certified component supply chains protects margin position in European rental channels facing F-Gas Regulation enforcement. For New Entrants and Emerging Players: Telematics-enabled predictive maintenance platforms offer entry leverage into fleet management contracts where usage analytics command premium positioning. Vietnam and Indonesia highway programs present white-space demand for direct sales channels with localized service partnerships. Target certified technician training programs as a go-to-market anchor in precision flatwork verticals. For Investors and Strategic Acquirers: Re-rating potential sits with battery-platform specialists given US Inflation Reduction Act clean construction incentives accelerating municipal procurement shifts. Long-term viability favors vendors with pre-certified EU supply chains and telematics integration capabilities. Watch for stranded gas-powered fleet write-downs as an inflection signal for distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Electrification | EU Green Deal and EPA emissions standards are tilting procurement specifications toward lithium-ion systems in enclosed commercial environments. |
| Telematics Integration | IoT-enabled usage analytics command premium positioning in fleet management contracts with national rental chains. |
| Certified Technician Training Programs | F-number precision requirements in warehouse construction create moats around operators qualified on laser-guided equipment. |
| Backward Integration into Blade Forging | Steel input volatility compresses margins for outsourced component buyers in competitive bidding environments. |
| Southeast Asia Direct Sales Expansion | Vietnam, Indonesia, and Philippines highway programs lack established rental networks, opening channel control opportunities. |
Research Methodology
Independent corroboration across equipment procurement managers, rental channel operators, and concrete finishing technicians underwrites the qualitative findings in this study. Primary interviews with maintenance directors at flooring specialist firms, OEM procurement teams at road contractors, and aftermarket service heads at national rental chains combined with secondary validation from MIIT energy efficiency disclosures, EPA emissions filings, and EU Green Deal implementation reports. Bottom-up unit economics and top-down infrastructure spend estimates triangulate volume and value outputs.
Comparable-period anchoring to historical highway construction cycles and warehouse buildout waves shaped the projection horizon. Segmentation modeling spans product type, technology platform, application intensity, and end-user channel structure. CAGRs derive from equipment replacement cycle analysis and procurement budget elasticity across commercial construction verticals. Lithium-ion battery density improvement curves and silica exposure compliance cost trajectories feed platform adoption assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to Chinese blade manufacturing clusters and abrupt shifts in municipal noise ordinance enforcement. Forecasts reflect assumptions about infrastructure budget continuity and battery cost decline trajectories. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or US EPA small off-road engine standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Concrete Block Making Machines Market